
 Nigeria Freight and Logistics Market | 2026-2036
Nigeria Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Freight and Logistics Market Outlook
Market Context
The Nigeria freight and logistics sector is recalibrating around a widening split between premium cold-chain and time-definite services versus commodity bulk haulage. GIG Logistics leverages its proprietary tracking infrastructure to dominate express parcel delivery in southern Nigeria. Red Star Express anchors its position through an extensive branch network spanning major commercial cities. A.P. Moller - Maersk competes on deep-sea container capacity through Lagos and Onne ports.
Technical Definition and Segment Structure
Nigeria freight and logistics encompasses the coordinated movement, storage, and information management of goods across road, rail, air, and sea modalities, typically operating with axle-load limits of 45 tonnes on federal highways and cold-chain temperature thresholds of 2-8°C for pharmaceutical cargo. Road Freight absorbs the majority of tonnage moved domestically, though margin pools concentrate in Last-Mile Delivery where E-commerce Platforms generate premium pricing power. Warehousing is maturing in Lagos Free Trade Zone corridors while IoT Solutions represent the fastest-growing technology spend as fleet operators deploy real-time fuel monitoring and geofencing systems.
Regulatory Framework
The Federal Ministry of Transportation, Nigerian Ports Authority, and Standards Organisation of Nigeria collectively enforce vehicle weight compliance, customs automation mandates, and cargo security protocols that determine market access for operators. These frameworks elevate capital requirements for new entrants while pushing incumbents toward digitized manifest systems and bonded terminal certifications. Stakeholders must monitor how port concession renewals and the Lekki Deep Sea Port ramp-up redistribute traffic flows between Lagos and emerging eastern gateways.
Market Dynamics
E-commerce order volumes are compressing delivery windows across Nigerian urban corridors, forcing fleet operators to reconfigure asset deployment around same-day and next-day service tiers rather than traditional batch-routing models.
Growth Catalysts
- National Transport Policy:Federal infrastructure modernization mandates are accelerating port automation timelines and widening bonded terminal access for logistics operators.
- Pharmaceutical cold-chain:Temperature-sensitive biologics distribution is expanding warehouse investment in 2-8°C compliant storage across Lagos pharmaceutical clusters.
- Lagos-Ibadan manufacturing belt:Industrial zone densification is generating dedicated contract logistics demand from consumer goods and automotive component suppliers.
Market Restraints
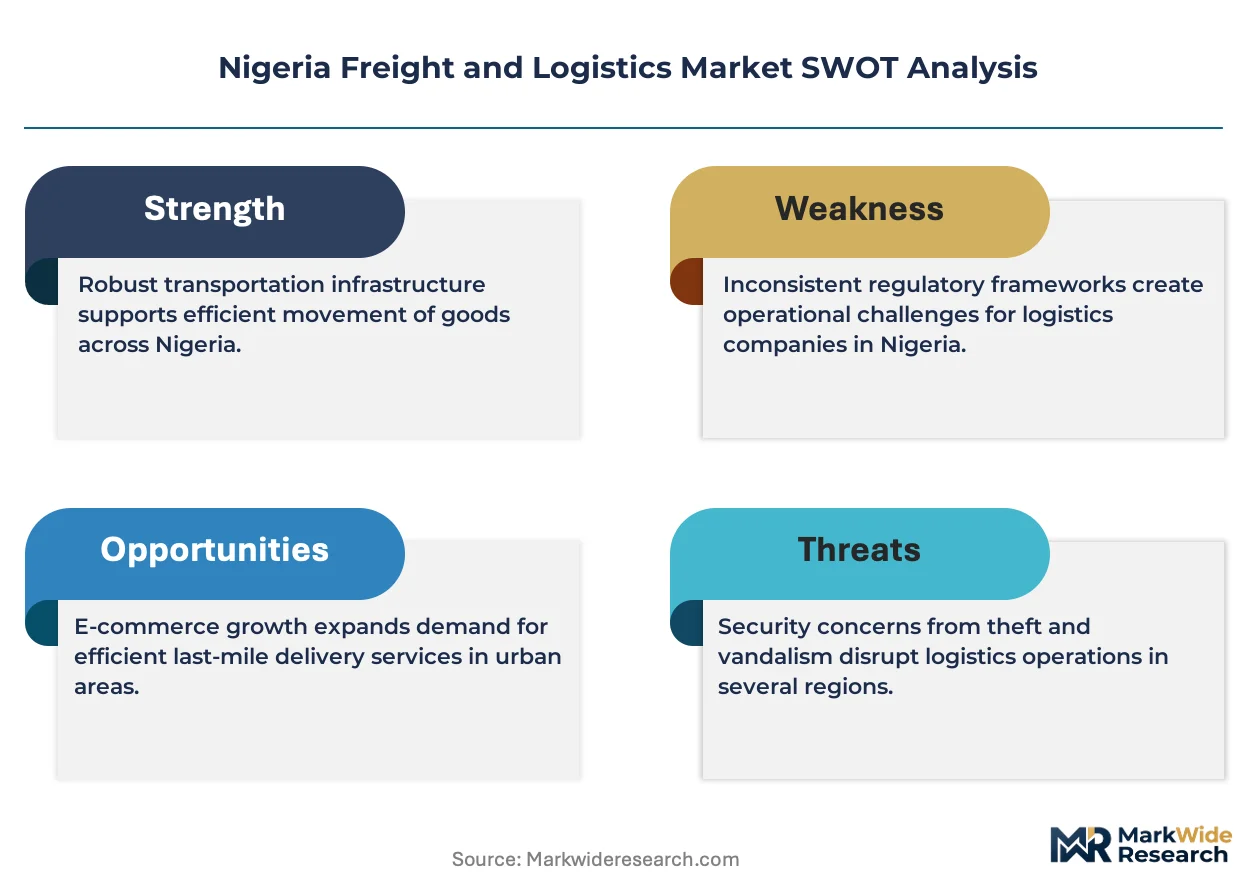
- Fuel price volatility:Diesel cost swings consume 35-45% of road freight operating budgets, eroding margin predictability for long-haul operators.
- Port concentration risk:Lagos Port Complex and Tin Can Island handle over 70% of containerized imports, creating systemic bottleneck exposure.
- Axle-load enforcement gaps:Inconsistent Federal Ministry of Transportation compliance checks allow overloaded competitors to undercut certified fleet pricing.
Strategic Opportunities
- Onne Port eastern gateway:Underutilized deep-water capacity in Rivers State offers first-mover advantages for Asia-Nigeria trade lane consolidation.
- IoT-fleet management convergence:Real-time fuel monitoring and predictive maintenance platforms are reducing asset downtime for mid-size haulage contractors.
- Kano-Kaduna distribution corridor:Northern Nigeria retail network expansion is opening regional hub-and-spoke warehousing opportunities outside Lagos dominance.
Industry Challenges
- Commercial driver certification backlog:Standards Organisation of Nigeria vehicle operator licensing delays are constraining qualified labor pool expansion.
- Legacy manifest system integration:Nigerian Customs Service automation mandates require expensive EDI upgrades for smaller freight forwarders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Freight and Logistics Market |
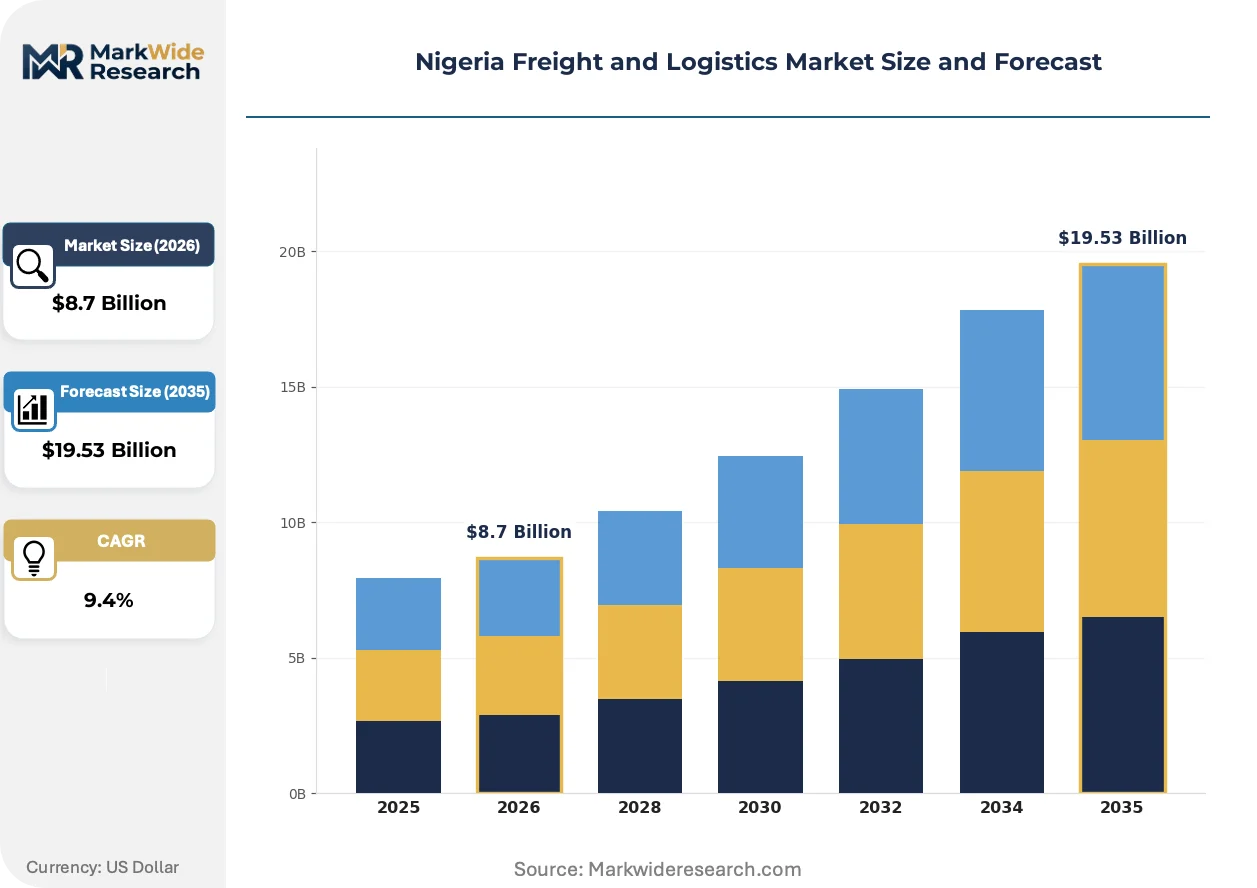
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Last-Mile Delivery End User: Manufacturers, Retailers, Distributors, E-commerce Platforms Transport Mode: Road Freight, Rail Freight, Air Freight, Sea Freight Technology: IoT Solutions, Freight Management Software, Tracking Systems, Automation Tools |
| Companies Covered | GIG Logistics, Red Star Express, A.P. Moller - Maersk, Q Logistics, UPS, CMA CGM Group, DHL Group, CarryGo, DP World, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Freight and Logistics Market Strategic Shifts
Digital freight matching platforms are collapsing traditional broker layers, while regulatory pressure on emissions and safety compliance is accelerating capital deployment into telematics and alternative fuel trials.
Telematics-enabled fleet management is unifying dispatch, fuel monitoring, and driver behavior analytics into single-dashboard operations. Third-party logistics providers in Lagos and Abuja are adopting these platforms within 12-18 month procurement cycles. The technology is compressing route optimization from daily batch planning to real-time dynamic reassignment based on traffic and delivery priority.
The Federal Ministry of Transportation's vehicle weight compliance automation mandate is tightening enforcement protocols on federal highways. Weighbridge data integration with Nigerian Ports Authority clearance systems is blocking overloaded trucks from terminal access. Road freight operators are responding by retrofitting axles and investing in lighter composite trailer materials to maintain payload competitiveness.
Consolidation of procurement authority among large retail chains is shifting logistics buying from transactional spot rates to annual contract structures with service-level guarantees. Dedicated fleet arrangements are displacing fragmented multi-provider models for grocery and electronics distributors. This concentration is most visible in Lagos, where Shoprite and Jumia anchor demand for integrated warehousing and last-mile bundles.
Nigeria Freight and Logistics Market Segmentation
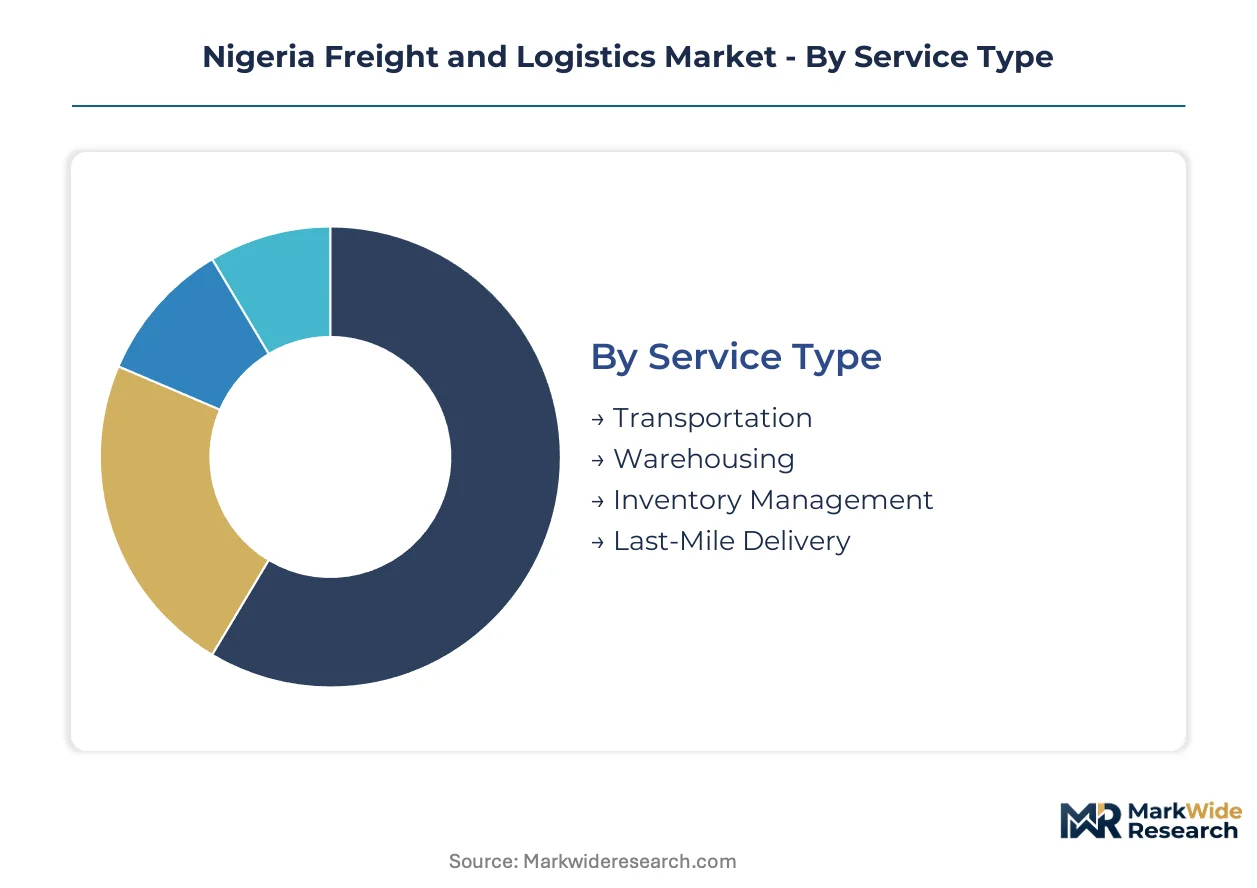
Segmentation in Nigeria freight and logistics reveals how capital pools around infrastructure-heavy modalities while technology spend concentrates in fleet monitoring and customs automation. Service configuration varies sharply between Lagos port corridors and northern distribution networks.
Service Type:
Supply concentration in Lagos-Ibadan warehousing clusters and port-adjacent bonded terminals shapes competitive positioning across service tiers.
- Transportation:Contracted fleet capacity moves containerized imports from Lagos and Onne ports to inland manufacturing zones. Diesel price exposure consumes 35-45% of operating budgets, forcing operators toward fuel hedging and axle-load optimization.
- Last-Mile Delivery:E-commerce Platforms in Lagos and Abuja compress delivery windows toward same-day and next-day tiers. GIG Logistics and Red Star Express deploy proprietary tracking infrastructure to capture premium pricing in southern urban corridors.
- Warehousing:Lagos Free Trade Zone corridors mature with 2-8°C compliant cold storage for pharmaceutical cargo.
- Inventory Management:Large retail chains consolidate procurement authority toward annual contract structures with service-level guarantees.
Transportation absorbs the bulk of installed capacity; Last-Mile Delivery is expanding most quickly.
End User:
Cost tier differentiation separates integrated contract logistics buyers from transactional spot-rate users.
- E-commerce Platforms:Jumia and Konga anchor demand for bundled warehousing and last-mile services across Lagos and Abuja. Order volume growth forces dynamic route reassignment from batch-routing models.
- Manufacturers:Consumer goods and automotive component suppliers in the Lagos-Ibadan belt generate dedicated contract logistics demand with strict inbound material scheduling.
- Retailers:Shoprite and domestic grocery chains shift from fragmented multi-provider models toward dedicated fleet arrangements.
- Distributors:Electronics and fast-moving consumer goods wholesalers concentrate procurement in annual structures with penalty clauses for service failures.
Manufacturers absorb the bulk of installed capacity; E-commerce Platforms are climbing the fastest.
Transport Mode:
Volume concentration on federal highways with 45-tonne axle-load limits creates enforcement arbitrage opportunities for non-compliant competitors.
- Road Freight:Domestic tonnage majority moves via diesel-powered fleets on Lagos-Ibadan and Kano-Kaduna corridors. Federal Ministry of Transportation weight compliance automation mandates are blocking overloaded trucks from Nigerian Ports Authority terminal access.
- Sea Freight:Deep-sea container capacity through Lagos Port Complex and Tin Can Island handles over 70% of imports. A.P. Moller - Maersk competes on vessel deployment frequency.
- Air Freight:Time-definite pharmaceutical and electronics cargo uses Murtala Muhammed International Airport cold-chain facilities.
- Rail Freight:Lagos-Kano standard gauge rehabilitation offers long-haul bulk alternatives for cement and agricultural commodities.
Road Freight absorbs the bulk of installed capacity; Sea Freight retains the steepest expansion trajectory.
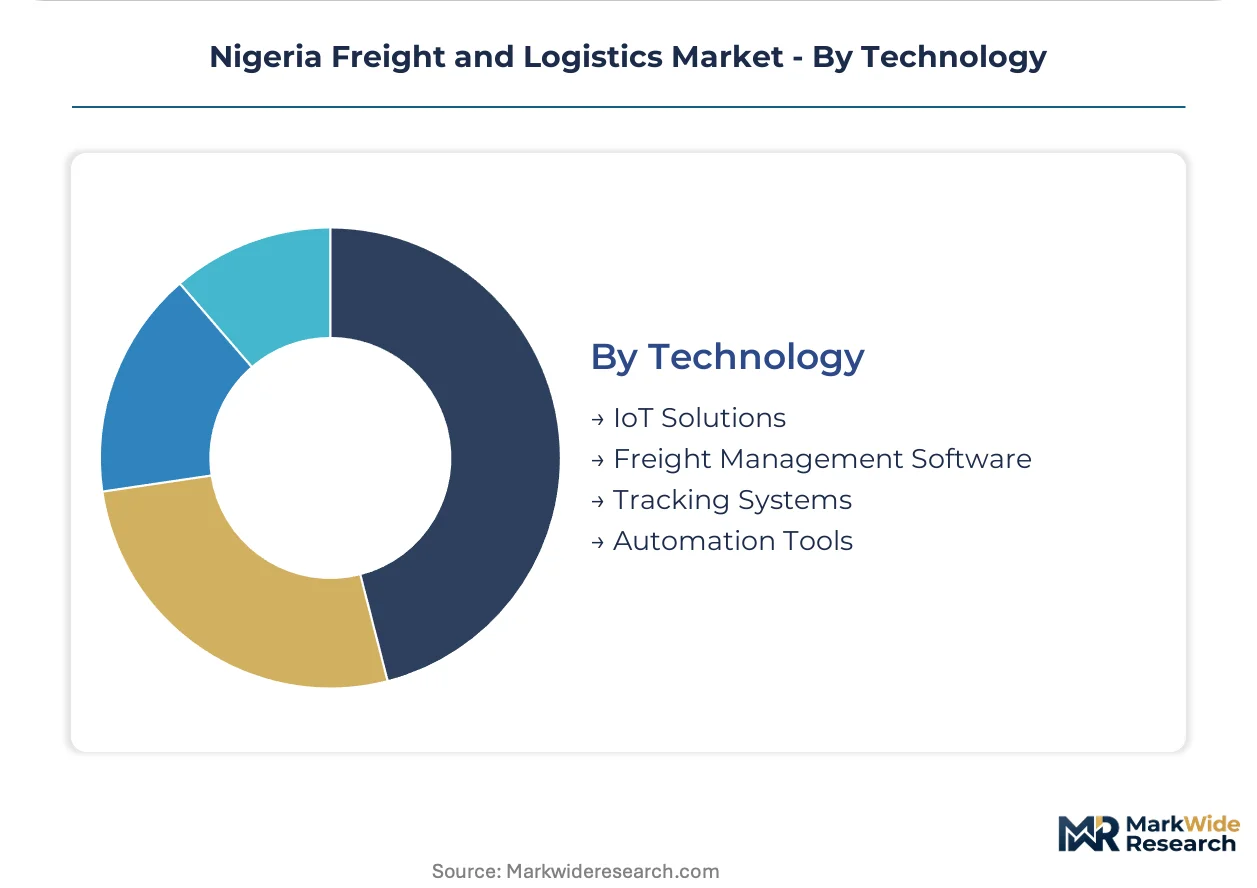
Technology:
Margin pressure from fuel volatility and driver certification backlogs accelerates technology deployment cycles.
- IoT Solutions:Real-time fuel monitoring and geofencing systems reduce asset downtime for mid-size haulage contractors in Lagos and Abuja. Predictive maintenance platforms compress procurement cycles to 12-18 months.
- Tracking Systems:GIG Logistics leverages proprietary infrastructure for express parcel visibility. Integration with Nigerian Customs Service automation mandates requires expensive EDI upgrades.
- Freight Management Software:Digital freight matching platforms collapse traditional broker layers between shippers and certified fleet operators.
- Automation Tools:Weighbridge data integration with port clearance systems enforces vehicle weight compliance on federal highways.
Tracking Systems absorb the bulk of installed capacity; IoT Solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors Nigerian freight activity through the Lagos Port Complex and Tin Can Island terminals, which together handle over 70% of containerized imports. The Lagos-Ibadan corridor concentrates warehousing investment and last-mile delivery networks serving manufacturing clusters and e-commerce distribution. Federal infrastructure programs are redistributing capacity toward eastern and northern gateways.
Lagos State
E-commerce order volumes from Jumia and Konga compress delivery windows toward same-day tiers across Lagos metropolitan zones. The Federal Ministry of Transportation enforces vehicle weight compliance automation on Lagos-Ibadan federal highways, blocking overloaded trucks from Nigerian Ports Authority terminal access. Lekki Deep Sea Port ramp-up is redistributing container traffic from congested Apapa terminals toward the eastern lagoon corridor.
Oyo State
Manufacturing densification around Ibadan generates dedicated contract logistics demand from consumer goods and automotive component suppliers. Standards Organisation of Nigeria cargo security protocols mandate digitized manifest systems for bonded warehouse certification. The Lagos-Ibadan expressway rehabilitation is accelerating transit times for containerized imports moving to inland distribution hubs.
Rivers State
Onne Port deep-water capacity offers underutilized alternatives for Asia-Nigeria trade lane consolidation outside Lagos bottleneck exposure. Nigerian Ports Authority concession frameworks are expanding terminal automation timelines for eastern gateway operators. Port Harcourt industrial zones attract chemical and petroleum logistics specialists serving Niger Delta extraction operations.
Kano State
Northern Nigeria retail network expansion opens regional hub-and-spoke warehousing opportunities for fast-moving consumer goods distributors. Central Bank of Nigeria trade finance regulations shape import documentation workflows for Kano-based commodities traders. Kano-Kaduna distribution corridors concentrate cold storage investment serving pharmaceutical and agricultural supply chains.
Abuja Federal Capital Territory
Government procurement logistics and diplomatic cargo sustain premium air freight demand through Nnamdi Azikiwe International Airport. National Transport Policy implementation mandates federal fleet modernization standards affecting contract award eligibility. Gwagwalada satellite town warehousing clusters serve Abuja metropolitan retail distribution with cross-dock facilities.
Nigeria Freight and Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across service tier differentiation, with integrated contract logistics commanding annual structures while spot-rate haulage competes on diesel price exposure. The vendor base stratifies between international container lines with deep-sea capacity, domestic express parcel networks with proprietary tracking infrastructure, and regional haulage contractors competing on federal highway access. Three archetypes dominate: global shipping lines anchoring port throughput, Nigerian-owned logistics platforms capturing last-mile premiums, and mid-size fleet operators retrofitting for weight compliance. Competitive moves concentrate on M&A for branch network density and IoT fleet management licensing for fuel monitoring differentiation.
Among Nigerian-owned express delivery platforms, GIG Logistics and Red Star Express exemplify the proprietary infrastructure archetype through tracking-enabled parcel visibility. A.P. Moller - Maersk occupies a position representing global container line competition on vessel deployment frequency through Lagos and Onne terminals. These three anchors illustrate how domestic technology investment, international ocean capacity, and compliance-certified fleet operations constitute distinct competitive vectors within the market structure.
| Leading Market Players |
|---|
| GIG Logistics |
| Red Star Express |
| A.P. Moller - Maersk |
| Q Logistics |
| UPS |
| CMA CGM Group |
| DHL Group |
| CarryGo |
| DP World |
| Others |
Value Chain & Pricing Dynamics
Premium cold-chain certification separates pharmaceutical-grade logistics from commodity bulk haulage in Nigeria, with temperature-compliant operators capturing annual contract structures while diesel-exposed road freight competes on spot-rate volatility. This divergence concentrates margin pools around Lagos pharmaceutical clusters and bonded terminals, while fuel price swings erode predictability for long-haul operators serving northern distribution corridors.
Pricing Analysis
Value-based pricing anchored to delivery-window guarantees dominates last-mile services, with same-day and next-day tiers commanding premium spreads over standard batch-routing. Price differentiation rests on proprietary tracking infrastructure and cold-chain certification grade, with Standards Organisation of Nigeria compliance serving as a tier separator. Cost compression in long-haul road freight intensifies as diesel exposure consumes operating budgets, making e-commerce platforms the least price-sensitive buyers while commodity distributors face acute margin pressure.
Supply Chain Analysis
Diesel supply rests on Nigerian National Petroleum Corporation downstream distribution and imported refined products through Lagos and Onne terminals. Fleet operators draw from Chinese and European trailer manufacturers for axle-load-compliant equipment, while telematics hardware sources from Israeli and South Korean IoT specialists. Single-source vulnerability concentrates in Lagos Port Complex container handling, where overcapacity exposure creates systemic bottleneck risk. Distribution runs through hub-and-spoke configurations anchored in Lagos Free Trade Zone corridors, with cross-dock facilities feeding northern spokes via Kano-Kaduna routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria freight and logistics is becoming a vertical-integration race, with fleet operators pursuing captive fuel supply through bunkering partnerships and warehousing providers acquiring last-mile delivery capabilities to capture bundled contract premiums.
For Market Incumbents: Cement branch network density in the Lagos-Ibadan corridor to defend against digital freight matching platforms collapsing traditional broker layers. Acquire cold-chain certification capacity to meet pharmaceutical distributor procurement consolidation, while retrofitting axles for Federal Ministry of Transportation weight compliance automation.
For New Entrants and Emerging Players: IoT-enabled fleet management platforms offer a technology-first wedge, with predictive maintenance and real-time fuel monitoring penetrating mid-size haulage contractors in Abuja and Port Harcourt. Target underutilized Onne Port capacity for Asia-Nigeria trade lane consolidation, deploying bonded terminal access as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with compliance-certified regional haulage specialists given Nigerian Ports Authority automation mandates and Lekki Deep Sea Port ramp-up redistributing container flows. Long-term viability favors operators with integrated warehousing and transportation bundles. Watch for weighbridge data integration completion as the inflection signal for enforcement-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Certification Investment | Standards Organisation of Nigeria compliance unlocks pharmaceutical logistics contracts with 2-8°C storage mandates. |
| IoT Fleet Management Deployment | Real-time fuel monitoring reduces asset downtime for mid-size haulage operators on Lagos-Ibadan corridors. |
| Bonded Terminal Access Expansion | Nigerian Ports Authority concession frameworks accelerate automation timelines for eastern gateway operators. |
| Last-Mile Capability Integration | E-commerce platforms in Lagos and Abuja compress delivery windows toward same-day service tiers. |
| Axle-Load Compliance Retrofit | Federal Ministry of Transportation mandates block overloaded trucks from port terminal access. |
Study Parameters
Nigerian Ports Authority statistical bulletins, Federal Ministry of Transportation regulatory filings, and Standards Organisation of Nigeria certification databases formed the secondary backbone. Primary interviews with fleet operations managers, bonded terminal operators, pharmaceutical distribution executives, and e-commerce logistics procurement leads combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up volume modeling across service type, end user, transport mode, and technology segmentation integrated with top-down macroeconomic anchoring. CAGRs were derived from trend extrapolation and adoption curve analysis across the projection horizon, incorporating diesel price volatility assumptions and port automation timeline inputs specific to Nigerian logistics infrastructure.
Several conditions sit outside the modeled scope, including currency devaluation scenarios beyond historical bands and political disruption affecting federal highway enforcement. Forecasts reflect documented assumptions about regulatory implementation pace and infrastructure completion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market