
 Global Grain Seed Market | 2026-2036
Global Grain Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grain Seed Market Foresight
Commercial farming cooperatives are bifurcating procurement budgets between high-performance hybrid seeds and cost-optimized conventional lines. Bayer leverages its trait platform to anchor premium positioning across North American corn belts. Corteva sustains broad germplasm libraries that span multiple grain species and climate zones. Syngenta competes through integrated crop solution bundling that extends beyond standalone seed sales.
Grain seed comprises reproductive plant material bred for agricultural propagation, typically meeting minimum germination thresholds, varietal purity standards, and pathogen-free certification before commercial distribution. Its primary purpose centers on establishing crop stands that optimize yield potential, grain quality, and harvest reliability for downstream food, feed, and fuel applications. Corn seed dominates value pools given its dual use in animal feed and ethanol production, while wheat seed retains mature volume positions across temperate cereal systems. Genetically modified technology captures premium pricing in markets with regulatory acceptance, though organic seed lines are gaining traction among contract farmers serving certified supply chains.
The USDA's Plant Variety Protection Office and China's Ministry of Agriculture and Rural Affairs enforce distinct intellectual property and biosafety frameworks that shape market access for trait-enhanced varieties. REACH and OECD Seed Schemes establish cross-border phytosanitary and chemical compliance benchmarks that seed exporters must satisfy. Stakeholders should monitor evolving gene-editing regulatory classifications across Brazil, Argentina, and the European Union to anticipate trait approval timelines and portfolio repositioning requirements.
Market Dynamics
Hybrid trait penetration is compressing germplasm diversity while elevating yield floor requirements, forcing seed producers to prioritize biotech licensing velocity over conventional breeding cycles.
Growth Catalysts
- Brazil's Cerrado intensification:Soybean-corn rotation systems are expanding planted hectares and driving recurrent seed replacement cycles among commercial operators.
- EU Seed Marketing Directives:Tightening genetic purity standards are filtering substandard suppliers and concentrating procurement among certified distributors.
- CRISPR trait editing:Accelerated varietal development timelines are compressing R&D payback periods for drought-tolerant lines.
Market Restraints
- Phosphate and nitrogen input volatility:Fertilizer cost spikes are squeezing farmer working capital and deferring premium seed upgrades.
- USDA Plant Variety Protection enforcement:IP litigation friction is slowing trait-stacking approvals and extending commercialization timelines.
- Gene-editing regulatory divergence:Brazil's CTNBio, Argentina's CONABIA, and EU EFSA maintain incompatible classification frameworks for edited varieties.
Strategic Opportunities
- India's Seed Control Order implementation:Formalizing seed quality standards creates certification-driven demand for branded hybrid corn and pearl millet lines.
- Carbon credit-linked agronomy:Regenerative farming protocols are creating premium positioning for cover-crop-compatible grain varieties.
- Direct-to-farm digital platforms:Bypassing traditional distributor networks in Australia's wheat belt and Canada's prairie provinces.
Industry Challenges
- Trait licensing negotiation complexity:Stacked biotechnology events require multi-party IP agreements that extend product development timelines.
- Phytosanitary certification bottlenecks:OECD Seed Scheme compliance documentation delays are constraining cross-border shipment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grain Seed Market |
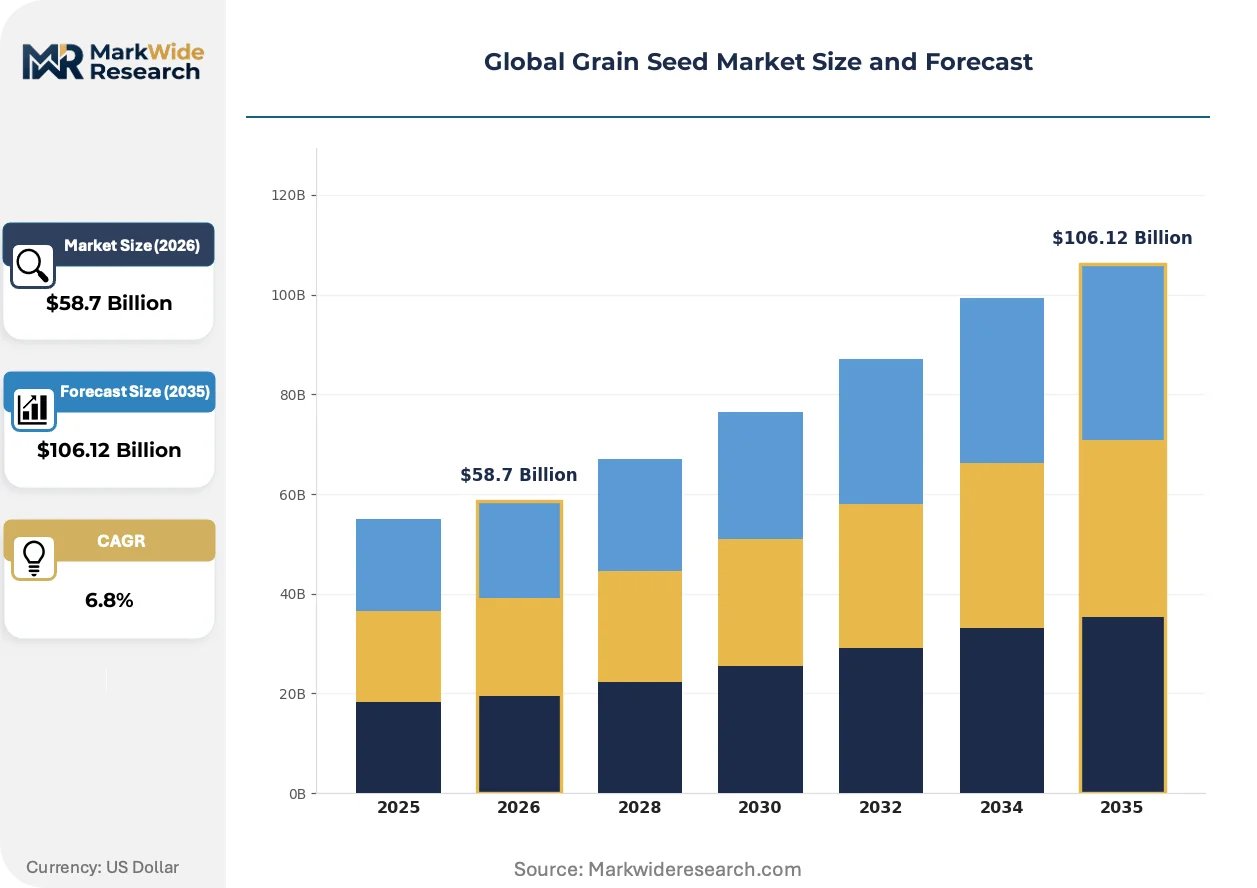
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Corn, Wheat, Barley, Sorghum, Millet Technology: Conventional, Hybrid, Genetically Modified, Organic, Marker-Assisted Selection Application: Animal Feed, Biofuel Production, Human Consumption, Industrial Use, Seed Multiplication End User: Seed Companies, Agricultural Cooperatives, Research Institutions, Contract Farmers |
| Companies Covered | Bayer, Corteva, Syngenta, Groupe Limagrain, BASF, KWS SAAT, Limagrain, AgReliant Genetics, Sakata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grain Seed Market Shifts & Advancements
Gene-editing platforms are compressing varietal development timelines while regulatory frameworks scramble to classify novel traits, creating temporary competitive windows for first movers.
RNA interference traits targeting rootworm and corn borer pressure are supplanting Bt toxin reliance in North American corn belts. Large-scale farming cooperatives in Iowa and Illinois are adopting these traits at accelerating rates. The technology is enabling reduced refuge planting requirements and compressing insect resistance management costs.
REACH chemical compliance and the EU Green Deal's Farm to Fork strategy are tightening maximum residue limits for seed treatment compounds. Seed exporters to European markets are reformulating coating chemistries and accelerating biological alternative development. Small-grain cereal segments face the steepest reformulation timelines given established fungicide dependencies.
Farmer buying committees are consolidating procurement decisions across multi-state operations, displacing individual farm-level seed selection. Regional distributor networks in the US Corn Belt and Ukraine's Black Sea corridor are losing volume to direct manufacturer relationships. This concentration is most visible among ethanol-integrated farming enterprises securing multi-year supply agreements.
Global Grain Seed Market Segmentation
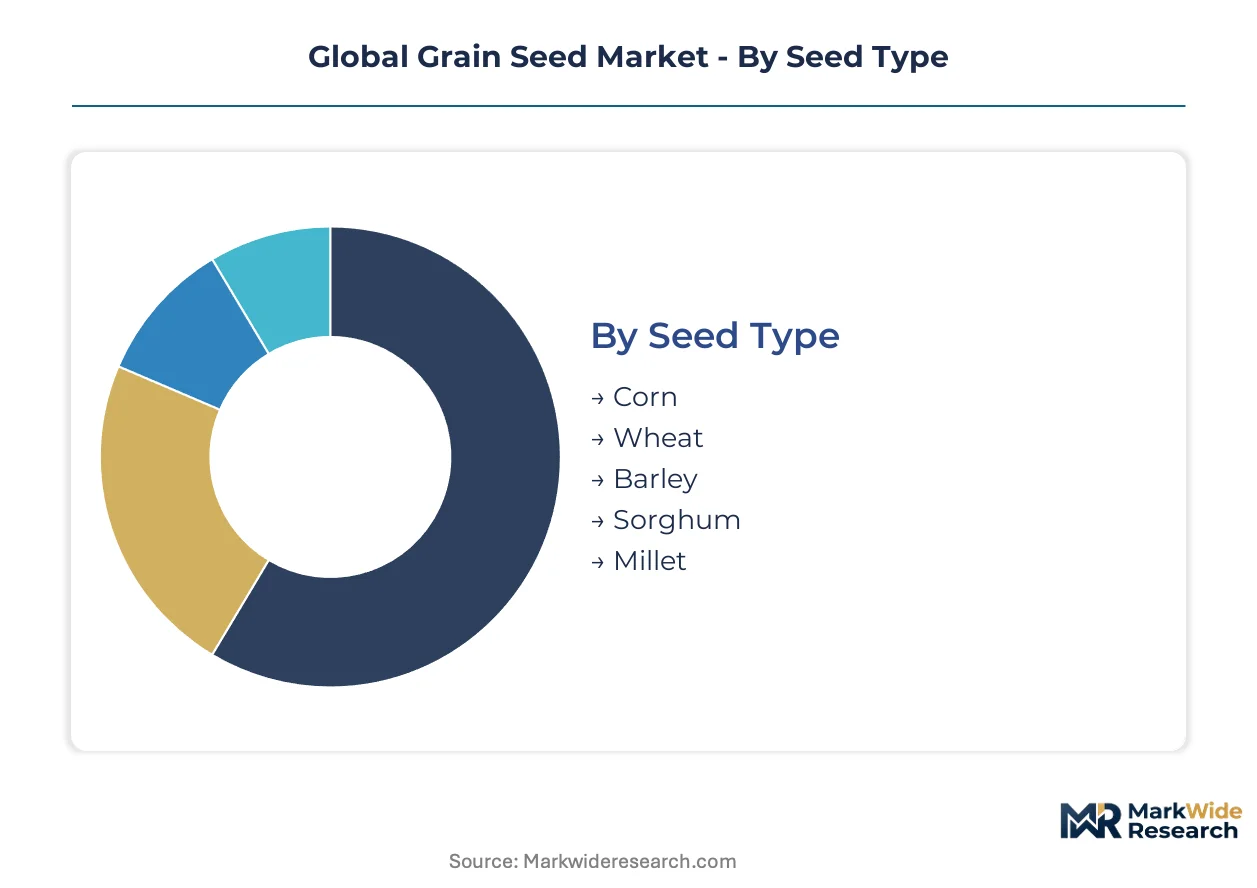
Grain seed segmentation reveals distinct margin architectures across reproductive material categories. Technology tiers and crop species create divergent pricing power depending on trait complexity and regulatory acceptance.
Seed Type:
Margin pools concentrate in hybrid corn given dual-use feed and ethanol demand, while wheat seed operates on volume-driven economics.
- Corn:Dual-purpose grain dominates value capture through hybrid trait stacking for ethanol-integrated farming enterprises and concentrated animal feeding operations. Iowa and Illinois cooperatives drive recurrent replacement cycles demanding higher germination consistency.
- Wheat:Temperate cereal systems across the US Great Plains and Ukraine's Black Sea corridor sustain mature volume positions with lower per-unit margins than hybrid alternatives. Australia's wheat belt procurement committees favor certified seed for export quality compliance.
- Barley:Malt-quality specifications for brewing applications command modest premiums over feed-grade lines in European and North American contracting systems.
- Sorghum:Heat-tolerant lines gain traction in India's semi-arid zones and Nigeria's northern grain belts where water stress limits corn viability.
- Millet:Pearl millet hybrids under India's Seed Control Order are formalizing quality tiers previously dominated by farmer-saved seed.
The dominant share belongs to corn, while millet is closing the gap fastest through formal hybridization programs.
Technology:
Cost tier stratification separates biotech-licensed premiums from certified organic positioning across regulatory jurisdictions.
- Hybrid:Controlled pollination systems deliver heterosis-driven yield floors that commercial operators in Brazil's Cerrado prioritize over seed cost. Brazilian and Argentinian regulatory frameworks accelerate approval velocity relative to European counterparts.
- Genetically Modified:Stacked biotechnology events capture pricing premiums in markets with CTNBio and USDA regulatory acceptance, though EU marketing restrictions constrain geographic deployment. RNA interference traits for rootworm resistance are supplanting earlier Bt toxin reliance.
- Conventional:Open-pollinated varieties retain cost-optimized positioning among smallholder systems and organic transition farmers.
- Organic:Certified reproductive material serves contract farmers supplying EU and North American certified supply chains under tightening residue limits.
- Marker-Assisted Selection:Genomic screening accelerates conventional breeding timelines without triggering GMO classification debates.
Hybrid technology holds the largest revenue footprint, with marker-assisted selection expanding most quickly as regulatory uncertainty around gene-editing persists.
Application:
Volume concentration tracks downstream commodity price cycles and biofuel policy mandates.
- Animal Feed:Corn and soybean meal substitution ratios drive seed procurement decisions among US and Brazilian integrated protein producers. Lysine-optimized hybrids command procurement premiums from poultry and swine operations.
- Biofuel Production:Ethanol-integrated farming enterprises in the US Corn Belt secure multi-year supply agreements with direct manufacturer relationships, displacing traditional distributor networks.
- Human Consumption:Quality protein maize and high-zinc wheat varieties target nutrition intervention programs in South Asia and sub-Saharan Africa.
- Industrial Use:Starch and adhesive applications sustain steady demand for specific endosperm texture profiles.
- Seed Multiplication:Foundation seed production requires genetic purity certification under OECD Seed Scheme protocols.
Animal feed consumes the greatest seed volume, while biofuel production is gaining share fastest through policy-linked demand expansion.
End User:
Customer type determines procurement scale and price sensitivity thresholds.
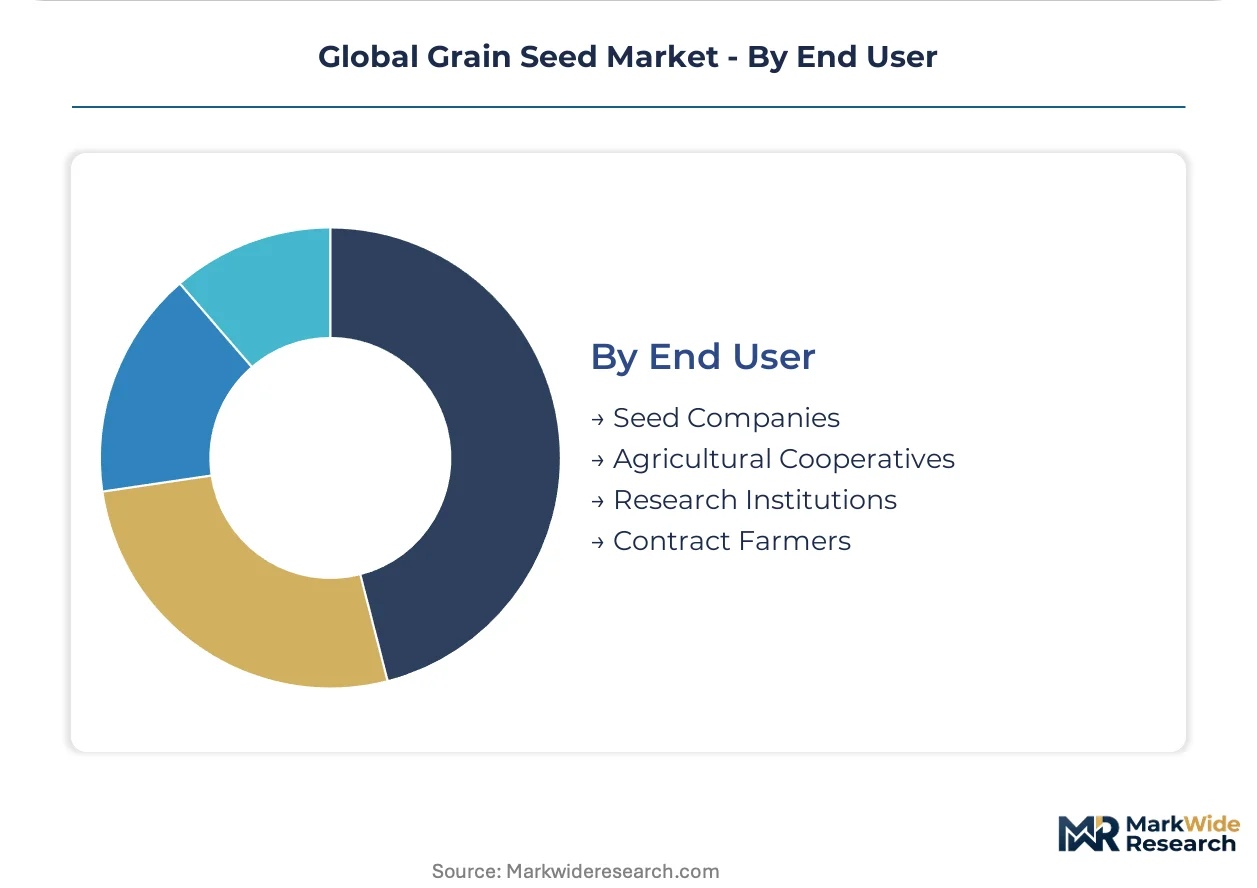
- Agricultural Cooperatives:Multi-state buying committees consolidate decisions across Iowa, Illinois, and Nebraska operations, extracting volume discounts from manufacturers.
- Contract Farmers:Certified supply chain requirements mandate specific varietal registrations and treatment protocols for EU and North American export markets.
- Seed Companies:Germplasm licensing and trait stacking negotiations dominate R&D procurement budgets.
- Research Institutions:Public breeding programs in India and Brazil maintain germplasm libraries for climate adaptation screening.
Agricultural cooperatives represent the largest procurement segment, with contract farmers climbing the fastest as certified supply chains formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports hybrid corn seed genetics to Argentina's Pampas farming belt while US germplasm flows north to Canadian prairie provinces. Trade corridors concentrate trait licensing revenue in breeding hubs with regulatory acceleration advantages.
United States
Iowa and Illinois ethanol-integrated cooperatives drive recurrent hybrid corn replacement cycles demanding higher germination consistency. The USDA's Plant Variety Protection Office enforces IP frameworks that shape trait-stacking approval timelines. Research clusters in Johnston, Iowa and Indianapolis anchor biotech breeding pipelines serving North American corn belts.
Brazil
Soybean-corn rotation systems across Mato Grosso and Goiás intensify planted hectares and compress seed replacement intervals. CTNBio maintains accelerated regulatory velocity for gene-edited varieties relative to European counterparts. The Cerrado biome concentration around Rondonópolis draws multi-year supply agreements from global seed manufacturers.
India
Pearl millet and hybrid corn demand concentrates in Maharashtra and Karnataka semi-arid zones transitioning from farmer-saved seed. The Seed Control Order formalizes quality tiers that filter uncertified suppliers from commercial distribution. Haryana's research institutions maintain public germplasm libraries for climate adaptation screening.
Germany
EU Seed Marketing Directives tighten genetic purity thresholds that concentrate procurement among certified distributors. REACH chemical compliance mandates reformulation of seed treatment compounds for export-bound cereal lines. KWS SAAT anchors breeding operations in Einbeck with germplasm libraries spanning multiple temperate grain species.
China
Domestic hybrid corn procurement scales in Heilongjiang and Jilin provinces support concentrated animal feeding operation expansion. The Ministry of Agriculture and Rural Affairs enforces distinct biosafety frameworks for trait-enhanced varieties. Yangling Agricultural Hi-tech Industry Demonstration Zone hosts public breeding programs screening drought-tolerant lines.
Global Grain Seed Market Competitive Landscape
Player mix skews toward integrated agrochemical-seed conglomerates with trait platform dominance. Three multinational groups control germplasm licensing velocity through stacked biotechnology event portfolios. Competitive dynamics center on M&A consolidation of regional breeding stations and strategic partnerships with gene-editing technology providers.
Among integrated conglomerates, Bayer and Corteva occupy positions spanning multiple grain species and climate zones. Syngenta exemplifies the crop solution bundling archetype that extends positioning beyond standalone seed sales. BASF and KWS SAAT represent specialized players with concentrated germplasm depth in specific cereal segments. Groupe Limagrain anchors European cooperative ownership structures that differ from publicly traded competitors.
| Leading Market Players |
|---|
| Bayer |
| Corteva |
| Syngenta |
| Groupe Limagrain |
| BASF |
| KWS SAAT |
| Limagrain |
| AgReliant Genetics |
| Sakata |
| Others |
Supply & Pricing Matrix
RNA interference trait substitution for Bt toxin stacks simultaneously redraws breeding investment geography toward CTNBio-accelerated Brazil and widens the pricing spread between gene-edited premiums and conventional hybrid floors.
Pricing Analysis
The technology-generation pricing gap between CRISPR-edited lines, stacked RNAi hybrids, and first-generation Bt varieties stratifies procurement budgets across Brazilian Cerrado cooperatives and Iowa ethanol-integrated enterprises. Three-tier pricing structure across premium gene-edited, standard biotech-stacked, and economy conventional levels reflects germplasm licensing velocity and OECD Seed Scheme certification tier. Pricing pressure stems from phosphate and nitrogen input volatility squeezing farmer working capital and deferring premium seed upgrades. Smallholder systems and organic transition farmers exhibit highest price sensitivity, while ethanol-integrated farming enterprises securing multi-year supply agreements demonstrate lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs through Santos and Paranaguá port congestion, combined with container availability constraints on the Asia-Brazil grain trade lane, compress cross-border shipment windows for OECD Seed Scheme-certified lots. Germplasm concentration centers on Johnston, Iowa and Indianapolis research clusters for North American deployment, with Rondonópolis anchoring Brazilian Cerrado distribution and Einbeck serving European temperate cereal systems. Production rests on proprietary inbred parent lines, trait licensing agreements, and phytosanitary-certified foundation seed multiplication. Single-source vulnerability in stacked biotechnology IP negotiations constrains supply security. Distribution runs through direct manufacturer relationships with ethanol-integrated cooperatives and certified distributor networks serving contract farmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global grain seed market functions as a defensive-moat arena where regulatory entrenchment through OECD Seed Scheme certification and USDA Plant Variety Protection enforcement creates substantial switching costs for commercial operators.
For Market Incumbents: Compound trait platform dominance through accelerated germplasm licensing velocity in CTNBio-favorable Brazilian jurisdictions and backward integration into gene-editing technology providers. Defend against RNAi trait substitution threats by securing multi-party IP agreements for stacked biotechnology events before regulatory divergence hardens. Prioritize certification investment in India's Seed Control Order formalization to filter uncertified competitors from commercial distribution channels. For New Entrants and Emerging Players: Seed Control Order fast-track certification in Maharashtra and Karnataka semi-arid zones opens procurement access previously dominated by farmer-saved pearl millet lines. Target Australia's wheat belt direct-to-farm digital platforms bypassing traditional distributor networks concentrated among ethanol-integrated enterprises. Carbon credit-linked regenerative farming protocols offer white-space positioning for cover-crop-compatible grain varieties with premium procurement potential. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional breeding stations holding concentrated germplasm depth in specific climate zones but lacking trait stacking capabilities. Long-term viability hinges on gene-editing regulatory convergence across Brazil, Argentina, and European Union jurisdictions over the projection horizon. Watch CTNBio approval velocity for drought-tolerant lines as inflection indicator for portfolio repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Platform Licensing Acceleration | Compresses R&D payback periods for CRISPR-edited drought-tolerant lines in Brazilian Cerrado systems. |
| Direct-to-Farm Digital Platform Launch | Bypasses traditional distributor networks in Australia's wheat belt and Canada's prairie provinces. |
| Seed Control Order Certification Investment | Filters uncertified suppliers from India's commercial hybrid corn and pearl millet distribution. |
| Carbon Credit-Linked Agronomy Partnership | Creates premium positioning for cover-crop-compatible varieties in EU regenerative supply chains. |
| Gene-Editing Technology Acquisition | Secures in-house CRISPR capabilities ahead of regulatory classification stabilization across key markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed company R&D directors, agricultural cooperative procurement committee members, regulatory affairs leads at germplasm licensing firms, and foundation seed multiplication facility managers. Secondary validation drew from USDA Plant Variety Protection Office filings, CTNBio trait approval databases, OECD Seed Scheme certification records, and EU Seed Marketing Directive implementation guidance. Bottom-up volume estimates from country-level planted hectare data and top-down value triangulation from manufacturer revenue disclosures were reconciled across the analysis window.
The projection horizon spans segmentation by seed type, technology tier, application end-use, and customer archetype with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation of replacement cycle compression rates, trait penetration curves, and policy-linked biofuel demand expansion. Forecast inputs incorporated germplasm licensing velocity timelines and gene-editing regulatory classification scenarios without specific year anchors.
Decision-makers should treat outputs as directional under assumptions of stable OECD Seed Scheme phytosanitary frameworks and continued CTNBio regulatory acceleration; material deviation through EU-EFSA gene-editing reclassification or USDA IP litigation friction would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Sports Turf Seed Market
Seeds
Pasture Seeds Market
Seeds
India Seed Market
Seeds
Sesame Seeds Market
Seeds
Vegetable Seed Protein Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Europe Forage Seed Market
Seeds
Africa Peas Market
Seeds
Global Sorghum Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Perilla Seed Oil Market
Seeds
Asia-Pacific Cotton Seed Market