
 Avena Sativa Market | 2026-2036
Avena Sativa Market Size, Share, and Industry Trends Forecast 2026-2036
Avena Sativa Market Outlook
The capability gap between integrated millers and commodity traders is collapsing as scale advantages in oat processing consolidate. Grain Millers Inc leverages captive grain origination networks across North American prairie corridors. European Oat Millers anchors its position through backward integration into certified seed programs and varietal development. Bob's Red Mill Natural Foods differentiates via stone-ground milling heritage and direct-to-consumer channel control.
Avena sativa, commonly cultivated oats, comprises approximately 12-14% protein by dry weight with beta-glucan soluble fiber concentrations of 3-5% in groat endosperm, serving as a functional ingredient in human nutrition, animal feed formulations, and cosmetic emulsions. Rolled oats and oat flour command the deepest margin pools within product type segments, driven by ready-to-eat cereal and bakery applications. The food and beverage end use industry dominates volume absorption, while cosmetics represents the fastest-growing outlet as oat-derived colloids replace synthetic stabilizers in dermatological formulations.
The USDA oversees oat grading standards and pesticide residue limits under the Grain Standards Act, while the EU Green Deal and REACH framework govern carbon intensity disclosures and chemical inputs in European oat supply chains. FDA nutrition labeling requirements and health claim substantiation rules shape how oat beta-glucan benefits are communicated to consumers. Stakeholders must monitor evolving clean-label certification thresholds and carbon accounting methodologies that will determine premium market access for sustainably milled oat ingredients.
Market Dynamics
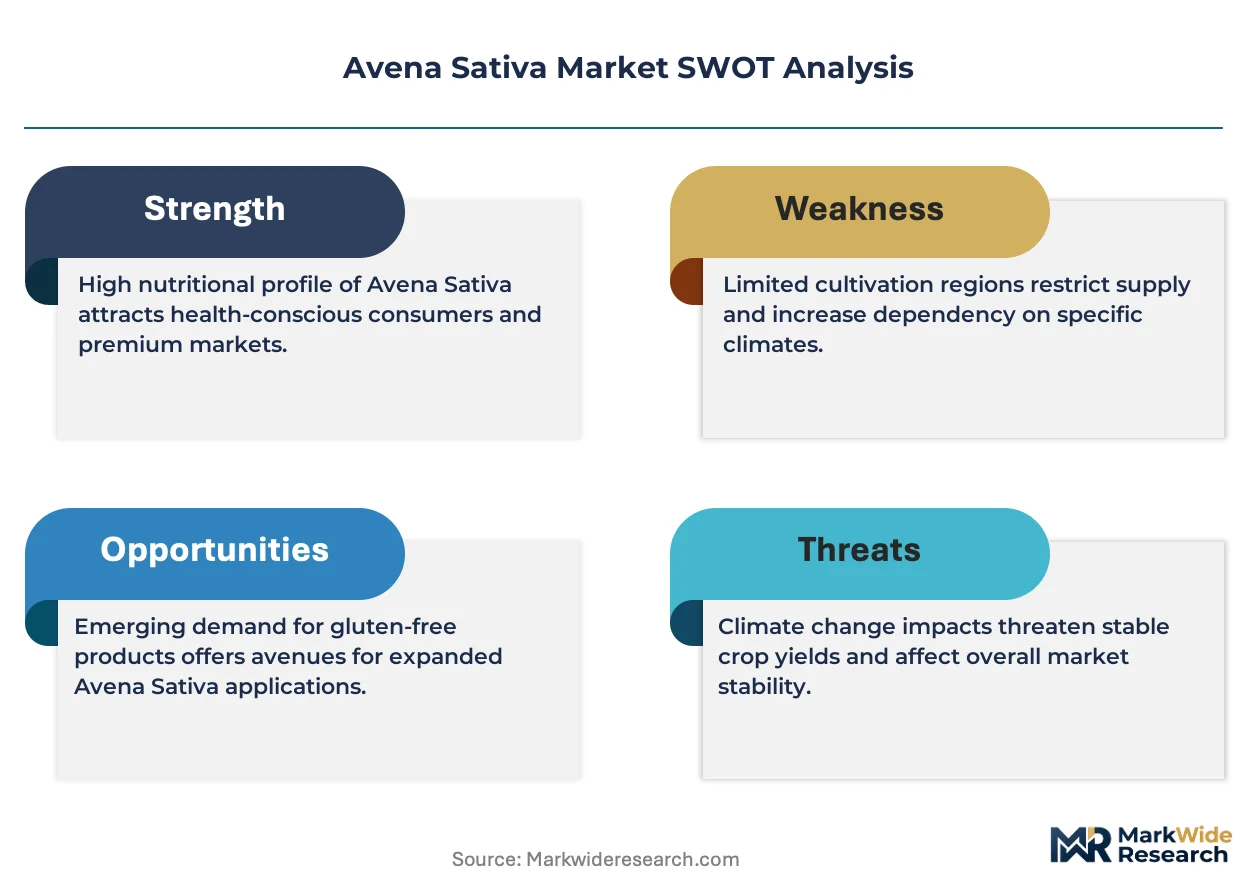
The EU Green Deal and F-Gas Regulation are compressing carbon intensity thresholds across European oat supply chains, forcing millers to reconfigure energy inputs and origination networks simultaneously.
Growth Catalysts
- Plant-Based Nutrition Pivot:Food and beverage manufacturers are expanding oat-based product lines as consumers reduce dairy consumption. Bakery and ready-to-eat cereal applications absorb the deepest volume pools.
- REACH Chemical Framework:The EU's chemical disclosure mandates are elevating demand for clean-label oat ingredients with traceable input histories. Premium positioning follows compliance certification.
- Beta-Glucan Dermatology:Oat-derived colloids are replacing synthetic stabilizers in cosmetic emulsions. Formulators prize the 3-5% soluble fiber concentration in groat endosperm for skin barrier applications.
Market Restraints
- Input Cost Volatility:Natural gas and electricity price swings in German milling clusters around Hamburg and Bremen compress operating margins for thermal-intensive kilning operations.
- Supply Concentration Risk:Premium oat varietal development concentrates within backward-integrated European seed programs. Smaller millers face captive supply constraints from dominant certified seed holders.
- Substitution Threat:Pea and rice proteins are capturing share in plant-based beverage formulations where oat milk previously dominated shelf space.
Strategic Opportunities
- Carbon Accounting Premiums:The EU Green Deal's evolving disclosure methodologies will determine market access for sustainably milled oat ingredients. Early adopters capture price premiums.
- Direct-to-Consumer Channel Control:Stone-ground heritage positioning enables margin retention bypassing conventional wholesale distribution. E-commerce fulfillment infrastructure supports this pivot.
- Animal Feed Formulation:Underpenetrated aquaculture and pet nutrition segments present volume expansion paths beyond human food applications.
Industry Challenges
- Clean-Label Certification Timelines:Third-party verification of pesticide residue compliance under USDA Grain Standards Act creates 90-120 day approval bottlenecks for new supplier onboarding.
- Retrofitting Legacy Kilns:Thermal processing equipment designed for conventional grain handling requires capital-intensive modification to meet EU F-Gas refrigerant phase-out schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avena Sativa Market |
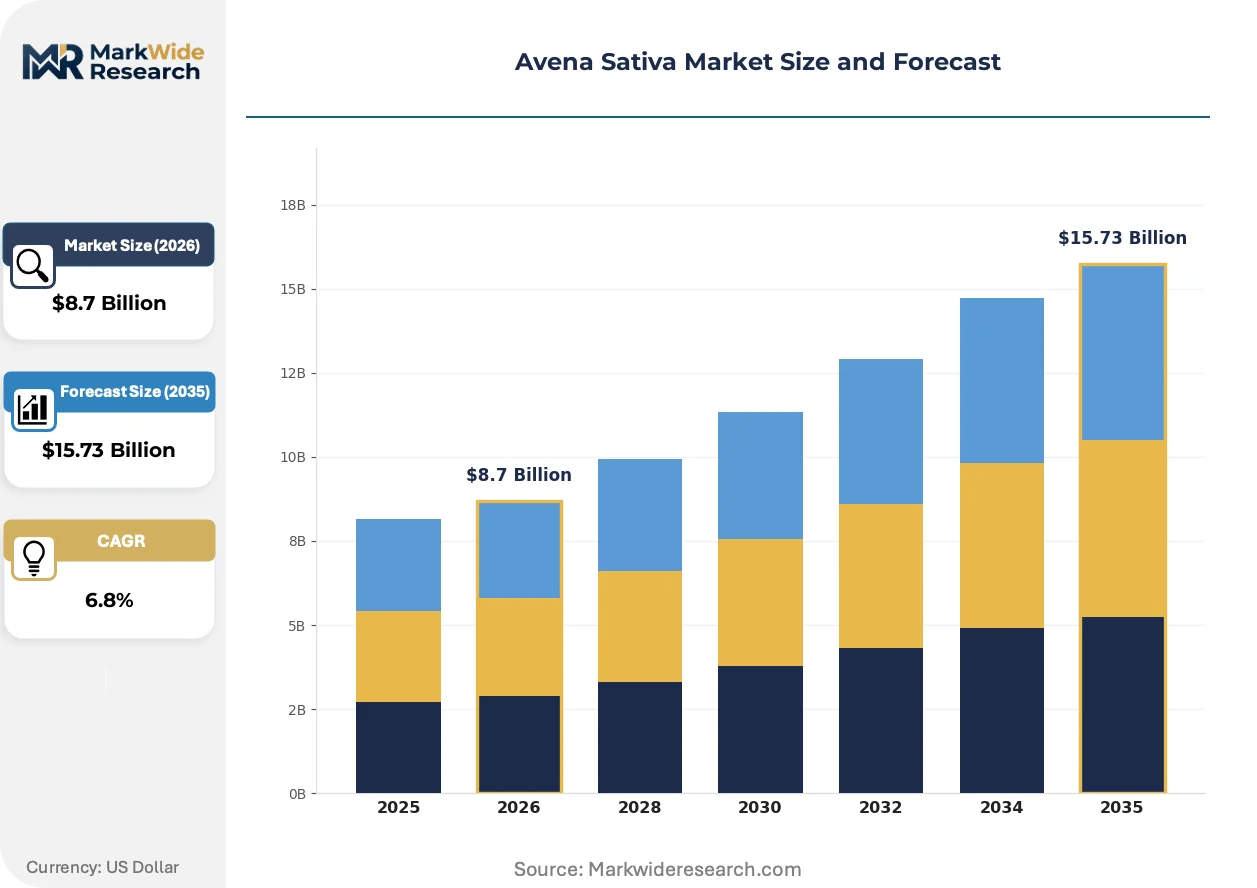
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Oats, Rolled Oats, Oat Flour, Oat Bran End Use Industry: Food & Beverage, Healthcare, Animal Feed, Cosmetics Form: Dry, Liquid, Powder, Flakes Packaging Type: Bag, Box, Bulk, Sachet |
| Companies Covered | European Oat Millers, Grain Millers Inc, PEPscO, Inc., Mornflake, Nature's Path Foods, The Hain Celestial Group, Inc., Bob's Red Mill Natural Foods, Jordans Mill, Oat Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avena Sativa Market Strategic Shifts
Novel milling technologies and regulatory disclosure mandates are restructuring how oat processors compete on transparency and functional ingredient purity.
Precision kilning with infrared moisture sensing is supplanting conventional steam conditioning in premium oat groat processing. North American prairie corridor millers are retrofitting facilities to capture beta-glucan integrity through gentler thermal curves. This equipment shift is compressing yield differentials between commodity and specialty-grade processors.
The EU Green Deal's carbon border adjustment mechanism is tightening disclosure requirements for agricultural inputs entering European supply chains. Millers must now document fertilizer application rates and transport emissions across multi-tier supplier networks. German export-oriented processors face the steepest compliance ramps as Hamburg and Bremen clusters serve premium Asian markets.
Ingredient buyers are consolidating supplier relationships around vertically integrated origination networks. Food manufacturers now audit seed certification, varietal purity, and processing methodology through single-source contracts rather than spot-market purchasing. This consolidation pattern is most visible in German milling clusters where backward-integrated processors control certified oat programs from field to finished ingredient.
Avena Sativa Market Segmentation
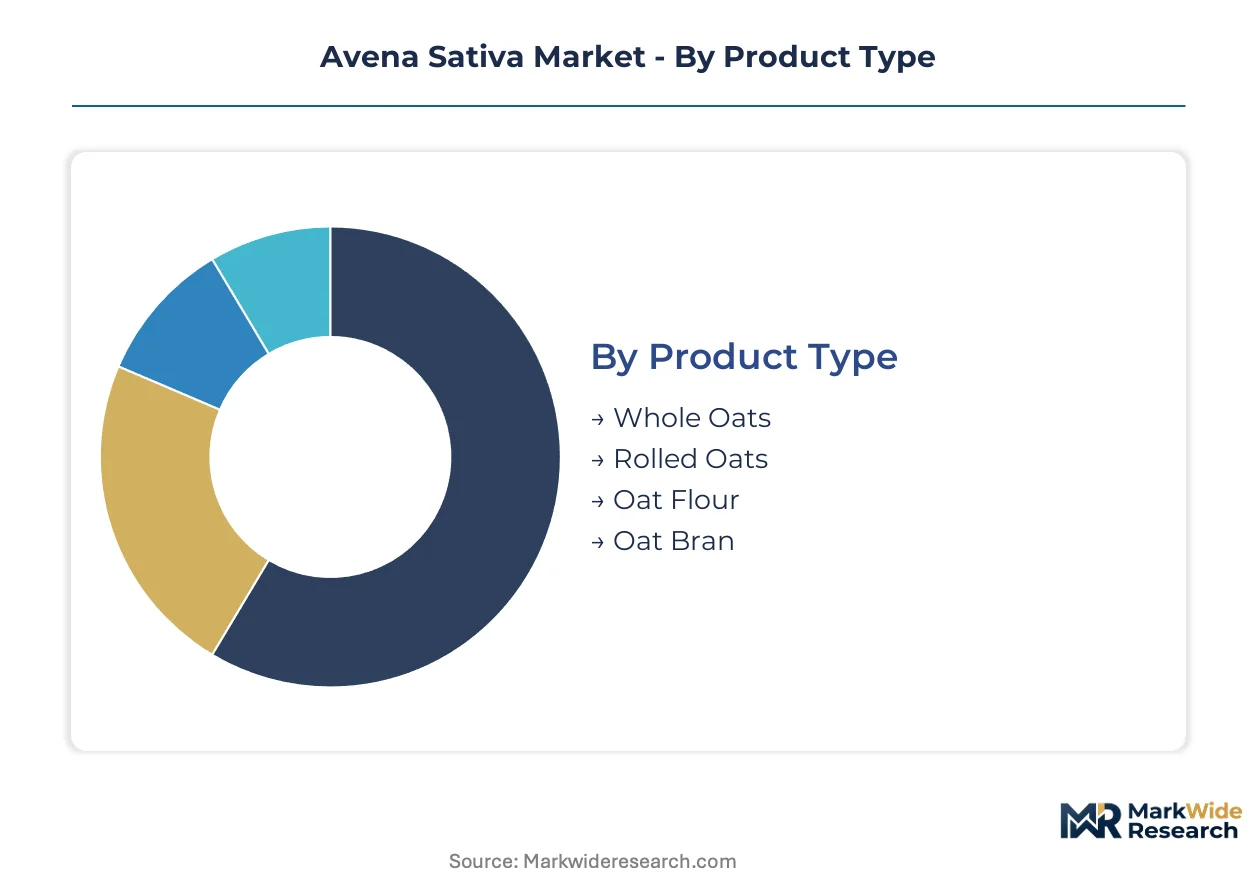
Oat processors compete across distinct specification tiers where regulatory compliance thresholds determine premium positioning. FDA beta-glucan health claim substantiation and EU REACH chemical disclosure mandates create divergent margin architectures across product categories.
Product Type:
FDA nutrition labeling requirements and EU EFSA health claim frameworks differentiate milling specifications across oat ingredient categories. Clean-label certification thresholds under USDA Grain Standards Act further stratify commercial positioning.
- Rolled Oats:Steam-stabilized groats processed through precision kilning with infrared moisture sensing retain 3-5% beta-glucan concentrations. German milling clusters around Hamburg and Bremen dominate export supply for ready-to-eat cereal manufacturers seeking EFSA-compliant health claim substantiation. Thermal curve optimization preserves functional fiber integrity for bakery applications.
- Oat Flour:Stone-ground or roller-milled groats milled to sub-150 micron particle size enable clean-label binding in gluten-free formulations. REACH chemical disclosure mandates favor traceable origination networks with documented pesticide residue compliance under USDA protocols. Precision particle distribution controls water absorption rates in industrial bakery mixes.
- Whole Oats:Unprocessed groat-in-hull format serving animal feed formulations and traditional food applications with minimal processing overhead.
- Oat Bran:Concentrated beta-glucan layer separated through air classification for functional ingredient fortification in nutraceutical applications.
Rolled oats handles the majority of throughput; oat flour is expanding most quickly on share.
End Use Industry:
Customer procurement patterns concentrate volume absorption around three dominant channels while emerging applications reshape growth trajectories.
- Food & Beverage:Ready-to-eat cereal, bakery, and plant-based beverage manufacturers absorb the deepest volume pools. FDA health claim rules for beta-glucan cholesterol reduction drive formulation specifications. German export processors supply Asian markets with EFSA-compliant ingredient documentation.
- Cosmetics:Oat-derived colloids replace synthetic stabilizers in dermatological emulsions. Formulators prize Avena sativa lipid fractions for skin barrier repair. EU REACH framework governs chemical input disclosure for cosmetic-grade oat extracts.
- Healthcare:Medical nutrition and enteral feeding applications leverage hypoallergenic protein profiles.
- Animal Feed:Underpenetrated aquaculture and pet nutrition segments present volume expansion paths beyond human food channels.
Food and beverage commands the dominant share position; cosmetics is climbing the fastest on volume trajectory.
Form:
Processing methodology and shelf-stability requirements segment oat ingredients across physical states with distinct supply chain configurations.
- Dry:Kilned groats and flakes with sub-12% moisture content enable ambient distribution economics. German milling clusters optimize thermal processing for extended shelf stability in export markets.
- Liquid:Enzymatically treated oat bases for plant-based beverage manufacturing require aseptic filling infrastructure and cold-chain distribution.
- Powder:Spray-dried or roller-dried concentrates for instant beverage and nutritional fortification applications.
- Flakes:Quick-cooking and instant formats for hot cereal and granola manufacturing with specific flake thickness tolerances.
Dry form maintains the largest installed processing base; liquid form is gaining share fastest as plant-based beverage capacity expands.
Packaging Type:
Channel economics and customer scale determine packaging specification with direct-to-consumer disruption reshaping traditional formats.
- Bulk:Railcar and tanker shipments for industrial food manufacturers with integrated milling capabilities. USDA Grain Standards Act inspection protocols govern loading documentation.
- Bag:Multiwall paper or woven polypropylene for ingredient distributors and smaller-scale food processors.
- Box:Retail-ready formats for grocery channel placement with shelf-impact graphics and resealability features.
- Sachet:Single-serve portions for foodservice and convenience applications with precise portion control.
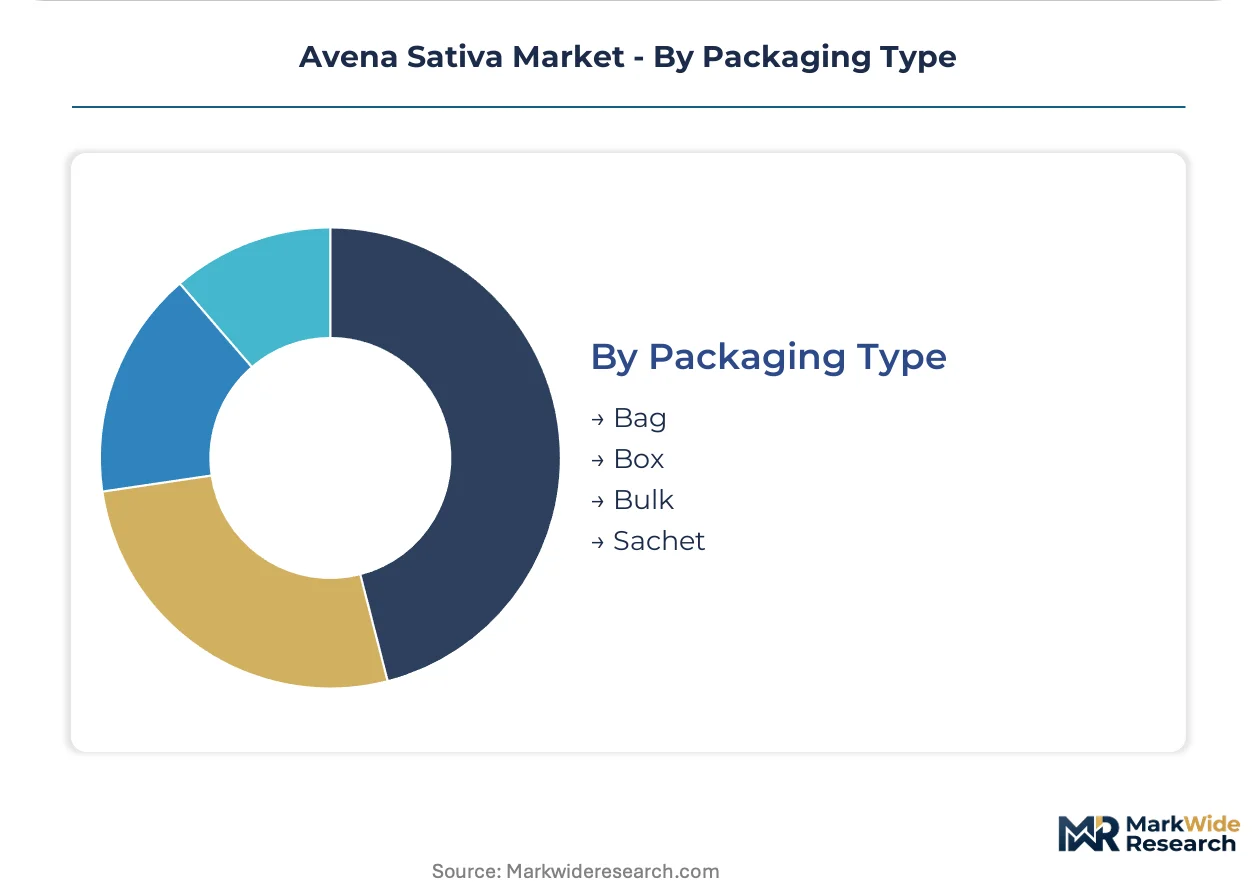
Bulk packaging moves the greatest tonnage; sachet formats are expanding most rapidly through foodservice channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German milling clusters command premium pricing power against North American prairie corridor suppliers, creating a transatlantic arbitrage in oat ingredient sourcing that shapes procurement patterns across food and beverage manufacturers.
United States
Plant-based beverage manufacturers and ready-to-eat cereal producers drive oat ingredient absorption across the Great Plains and Pacific Northwest. The USDA Grain Standards Act governs pesticide residue limits and grading protocols for domestic and export shipments. Minneapolis-St. Paul anchors the largest North American milling concentration, with prairie corridor origination networks feeding integrated processing facilities.
Germany
Export-oriented processors supply premium oat varieties to Asian markets with EFSA-compliant health claim documentation. The EU Green Deal and F-Gas Regulation mandate carbon intensity disclosures and refrigerant phase-outs across Hamburg and Bremen milling clusters. Hamburg's port-adjacent kilning operations face steep retrofitting costs to meet thermal efficiency thresholds.
Canada
Prairie oat production serves both domestic food processors and trans-Pacific export channels with non-GMO positioning. Health Canada and PMRA oversee pesticide maximum residue limits and novel food ingredient approvals. Saskatchewan and Manitoba field operations supply Winnipeg and Calgary milling facilities with high-beta-glucan varietals.
United Kingdom
Heritage stone-ground positioning and direct-to-consumer channel development differentiate smaller-scale millers from industrial competitors. REACH chemical disclosure mandates and post-Brexit regulatory divergence complicate cross-border supply chain compliance. Cambridgeshire and Yorkshire retain traditional milling infrastructure now retrofitting for clean-label certification.
Sweden
Functional ingredient R&D concentrates around oat beta-glucan extraction for nutraceutical and dermatological applications. The EU Green Deal's carbon border adjustment mechanism pressures documentation of fertilizer and transport emissions across supplier tiers. Lund and Uppsala host research clusters linking agricultural universities to commercial extraction facilities.
Avena Sativa Market Competitive Environment
Concentration sits with backward-integrated millers controlling certified seed programs from field to finished ingredient. The vendor base spans three tiers: multinational grain processors with captive origination networks, regional specialists leveraging heritage positioning and direct channel control, and commodity traders facing margin compression from scale-advantaged competitors. Two competitive moves dominate: retrofitting legacy kilns for EU F-Gas compliance, and consolidating supplier relationships around single-source contracts with full traceability documentation.
Within the heritage-positioned tier, Bob's Red Mill Natural Foods and Nature's Path Foods exemplify direct-to-consumer channel strategies that bypass conventional wholesale distribution. European Oat Millers anchors the backward-integrated archetype through certified oat programs spanning varietal development to export-grade processing. Grain Millers Inc occupies the scale-driven position with North American prairie corridor origination networks.
| Leading Market Players |
|---|
| European Oat Millers |
| Grain Millers Inc |
| PEPscO, Inc. |
| Mornflake |
| Nature's Path Foods |
| The Hain Celestial Group, Inc. |
| Bob's Red Mill Natural Foods |
| Jordans Mill |
| Oat Services Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization disparities between Hamburg-Bremen milling clusters and North American prairie corridor processors create divergent cost floors that stratify oat ingredient pricing across export tiers. German export-oriented kilning operations absorb steep EU F-Gas retrofitting costs that transmit into premium positioning for EFSA-compliant health claim documentation, while prairie corridor millers compete on volume throughput with lower thermal processing overhead.
Pricing Analysis
The customization-premium spread separates stone-ground heritage positioning from commodity roller-milled supply, with three-tier pricing structure across premium, standard, and economy levels governing oat flour and rolled oats segments. Price differentiation hinges on beta-glucan concentration certification and USDA Grain Standards Act compliance tier, with organic and clean-label varietals commanding spreads over conventional grades. Cost compression in standard-tier supply is intensifying because natural gas price volatility in German clusters compresses kiln operating margins. Industrial food manufacturers exhibit highest price sensitivity due to formulation cost targets, while cosmetic formulators show lowest sensitivity given functional ingredient performance requirements.
Supply Chain Analysis
Germany and Canada anchor premium oat varietal production through backward-integrated certified seed programs, with Saskatchewan field operations supplying high-beta-glycan groats to Winnipeg milling facilities and Hamburg clusters serving Asian export markets. Raw material flows draw from prairie corridor grain origination networks and EU varietal development stations, with beta-glucan integrity preserved through precision kilning equipment. Single-source vulnerability concentrates in certified oat seed stock controlled by dominant European breeding programs. Distribution runs through bulk railcar shipments for industrial manufacturers and direct-to-consumer e-commerce fulfillment for heritage-positioned brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Avena Sativa Market represents a high-growth disruption as EU Green Deal carbon border adjustment mechanisms restructure competitive access for sustainably milled ingredients. Precision kilning technology and REACH chemical disclosure mandates are compressing the capability gap between integrated millers and commodity traders.
For Market Incumbents: Secure captive origination networks through certified oat program expansion in Saskatchewan and Manitoba prairie corridors to defend against pea and rice protein substitution in plant-based beverages. Retrofit legacy kilns for EU F-Gas refrigerant phase-out compliance ahead of disclosure mandate deadlines to preserve Hamburg-Bremen cluster premium positioning. For New Entrants and Emerging Players: Anchor in underpenetrated aquaculture and pet nutrition feed formulations where oat protein hypoallergenic profiles remain unexploited. Target direct-to-consumer stone-ground heritage positioning with e-commerce fulfillment infrastructure to bypass wholesale margin compression and capture clean-label certification premiums. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated milling assets with certified seed program control over commodity trading operations lacking varietal development capabilities. Long-term viability across the projection horizon rests on carbon accounting methodology compliance infrastructure and beta-glucan extraction R&D capabilities. The signal to watch is EU Green Deal carbon border adjustment mechanism implementation timing for agricultural input documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Kilning Retrofit | Infrared moisture sensing preserves beta-glucan integrity for EFSA health claim substantiation. |
| Certified Seed Program Expansion | Backward integration into varietal development secures supply against European seed concentration. |
| Direct-to-Consumer Channel Buildout | Heritage stone-ground positioning bypasses wholesale margin compression in retail grocery. |
| Carbon Accounting Infrastructure | EU Green Deal disclosure methodologies determine premium market access for export-grade ingredients. |
| Aquaculture Feed Formulation Entry | Underpenetrated fish and pet nutrition segments expand volume beyond human food applications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with oat millers, grain origination specialists, and food formulation scientists, and secondary validation through USDA Grain Standards Act filings, EU EFSA health claim registers, and customs trade documentation. Primary fieldwork captured thermal processing equipment specifications, certified seed program structures, and carbon accounting methodology implementation timelines across Hamburg, Minneapolis-St. Paul, and Winnipeg milling clusters. Secondary sources included FDA nutrition labeling guidance documents, REACH chemical disclosure frameworks, and agricultural university research publications on beta-glucan extraction technologies. Bottom-up volume modeling triangulated against top-down market sizing from grain production statistics and processing capacity utilization estimates.
Across the analysis window, forecasts integrated product type segmentation by beta-glucan concentration tier, end-use industry absorption patterns across food and beverage versus cosmetics channels, and form factor distribution economics for dry versus liquid oat bases. CAGRs derived from historical volume trajectories, capacity expansion announcements, and substitution elasticity estimates for plant-based protein alternatives. Industry-specific inputs incorporated EU F-Gas phase-out schedules, clean-label certification adoption curves, and carbon border adjustment mechanism implementation pathways.
Material uncertainties — regulatory timeline delays, input cost volatility in natural gas and electricity markets, and competitive substitution from pea and rice proteins — sit outside the modeled envelope. Forecasts reflect assumptions on clean-label certification threshold evolution and carbon accounting standard harmonization across EU and North American jurisdictions. Recalibration cycles align with material shifts in EU Green Deal implementation, precision kilning technology adoption rates, and plant-based beverage formulation specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Africa Peas Market
Seeds
Agricultural Seeder Market
Seeds
Buckwheat Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Okra Seed Market
Seeds
Organic Sesame Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Flax Crop Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Quinoa Seed Market
Seeds
Russia Forage Seed Market
Seeds
Indonesia Seeds Market