
 Electroplating Chemicals Market | 2026-2036
Electroplating Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Electroplating Chemicals Market Analytics
Modular additive bundles is pivoting buyer choice in electroplating chemicals, as formulators unbundle pretreatment, plating, and post-treatment chemistries to let end-users customize line configurations. BASF SE leverages its global pigment and precursor infrastructure to sustain captive supply of nickel salts across European automotive plating lines. DuPont anchors its position through fluoropolymer-based chromium-free sealant technologies that compete with traditional hexavalent systems. Uyemura International Corporation specializes in high-phosphorus electroless nickel formulations that dominate semiconductor tooling applications in East Asian electronics clusters.
Electroplating chemicals encompass the aqueous and organic formulations—acid salts, brighteners, levelers, wetting agents, and post-treatment sealants—used to deposit metallic coatings onto conductive substrates via electrolytic reduction, typically operating at current densities between 2 and 50 A/dm² depending on the target metal and substrate geometry. These chemistries serve primarily to enhance corrosion resistance, electrical conductivity, wear properties, and aesthetic finish across industrial and consumer goods. Alkaline zinc formulations occupy mature, high-volume positions in automotive fastener and hardware plating, where cost sensitivity limits margin expansion. Nickel chemistries, particularly sulfamate and electroless variants, represent the fastest-growing product category as aerospace turbine blade repair and EV battery interconnect specifications tighten deposit uniformity requirements. Barrel plating technology leads job-shop throughput for small-part jewelry and electronics connector volumes, while ion plating commands premium positioning in medical device and precision optical coatings where porosity thresholds fall below 0.1 percent.
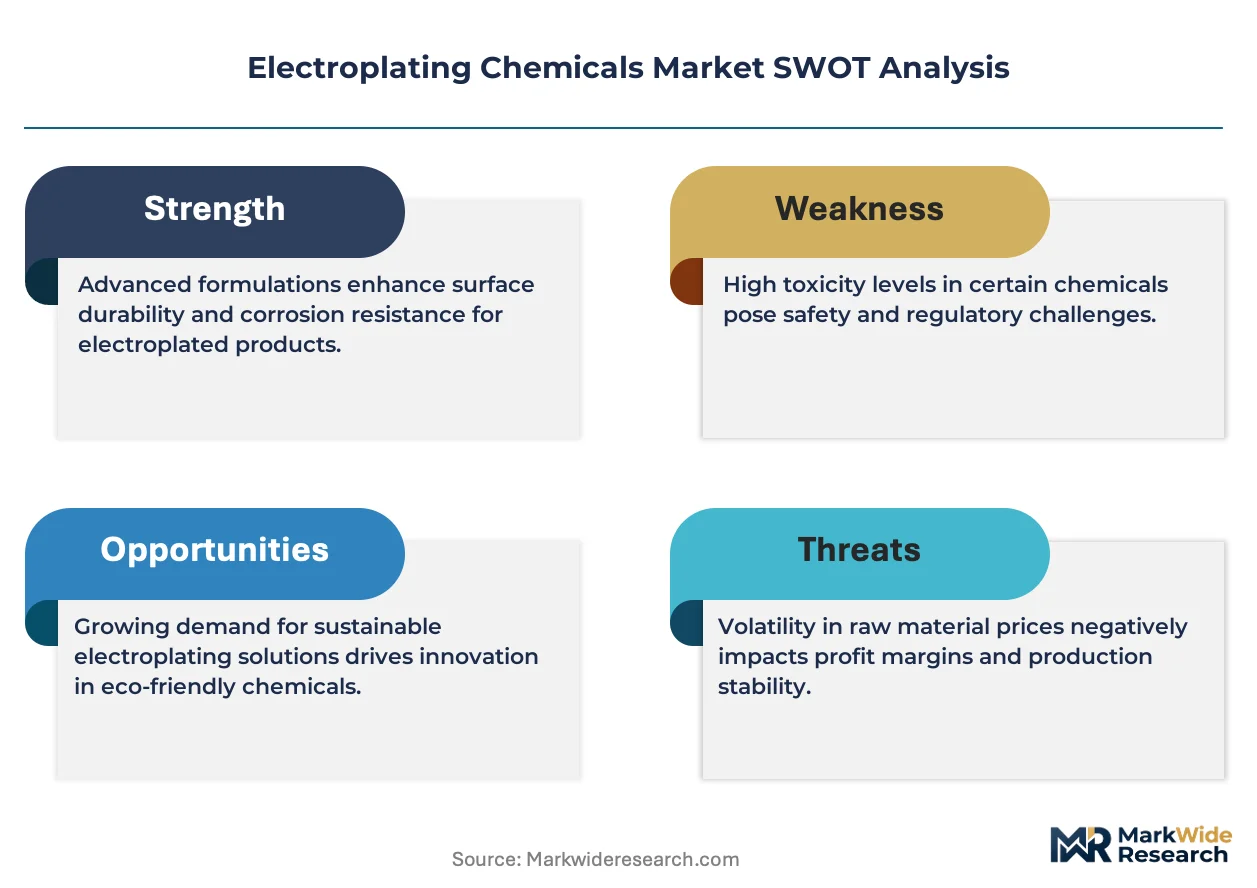
EPA effluent guidelines under the Clean Water Act limit heavy metal discharge from plating operations, compelling U.S. facilities to install closed-loop rinse recovery and substitute cyanide-based copper baths with alkaline non-cyanide alternatives. REACH annex XVII restrictions on chromium VI compounds and the EU Green Deal industrial emissions framework are restructuring European supplier portfolios toward trivalent passivation and electroless nickel-phosphorus systems. China's MEE standards for electroplating wastewater discharge in the Yangtze River Economic Belt are forcing consolidation among small Dongguan job-shops and redirecting procurement toward certified chemical distributors with environmental compliance documentation. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and align R&D pipelines with the trajectory of substance restrictions.
Market Dynamics
Formulation substitution pressure from REACH chromium VI restrictions is compressing supplier portfolios toward trivalent and electroless alternatives, restructuring competitive positioning across European automotive and electronics plating lines.
Growth Catalysts
- EV battery interconnect specifications:Nickel sulfamate chemistries face tightening uniformity requirements for copper busbar and connector plating as automotive OEMs scale electric powertrain manufacturing.
- China MEE wastewater standards:Consolidation among Dongguan job-shops redirects procurement toward certified chemical distributors with environmental compliance documentation.
- Semiconductor tooling demand:High-phosphorus electroless nickel dominates East Asian electronics clusters for wafer handling equipment requiring porosity thresholds below 0.1 percent.
Market Restraints
- Input cost volatility:Nickel salt prices fluctuate with London Metal Exchange spot markets, squeezing margin stability for formulators without captive precursor supply.
- Supply concentration risk:Specialty brightener and leveler production clusters in Germany and Japan create single-source dependencies for high-performance decorative plating lines.
- Technical limitation:Trivalent chromium systems still fail to match hexavalent salt spray performance in certain aerospace fastener specifications, delaying full substitution.
Strategic Opportunities
- Underpenetrated application:Medical device ion plating for implantable components offers premium positioning where porosity thresholds drive specification lock-in.
- Regulatory tailwind:EPA Clean Water Act effluent guidelines accelerate closed-loop rinse recovery system adoption, creating aftermarket chemical service contracts.
- Technology convergence:Integration of real-time bath analysis with automated additive dosing is compressing labor intensity in high-volume barrel plating operations.
Industry Challenges
- Skill gap in process engineering:Electroless nickel bath stability management requires specialized analytical chemistry expertise that job-shops struggle to recruit.
- Capex intensity for compliance:Closed-loop wastewater treatment and zero-liquid-discharge systems demand capital outlays that fragment the supplier base toward integrated chemical-service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroplating Chemicals Market |
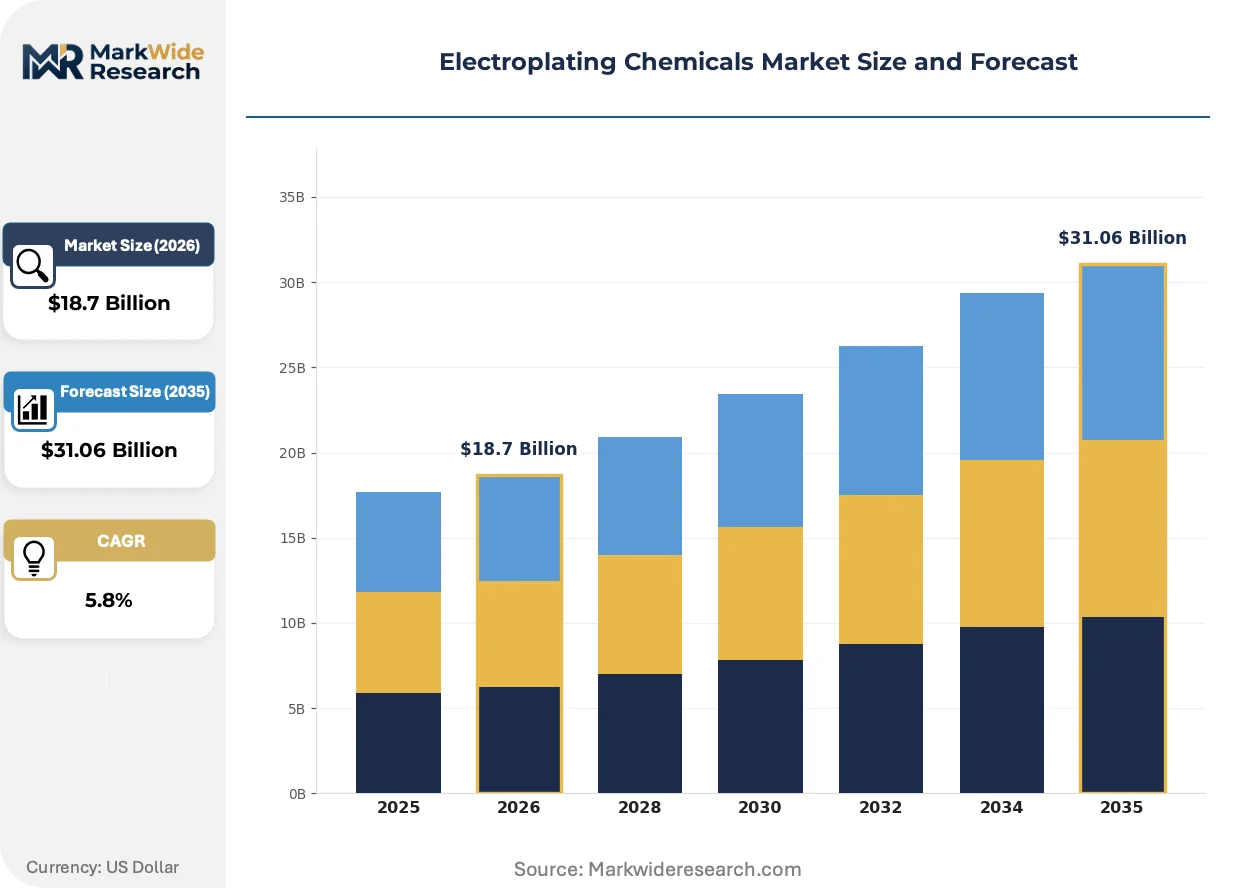
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Zinc, Nickel, Copper, Gold Application: Aerospace, Automotive Parts, Electronics, Jewelry Technology: Electroless Plating, Anodic Plating, Ion Plating, Barrel Plating End User: Manufacturers, OEMs, Contractors, Retailers |
| Companies Covered | DuPont, PAVCO, Inc., Atotech, BASF SE, Uyemura International Corporation, Technic Inc., MacDermid Enthone Industrial Solutions, METALOR Technologies SA, JCU Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroplating Chemicals Market Evolving Landscape
Active substitution of legacy hexavalent systems is reshaping formulation R&D priorities, with electrochemical process control and modular chemical bundles emerging as parallel vectors of competitive differentiation.
Pulse-reverse rectification technology is electrifying deposit uniformity control in high-aspect-ratio PCB through-hole plating. Electronics manufacturers in Shenzhen and Dongguan clusters are retrofitting rack lines with programmable power supplies. This hardware shift is compressing demand for traditional brightener-heavy formulations while elevating bath analysis and additive dosing precision.
REACH annex XVII chromium VI restrictions are forcing European suppliers to restructure product portfolios around trivalent passivation and electroless nickel-phosphorus systems. Automotive OEMs in Germany and France now specify trivalent-only decorative finishes for exterior trim. Plating job-shops are responding by dual-sourcing qualified chemistries to avoid formulation strandedness during substance restriction phase-ins.
Modular unbundling of pretreatment, plating, and post-treatment chemistries is letting end-users customize line configurations rather than buying bundled proprietary systems. Large automotive tier-1 suppliers in the US Midwest are selecting best-in-class components from multiple formulators. This purchasing behavior is most visible in high-volume zinc and nickel operations where line flexibility outweighs single-source technical support convenience.
Electroplating Chemicals Market Segmentation
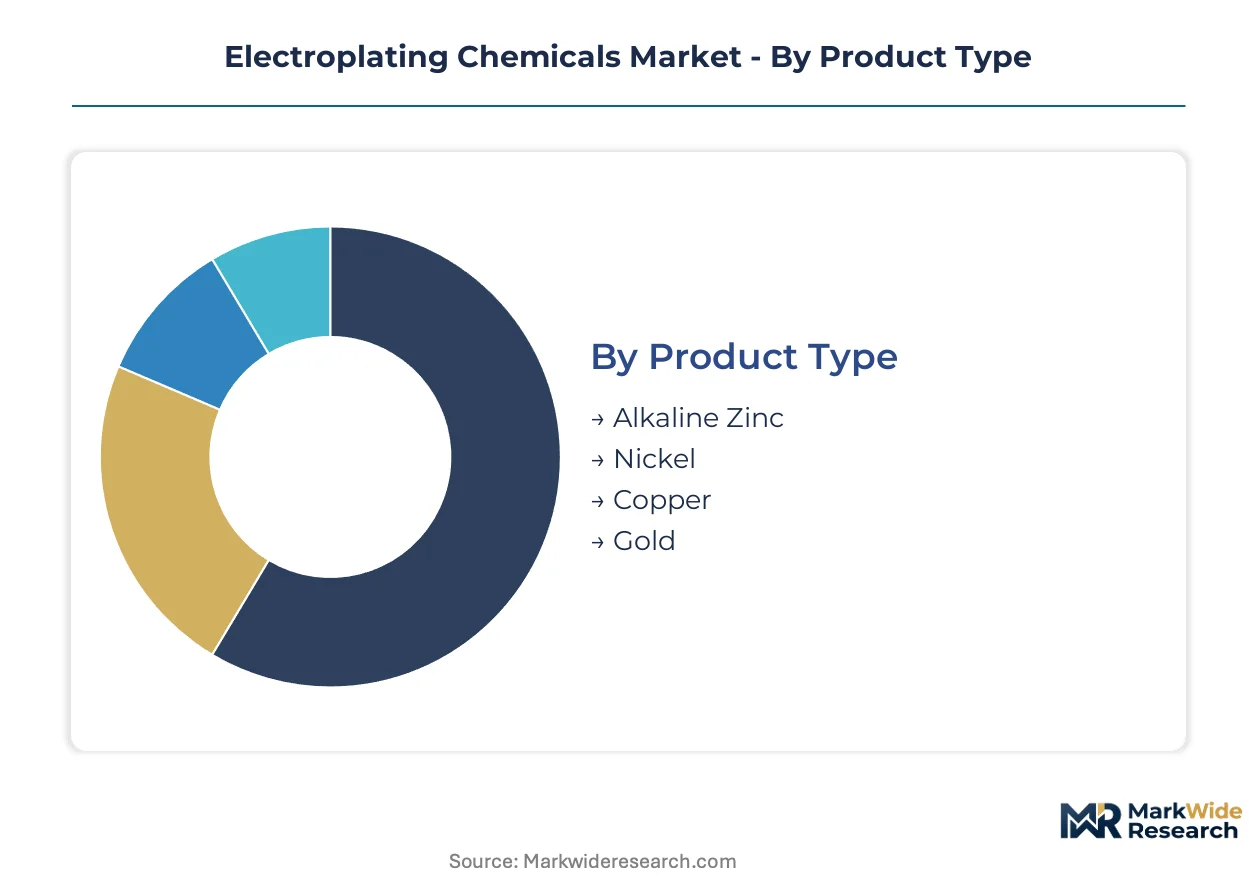
Electroplating chemical procurement patterns diverge sharply across product chemistries and end-use specifications, with aerospace turbine blade repair demanding sulfamate nickel uniformity that automotive fastener plating rarely requires. Technology selection further fragments the supplier landscape, as barrel plating job-shops in China's electronics clusters source entirely different additive bundles than medical device ion plating specialists.
Product Type:
Cost sensitivity and performance tier separate buyers in this category, with commodity hardware plating tolerating alkaline zinc price volatility while EV battery interconnect specifications tighten nickel deposit tolerances.
- Alkaline Zinc:Cost-driven formulations dominate automotive fastener and hardware plating where margin pressure limits additive sophistication. Demand concentrates in China's Yangtze River manufacturing belt, where Dongguan job-shops face MEE wastewater compliance costs that squeeze already thin plating margins.
- Nickel:Sulfamate and electroless variants command premium positioning as aerospace OEMs specify deposit uniformity for turbine blade repair and automotive EV programs tighten copper busbar plating tolerances. Germany's automotive tier-1 suppliers now dual-source qualified nickel chemistries to avoid stranded inventory during REACH substance restriction phase-ins.
- Copper:Acid and alkaline non-cyanide baths serve PCB through-hole plating in Shenzhen electronics clusters, with pulse-reverse rectification hardware retrofits compressing traditional brightener demand.
- Gold:High-purity formulations for semiconductor probe cards and connector plating in East Asian electronics manufacturing, where porosity thresholds below 0.1 percent justify chemistry premiums.
Alkaline zinc leads volumes today; nickel formulations are gaining share fastest.
Application:
Specification stringency and certification burden fragment demand, with medical device ion plating requiring lot traceability that jewelry barrel plating rarely demands.
- Aerospace:Sulfamate nickel deposits for turbine blade repair and fastener plating operate under Nadcap accreditation requirements that limit qualified chemical suppliers. France's Safran and Germany's MTU Aero Engines specify deposit thickness uniformity within 5 percent tolerance, driving bath analysis automation.
- Automotive Parts:Exterior trim specifications now mandate trivalent chromium-only finishes across German and French OEM programs, forcing formulation substitution away from hexavalent systems. EV battery interconnect copper busbar plating tightens current density control as powertrain manufacturing scales.
- Electronics:PCB through-hole and connector plating in Shenzhen and Dongguan clusters drives barrel and rack line chemical procurement, with pulse-reverse rectification retrofits elevating additive dosing precision requirements.
- Jewelry:Decorative gold and rhodium plating for small-part volumes favors low-cost barrel line configurations where brightener-heavy formulations mask substrate imperfections.
Automotive parts command the largest revenue pool; aerospace specifications are climbing the fastest.
Technology:
Capital intensity and labor substitution separate adoption patterns, with automated electroless systems requiring analytical chemistry expertise that barrel plating job-shops struggle to recruit.
- Electroless Plating:Autocatalytic nickel-phosphorus deposition achieves uniform coating on complex geometries without external current, dominating semiconductor wafer handling equipment in Taiwan and South Korea where porosity thresholds fall below 0.1 percent. Bath stability management requires specialized analytical chemistry expertise that fragments the supplier base toward integrated chemical-service providers.
- Anodic Plating:Aluminum oxide formation for wear resistance and dielectric properties serves aerospace and automotive component specifications, with sulfuric and chromic acid variants selected by hardness requirements.
- Ion Plating:Vacuum-based physical vapor deposition commands premium medical device positioning for implantable components where specification lock-in limits supplier switching.
- Barrel Plating:Bulk small-part processing for jewelry and electronics connectors favors low-cost aqueous formulations, with real-time bath analysis and automated additive dosing compressing labor intensity in high-volume operations.
Barrel plating retains volume leadership; electroless systems are expanding most quickly.
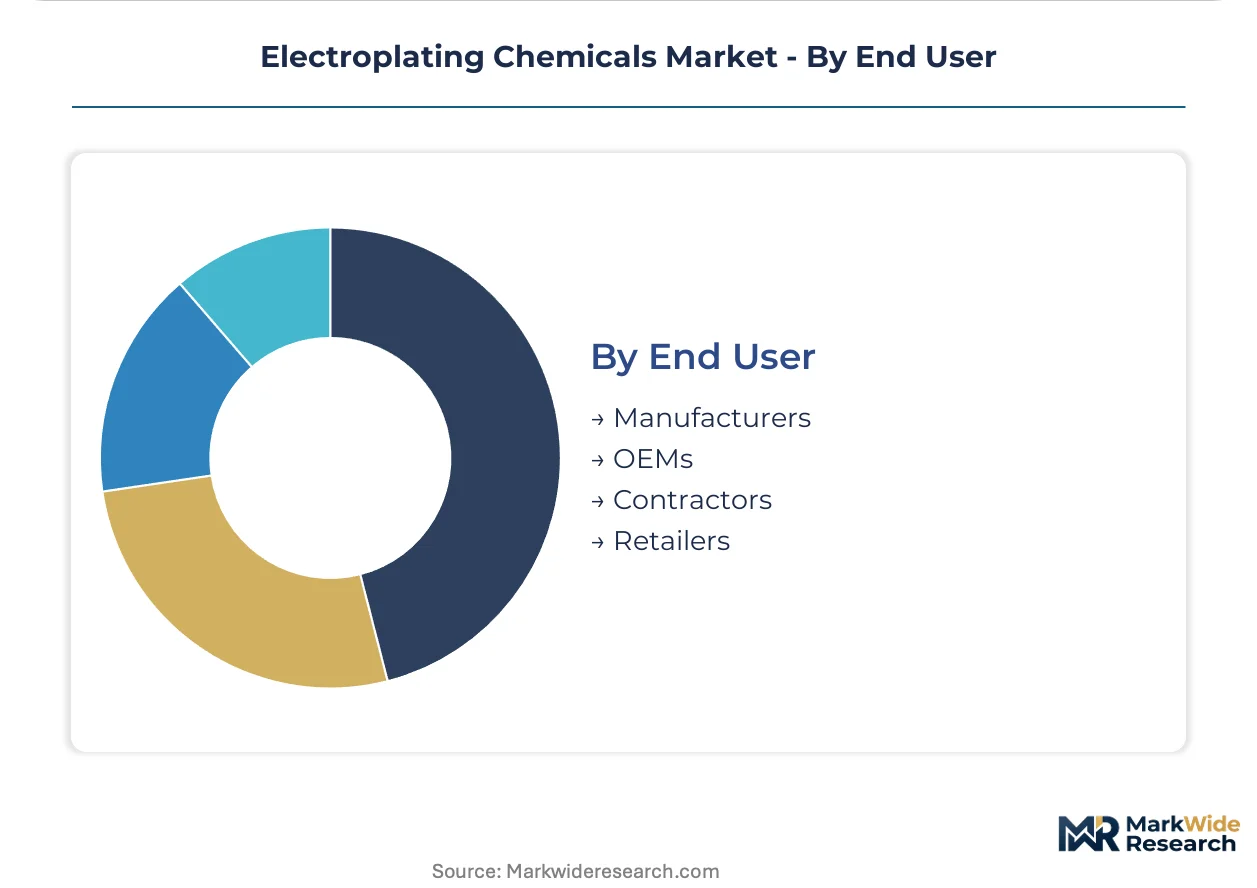
End User:
Technical integration depth and procurement sophistication divide this category, with OEMs specifying qualified chemistries while contractors optimize line flexibility.
- Manufacturers:In-house plating operations at automotive tier-1 suppliers in the US Midwest unbundle pretreatment, plating, and post-treatment chemistries to customize line configurations, selecting best-in-class components from multiple formulators rather than accepting bundled proprietary systems.
- OEMs:Automotive and aerospace original equipment manufacturers specify deposit tolerances and qualified chemical suppliers, with Germany's Volkswagen Group and France's Stellantis mandating trivalent-only decorative finishes for exterior trim programs.
- Contractors:Independent job-shops in China's Dongguan cluster face MEE wastewater discharge standards that force consolidation toward certified chemical distributors with environmental compliance documentation.
- Retailers:Jewelry and consumer goods distributors source finished plated products rather than chemicals directly, exerting indirect pressure on supply chain sustainability credentials.
Manufacturers dominate current procurement volumes; OEM specification authority is rising fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electroplating chemistry originated in European metallurgical traditions before scaling through German automotive plating lines and later migrating to East Asian electronics manufacturing clusters. Today, formulation demand distributes across automotive specification centers, semiconductor tooling hubs, and job-shop consolidation zones where environmental compliance has become the primary site-selection filter.
United States
Automotive tier-1 suppliers in Michigan and Ohio unbundle chemical procurement across pretreatment, plating, and post-treatment stages. EPA effluent guidelines under the Clean Water Act compel closed-loop rinse recovery installations. The US Midwest plating corridor is retrofitting barrel lines with automated additive dosing to compress labor intensity.
Germany
Volkswagen Group and Stellantis mandate trivalent-only decorative finishes for exterior trim programs. REACH annex XVII chromium VI restrictions force dual-sourcing strategies among qualified chemical suppliers. Bavarian automotive plating lines are restructuring supplier portfolios toward electroless nickel-phosphorus systems.
China
Shenzhen and Dongguan electronics clusters drive barrel and rack line chemical procurement for PCB through-hole plating. MEE wastewater discharge standards in the Yangtze River Economic Belt consolidate small job-shops toward certified distributors. Pulse-reverse rectification retrofits are elevating bath analysis precision requirements.
Japan
Semiconductor wafer handling equipment manufacturers specify high-phosphorus electroless nickel with porosity thresholds below 0.1 percent. METI industrial emissions frameworks align with broader East Asian environmental compliance trajectories. Kyushu electronics tooling clusters source specialized formulations from integrated chemical-service providers.
South Korea
Memory and logic chip fabrication drives demand for ultra-high-purity gold chemistries in probe card and connector applications. MFDS medical device regulations create specification lock-in for implantable component plating. The Seoul Capital Area concentration of semiconductor OEMs concentrates procurement among qualified chemistry distributors.
Electroplating Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification burden. The supplier base organizes into three tiers: integrated multinationals with captive precursor supply, specialized electroless chemistry houses with analytical service bundles, and regional job-shop distributors competing on logistics coverage. Competitive moves center on portfolio restructuring toward trivalent and electroless alternatives, plus backward integration into nickel salt production to offset London Metal Exchange volatility.
Within the integrated multinational tier, BASF SE and DuPont exemplify archetypes of upstream-controlled supply chains and fluoropolymer-based sealant positioning respectively. Uyemura International Corporation occupies a specialist position in high-phosphorus electroless formulations. These three anchors represent divergent strategic postures: European chemical conglomerate scale, American materials science diversification, and Japanese precision plating specialization.
| Leading Market Players |
|---|
| DuPont |
| PAVCO, Inc. |
| Atotech |
| BASF SE |
| Uyemura International Corporation |
| Technic Inc. |
| MacDermid Enthone Industrial Solutions |
| METALOR Technologies SA |
| JCU Corporation |
| Others |
Value Network & Pricing Analysis
REACH annex XVII chromium VI restrictions are forcing European automotive OEMs to dual-source qualified trivalent and electroless nickel chemistries, compelling suppliers to restructure production lines and compressing margins on legacy hexavalent formulations. This specification-driven procurement shift concentrates purchasing power among certified distributors with environmental compliance documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified sulfamate nickel from commodity alkaline zinc. Price differentiation centers on Nadcap certification tier and captive nickel salt supply. Cost compression in standard-grade barrel plating chemicals is intensifying because Dongguan job-shop consolidation redirects volume toward certified distributors. Contract manufacturers exhibit highest price sensitivity; semiconductor OEMs tolerate premiums for sub-0.1 percent porosity specifications.
Supply Chain Analysis
REACH and EU Green Deal qualification requirements gate supplier access to Volkswagen Group and Stellantis plating programs. Nickel salt production concentrates in Germany, Japan, and China; specialty brightener synthesis rests on German and Japanese chemical houses. Single-source vulnerability runs through high-phosphorus electroless nickel additive bundles. Distribution runs through integrated chemical-service providers with analytical laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Water Act effluent guidelines and REACH substance restrictions continuously requalify supplier rosters and redirect procurement toward compliant formulations.
For Market Incumbents: Cement position by securing captive nickel salt supply through backward integration into precursor production, insulating margin stability from London Metal Exchange volatility. Expand analytical service bundles for electroless nickel bath stability management to capture job-shops lacking in-house chemistry expertise. Defend against modular unbundling trends by locking automotive tier-1 suppliers into multi-year technical service contracts.
For New Entrants and Emerging Players: Medical device ion plating specialists represent an underserved buyer archetype where specification lock-in limits incumbent switching and justifies premium positioning. Target semiconductor wafer handling equipment manufacturers in Taiwan and South Korea with high-phosphorus electroless nickel formulations. Enter through integrated chemical-service partnerships offering bath analysis automation alongside chemistry supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with electroless nickel chemistry houses possessing analytical service capabilities and Nadcap-qualified production facilities. Long-term viability favors suppliers with demonstrated regulatory navigation across multiple jurisdictions. Monitor REACH substance restriction phase-in timelines as the inflection indicator for portfolio restructuring velocity and stranded formulation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Salt Production | BASF SE leverages captive precursor supply to stabilize margins against London Metal Exchange volatility. |
| Green Manufacturing Transition | DuPont fluoropolymer-based chromium-free sealants capture automotive OEMs exiting hexavalent systems. |
| Long-term Supply Agreement | Uyemura International Corporation locks semiconductor tooling manufacturers into high-phosphorus electroless nickel contracts. |
| Joint Venture | Regional distributors partner with German brightener specialists to bypass single-source dependencies in decorative plating. |
| Capacity Expansion | Certified chemical distributors add analytical laboratory capacity to serve consolidated Dongguan job-shops under MEE standards. |
Research Methodology
Bottom-up automotive and electronics plating line modeling reconciled against top-down nickel salt and brightener production tracking forms the analytical core of this study. Primary interviews with plating plant managers, automotive tier-1 procurement leads, chemical distribution channel partners, and electroless nickel R&D directors combined with secondary validation from EPA effluent filings, REACH substance restriction databases, SEC 10-K chemical segment disclosures, and Yangtze River Economic Belt environmental compliance records. Triangulation across these sources produced volume and value estimates.
Input-output matrices mapped electroplating chemical consumption by grade tier, end-use industry, technology type, and regional production hub across the projection horizon. CAGRs derived from segmented growth rate analysis incorporating EV battery interconnect specification tightening, semiconductor tooling demand trajectories, and regulatory substitution timelines. Forecast inputs included London Metal Exchange nickel price scenarios and REACH substance restriction phase-in schedules.
Inputs from EPA, ECHA, and China MEE regulatory filings were available through the study window; gaps in real-time job-shop consolidation rates in Dongguan introduce uncertainty bands around contractor segment forecasts. Model refresh is warranted upon material change in REACH annex XVII chromium VI restriction enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
1-Methylimidazole Market
Chemicals
Tromethamine Market
Chemicals
Coal Tar Market
Chemicals
Welding Chemicals Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Heptaldehyde Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Ferric Chloride Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Calcium Methoxide Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Fluorene Market
Chemicals
Potassium Iodide Market
Chemicals
Benzoyl Alcohol Market