
 Silicone in Electric Vehicles Market | 2026-2036
Silicone in Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone in Electric Vehicles Market Intelligence
Aftermarket thermal management refurbishment is rewriting margin capture across the value chain as EV fleets age and battery warranty periods expire. Dow Inc. leverages its Midland-based polymer research campus to sustain fluorosilicone innovation for high-voltage connectors. Wacker Chemie AG anchors European supply through its Burghausen integrated silicone complex, while Shin-Etsu Chemical Co., Ltd. dominates Asian feedstock flows with captive quartz-to-silicone production.
Silicone in electric vehicles encompasses elastomeric and resinous organosilicon compounds formulated for dielectric strength above 15 kV/mm, thermal stability beyond 200°C, and compression set resistance under sustained loads. These materials seal battery enclosures, conduct heat away from power electronics, and electrically insulate high-voltage busbars across drivetrain architectures. Adhesives and sealants within the product type dimension carry the widest margin pools because they command specification-locked positions in battery pack designs. Thermal management within the application dimension grows fastest as 800-volt architectures multiply heat flux densities beyond legacy coolant capacities.
The EPA tailpipe emission standards and the EU F-Gas Regulation constrain volatile organic compound content and global warming potential in silicone curing agents, forcing reformulation investments that favor suppliers with in-house catalyst development. China's MIIT new-energy-vehicle catalog ties subsidy eligibility to battery thermal runaway containment standards that specify silicone fire-barrier performance. OEMs and Tier-1 Suppliers within the end user dimension must now decide whether to qualify second-source silicone formulations before next-generation platform gates close.
Market Dynamics
The transition to 800-volt electrical architectures is compressing thermal management tolerances and forcing silicone suppliers to reformulate for higher dielectric stress and continuous operating temperatures above 200°C.
Growth Catalysts
- China's NEV mandate:MIIT catalog requirements for battery thermal runaway containment specify silicone fire-barrier performance, pulling formulation demand from domestic OEMs and joint ventures.
- Cell energy density escalation:Lithium-ion pack designs above 300 Wh/kg require advanced thermal interface materials to manage heat flux densities that legacy gap-fillers cannot absorb.
- Germany's automotive supplier corridor:Concentrated R&D spending around Stuttgart and Munich accelerates qualification cycles for fluorosilicone compounds in high-voltage connectors.
Market Restraints
- Quartz feedstock concentration:Captive mining-to-silicone production in East Asia creates supply vulnerability for European and North American compounders without backward integration into raw material streams.
- F-Gas Regulation compliance costs:The EU's phasedown of high-global-warming-potential blowing agents forces reformulation of silicone foams and sealants with alternative catalyst systems that extend development timelines.
- Polyimide substitution in power electronics:Thin-film insulation materials compete for slot liner applications in motor windings where silicone elastomers previously dominated.
Strategic Opportunities
- Aftermarket thermal refurbishment:Expiring battery warranties across aging EV fleets create service-channel demand for replacement thermal interface pads and resealing compounds.
- Solid-state battery packaging:Next-generation cell architectures with sulfide or oxide electrolytes require hermetic sealing solutions that silicone elastomers can provide at module and pack levels.
- US Inflation Reduction Act content credits:Domestic content requirements for battery components incentivize North American silicone compounding capacity expansion to serve qualifying OEM supply chains.
Industry Challenges
- Electrochemical compatibility testing:Extended validation protocols for silicone compatibility with new electrolyte chemistries delay qualification gates and compress product launch windows.
- High-voltage safety certification:IEC 60664-1 clearance and creepage requirements for 800-volt systems demand redesigned material geometries that existing production tooling cannot achieve without capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone in Electric Vehicles Market |
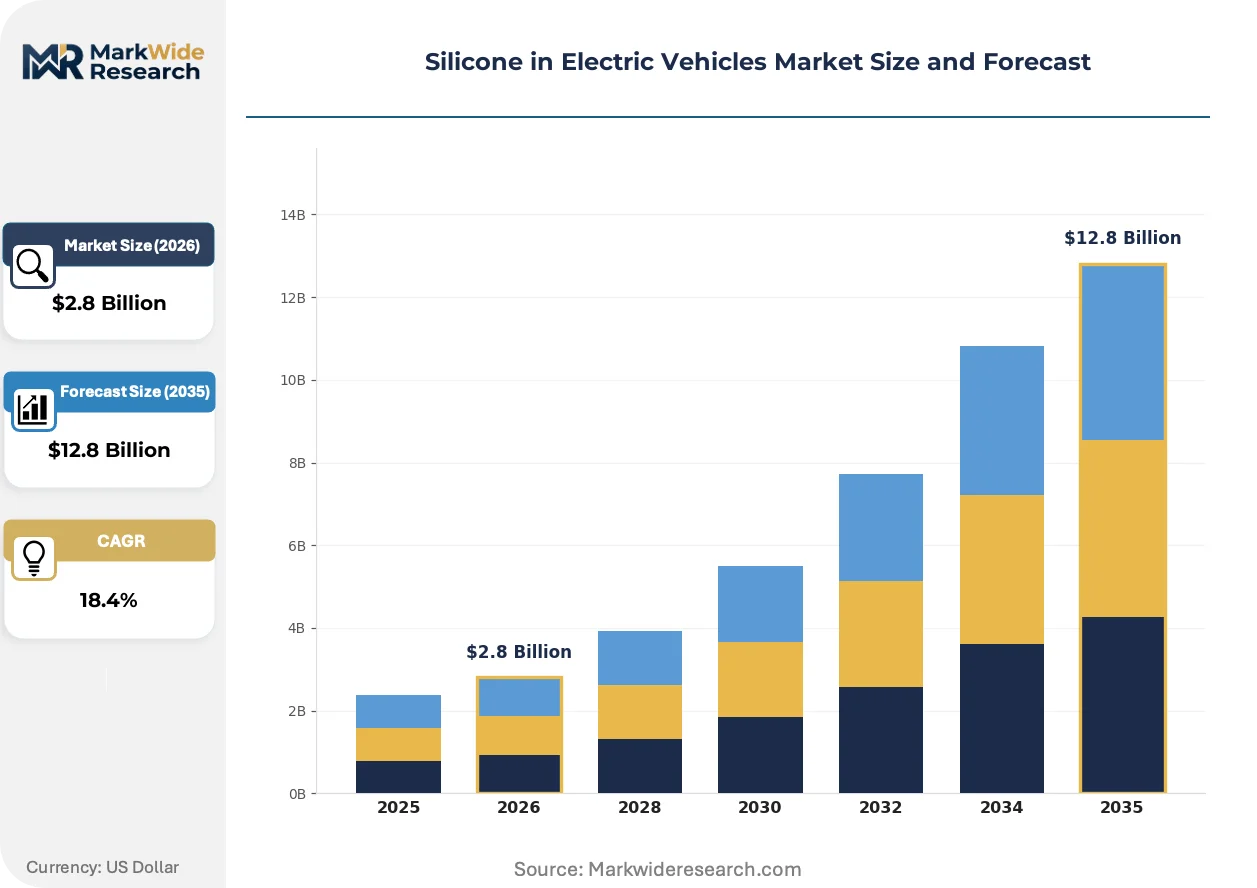
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealants, Gaskets, Coatings, Adhesives Application: Batteries, Thermal Management, Connectors, Insulation End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Extrusion, Compression Molding, 3D Printing |
| Companies Covered | Momentive Performance Materials Inc., Evonik Industries AG, Dow Inc., H.B. Fuller Company, Henkel AG & Co. KGaA, Wacker Chemie AG, Elkem Silicones, Rogers Corporation, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone in Electric Vehicles Market Strategic Shifts & Innovations
Formulation chemistry and procurement architecture are evolving in parallel as voltage platforms advance and regulatory jurisdictions tighten environmental performance standards for automotive materials.
Thermally conductive gap fillers with boron nitride loading are collapsing the performance gap between legacy silicone greases and phase-change materials in power module applications. Tier-1 suppliers in Germany and Japan are adopting these compounds for inverter housings where thermal cycling resistance exceeds 10,000 cycles. The shift is collapsing qualification timelines for second-source materials as OEM platform gates lock.
The EU F-Gas Regulation's hydrofluorocarbon phasedown is forcing silicone foam producers to switch from HFC-245fa to hydrocarbon or water-blown expansion systems. Industrial consequence includes reformulated density grades and retested fire-performance ratings for battery pack seals. German OEMs are responding by pre-qualifying multiple foam suppliers to avoid single-source dependency during the transition window.
Cell manufacturers are consolidating procurement of thermal management materials under long-term framework agreements that bundle adhesives, gap fillers, and encapsulants under single-supplier contracts. The practice displaces spot purchasing for individual chemistries and compresses margin pools for specialty compounders without full-stack capability. China-based battery producers are most aggressive in this consolidation, locking in three-year supply commitments ahead of capacity ramp-ups.
Silicone in Electric Vehicles Market Segmentation
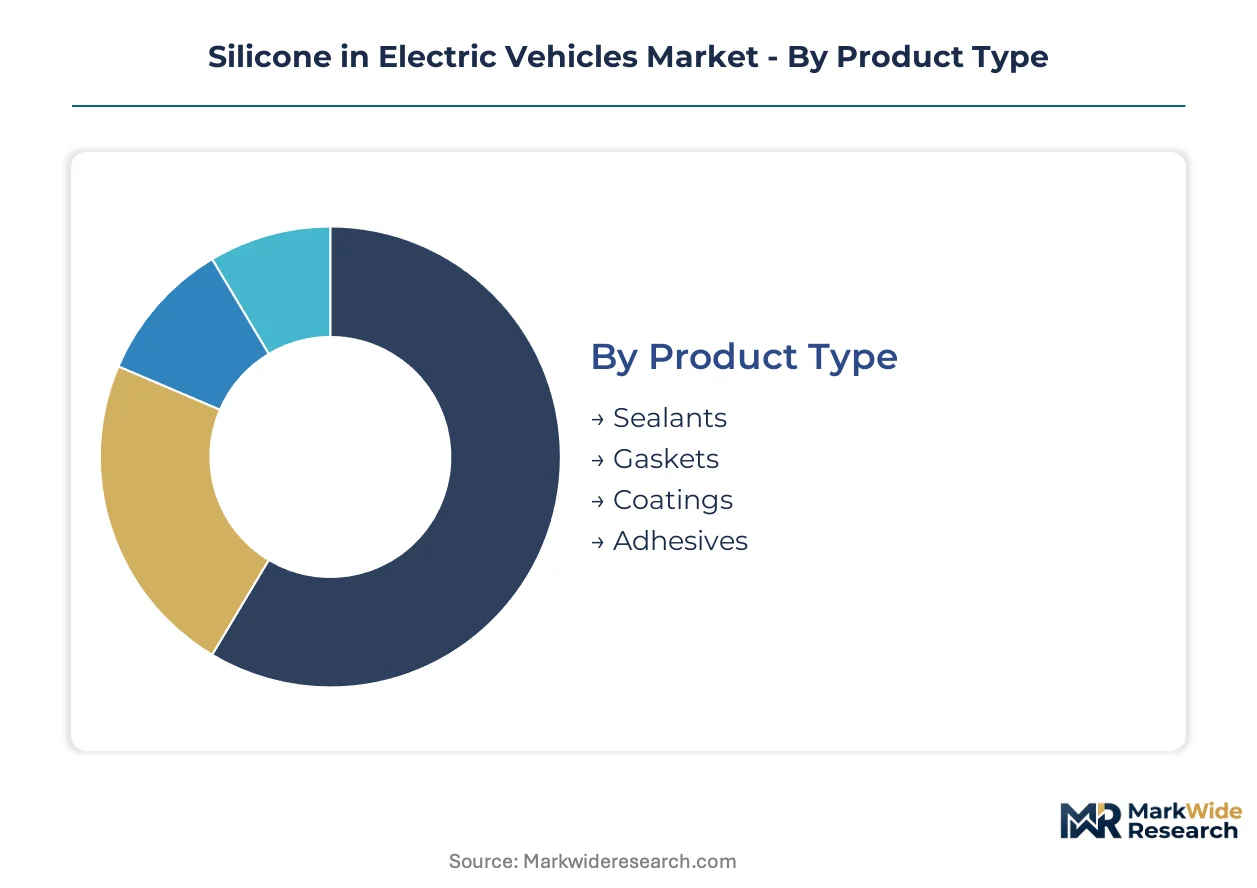
Silicone procurement in electric vehicles fragments across four distinct dimensions that determine formulation specifications, qualification timelines, and margin capture. Product chemistry, thermal application requirements, customer integration depth, and manufacturing process constraints each create separate competitive battlegrounds for suppliers.
Product Type:
Cost tier stratification separates specification-locked formulations from commodity alternatives, with premium grades commanding locked-in design positions.
- Sealants:Elastomeric compounds formulated for compression set resistance below 15% after 1,000 hours at 150°C absorb the largest procurement budgets from battery pack OEMs. Cell enclosure sealing against IP67 ingress standards requires platinum-cured formulations that Dow Inc. and Wacker Chemie AG dominate in Germany's automotive corridor.
- Adhesives:Structural bonding systems with dielectric strength exceeding 15 kV/mm now displace mechanical fasteners in module-to-pack assembly. China's CATL and BYD specify these chemistries for thermal runaway containment under MIIT catalog requirements, locking in three-year framework agreements with qualified suppliers.
- Gaskets:Cellular silicone profiles with closed-cell density below 200 kg/m³ seal inverter housings and cooling plates.
- Coatings:Conformal films with fluorosilicone chemistry protect high-voltage busbars from moisture-induced tracking.
Sealants hold installed capacity. Adhesives are rotating up the share rankings.
Application:
Volume concentration tracks heat flux density escalation as 800-volt architectures multiply thermal management material intensity per vehicle.
- Thermal Management:Boron nitride-loaded gap fillers with thermal conductivity above 3 W/m·K conduct heat from power modules to cooling channels. German Tier-1 suppliers around Stuttgart adopt these compounds for inverter housings where thermal cycling resistance must exceed 10,000 cycles.
- Batteries:Fire-barrier silicone foams with UL 94 V-0 ratings contain thermal runaway propagation between cells. China's NEV mandate specifies these materials for subsidy eligibility, pulling formulation demand from domestic OEMs and joint ventures operating under MIIT catalog requirements.
- Connectors:Self-fusing silicone tapes insulate high-voltage junctions against creepage in 800-volt systems.
- Insulation:Extruded silicone sleeving protects motor windings and busbars from abrasion and voltage stress.
Batteries hold installed capacity. Thermal Management is rotating up the share rankings.
End User:
Customer type determines specification authority, with direct OEM relationships offering locked-in positions versus fragmented aftermarket channels.
- OEMs:Vehicle manufacturers with in-house battery pack design teams specify silicone chemistries at platform conception, creating three to five year qualification locks. Volkswagen Group and BMW AG in Germany pre-qualify multiple foam suppliers to avoid single-source dependency during F-Gas Regulation transitions.
- Tier-1 Suppliers:Bosch GmbH and Continental AG integrate silicone components into subsystems they deliver to multiple OEMs, spreading R&D costs across platform volumes.
- Vehicle Assemblers:Contract manufacturers without design authority procure specified materials under direction from brand-owning OEMs.
- Aftermarket Providers:Independent service channels source replacement thermal interface pads and resealing compounds as battery warranties expire across aging EV fleets.
OEMs hold installed capacity. Aftermarket Providers are rotating up the share rankings.
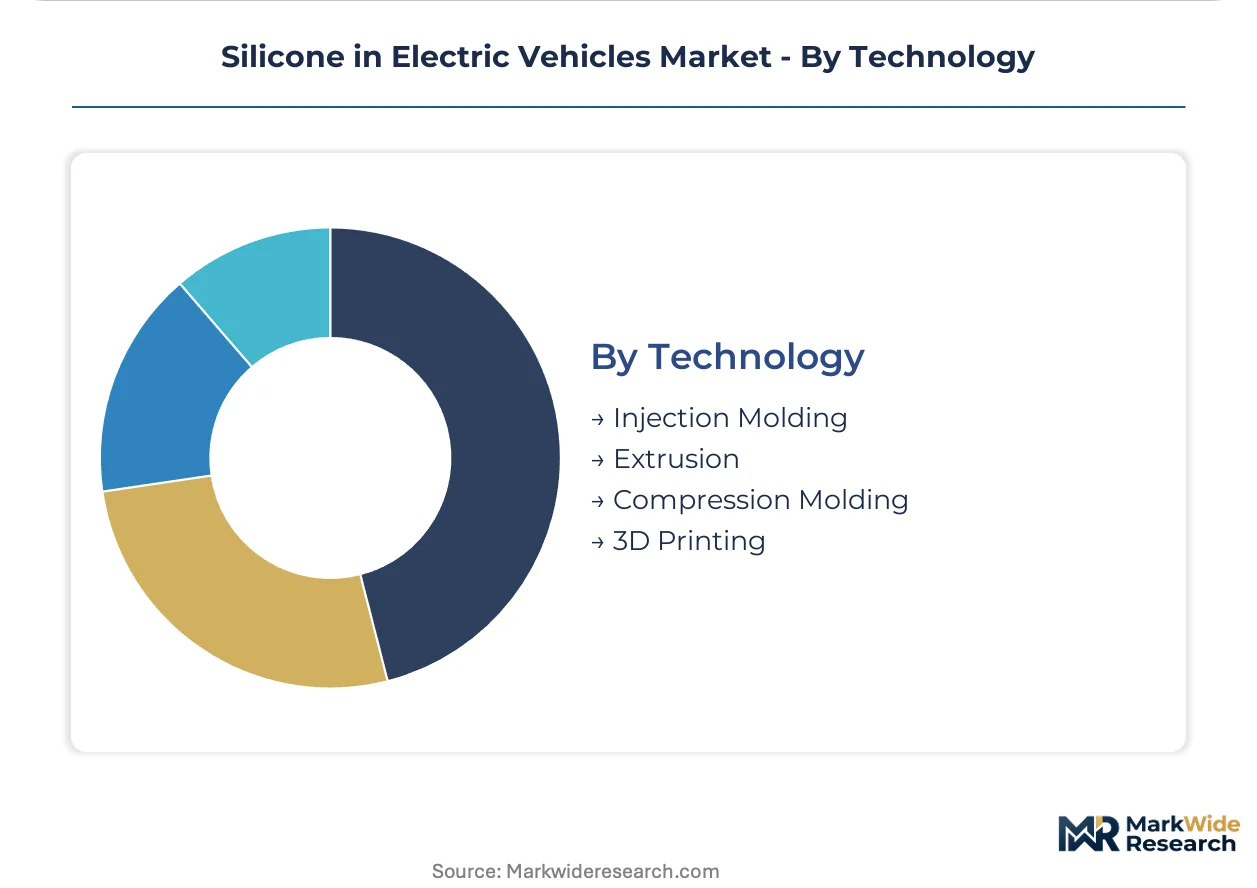
Technology:
Manufacturing maturity separates high-volume processes from emerging methods still seeking automotive qualification cycles.
- Injection Molding:Liquid silicone rubber processing with cycle times below 60 seconds produces complex seals for battery enclosures. Wacker Chemie AG's Burghausen complex supplies European compounders with LSR base polymers qualified for automotive production.
- Extrusion:Continuous profile manufacturing delivers gasket cords and tubing with tight dimensional tolerances for cooling system connections. This process dominates high-volume thermal management component supply.
- Compression Molding:Solid silicone rubber forming suits low-volume, high-performance parts where tooling cost amortization favors longer production runs.
- 3D Printing:Additive deposition of silicone resins enables rapid prototyping and low-volume customization for specialty vehicle applications.
Extrusion holds installed capacity. Injection Molding is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb premium formulations with minimal price elasticity while European procurement teams force reformulation cost-sharing onto suppliers under F-Gas compliance pressures.
China
CATL and BYD lock three-year framework agreements for battery adhesives under MIIT thermal runaway containment mandates. The MIIT new-energy-vehicle catalog ties subsidy eligibility to silicone fire-barrier specifications. Yangtze River Delta cell producers consolidate thermal material procurement under single-supplier contracts ahead of capacity ramp-ups.
Germany
Volkswagen Group and BMW AG pre-qualify multiple foam suppliers to circumvent single-source exposure during F-Gas blowing-agent transitions. The EU F-Gas Regulation forces retested fire-performance ratings for battery pack seals. Stuttgart and Munich automotive corridors accelerate fluorosilicone qualification cycles for 800-volt high-voltage connectors.
United States
Domestic OEMs exploit Inflation Reduction Act content credits to onshore silicone compounding capacity for qualifying battery supply chains. EPA tailpipe emission standards constrain volatile organic compound content in curing agents. Michigan and Ohio-based battery gigafactories specify platinum-cured sealants for IP67 cell enclosure standards.
Japan
Shin-Etsu Chemical's captive quartz-to-silicone production secures feedstock autonomy for Asian compounders serving Toyota and Nissan solid-state battery programs. METI carbon-neutrality roadmaps pressure reformulation toward low-global-warming-potential variants. Kyushu-based material suppliers qualify hermetic sealing solutions for sulfide electrolyte architectures.
South Korea
LG Energy Solution and Samsung SDI specify boron nitride-loaded gap fillers for inverter housings requiring 10,000-cycle thermal resistance. MFDS chemical safety protocols extend validation timelines for new electrolyte compatibility testing. Seoul Capital Area battery producers bundle adhesives, gap fillers, and encapsulants under consolidated procurement frameworks.
Silicone in Electric Vehicles Market Key Industry Players
Integrated petrochemical conglomerates and specialty silicone compounders split the market through divergent scale-versus-precision positioning. The supplier base organizes around three strategic archetypes: backward-integrated feedstock controllers, specification-locked formulation specialists, and full-stack thermal management bundlers. Dominant competitive moves include captive mining-to-silicone production investments and long-term framework contracting with cell manufacturers.
Within the integrated feedstock tier, Dow Inc. and Shin-Etsu Chemical Co., Ltd. exemplify archetypes of raw material security. Wacker Chemie AG anchors European supply architecture through its Burghausen integrated complex. These entities represent distinct geographic anchoring strategies—Midland-based polymer research, Asian captive quartz flows, and Bavarian compounding integration—each securing qualification locks with platform-level OEMs.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| Evonik Industries AG |
| Dow Inc. |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| Elkem Silicones |
| Rogers Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor's volatile container rates compress margins for silicone compounders serving European battery OEMs while amplifying price spreads between specification-locked formulations and commodity alternatives. This logistics pressure concentrates procurement leverage among buyers with multi-year framework agreements, forcing spot-market purchasers to absorb tariff-induced cost escalations or downgrade to lower-certification grades.
Pricing Analysis
Aftermarket thermal refurbishment service contracts now drive lifetime value capture as aging EV fleets exit warranty periods. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured sealants with IP67 certification from peroxide-cured alternatives and uncertified imports. Cost compression in standard-grade adhesives is intensifying because Chinese cell manufacturers bundle procurement under single-supplier contracts. Fleet operators and independent service channels exhibit highest price sensitivity, while OEM platform engineering teams prioritize qualification-locked premium grades regardless of unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates risk calculus for silicone compounders without captive quartz processing. Raw material flows draw from East Asian mining operations, German chemical processing corridors, and North American petrochemical feedstocks. Single-source vulnerability concentrates in platinum catalyst supply chains anchored to South African and Russian mining operations. Distribution runs through Tier 1 subsystem integrators who consolidate adhesives, gap fillers, and encapsulants under consolidated procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against polyimide thin-film insulation encroaching on motor winding applications where silicone elastomers previously held specification locks. Incumbents must navigate reformulation investments triggered by F-Gas Regulation phasedowns while preserving margin structures.
For Market Incumbents: Harden qualification positions through captive catalyst development capabilities that accelerate low-global-warming-potential formulation transitions ahead of regulatory deadlines. Deepen backward integration into quartz-to-silicone production streams to circumvent East Asian feedstock concentration. Polyimide substitution in power electronics slot liners threatens volume erosion in motor insulation segments.
For New Entrants and Emerging Players: Pursue aftermarket thermal refurbishment channels where specification authority fragments across independent service networks and price sensitivity exceeds OEM procurement thresholds. North American silicone compounding capacity serving Inflation Reduction Act-qualifying battery supply chains represents the most penetrable white space. Target qualification partnerships with solid-state battery developers seeking hermetic sealing solutions for sulfide electrolyte architectures.
For Investors and Strategic Acquirers: The EU F-Gas Regulation's hydrofluorocarbon phasedown reshapes the acquisition landscape by devaluing foam producers dependent on HFC-245fa expansion systems and elevating compounders with hydrocarbon-blown alternatives already validated. Long-term viability centers on suppliers with in-house catalyst platforms capable of servicing multiple OEM qualification cycles. Monitor German OEM pre-qualification announcements for second-source foam suppliers as inflection indicators for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Processing | Shin-Etsu Chemical's captive mining-to-silicone model secures feedstock autonomy against East Asian supply concentration. |
| Low-GWP Formulation Transition | EU F-Gas Regulation compliance forces retested fire-performance ratings for battery pack sealants. |
| Aftermarket Channel Development | Expiring battery warranties across aging EV fleets create service-channel demand for replacement thermal interface materials. |
| Long-Term Framework Contracting | CATL and BYD lock three-year supply commitments ahead of capacity ramp-ups. |
| Solid-State Battery Sealing Qualification | Hermetic sealing solutions for sulfide electrolyte architectures open module-level specification positions. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, silicone compounder technical directors, and aftermarket service channel operators and refined through secondary validation. Primary intelligence combined structured interviews with downstream specification authorities and upstream formulation specialists. Secondary sources encompassed MIIT catalog filings, EU F-Gas Regulation implementation documents, SEC 10-K disclosures from listed chemical producers, and customs trade flow data. Bottom-up volume builds triangulated against top-down OEM production forecasts.
Demand-supply-balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product chemistry grade, thermal application intensity, end-user integration depth, and manufacturing process maturity. CAGRs derived from fitted growth curves applied to battery pack content-per-vehicle trajectories and 800-volt architecture penetration schedules. Key inputs included cell energy density roadmaps, thermal runaway containment regulatory thresholds, and platinum catalyst price indices.
Sensitivities concentrate around F-Gas Regulation implementation pacing, solid-state battery commercialization timelines, and polyimide substitution rates in motor winding applications. Forecasts reflect documented assumptions regarding OEM platform gate schedules and qualification cycle durations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market