
 Mexico Electric Bus Market | 2026-2036
Mexico Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Electric Bus Market Insights
Public transport fleets are rebalancing toward battery-electric configurations as municipal operators phase out diesel units in Mexico City, Monterrey, and Guadalajara. BYD Co Ltd leverages its integrated battery-cell-to-chassis architecture to anchor procurement contracts with state-owned transit authorities. Daimler AG sustains engineering credibility through its modular eCitaro platform adapted for Latin American road grades and climate conditions. Volvo AB differentiates via predictive charging algorithms and depot-management software bundled with bus deliveries.
An electric bus integrates high-voltage battery packs, permanent-magnet synchronous motors, and regenerative braking systems to replace internal combustion propulsion in passenger transit duty cycles, typically operating at 300-800V DC with 150-500 kWh pack configurations. City Bus configurations dominate unit shipments due to predictable stop-and-go routes that maximize regenerative energy recovery, while Depot Charging infrastructure leads capital deployment because overnight plug-in cycles align with fleet parking patterns and minimize grid-peak strain. Lithium-ion battery technology occupies the near-term procurement landscape despite solid-state pilot interest, as cell cost curves and established recycling pathways preserve its economic advantage.
SEMARNAT enforces NOM-044 emissions benchmarks that tighten particulate limits for urban diesel fleets, while the Secretaría de Energía coordinates federal charging-station subsidies through FIDE successor programs. CRE grid-interconnection rules shape how depot operators size transformer capacity and negotiate demand-charge structures with CFE. Stakeholders must monitor state-level ZEB mandates beyond federal minimums, as Nuevo León and Jalisco draft accelerated electrification timelines that could reshape supplier qualification criteria and localize content requirements.
Market Dynamics
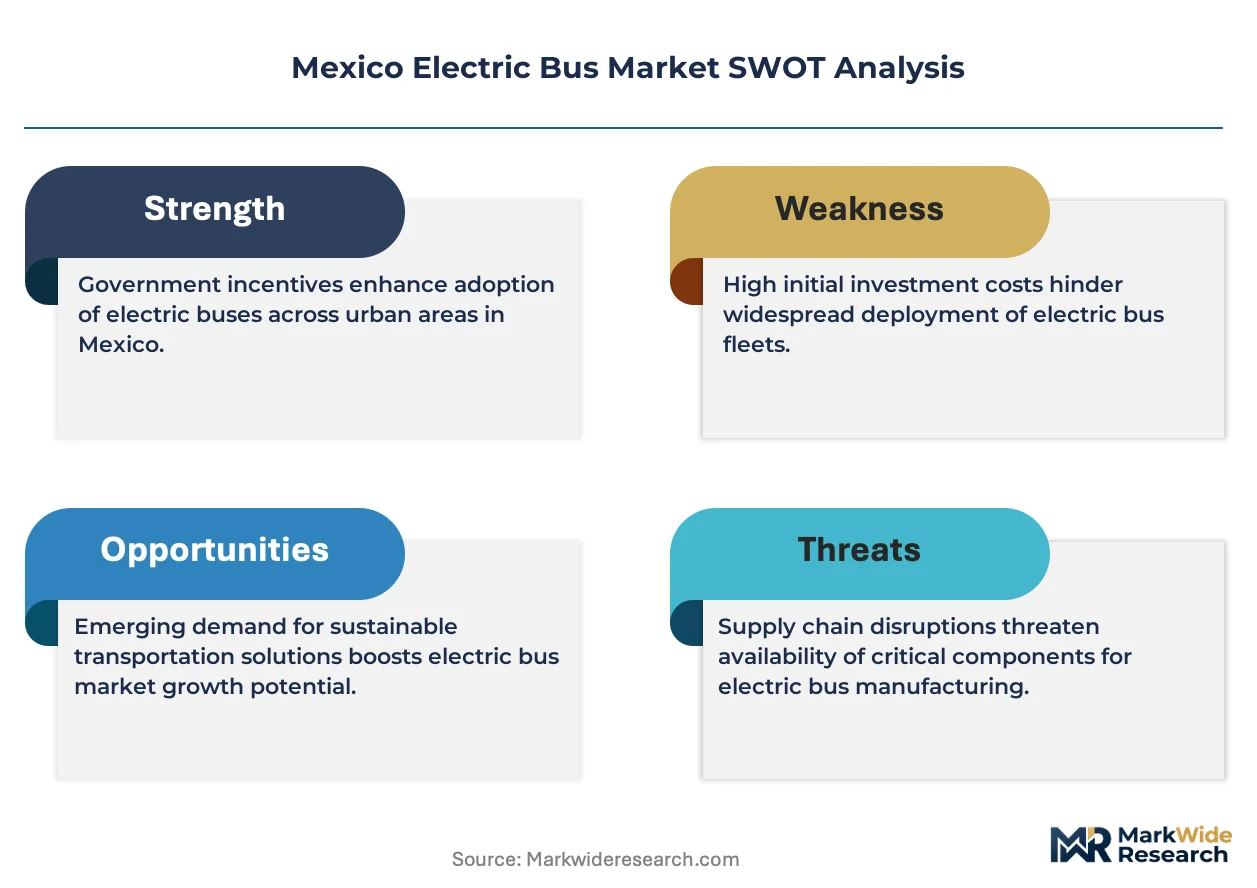
Fleet operators across Mexico's central corridor face compressed procurement timelines as NOM-044-SEMARNAT-2017 particulate limits force diesel bus retirements ahead of schedule. Municipal transit authorities must reconcile zero-emission mandates with depot infrastructure gaps and grid interconnection bottlenecks.
Growth Catalysts
- NOM-044-SEMARNAT-2017:Tightened particulate emissions standards for urban diesel fleets accelerate retirement schedules and open procurement windows for battery-electric replacements in Mexico City and Guadalajara.
- Congestion pricing zones:Mexico City's Hoy No Circula program and dedicated bus lane networks create operational cost advantages for electric powertrains through reduced toll exposure and priority corridor access.
- FIDE successor programs:Secretaría de Energía charging infrastructure subsidies reduce capital barriers for depot operators sizing transformer capacity and negotiating demand-charge structures with CFE.
Market Restraints
- Lithium carbonate price volatility:Cell material cost swings compress pack supplier margins and destabilize long-term procurement contracts for 150-500 kWh configurations.
- CFE grid interconnection queues:CRE transformer upgrade approval timelines extend depot electrification projects by months, delaying fleet deployment schedules.
- Depot charging infrastructure concentration:Overnight plug-in cycles require dedicated land parcels in dense urban cores where real estate scarcity drives site acquisition costs upward.
Strategic Opportunities
- Jalisco state ZEB mandates:Accelerated electrification timelines under draft state legislation could reshape supplier qualification criteria and create localized content requirements for Guadalajara-area fleets.
- Opportunity charging corridors:Pantograph-based en-route charging at terminal stations enables smaller pack configurations and extends operational range for intercity routes connecting Puebla and Toluca.
- Second-life battery applications:Retired transit packs repurposed for stationary grid storage create circular revenue streams for operators managing 300-800V DC asset lifecycles.
Industry Challenges
- High-voltage technician scarcity:Permanent-magnet synchronous motor maintenance and 800V DC pack servicing require specialized certifications that Mexico's vocational training pipeline has not yet scaled to meet.
- Regenerative braking integration:Fleet mechanics must recalibrate diagnostic protocols for blended brake systems where friction and electric retardation interact unpredictably on Latin American road grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Electric Bus Market |
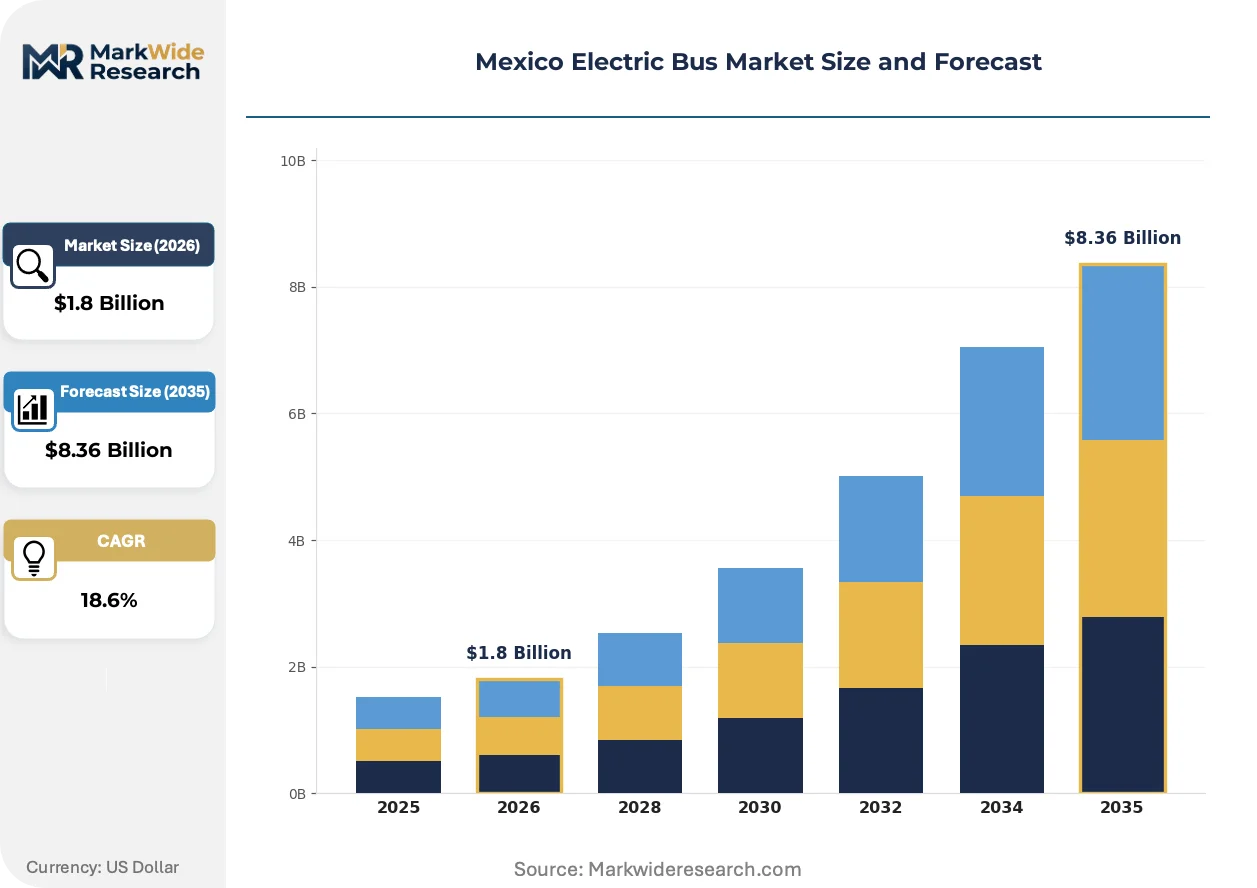
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: City Bus, Shuttle Bus, Intercity Bus, School Bus Charging Infrastructure: Fast Charging, Depot Charging, Wireless Charging, Slow Charging End User: Public Transport, Private Operators, Government, Fleet Operators Battery Technology: Lithium-ion, Solid State, Nickel Metal Hydride, Lead Acid |
| Companies Covered | Daimler AG, Higer Bus Co Ltd, BYD Co Ltd, Dina, Volvo AB, Zhengzhou Yutong Bus Co Ltd, Zhongtong Bus Co Ltd, Megaflux, King Long Bus United Automotive Industries Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Electric Bus Market Trends and Innovations
Predictive charging algorithms and depot-management software bundles now reshape how Mexican operators optimize asset utilization and energy costs. Three convergent developments define the technology frontier.
Battery-cell-to-chassis architecture eliminates traditional pack framing and reduces vehicle weight. State-owned transit authorities in Nuevo León and Mexico City are specifying integrated designs for new procurements. This structural simplification is automating assembly sequences and compressing supplier qualification timelines for chassis integrators.
SEMARNAT enforcement protocols for NOM-044 now include real-time telematics verification of diesel fleet emissions. Non-compliant operators face operating permit suspensions. Mexico City metropolitan area agencies are responding by front-loading electric procurement to preempt regulatory shutdowns.
Service contracting is fragmenting from bundled procurement toward unbundled after-sales agreements. Fleet managers now source predictive maintenance software, driver training, and charging infrastructure from separate vendors rather than single-source OEM packages. This disaggregation is most visible in Guadalajara where municipal operators negotiate software licenses independently of vehicle purchases.
Mexico Electric Bus Market Segmentation
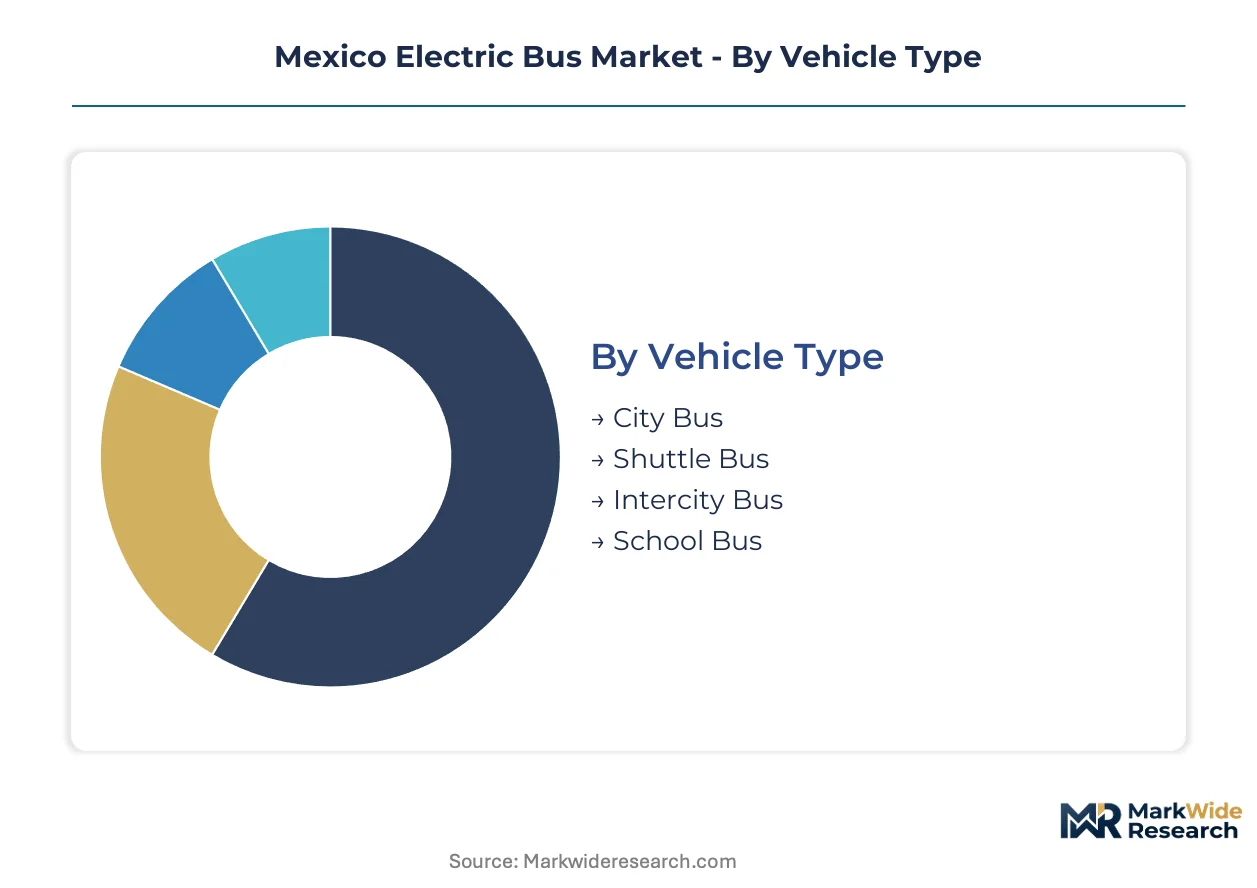
Segmentation in Mexico's electric bus market reveals where capital deployment concentrates and which technology configurations align with specific operational constraints. Procurement patterns diver sharply across vehicle duty cycles, charging topologies, and battery chemistries as operators balance range requirements against infrastructure investment horizons.
Vehicle Type:
Capital intensity varies dramatically across duty-cycle configurations, with depot infrastructure requirements and battery pack sizing driving total cost of ownership spreads.
- City Bus:Configured for 150-500 kWh pack architectures with permanent-magnet synchronous motors optimized for stop-and-go regenerative recovery. Mexico City metropolitan agencies dominate procurement volumes as Hoy No Circula congestion exemptions and dedicated lane access compress payback periods for high-utilization fleets.
- Intercity Bus:Demands extended-range battery configurations and opportunity charging corridors along Puebla-Toluca routes. Operators face range anxiety on highway grades where regenerative braking yields diminish, forcing larger pack investments or pantograph infrastructure at terminal stations.
- Shuttle Bus:Compact routes serving corporate campuses and airport connectors favor smaller pack sizes with overnight depot cycles.
- School Bus:Predictable morning-afternoon duty cycles align with residential depot locations, though NOM-044 enforcement has lagged behind municipal transit timelines.
Most installed capacity flows through City Bus configurations. Expansion is steepest in Intercity Bus as corridor electrification pilots advance.
Charging Infrastructure:
Site acquisition costs and grid interconnection timelines differentiate deployment economics across charging modalities.
- Depot Charging:Overnight plug-in cycles at 300-800V DC align with fleet parking patterns and minimize CFE demand-charge exposure. Guadalajara municipal operators prioritize this topology for its operational predictability, though CRE transformer upgrade queues extend project timelines.
- Fast Charging:High-power pantograph systems enable smaller pack configurations and extended route flexibility. Nuevo León transit authorities pilot terminal-station installations to reduce midday downtime for intercity services.
- Slow Charging:Lower capital requirements suit private operator fleets with extended dwell periods.
- Wireless Charging:Inductive pad systems remain pre-commercial in Mexico, with pilot interest concentrated in Monterrey tech-corridor demonstrations.
Depot Charging absorbs the majority of capital deployment. Fast Charging is climbing the fastest as opportunity-charging corridors reshape route planning.
End User:
Procurement authority and subsidy access create divergent qualification requirements across operator categories.
- Public Transport:State-owned transit authorities in Mexico City, Guadalajara, and Monterrey command procurement volumes through FIDE successor program eligibility and NOM-044 compliance mandates. These operators specify integrated battery-cell-to-chassis architectures and bundled depot-management software.
- Fleet Operators:Corporate and intercity charter services prioritize total cost of ownership metrics and residual value certainty, driving demand for predictive maintenance contracts and second-life battery revenue streams.
- Private Operators:Smaller scale and limited balance-sheet capacity restrict access to federal charging subsidies.
- Government:Federal and state agency fleets follow procurement protocols distinct from municipal transit, with Jalisco state ZEB mandates creating localized content requirements.
Public Transport channels the dominant share of unit volume. Fleet Operators are gaining share fastest as corporate sustainability commitments harden.
Battery Technology:
Cell chemistry selection trades energy density, cycle life, and supply chain maturity against pack cost curves.
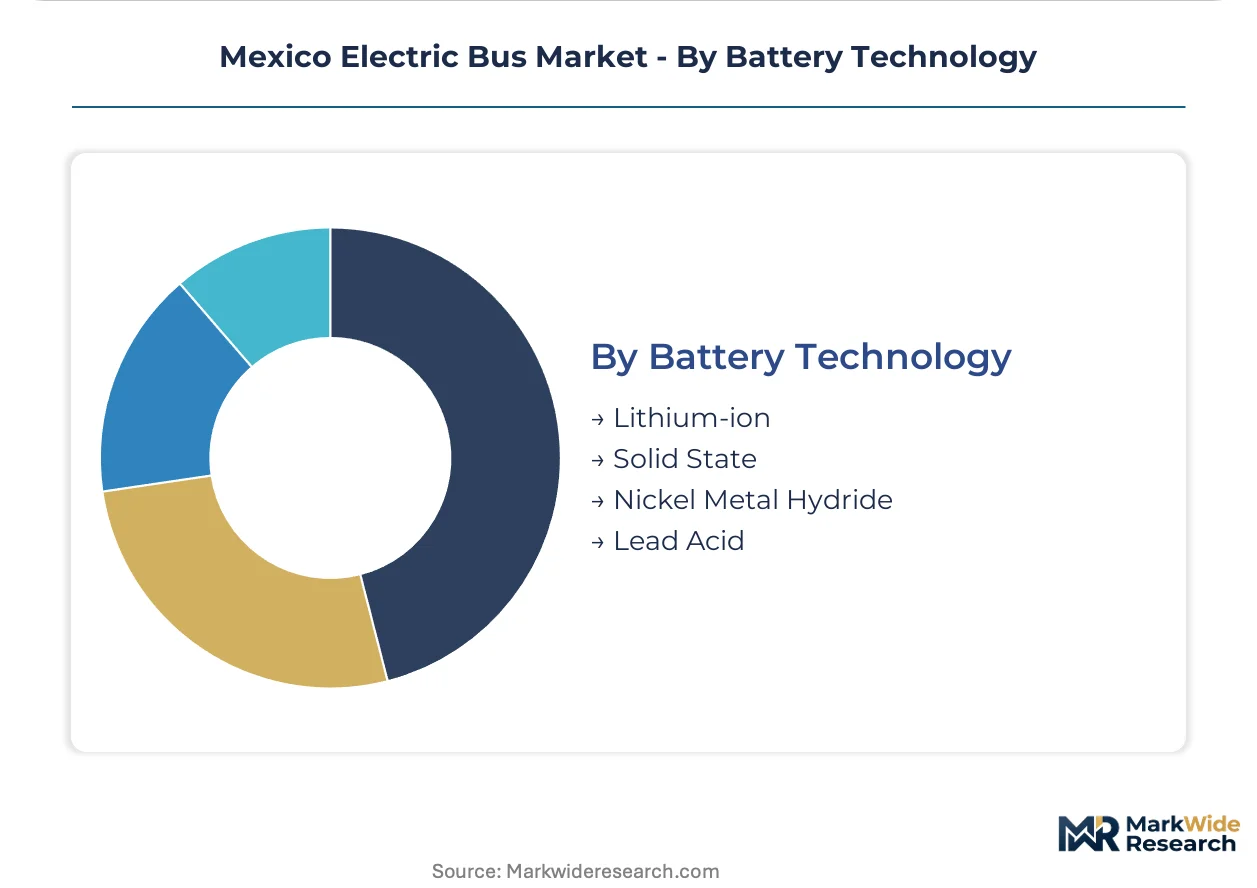
- Lithium-ion:NMC and LFP cell formats dominate near-term procurement through established recycling pathways and supplier qualification timelines. BYD's integrated cell-to-chassis designs anchor Mexico City contracts, while established cost curves preserve economic advantage over emerging alternatives.
- Solid State:Pilot interest concentrates in next-generation procurement specifications for extended-range intercity configurations, though manufacturing scale and thermal management validation remain unresolved.
- Nickel Metal Hydride:Legacy hybrid applications persist in shuttle segments where pack replacement cycles favor proven reliability.
- Lead Acid:Auxiliary power applications only, excluded from traction powertrain specifications.
Lithium-ion carries virtually all traction powertrain deployment. Solid State is expanding most quickly in pilot specifications for premium intercity configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Mexican states are redirecting procurement volume toward jurisdictions with faster subsidy disbursement and streamlined CRE interconnection approvals. Fleet operators migrate contracts across state lines to capture FIDE successor program eligibility and avoid NOM-044 enforcement backlogs.
Mexico City Metro
Hoy No Circula congestion exemptions and dedicated Metrobús lane access concentrate electric bus deployment in the capital corridor. SEMARNAT enforcement of NOM-044 particulate limits forces diesel retirements ahead of schedule across Miguel Hidalgo and Benito Juárez boroughs. State-owned transit authorities specify integrated battery-cell-to-chassis architectures for high-utilization fleets serving the Tláhuac and Insurgentes corridors.
Nuevo León
Monterrey metropolitan agencies pilot opportunity-charging corridors along the García-Apodaca axis to reduce midday downtime for intercity services. Draft state ZEB mandates under Jalisco-style acceleration timelines could reshape supplier qualification criteria and localize content requirements for northern border fleets. Industrial clusters in Santa Catarina and San Pedro Garza García anchor depot electrification projects with CRE transformer upgrade queues extending project timelines.
Jalisco
Guadalajara municipal operators negotiate software licenses independently of vehicle purchases, fragmenting service contracting from bundled procurement. State-level clean mobility programs compress procurement timelines for zero-emission vehicles serving the Zapopan-Tlaquepaque corridor. SITEUR and Mi Macro infrastructure expansion creates dedicated bus lane networks favoring electric powertrains through priority corridor access.
Bajío Region
Querétaro and Guanajuato industrial corridors attract second-life battery repurposing facilities for stationary grid storage applications. Automotive supplier ecosystems in Silao and San José Iturbide provide chassis fabrication capacity for electric bus integrators. State energy commissions coordinate with CFE on demand-charge structures for depot operators sizing transformer capacity in León and Querétaro City.
Northern Border States
Baja California and Chihuahua transit agencies leverage proximity to US cross-border freight corridors for pantograph-based fast charging infrastructure. Maquiladora zone electrification commitments drive corporate shuttle bus demand in Tijuana and Ciudad Juárez. CFE interconnection bottlenecks remain acute where grid infrastructure serves industrial load centers ahead of transit depot requirements.
Mexico Electric Bus Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding public transport tenders while regional assemblers serve private fleet niches. Market structure tilts toward consolidation at the high-volume end where battery-cell-to-chassis architectures require capital-intensive qualification timelines. Three archetypes dominate: integrated Chinese battery-bus specialists, European modular platform providers, and Latin American chassis integrators. Competitive moves center on strategic partnerships for charging infrastructure bundling and backward integration into cell supply to stabilize pack cost exposure.
Within the integrated specialist tier, BYD Co Ltd and Zhengzhou Yutong Bus Co Ltd exemplify the battery-cell-to-chassis approach that anchors Mexico City procurement contracts. Daimler AG occupies a position among European modular platform providers adapting engineering credibility for Latin American road grades. Among regional fabricators, Dina represents the chassis integration archetype serving state-level qualification requirements.
| Leading Market Players |
|---|
| Daimler AG |
| Higer Bus Co Ltd |
| BYD Co Ltd |
| Dina |
| Volvo AB |
| Zhengzhou Yutong Bus Co Ltd |
| Zhongtong Bus Co Ltd |
| Megaflux |
| King Long Bus United Automotive Industries Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Battery-cell-to-chassis architecture adoption by Mexican state-owned transit authorities compresses assembly costs while concentrating supplier qualification power among integrated Chinese specialists. This structural shift simultaneously reduces pack framing expenses and locks procurement channels toward vertically integrated OEMs capable of delivering 300-800V DC systems with bundled depot-management software.
Pricing Analysis
Distributor margins on charging infrastructure equipment absorb 12-18 points before municipal operators negotiate final depot electrification contracts. Three-tier pricing structure across premium, standard, and economy levels separates integrated cell-to-chassis platforms from modular retrofits and basic conversion kits. Cost compression in economy-tier configurations is intensifying because lithium carbonate volatility forces pack suppliers to absorb margin erosion. Fleet operators with FIDE successor program eligibility demonstrate lowest price sensitivity, while private charter services without subsidy access face acute procurement budget constraints.
Supply Chain Analysis
Lithium carbonate feedstock rests on Chilean and Argentine brine extraction operations, with Chinese chemical processing dominance converting raw material into cathode precursors. Permanent-magnet synchronous motors draw from Japanese and South Korean rare-earth magnet fabricators, while high-voltage inverter assemblies hinge on German power electronics specialists. Single-source vulnerability concentrates in NMC cell supply where CATL and BYD captive production controls pricing power. Distribution runs through state-level transit authority procurement offices that bundle vehicle, software, and charging infrastructure into consolidated tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's electric bus market compounds steadily as NOM-044 enforcement tightens particulate limits and compresses diesel retirement timelines across metropolitan corridors.
For Market Incumbents: Hedge cell cost exposure through backward integration into cathode precursor supply or long-term offtake agreements with Chilean brine operators. Secure CRE transformer upgrade queue priority by pre-positioning engineering documentation for depot interconnection applications ahead of competitor filings. Counter emerging Chinese specialist pressure by localizing chassis assembly in Bajío automotive clusters to satisfy Jalisco-style content requirements. For New Entrants and Emerging Players: Begin with second-life battery repurposing services for stationary grid storage, where Querétaro and Guanajuato industrial corridors lack established asset lifecycle managers. Target corporate shuttle operators in Tijuana maquiladora zones, where sustainability commitments outpace qualified supplier availability. Lead with predictive maintenance software unbundled from vehicle procurement, mirroring Guadalajara municipal operators' contracting fragmentation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chassis integrators without captive cell supply, as lithium price volatility discounts their forward earnings. Five-to-ten year viability favors specialists with FIDE successor program eligibility and Nuevo León state procurement relationships. Watch CRE interconnection approval velocity as the inflection signal—accelerating transformer upgrade queues indicate depot electrification capex inflection and fleet deployment pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode precursor contracts with Chilean producers stabilize pack cost curves for 150-500 kWh configurations. |
| Charging Infrastructure Partnership | Pantograph corridor development along Puebla-Toluca routes enables intercity range extension without oversized battery investments. |
| Platform Standardization | Unified 800V DC architectures reduce technician training burden and parts inventory complexity across mixed fleets. |
| Software-Defined Vehicle Investment | Predictive charging algorithms bundled with depot-management systems differentiate procurement bids for Mexico City tenders. |
| Geographic Manufacturing Footprint | Silao chassis assembly localization satisfies draft Jalisco content requirements and compresses logistics costs for central corridor deliveries. |
Research Methodology
Bottom-up municipal fleet procurement modeling reconciled against top-down battery pack shipment tracking forms the analytical core. Primary interviews with SEMARNAT compliance officers, CFE interconnection planners, state transit authority procurement directors, and depot infrastructure EPC contractors generated operational constraint data. Secondary validation drew from CRE regulatory filings, FIDE successor program disbursement records, NOM-044 enforcement protocols, and lithium carbonate trade flow customs data. Triangulation between operator-level deployment schedules and supplier production bookings calibrated market sizing.
Historical deployment trendlines across Mexico City, Guadalajara, and Monterrey metropolitan areas established baseline penetration rates. The analytical framework projects unit volumes across vehicle type, charging topology, battery chemistry, and end-user category over the projection horizon. CAGRs derive from regression-adjusted fleet replacement cycles, subsidy disbursement trajectories, and CRE interconnection capacity expansion schedules. Segment-specific inputs include Hoy No Circula exemption eligibility, NOM-044 enforcement phase-in timing, and state-level ZEB mandate acceleration scenarios.
Several conditions sit outside the modeled scope, including unannounced federal subsidy program modifications, lithium carbonate spot price spikes exceeding historical volatility bands, and CFE grid infrastructure investment delays beyond CRE-approved timelines. Forecasts reflect documented assumptions about NOM-044 enforcement consistency and FIDE successor program continuity. A small set of named triggers warrants ongoing watch: CRE interconnection queue acceleration, Jalisco ZEB mandate legislative passage, and solid-state battery manufacturing scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market