
 Packaging Solutions Market | 2026-2036
Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Solutions Market Outlook
India's corrugated capacity expansion is reshaping regional supply dynamics for fiber-based protective formats. Amcor plc leverages multi-layer barrier film expertise to anchor pharmaceutical serialization compliance in European markets. Smurfit Westrock controls containerboard integration across recycled fiber networks, while Mondi specializes in kraft paper solutions for industrial bulk applications.
Packaging solutions encompass engineered enclosures, wraps, and containment systems manufactured from substrates including polyethylene terephthalate, unbleached kraft pulp, aluminum alloys, and borosilicate glass, formed through extrusion blow molding, thermoforming, or flat-bed die cutting to preserve product integrity through distribution cycles. Flexible packaging leads margin capture in moisture-sensitive food matrices where multi-layer coextrusion replaces rigid alternatives. Rigid packaging dominates shelf-stable beverage and personal care segments where dimensional stability protects brand presentation. Eco-friendly packaging formats attract converter R&D allocation as Extended Producer Responsibility schemes tighten material recovery thresholds.
The EPA governs per- and polyfluoroalkyl substance restrictions in food-contact materials, compelling substrate reformulation across US converter operations. REACH and EU Green Deal packaging waste directives mandate recycled content minimums and design-for-recycling protocols, reshaping material procurement for exporters serving European markets. India's BIS certification requirements for food-grade plastics create compliance gateways for domestic and imported formats. Stakeholders must track evolving extended producer responsibility implementations and mono-material substitution feasibility to preserve market access and margin structure.
Market Dynamics
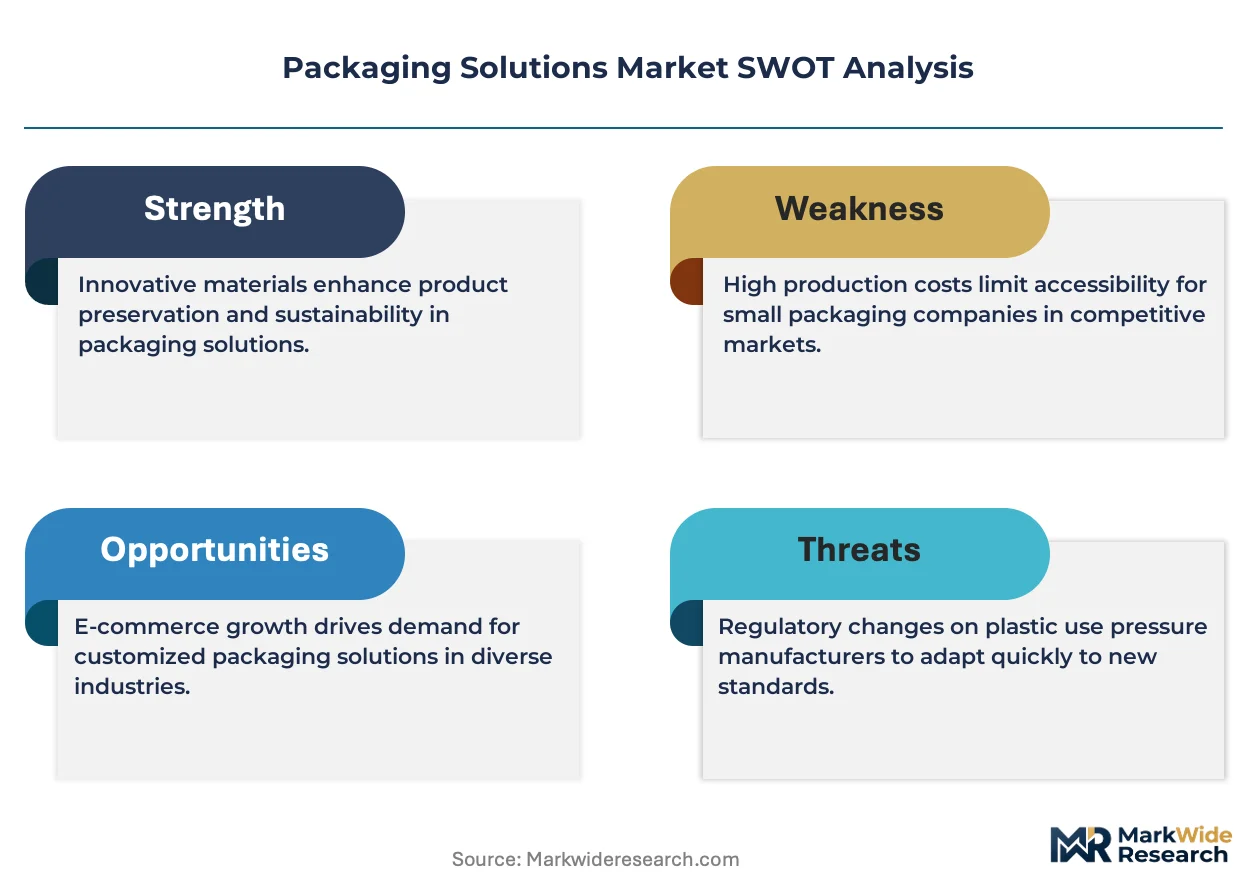
Mono-material film substitution is compressing multi-layer barrier margins while EU Green Deal packaging waste rules force converter asset reconfiguration across European extrusion networks.
Growth Catalysts
- E-commerce fulfillment density:Asia-Pacific cross-border parcel volumes are pulling protective corrugated and air cushion formats into automated sortation hubs in China, Vietnam, and Indonesia.
- REACH recycled content mandates:European converters are qualifying post-consumer polyethylene streams for food-contact applications ahead of 2030 minimum thresholds.
- Pharmaceutical serialization:Track-and-trace compliance requirements in India and the European Union are expanding demand for tamper-evident blister foils and serialized labels.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings in the US Southeast and Nordic regions are squeezing containerboard converter margins.
- Fluoropolymer reformulation lag:EPA restrictions on per- and polyfluoroalkyl substances in grease-resistant food packaging have eliminated incumbent substrate options before commercial replacements reached scale.
- Aluminum can sheet concentration:Primary aluminum rolling capacity in the Middle East and Russia supplies three-quarters of European beverage can body stock, creating single-source vulnerability.
Strategic Opportunities
- India pharmaceutical export corridors:Cold-chain packaging demand for temperature-sensitive biologics is outpacing domestic insulated box production capacity.
- Chemical recycling feedstock:Pyrolysis oil from mixed plastic waste is qualifying for food-contact mechanical recycling equivalence under emerging EFSA guidelines.
- Reusable transit packaging:Pooling systems for automotive and electronics components are displacing single-use corrugated in German and French manufacturing supply loops.
Industry Challenges
- Mono-material barrier performance gaps:Oxygen and moisture transmission rates in polyethylene-only structures still fail shelf-stable meat and cheese specifications, forcing extended R&D timelines.
- Extended producer responsibility administration:Fragmented national reporting systems across EU member states are multiplying compliance overhead for pan-European brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Solutions Market |
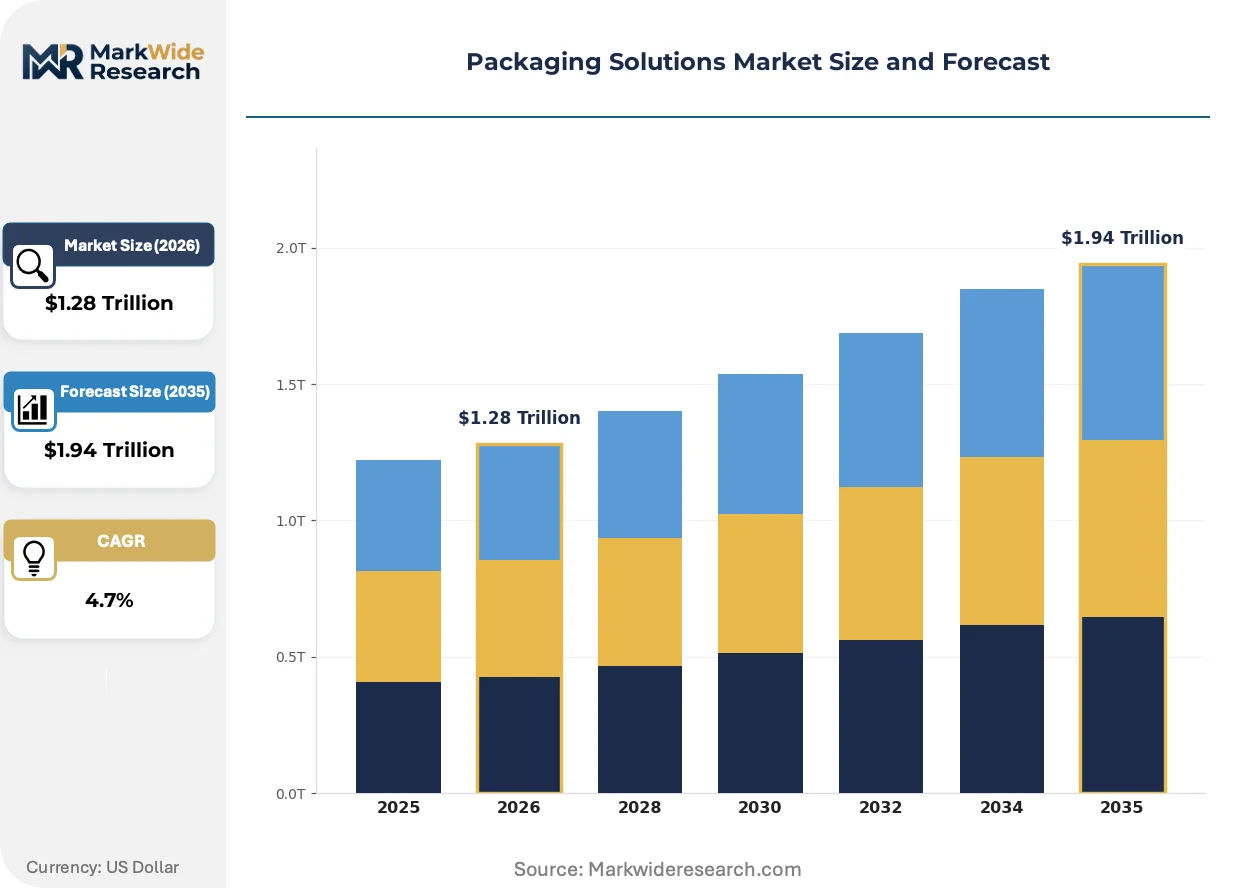
| Market Size in 2026 | $1.28 Trillion |
| Market Size in 2035 | $1.94 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Containers, Labels Material: Plastic, Paper, Metal, Glass End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Packaging Type: Retail Packaging, Industrial Packaging, Tray Packaging, Eco-Friendly Packaging |
| Companies Covered | Amcor plc, Smurfit Westrock, Mondi, International Paper, Berry Global Group, Sealed Air, WestRock, Ball Corporation, Sonoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Solutions Market Strategic Shifts
Digital printing and smart packaging integration are collapsing minimum order quantities while enabling unit-level traceability, reshaping converter equipment investment priorities and brand owner procurement patterns simultaneously.
Water-based barrier coatings derived from cellulose nanofibrils are rendering obsolete conventional polyethylene extrusion layers in frozen food cartons. European retail private-label buyers are qualifying these substrates for microwaveable vegetable and ready-meal applications. The shift is compressing coextrusion line utilization rates at integrated paperboard mills.
EU Green Deal packaging waste directives are mandating design-for-recycling protocols and recycled content minimums that disqualify multi-material laminates from extended producer responsibility fee discounts. Exporters serving European markets are reformulating snack and confectionery wrappers ahead of 2030 enforcement milestones. The regulatory pressure is accelerating mono-material film pilot programs in Southeast Asian converter networks.
Brand owners are consolidating supplier panels around converters offering integrated design, pre-press, and fulfillment services, displacing transactional spot purchasing for seasonal promotions. Food and beverage multinationals in Germany and the Netherlands are embedding packaging engineers within converter innovation centers. The procurement model shift is most visible in personal care and premium chocolate segments where speed-to-shelf determines competitive position.
Packaging Solutions Market Segmentation
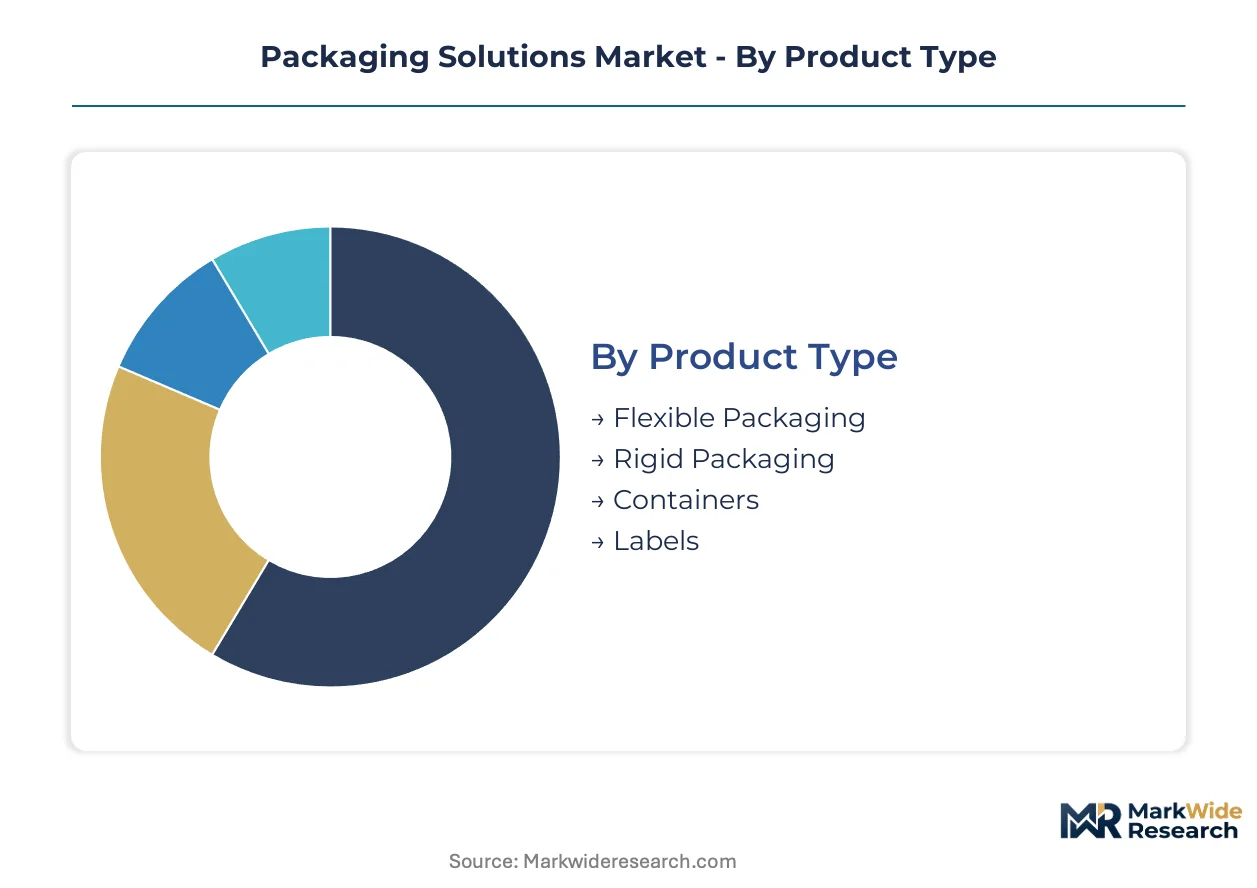
Segmentation in packaging solutions reveals divergent margin structures and capital intensity across substrate classes. Converter investment cycles and brand owner procurement patterns align tightly with product type and material characteristics rather than end-use alone.
Product Type:
Flexible formats turn inventory fastest through roll-fed converting lines, while rigid packaging ties up capital in injection molds with multi-year amortization schedules.
- Flexible Packaging:Multi-layer films and pouches formed through blown film extrusion and lamination dominate moisture-sensitive food matrices. Pharmaceutical blister foils in India and Southeast Asia are pulling metallized polyester capacity toward serialization-compliant formats.
- Rigid Packaging:Injection-molded containers, thermoformed trays, and blow-molded bottles provide dimensional stability for shelf-stable beverages. European dairy and personal care brand owners are consolidating supplier panels around converters with in-house toolmaking capability.
- Containers:Corrugated boxes, folding cartons, and rigid boxes engineered through flat-bed die cutting and gluing operations. E-commerce fulfillment density in Vietnam and Indonesia is accelerating automated corrugated line investment.
- Labels:Pressure-sensitive, shrink-sleeve, and in-mold formats carrying variable data printing for track-and-trace compliance. Wine and spirits exporters in France and Italy are qualifying digital label presses for short-run regional customization.
Flexible packaging anchors the volume base while labels gain share at the steepest rate.
Material:
Cost tiers stratify sharply between commodity resin cycles and specialty substrate premiums, with recycled content mandates compressing virgin material margins.
- Plastic:Polyethylene terephthalate, polypropylene, and polyethylene resins formed through extrusion and thermoforming. REACH recycled content thresholds are forcing European converters to qualify post-consumer polyethylene streams for food-contact applications.
- Paper:Unbleached kraft pulp, recycled linerboard, and solid bleached sulfate for folding cartons. Old corrugated container price volatility in the US Southeast is squeezing containerboard converter margins.
- Metal:Aluminum alloys for beverage cans and aerosol containers, tinplate for food cans. Primary aluminum rolling capacity concentration in the Middle East and Russia supplies three-quarters of European can body stock.
- Glass:Borosilicate and soda-lime formulations for pharmaceutical vials and premium beverage bottles. Borosilicate demand for temperature-sensitive biologics is outpacing domestic insulated box production capacity in India.
Plastic commands the widest application footprint though paper is climbing the fastest on sustainability-driven substitution.
End User:
Application requirements dictate barrier specifications, with pharmaceutical and electronics segments imposing the most stringent contamination controls.
- Food & Beverage:Modified atmosphere packaging and aseptic filling systems for shelf-life extension. Water-based cellulose nanofibril coatings are displacing polyethylene extrusion layers in European frozen food cartons.
- Pharmaceuticals:Tamper-evident blister foils, serialized labels, and cold-chain insulated boxes. India's pharmaceutical export corridors are expanding demand for temperature-controlled packaging beyond domestic production capacity.
- Personal Care:Airless pumps, dual-chamber tubes, and premium rigid boxes for brand differentiation. German and Dutch multinationals are embedding packaging engineers within converter innovation centers.
- Electronics:Anti-static films, foam-in-place cushioning, and moisture barrier bags for semiconductor shipment. Reusable transit packaging pooling systems are displacing single-use corrugated in German and French manufacturing supply loops.
Food and beverage generates the highest absolute tonnage while pharmaceuticals posts the steepest expansion trajectory.
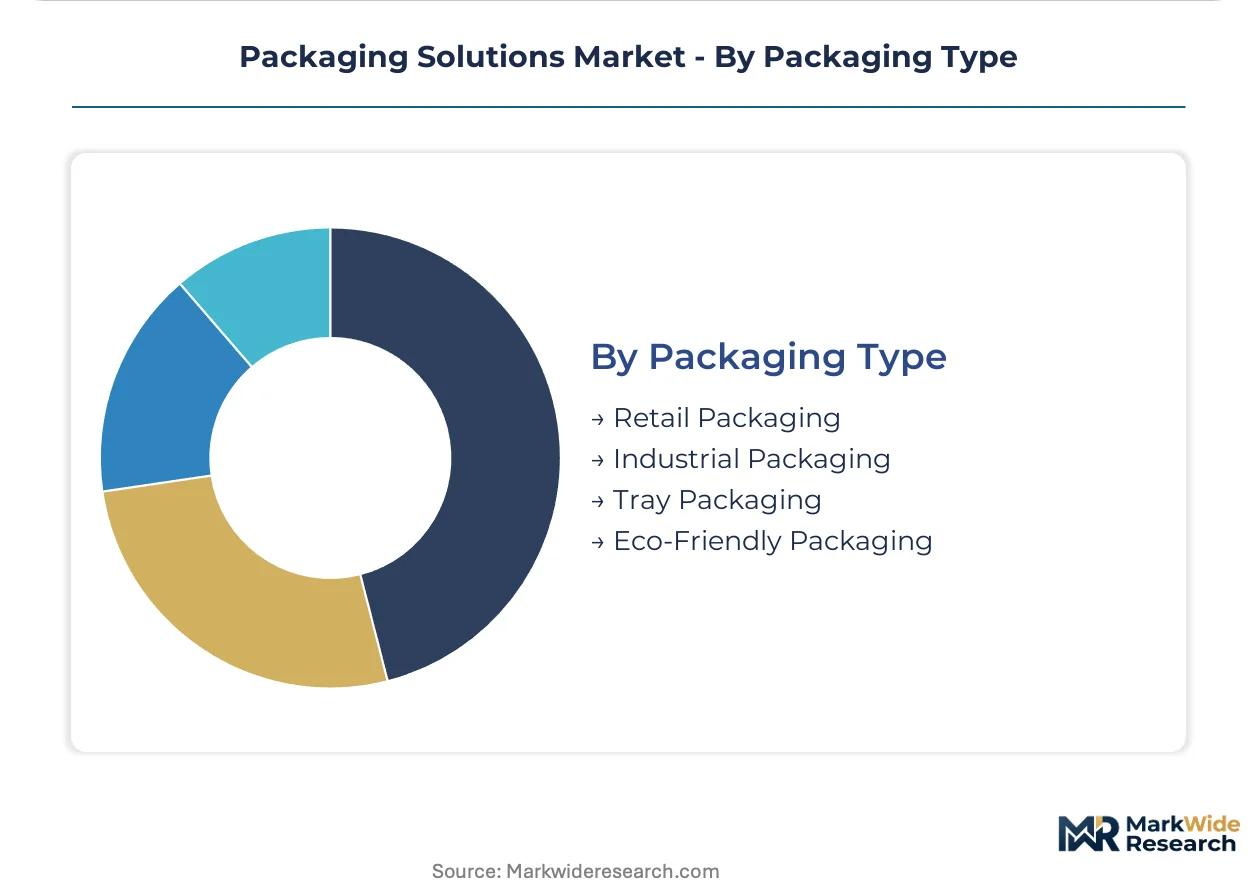
Packaging Type:
Customer type and channel configuration separate high-velocity retail formats from durable industrial systems with extended reuse cycles.
- Retail Packaging:Shelf-ready trays, display cartons, and primary consumer-facing formats. EU Green Deal packaging waste directives are disqualifying multi-material laminates from extended producer responsibility fee discounts.
- Industrial Packaging:Bulk containers, intermediate bulk containers, and protective dunnage for manufacturing supply chains. Automotive component pooling systems in France are scaling reusable plastic container networks.
- Tray Packaging:Thermoformed PET and PP trays for fresh produce and ready meals. Mono-material polyethylene tray pilot programs in Southeast Asia are accelerating ahead of European regulatory alignment.
- Eco-Friendly Packaging:Compostable films, molded fiber, and mono-material structures designed for circular recovery. Pyrolysis oil from mixed plastic waste is qualifying for food-contact mechanical recycling equivalence under emerging EFSA guidelines.
Retail packaging holds the installed base while eco-friendly formats are expanding most quickly on regulatory pressure and brand owner commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA restrictions on per- and polyfluoroalkyl substances are forcing substrate reformulation across US converter operations, while EU Green Deal packaging waste directives and India's BIS certification requirements create divergent compliance gateways for exporters.
United States
E-commerce fulfillment density pulls protective corrugated into automated sortation hubs across California and Texas. The EPA governs PFAS restrictions in food-contact materials, compelling converter asset reconfiguration. Old corrugated container price volatility in the US Southeast squeezes containerboard converter margins.
Germany
Automotive and electronics manufacturers are scaling reusable transit packaging pooling systems across Bavaria and Baden-Württemberg. REACH recycled content mandates force qualification of post-consumer polyethylene streams for food-contact applications. Brand owners in the Rhine-Ruhr corridor embed packaging engineers within converter innovation centers.
India
Pharmaceutical export corridors expand cold-chain packaging demand for temperature-sensitive biologics beyond domestic insulated box production capacity. BIS certification requirements for food-grade plastics create compliance gateways for imported formats. Organized retail concentration in Maharashtra and Gujarat drives corrugated capacity expansion.
China
Cross-border parcel volumes accelerate automated corrugated line investment in Yangtze River Delta fulfillment networks. Dual carbon goals redirect converter R&D toward mono-material substitution feasibility. Shenzhen and Guangzhou converter networks pilot chemical recycling feedstock qualification under emerging EFSA-aligned guidelines.
France
Wine and spirits exporters qualify digital label presses for short-run regional customization in Bordeaux and Champagne. EU Green Deal packaging waste rules disqualify multi-material laminates from extended producer responsibility fee discounts. Île-de-France retail private-label buyers qualify water-based cellulose nanofibril coatings for microwaveable ready-meal applications.
Packaging Solutions Market Competitive Environment
Integrated substrate producers and specialized converter networks split the market between scale-driven margin capture and agility-focused service models. Tier-one players control multi-layer barrier film expertise and containerboard integration across recycled fiber networks. Mid-cap specialists anchor pharmaceutical serialization compliance and kraft paper solutions for industrial bulk applications. Competitive moves concentrate on capacity expansion in Asia-Pacific fulfillment corridors and portfolio diversification toward mono-material structures.
Within the integrated packaging tier, Amcor plc and Smurfit Westrock occupy positions exemplifying multi-regional substrate control and containerboard network integration respectively. Mondi represents the specialized industrial positioning anchored in kraft paper solutions. These three entities illustrate the strategic archetype spectrum: Australian- and Irish-American-anchored integrated players versus Austrian-based substrate specialists, each responding to EU Green Deal mandates and Asia-Pacific e-commerce density through divergent asset configurations.
| Leading Market Players |
|---|
| Amcor plc |
| Smurfit Westrock |
| Mondi |
| International Paper |
| Berry Global Group |
| Sealed Air |
| WestRock |
| Ball Corporation |
| Sonoco |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta converter clusters anchor global polyethylene film supply, translating capacity concentration into pricing leverage over European brand owners facing REACH recycled content mandates. Old corrugated container volatility in the US Southeast and Nordic regions feeds directly into containerboard converter margin compression, while mono-material substitution pilots in Southeast Asia redirect procurement toward simplified substrate specifications.
Pricing Analysis
Price spreads between European and Asian flexible film converters have widened as EU Green Deal packaging waste rules impose compliance premiums on multi-layer structures. Three-tier pricing structure across premium serialization-compliant formats, standard food-contact films, and economy-grade industrial wraps reflects certification grade and volume scale differentiation. Pricing pressure stems from mono-material barrier performance gaps forcing extended R&D timelines before commercial scale. Small-batch pharmaceutical exporters in India exhibit highest price sensitivity, while German automotive manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Upstream feedstock dependence draws from Saudi Arabian and Qatari polyethylene resin production, US Gulf Coast propylene derivatives, and Brazilian eucalyptus pulp for kraft paper grades. Raw material procurement rests on naphtha cracking margins, recycled fiber collection rates, and aluminum ingot availability from Middle Eastern smelters. Single-source vulnerability concentrates in Russian and Middle Eastern primary aluminum rolling capacity supplying European beverage can body stock. Distribution runs through converter-direct relationships with multinational brand owners, bypassing traditional distributor networks for serialized pharmaceutical and premium food segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging solutions are shifting toward platform economics as digital printing and smart packaging integration collapse minimum order quantities and enable unit-level traceability, creating interoperability standards between converter equipment networks and brand owner procurement systems.
For Market Incumbents: Entrench multi-layer barrier expertise through captive chemical recycling feedstock qualification under emerging EFSA guidelines, defending against mono-material substitution threats from Southeast Asian pilot programs. Deepen backward integration into post-consumer polyethylene stream collection networks ahead of 2030 REACH thresholds. Prioritize embedding packaging engineers within German and Dutch multinational innovation centers to lock in co-development relationships.
For New Entrants and Emerging Players: Build out cold-chain insulated box production capacity targeting India's pharmaceutical export corridors where domestic supply lags biologics demand. White-space opportunities concentrate in reusable transit packaging pooling systems for French and German automotive manufacturing loops. Qualify water-based cellulose nanofibril coatings for European frozen food private-label buyers seeking microwaveable substrate alternatives.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated design-to-fulfillment service platforms over transactional spot-purchase suppliers. Long-term viability across the projection horizon rests on mono-material barrier R&D pipelines and chemical recycling infrastructure access. Acquisition targets should demonstrate EPR fee optimization capabilities under fragmented EU national reporting systems. Watch for EFSA pyrolysis oil qualification milestones as inflection indicators for mechanical recycling equivalence.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Scale-Up | EU Green Deal fee discounts drive converter asset reconfiguration toward recyclable structures. |
| Chemical Recycling Feedstock Integration | Pyrolysis oil qualification under EFSA guidelines opens food-contact mechanical recycling pathways. |
| Pharmaceutical Serialization Capacity Expansion | India's CDSCO track-and-trace mandates expand demand for tamper-evident blister foil lines. |
| Reusable Transit Packaging Pooling Systems | German automotive manufacturers displace single-use corrugated through closed-loop container networks. |
| Digital Printing Platform Deployment | French wine exporters adopt short-run regional customization through variable data label presses. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of converter capacity databases, customs trade records, and regulatory filing repositories. Interviews with corrugated plant managers, flexible film procurement leads at food multinationals, pharmaceutical packaging engineers, and EPR scheme administrators combined with FDA food-contact notifications, ECHA REACH registrations, and BIS certification records. Bottom-up volume estimates from substrate-level production data triangulate against top-down brand owner procurement surveys.
Forecast inputs incorporate substrate substitution elasticities, regulatory enforcement timelines, and e-commerce fulfillment density trajectories across the analysis window. Segmentation dimensions span product type, material class, end-use industry, and geographic regulatory cluster. CAGRs derive from fitted growth curves applied to converter investment pipelines and brand owner sustainability commitment disclosures. Industry-specific inputs include mono-material barrier performance improvement curves and chemical recycling capacity buildout schedules.
Stress conditions across recycled fiber price volatility, PFAS reformulation lag durations, and aluminum rolling supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and Asia-Pacific cross-border parcel growth trajectories. Cross-checking against converter equipment order backlogs and brand owner RFP release patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market