
 Strawless Lids Market | 2026-2036
Strawless Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Strawless Lids Market Analytics
The gap between premium fiber-based lids and commodity polypropylene alternatives is expanding as sustainability mandates harden across foodservice procurement. Amcor leverages its global packaging film infrastructure to supply calibrated barrier coatings for paper lid substrates. Greiner Packaging anchors European dairy and beverage accounts with deep tooling libraries for hinged, strawless formats. Berry Global competes through thermoforming scale and quick-turn customization for regional quick-service brands.
Strawless lids are engineered drinking closures that integrate sip ports, vent channels, or raised dome profiles to eliminate separate straw dependency, typically manufactured through thermoforming, injection molding, or fiber-pressing processes with specified liquid-seal integrity under tilt and transport conditions. Their primary commercial purpose is to maintain beverage containment and consumer ergonomics while satisfying operator cost and regulatory constraints. Rigid plastic lids still occupy the largest volume share across fast-food fountain and drive-through applications, though compostable fiber variants represent the fastest-expanding margin pool as operators face Scope 3 emissions scrutiny. Reusable silicone lids lead in specialty cafe and subscription beverage programs where deposit-return schemes or brand loyalty programs justify higher unit economics.
The FDA governs food-contact substance migration limits for plastic and coating components in the United States, while the EU REACH framework and Single-Use Plastics Directive restrict certain polymer chemistries and mandate extended producer responsibility labeling across member states. These overlapping compliance architectures force lid suppliers to maintain parallel certification portfolios and regional material formulations. Stakeholders must monitor pending state-level packaging EPR legislation in the United States and evolving compostability certification thresholds under EN 13432 to determine capital allocation between fiber press capacity and conventional thermoforming lines.
Market Dynamics
Regulatory bans on single-use plastics are compressing the installed base of conventional straw-dependent lids while forcing capital reallocation toward fiber-pressing and barrier-coating infrastructure across foodservice supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory extended producer responsibility labeling and polymer restrictions across member states are eliminating conventional alternatives and pulling demand toward certified compostable formats.
- Quick-service restaurant chains:Drive-through and fountain beverage operators in California and New York are accelerating procurement of sip-through formats to preempt municipal enforcement timelines.
- Fiber-pressing technology:Advances in molded fiber barrier coatings are closing the performance gap with polypropylene for hot liquid containment, expanding addressable applications.
Market Restraints
- Pulp fiber input volatility:Agricultural residue supply fluctuations and energy costs at European fiber-pressing facilities are compressing margins on compostable lid lines.
- Thermoforming equipment concentration:Tooling fabrication for complex dome profiles clusters with a limited set of German and Austrian mold-makers, creating bottleneck risk.
- EN 13432 certification timelines:Multi-month industrial compostability testing delays product launches and locks up working capital for format development.
Strategic Opportunities
- Deposit-return scheme expansion:Reusable silicone lid programs in Scandinavian markets demonstrate viable unit economics for subscription beverage services.
- India quick-service penetration:Western coffeehouse format rollouts in Mumbai and Bangalore create first-mover positioning for fiber-based lid suppliers.
- On-premise dining revival:Full-service restaurant chains are testing durable polypropylene sip lids for dine-in beverage presentation, opening a premium segment.
Industry Challenges
- Barrier coating chemist scarcity:Formulation expertise for liquid-seal integrity in fiber substrates concentrates with a narrow talent pool in packaging R&D functions.
- Legacy lid inventory stranding:Quick-service operators face write-down pressure on polypropylene stockpiles as municipal ban dates approach.
- Multi-jurisdiction compliance stacking:Parallel FDA migration limits and EU REACH substance restrictions force redundant testing protocols and SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strawless Lids Market |
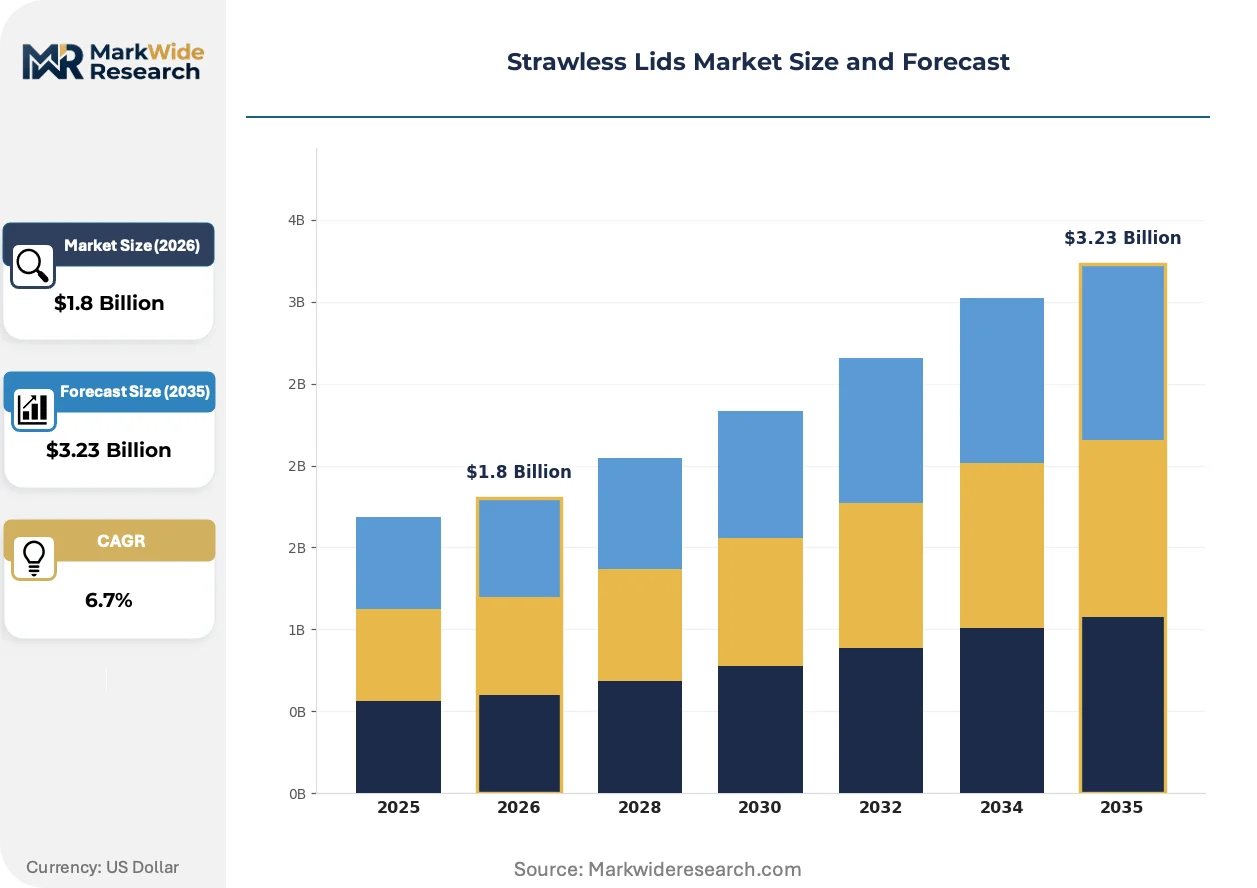
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Lids, Flexible Lids, Reusable Lids, Compostable Lids Material: Plastic, Paper, Biodegradable Materials, Silicone Application: Food Service, Beverage Industry, Retail Packaging, Event Catering End User: Restaurants, Cafes, Food Trucks, Retail Chains |
| Companies Covered | Crown Holdings, Greiner Packaging, Graphic Packaging International, Amcor, Berry Global, Pactiv Evergreen, Dart Container, Mondi Group, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strawless Lids Market Evolving Landscape
Active barrier coating development and regional regulatory fragmentation are simultaneously elevating technical performance requirements and complicating format standardization across foodservice packaging procurement.
Water-based barrier coatings with oxygen and grease resistance are decentralizing the historical polymer monopoly on hot beverage containment. Mid-size coffee roasters and regional bakery-cafe chains are piloting these fiber lids for espresso-based drinks. The shift is decentralizing volume concentration away from petrochemical suppliers toward agricultural fiber processors and coating formulators.
REACH substance restrictions under the EU framework are eliminating certain perfluorinated chemistries from food-contact coatings. Industrial consequence includes accelerated R&D spending on bio-based alternatives and silicone-modified formulations. German and British foodservice distributors are most affected, responding by consolidating procurement around suppliers with certified PFAS-free portfolios.
Direct supplier relationships are displacing traditional distribution intermediaries in lid procurement. Large quick-service chains are negotiating multi-year coating supply agreements that bypass regional packaging distributors. This pattern is most visible in coastal United States markets where sustainability scorecard requirements demand supply chain transparency.
Strawless Lids Market Segmentation
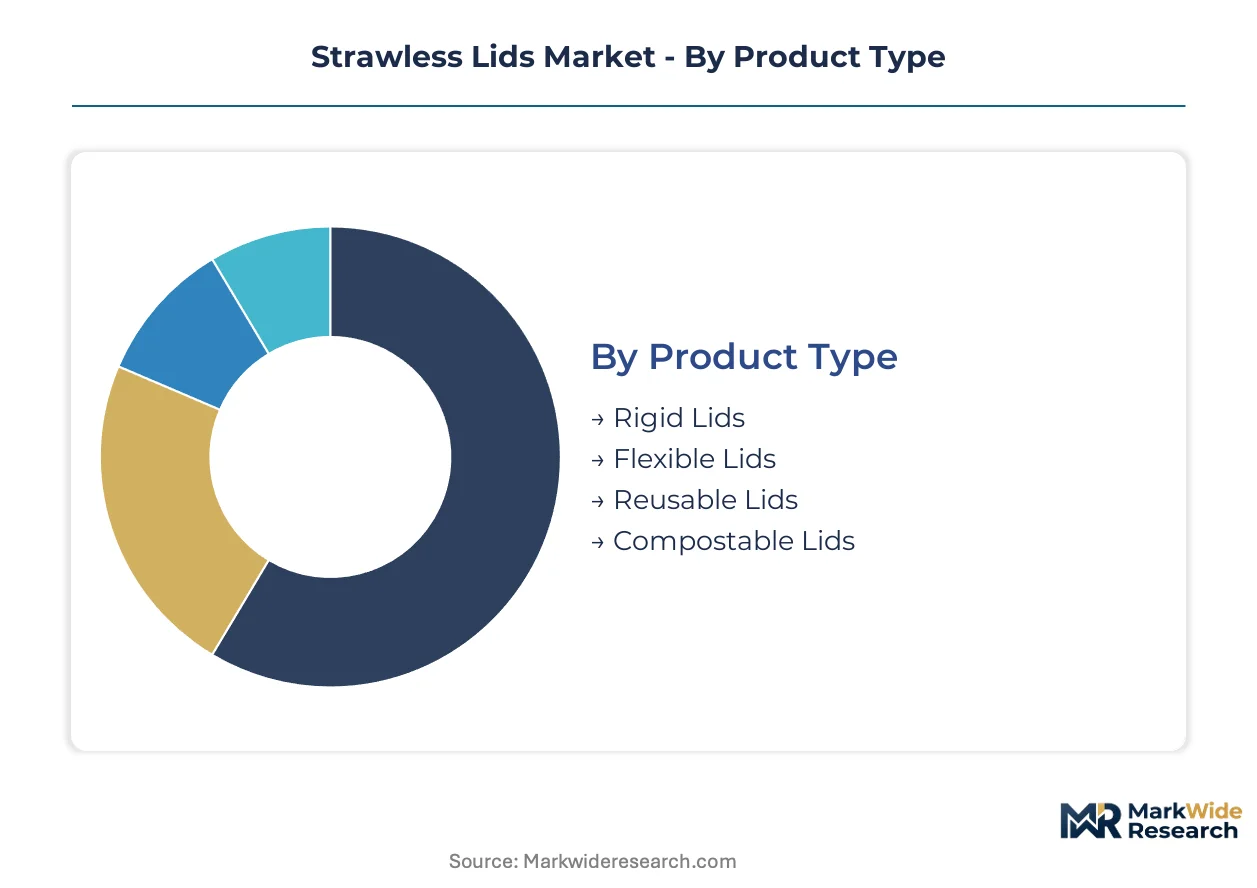
Strawless lid procurement decisions pivot on regulatory compliance timelines, beverage temperature profiles, and disposal infrastructure availability across operator locations. Segmentation reveals divergent margin structures between commodity thermoformed formats and certified compostable alternatives facing diverging certification burdens.
Product Type:
Quick-service operators select lid formats based on beverage viscosity, consumption occasion, and municipal waste stream access.
- Rigid Lids:Injection-molded polypropylene or polystyrene structures with integrated sip ports dominate fountain beverage and drive-through applications. California and New York quick-service chains are accelerating procurement to preempt municipal plastic straw enforcement timelines.
- Compostable Lids:Molded fiber substrates with water-based barrier coatings are closing the performance gap on hot liquid containment. German and British foodservice distributors are consolidating procurement around certified PFAS-free portfolios as REACH substance restrictions eliminate certain perfluorinated chemistries.
- Flexible Lids:Thin-gauge thermoformed formats for cold beverage applications with lower structural requirements.
- Reusable Lids:Silicone formats for specialty cafe subscription programs where deposit-return schemes justify higher unit economics.
Rigid lids lead on scale; compostable lids lead on momentum.
Material:
Material selection traces regulatory geography and waste infrastructure maturity rather than pure cost optimization.
- Plastic:Polypropylene homopolymer and impact copolymer grades remain dominant for fountain beverage containment. FDA migration limits govern food-contact substance thresholds for US operators while EU REACH restrictions constrain polymer chemistries across member states.
- Biodegradable Materials:PLA and PHA formulations serve operators in jurisdictions with industrial composting infrastructure. EN 13432 certification timelines create multi-month delays that lock up working capital for format development.
- Paper:Fiber-pressed substrates with barrier coatings for hot beverage applications in European markets with established composting streams.
- Silicone:Platinum-cured formulations for reusable programs in Scandinavian deposit-return markets.
Plastic dominates current volume; biodegradable materials are climbing the fastest.
Application:
Application segmentation reflects divergent consumption occasions and operator cost structures.
- Food Service:Quick-service and fast-casual operators drive standardization around sip-through formats. Coastal US markets are seeing direct supplier relationships displace traditional distribution intermediaries as sustainability scorecard requirements demand supply chain transparency.
- Beverage Industry:Coffeehouse chains and roasters pilot fiber lids for espresso-based drinks. Mid-size roasters and regional bakery-cafe chains are testing water-based barrier coatings with oxygen and grease resistance.
- Retail Packaging:Pre-packaged beverage formats with extended shelf-life requirements.
- Event Catering:Temporary service occasions with variable waste infrastructure access.
Food service commands installed base; beverage industry shows steepest expansion trajectory.
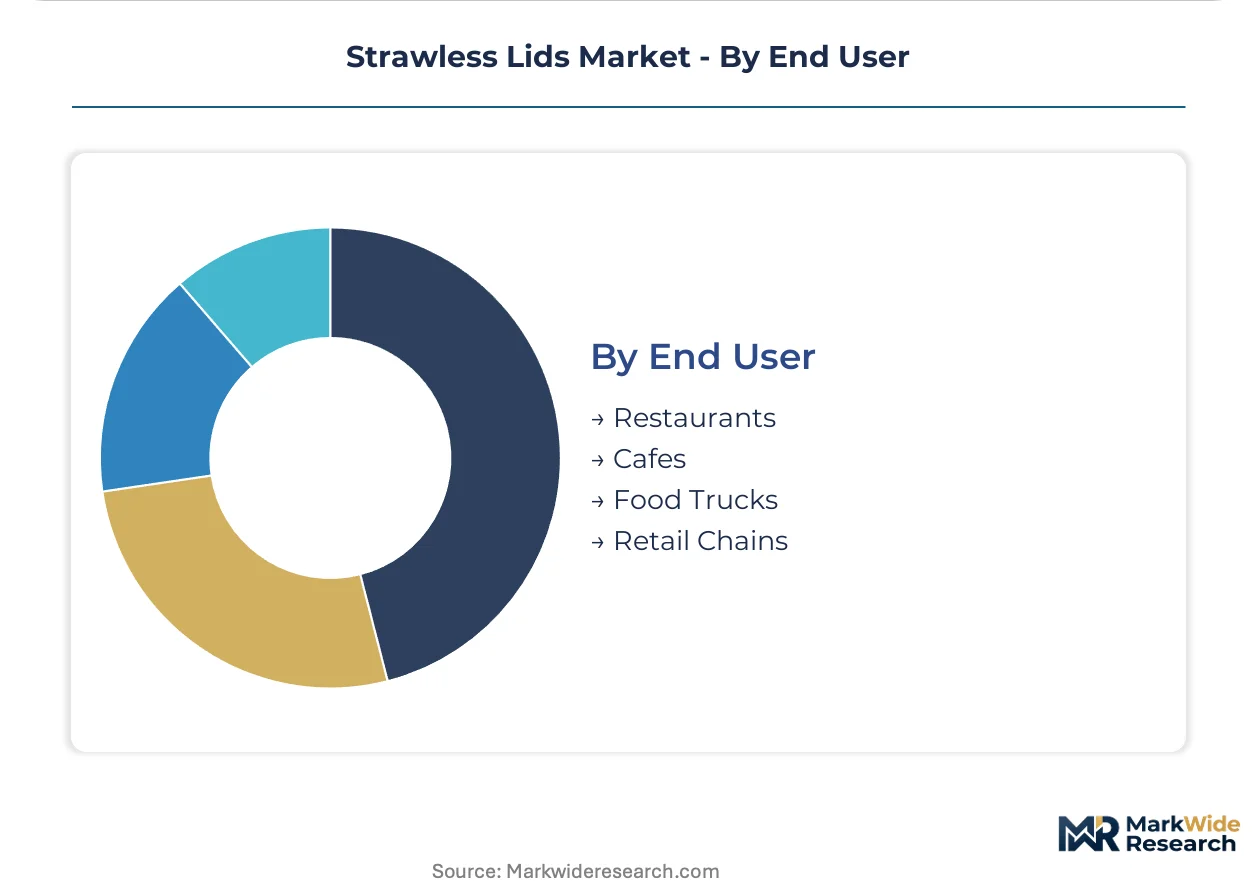
End User:
End-user scale determines procurement leverage and format customization depth.
- Restaurants:Full-service chains are testing durable polypropylene sip lids for dine-in beverage presentation. On-premise dining revival is opening a premium segment distinct from take-away formats.
- Retail Chains:Convenience store and grocery fountain operators with high-volume, low-mix procurement patterns. Large chains negotiate multi-year coating supply agreements that bypass regional packaging distributors.
- Cafes:Independent and small-chain specialty coffee operators with sustainability-forward positioning.
- Food Trucks:Mobile operators with variable regulatory exposure and limited storage capacity.
Retail chains anchor procurement volume; restaurants are gaining share fastest on format experimentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier-coating chemists and fiber-pressing engineers cluster in southern Germany and coastal California, anchoring the technical workforce that supplies strawless lid innovation across regulatory jurisdictions.
United States
California and New York quick-service chains accelerate sip-through lid procurement ahead of municipal enforcement timelines. The FDA governs food-contact substance migration limits for plastic components. Los Angeles and San Francisco foodservice distributors consolidate procurement around suppliers with certified PFAS-free portfolios.
Germany
Industrial composting infrastructure maturity pulls demand toward certified fiber-based formats for hot beverage containment. The EU Single-Use Plastics Directive mandates extended producer responsibility labeling across member states. Bavarian fiber-pressing facilities advance water-based barrier coating development for liquid-seal integrity.
United Kingdom
Mid-size coffee roasters and regional bakery-cafe chains pilot fiber lids for espresso-based drinks. REACH substance restrictions eliminate certain perfluorinated chemistries from food-contact coatings. London foodservice distributors respond by consolidating procurement around certified PFAS-free portfolios.
India
Western coffeehouse format rollouts in Mumbai and Bangalore create first-mover positioning for fiber-based lid suppliers. The FSSAI regulates food-contact materials for domestic operators. Maharashtra quick-service penetration drives demand for sip-through formats in fountain beverage applications.
Canada
Health Canada governs food-contact substance thresholds for quick-service operators across provincial markets. Ontario and British Columbia quick-service chains test durable polypropylene sip lids for dine-in beverage presentation. Toronto foodservice distributors pilot direct supplier relationships that bypass traditional packaging intermediaries.
Strawless Lids Market Competitive Landscape
Top-tier vendors anchor thermoforming and fiber-pressing scale, while mid-cap specialists concentrate barrier-coating formulation and regional customization. The vendor base stratifies across three archetypes: integrated packaging conglomerates with global film infrastructure, European dairy and beverage tooling specialists, and North American quick-service customization shops. M&A activity concentrates coating technology assets, while capacity expansion clusters in German fiber-pressing corridors and US thermoforming corridors.
Within the integrated packaging tier, Amcor leverages global film infrastructure to supply calibrated barrier coatings for paper lid substrates. Greiner Packaging anchors European dairy and beverage accounts with deep tooling libraries for hinged formats. Berry Global competes through thermoforming scale and quick-turn customization for regional quick-service brands.
| Leading Market Players |
|---|
| Crown Holdings |
| Greiner Packaging |
| Graphic Packaging International |
| Amcor |
| Berry Global |
| Pactiv Evergreen |
| Dart Container |
| Mondi Group |
| Huhtamaki |
| Others |
Value Network & Pricing Analysis
Fiber-pressing technology migration from conventional thermoforming is simultaneously elevating capital intensity for barrier-coating infrastructure and concentrating supplier power among German and Austrian mold-makers with proprietary dome-profile tooling libraries. This production-method transition forces quick-service operators to absorb premium unit economics for certified compostable formats while polypropylene lid margins compress under municipal straw-ban enforcement timelines.
Pricing Analysis
Coating supply agreements bundled with multi-year procurement contracts dominate pricing structures for large quick-service chains, while unbundled spot purchasing prevails among independent cafes and food trucks. Price differentiation hinges on EN 13432 certification status and PFAS-free coating portfolios demanded by EU REACH compliance. Cost compression in commodity polypropylene tiers is intensifying because legacy inventory stranding risks accelerate discounting ahead of municipal enforcement dates. Retail chains exhibit lowest price sensitivity due to volume leverage, whereas food trucks face acute margin pressure from storage constraints and variable regulatory exposure.
Supply Chain Analysis
Barrier-coating chemist scarcity in southern Germany and coastal California is constraining capacity expansion timelines for fiber-pressing facilities serving European and North American markets. Manufacturing gravity centers on Germany, Austria, and the United States, with raw material dependencies spanning agricultural pulp fiber, platinum-cured silicone, and water-based barrier formulations. Single-source vulnerability clusters with a limited set of German and Austrian mold-makers fabricating complex dome-profile tooling. Distribution runs through direct supplier relationships displacing traditional packaging intermediaries in coastal United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
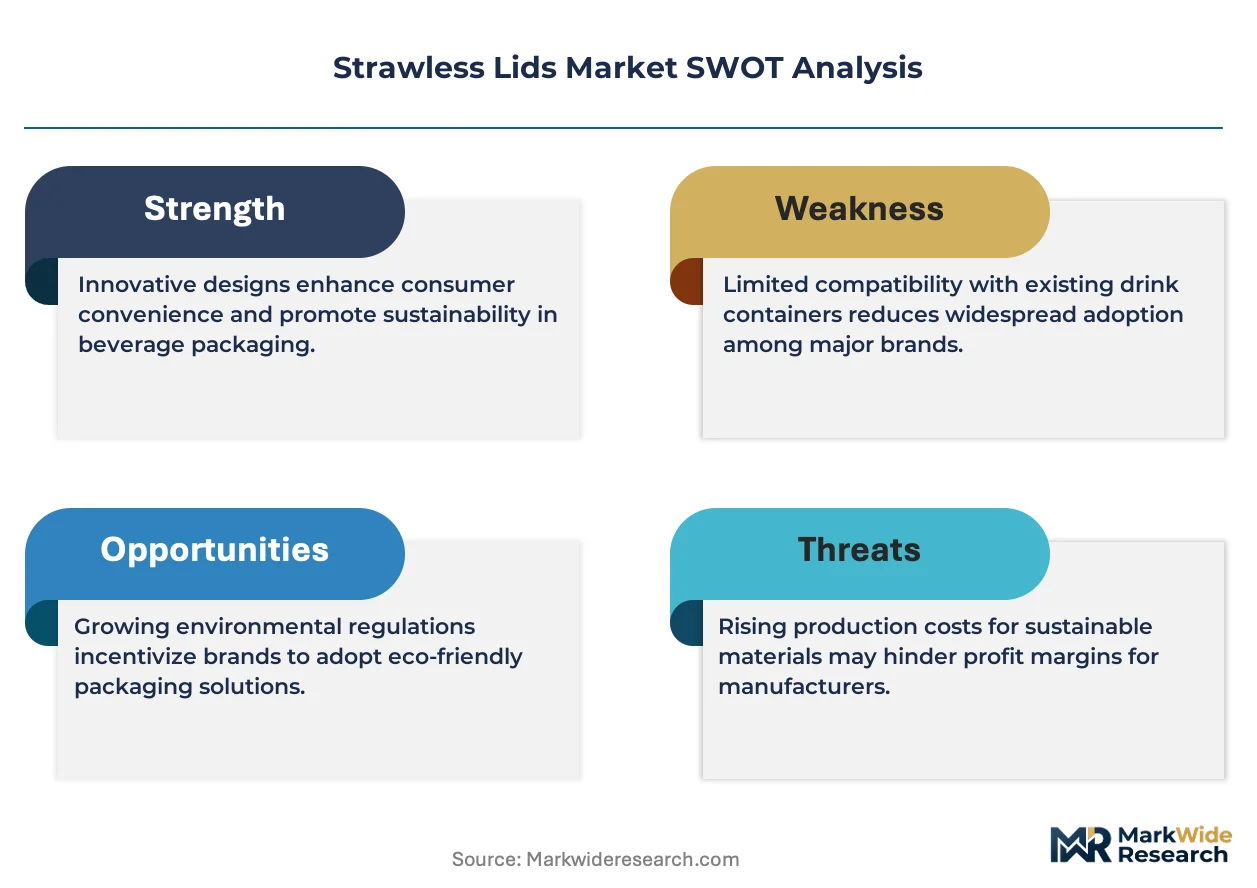
The strawless lids market functions as a regulatory compounder where EU Single-Use Plastics Directive mandates and municipal straw bans across California and New York are eliminating conventional alternatives and pulling demand toward certified formats.
For Market Incumbents: Anchor tooling library depth in German and Austrian manufacturing corridors to defend against emerging fiber-pressing specialists capturing quick-service procurement. Invest in parallel FDA and EU REACH certification portfolios to preempt multi-jurisdiction compliance stacking. Prioritize backward integration into water-based barrier coating formulation to offset chemist scarcity compressing R&D timelines. For New Entrants and Emerging Players: Silicone-modified barrier coating expertise offers entry leverage into Scandinavian reusable lid programs where deposit-return scheme expansion demonstrates viable unit economics. Target western coffeehouse format rollouts in Mumbai and Bangalore where first-mover positioning for fiber-based lids remains undercontested. Pursue direct supplier relationships bypassing traditional distribution intermediaries to capture sustainability scorecard-driven procurement in coastal United States markets. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap coating technology specialists because barrier formulation expertise concentrates with a narrow talent pool in packaging R&D functions. Long-term viability favors targets with certified PFAS-free portfolios and established EN 13432 testing relationships. Watch for acceleration in state-level packaging EPR legislation across the United States as inflection indicator for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Amcor leverages global film infrastructure to supply calibrated coatings for paper lid substrates. |
| Tooling Library Expansion | Greiner Packaging anchors European dairy accounts with deep libraries for hinged strawless formats. |
| Direct Supplier Relationship | Coastal US quick-service chains bypass distributors for multi-year coating supply agreements. |
| PFAS-Free Portfolio Certification | Los Angeles and San Francisco distributors consolidate procurement around certified portfolios. |
| Fiber-Pressing Capacity Addition | Bavarian facilities advance water-based barrier development for hot liquid containment. |
Research Methodology
Direct dialogue with foodservice procurement directors, packaging R&D leads, barrier-coating formulators, and municipal sustainability officers grounded the qualitative foundation for this analysis. Secondary validation drew from FDA food-contact substance filings, EU REACH substance restriction updates, EN 13432 certification registries, and quick-service chain sustainability reports. Bottom-up and top-down triangulation cross-checked fiber-pressing capacity announcements against thermoforming equipment installation data.
Bottom-up modeling aggregated segment-level volume assumptions across product type, material, application, and end-user dimensions, while top-down constraints calibrated aggregate market evolution across the analysis window. Growth rate derivation incorporated regulatory enforcement timelines, industrial composting infrastructure maturity curves, and quick-service chain format standardization patterns. Forecast inputs included agricultural pulp fiber price indices and water-based barrier coating formulation cost trajectories.
The model holds under steady regulatory enforcement and composting infrastructure investment; deviation in municipal ban delay or coating chemist availability would shift capacity expansion timelines. Forecasts reflect documented assumptions about fiber-pressing technology performance convergence with polypropylene. Material deviation in REACH substance restriction scope or FDA migration limit revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
India E-Commerce Packaging Market