
 India E-Commerce Logistics Market | 2026-2036
India E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Commerce Logistics Market Outlook
BIS certification for logistics service providers under warehousing and supply chain standards is redrawing competitive entry barriers. Delhivery leverages its proprietary technology stack to dominate express fulfillment across Indian pin codes. Blue Dart Express anchors premium delivery through its integrated air-ground network. Ekart Logistics sustains cost leadership via captive volumes from its parent marketplace ecosystem.
India e-commerce logistics encompasses the movement, storage, and last-mile distribution of goods ordered through digital retail platforms, typically involving automated sortation hubs operating at throughput rates exceeding 10,000 packages per hour. The sector functions as the operational backbone connecting online sellers to consumers across India's heterogeneous urban and rural terrain. Last Mile Delivery commands the largest service type share due to address density challenges and customer experience sensitivity in Indian metros. Express Shipping within delivery mode captures premium margin pools from time-sensitive categories including electronics and pharmaceuticals. Temperature-Controlled Packaging is expanding fastest among packaging types as fresh grocery and diagnostic sample volumes multiply.
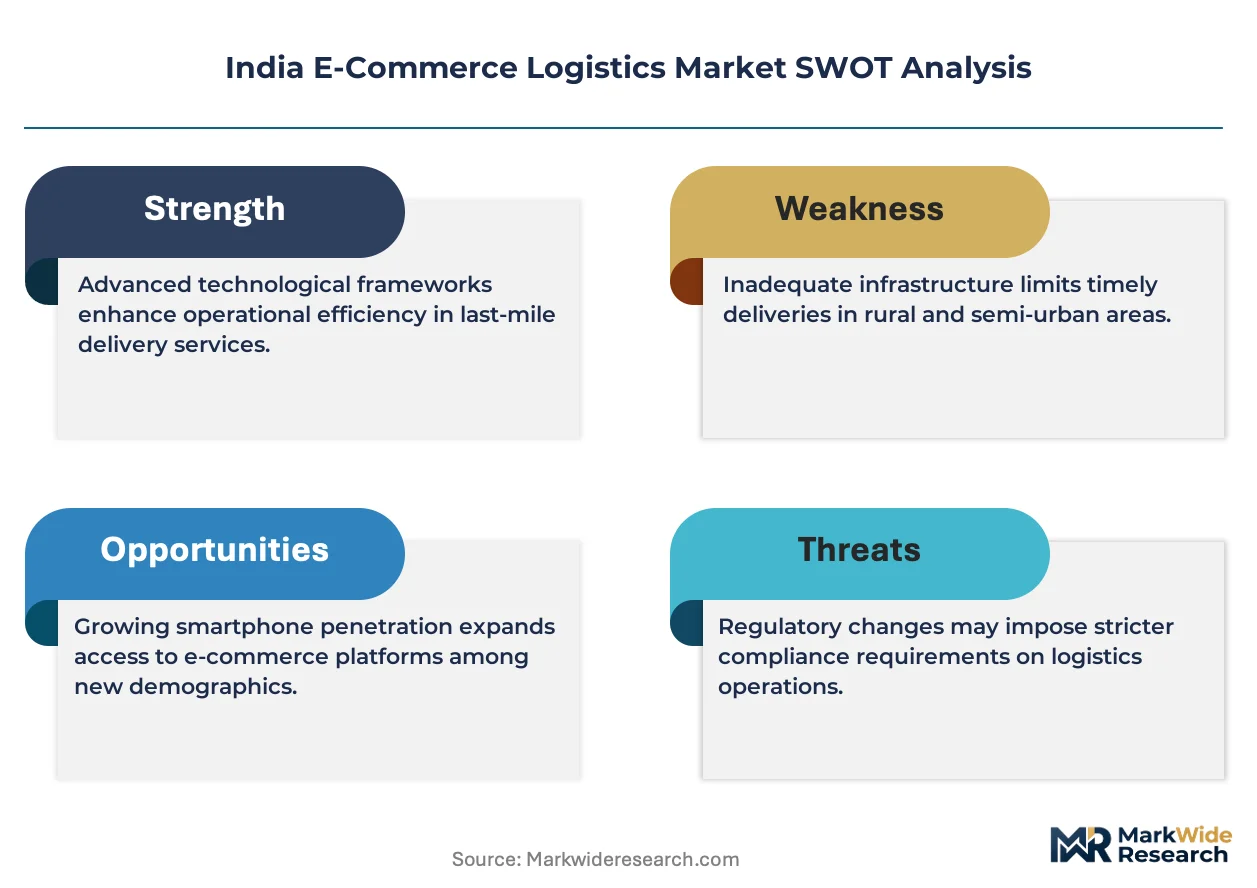
The PLI scheme administered by DPIIT incentivizes automated warehouse investments, while FSSAI mandates on temperature-controlled transit for perishable e-commerce shipments. BIS standards on packaging integrity and DGFT documentation requirements for cross-border e-commerce shape compliance costs and operational design. Stakeholders must monitor how state-level warehousing policy divergence affects network optimization decisions as fulfillment density becomes the decisive competitive variable.
Market Dynamics
The PLI scheme administered by DPIIT is compressing fulfillment center deployment timelines across Maharashtra, Karnataka, and Gujarat, forcing asset-light operators into capital partnerships or network-sharing arrangements to maintain service coverage.
Growth Catalysts
- Automated sortation infrastructure:DPIIT's PLI incentives for warehouse automation are accelerating hub throughput capabilities beyond 10,000 packages per hour, reducing per-unit handling costs for express delivery networks.
- Tier-two and tier-three city digital penetration:Consumer adoption in these geographies is expanding addressable markets beyond saturated metro corridors, creating new last-mile density pools for fulfillment operators.
- FSSAI temperature-control mandates:Regulatory requirements for perishable e-commerce shipments are standardizing cold-chain infrastructure investments, opening premium service tiers for grocery and diagnostic sample logistics.
Market Restraints
- Real estate cost escalation:Land acquisition in Mumbai, Bengaluru, and Ahmedabad fulfillment corridors is consuming disproportionate capital allocations, squeezing returns on automated warehouse investments.
- Diesel price volatility:Last-mile fleet operators face margin compression from fuel cost swings that cannot be fully passed through in competitive express delivery pricing.
- BIS certification timelines:Warehousing and supply chain standards compliance is extending facility commissioning periods, delaying revenue recognition for new capacity additions.
Strategic Opportunities
- Dark store networks in tier-two cities:Rapid commerce operators are pioneering 15-minute delivery models in Pune, Jaipur, and Lucknow, creating asset-light fulfillment templates replicable across similar density profiles.
- Reverse logistics specialization:Apparel and electronics return volumes are outpacing forward delivery growth in several categories, opening dedicated infrastructure plays for inspection and refurbishment workflows.
- DGFT cross-border documentation services:Export-oriented e-commerce sellers require integrated customs clearance and international last-mile handoffs, bundling opportunities for domestic operators with overseas partnerships.
Industry Challenges
- Sortation technician scarcity:Automated hub operations require maintenance skills combining mechanical, electrical, and software competencies that vocational training pipelines have not yet scaled to match deployment schedules.
- Legacy warehouse management system integration:Tier-two and tier-three city fulfillment partners often operate on incompatible software stacks, forcing expensive middleware development or operational workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Commerce Logistics Market |
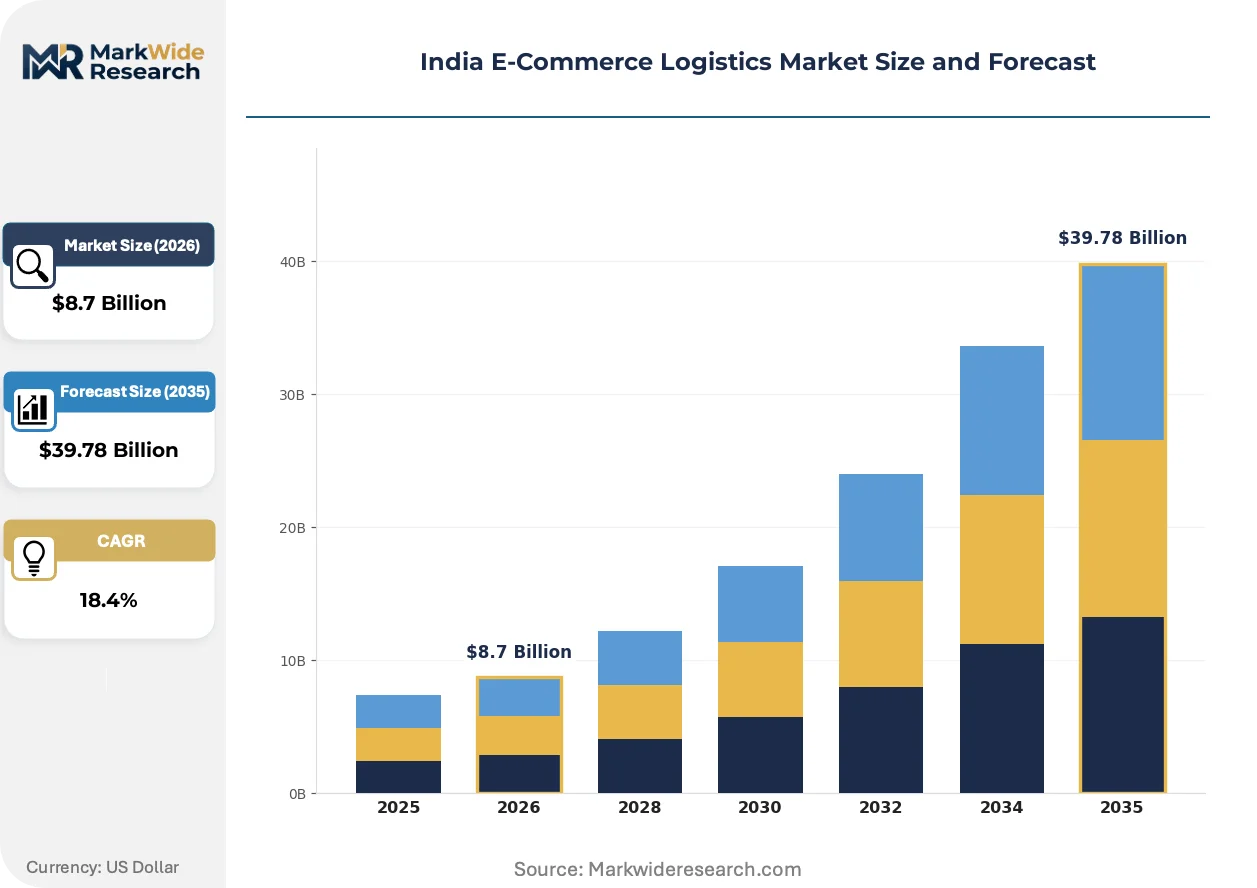
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Warehousing Solutions, Freight Forwarding, Distributed Fulfillment Delivery Mode: Express Shipping, Standard Shipping, Drone Delivery, Same Day Delivery Client Type: B2C, B2B, Marketplace, Hybrid Retail Packaging Type: Standard Packaging, Eco-Friendly Packaging, Bulk Packaging, Temperature-Controlled Packaging |
| Companies Covered | Delhivery, Ekart Logistics, XpressBees, Blue Dart Express, DTDC, Ecom Express, Shadowfax Technologies, Shiprocket, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Commerce Logistics Market Strategic Shifts
Operational technology deployment is diverging between capital-intensive automation leaders and network-optimization specialists, creating distinct competitive archetypes rather than convergent best-practice adoption.
AI-powered dynamic route optimization is fragmenting last-mile delivery economics across Indian metros. The technology ingests real-time traffic, address density, and delivery time-window constraints to generate courier sequences. Quick-commerce operators in Delhi and Hyderabad are deploying these systems at sub-10-minute recalculation intervals. Traditional express networks face margin compression as algorithmic dispatch narrows the efficiency gap between scaled incumbents and agile challengers.
BIS packaging integrity standards are mandating material specifications and stress-testing protocols for e-commerce shipments. The regulation forces substitution of conventional corrugated solutions with certified alternatives for electronics and fragile categories. Maharashtra-based fulfillment centers are responding by consolidating supplier relationships with BIS-accredited packaging converters, locking in multi-year volume commitments to secure compliance capacity.
Buyer expectations for delivery speed are compressing switching thresholds across Indian e-commerce. Same-day and next-day delivery guarantees are displacing standard 3-5 day options as the default selection in electronics and fashion categories. This behavioral shift is most pronounced in Bengaluru and Mumbai, where rapid commerce conditioning has spilled over into traditional marketplace purchase decisions, forcing inventory positioning closer to consumption endpoints.
India E-Commerce Logistics Market Segmentation
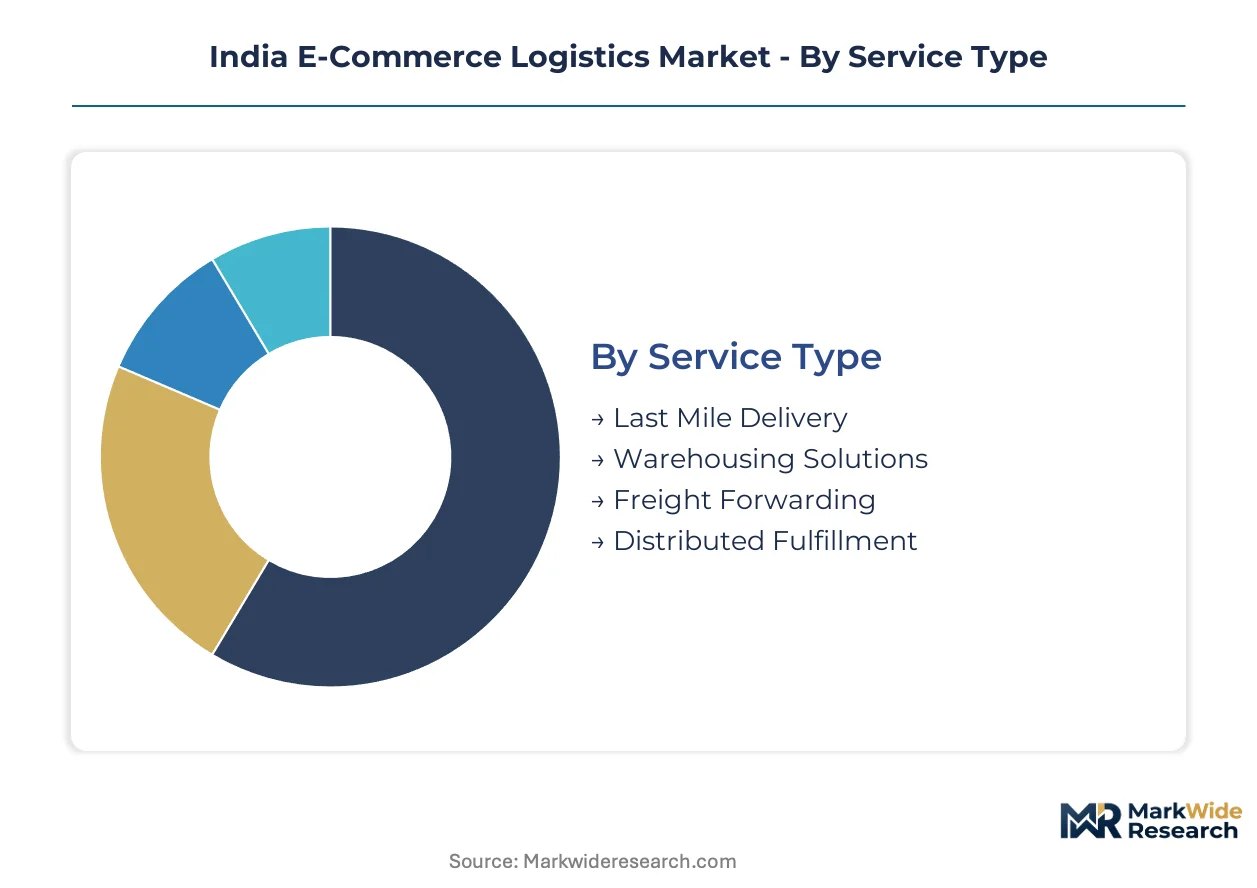
Segmentation in India e-commerce logistics reveals how operational complexity fragments across service tiers, delivery speeds, and client requirements. Each dimension carries distinct margin profiles and capital intensity thresholds that reshape competitive positioning.
Service Type:
Substitution pressure runs strongest against asset-heavy warehousing plays as network-sharing models and dark-store partnerships erode captive facility economics.
- Last Mile Delivery:Courier networks handle final-mile handoffs to residential and commercial addresses, navigating India's heterogeneous urban density and rural accessibility challenges. Maharashtra, Karnataka, and Gujarat concentrate demand where fulfillment center proximity enables sub-24-hour commitments. Address verification failures and return logistics consume disproportionate operational bandwidth.
- Warehousing Solutions:Climate-controlled storage and inventory positioning services anchor upstream supply chain control. DPIIT's PLI scheme for automated infrastructure is compressing deployment timelines, forcing asset-light operators into capital partnerships. Real estate escalation in Mumbai and Bengaluru corridors squeezes returns on automated investments.
- Freight Forwarding:Long-haul consolidation and line-haul transportation connecting sortation hubs across state boundaries.
- Distributed Fulfillment:Micro-warehouse networks positioning inventory within 10-15 kilometers of consumption endpoints for rapid commerce.
Last Mile Delivery anchors the volume base while Distributed Fulfillment gains share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium guaranteed service from economy deferred options, with algorithmic dispatch narrowing efficiency gaps between tiers.
- Express Shipping:Time-definite delivery commitments within 24-48 hours for electronics, pharmaceuticals, and high-value fashion. Bengaluru and Mumbai corridors exhibit strongest demand concentration as rapid commerce conditioning spills into traditional marketplace expectations. Premium pricing pools attract dedicated air-ground network investments.
- Standard Shipping:Deferred 3-5 day delivery windows with consolidated sorting and economy line-haul routing.
- Drone Delivery:Pilot programs in select geographies bypassing last-mile road infrastructure constraints for urgent medical and small-format shipments.
- Same Day Delivery:Inventory-proximate fulfillment enabling evening cutoff and midnight delivery guarantees in dense metro clusters.
Express Shipping commands the margin premium while Same Day Delivery climbs the fastest as consumer conditioning tightens delivery thresholds.
Client Type:
Application divergence between marketplace-captive volumes and independent merchant demand reshapes network design priorities.
- B2C:Direct-to-consumer parcel delivery serving individual online shoppers across India's tier-one through tier-three city hierarchy. Tier-two and tier-three geographies represent the fastest-expanding buyer segment as digital penetration deepens beyond saturated metro corridors. Return logistics complexity in apparel and electronics categories outpaces forward delivery growth.
- B2B:Bulk replenishment and procurement logistics serving retailers, manufacturers, and institutional buyers.
- Marketplace:Captive logistics serving parent e-commerce platforms with integrated fulfillment and exclusive service level agreements.
- Hybrid Retail:Unified inventory pools serving both online orders and physical store replenishment from common distribution nodes.
B2C anchors the volume base while Hybrid Retail gains share at the steepest rate as omnichannel integration accelerates.
Packaging Type:
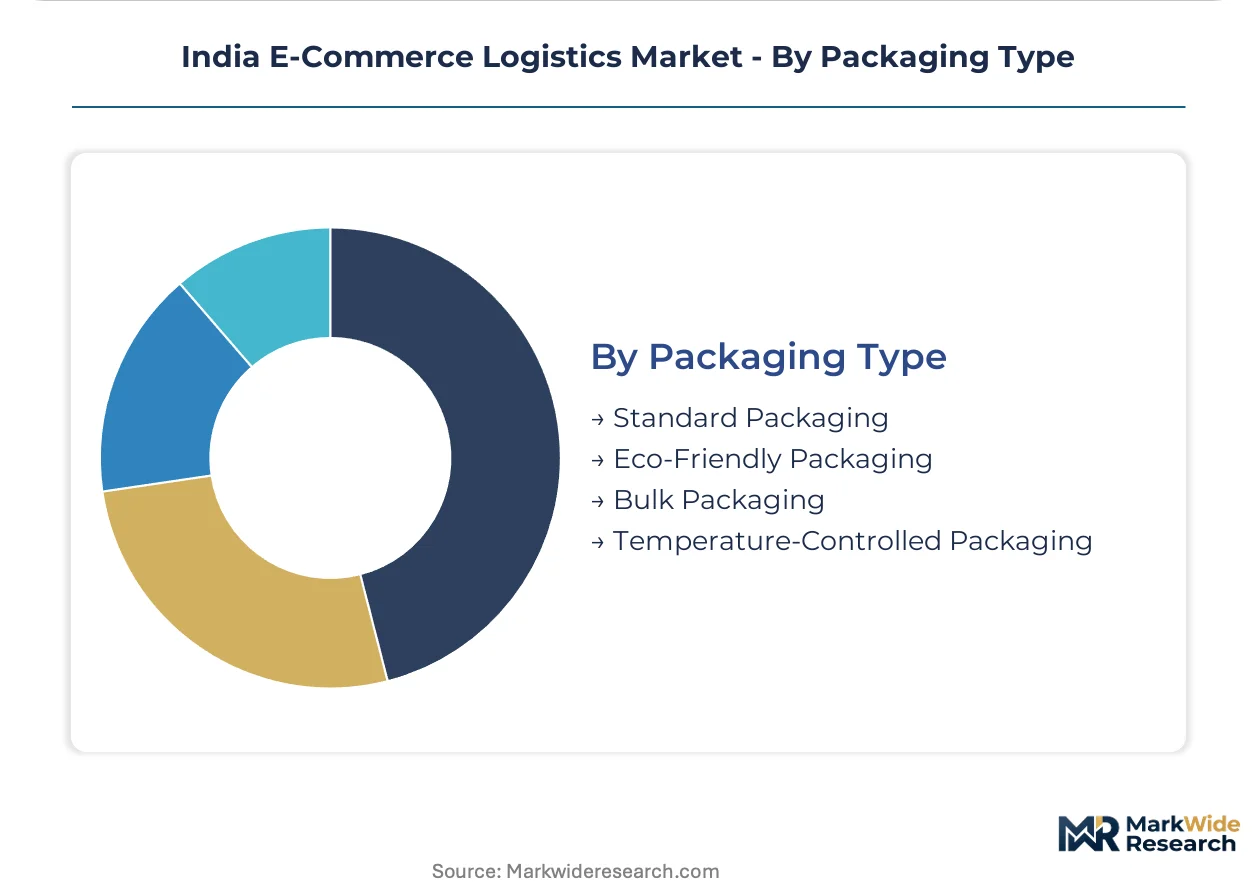
Regulatory compliance tiering under BIS standards and FSSAI mandates is forcing material substitution and certified supplier consolidation.
- Temperature-Controlled Packaging:Insulated containers and active cooling systems maintaining cold chain integrity for perishables, groceries, and diagnostic samples. FSSAI mandates on temperature-controlled transit are standardizing infrastructure investments across Maharashtra-based fulfillment centers. Fresh grocery volume multiplication drives steepest expansion trajectory among packaging categories.
- Standard Packaging:Conventional corrugated fiberboard and protective dunnage for general merchandise categories.
- Eco-Friendly Packaging:Biodegradable and recycled-content alternatives responding to sustainability procurement criteria.
- Bulk Packaging:Palletized and containerized solutions for B2B replenishment and marketplace seller consolidation.
Standard Packaging anchors the volume base while Temperature-Controlled Packaging gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor's Western and Eastern spines underwrite India's logistics backbone, compressing transit times between manufacturing clusters and consumption centers. This rail infrastructure anchors the geographic expansion of e-commerce fulfillment networks.
Maharashtra
Mumbai and Pune generate the highest express delivery volumes as rapid commerce penetration reshapes consumer expectations. The state's warehousing policy offers stamp duty exemptions for automated fulfillment centers in the Mumbai Metropolitan Region. Bhiwandi's logistics cluster hosts the densest concentration of temperature-controlled facilities serving grocery and pharmaceutical e-commerce.
Karnataka
Bengaluru's electronics manufacturing ecosystem feeds specialized reverse logistics demand for device returns and refurbishment. The state's EV policy mandates last-mile fleet electrification targets that logistics operators must integrate into capital planning. Whitefield and Electronic City sub-clusters concentrate same-day delivery infrastructure for premium electronics categories.
Gujarat
Ahmedabad and Surat anchor western India's cross-border e-commerce export processing through Mundra port connectivity. The state's industrial policy reserves land parcels for logistics parks with automated sortation specifications. Sanand's automotive manufacturing corridor is spawning dedicated B2B fulfillment networks serving component suppliers.
Telangana
Hyderabad's pharmaceutical and biotechnology base drives temperature-controlled diagnostic sample logistics volumes. The state's life sciences policy incentivizes cold-chain infrastructure investments through capital subsidies. Genome Valley's research institutions generate specialized courier demand for time-sensitive biological materials.
Delhi-NCR
The National Capital Region's consumer density supports the highest dark store deployment intensity for rapid commerce models. Haryana's warehousing policy permits floor area ratio relaxations for automated fulfillment centers in Manesar and Sonipat. Ghaziabad's logistics cluster specializes in bulky furniture and appliance last-mile delivery networks.
India E-Commerce Logistics Market Competitive Environment
Listed leaders compete with private specialists across technology investment capacity and network coverage breadth. The market structure fragments between asset-heavy integrated operators and asset-light platform aggregators. Three archetypes dominate: captive logistics arms of parent marketplaces, independent express networks with proprietary sortation infrastructure, and technology platforms aggregating fragmented carrier capacity. Capacity expansion through automated hub deployment and strategic partnerships with tier-two city fulfillment operators constitute the primary competitive vectors.
Within the integrated network tier, Delhivery and Blue Dart Express exemplify divergent scale strategies. Delhivery occupies a position as the technology-native express operator with proprietary sortation infrastructure spanning Indian pin codes. Blue Dart Express anchors premium service positioning through integrated air-ground capabilities. Ekart Logistics represents the captive logistics archetype, leveraging parent marketplace volume density to sustain cost leadership in standard delivery tiers.
| Leading Market Players |
|---|
| Delhivery |
| Ekart Logistics |
| XpressBees |
| Blue Dart Express |
| DTDC |
| Ecom Express |
| Shadowfax Technologies |
| Shiprocket |
| FedEx |
| Others |
Value Chain & Pricing Dynamics
Automated sortation equipment replacing manual hub operations is compressing per-unit handling costs while redrawing fulfillment geography toward Maharashtra, Karnataka, and Gujarat corridors where DPIIT PLI incentives accelerate deployment timelines. This capital substitution simultaneously concentrates pricing power among technology-integrated operators and squeezes asset-light competitors into network-sharing arrangements.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between marketplace platforms and logistics providers, with annual committed throughput securing preferential rates. Pricing stratifies across express, standard, and deferred tiers based on delivery speed guarantees and value-added services like temperature control. Cost compression in standard delivery is intensifying because diesel price volatility cannot be fully passed through in competitive markets. Small and medium marketplace sellers exhibit highest price sensitivity, while pharmaceutical and electronics shippers prioritize reliability over rate minimization.
Supply Chain Analysis
Inventory-strategy preferences favor distributed positioning over centralized stockpiling as same-day delivery guarantees reshape fulfillment network design. Supply draws from automated sortation hub manufacturers in China, Germany, and Japan, with domestic assembly capacity expanding in Pune and Chennai. Cold-chain packaging materials and electric last-mile vehicles represent critical input dependencies. Single-source vulnerability concentrates in specialized conveyor and robotics components. Distribution runs through multi-tier hub-and-spoke networks terminating in dark stores and micro-warehouses within 10-15 kilometers of consumption endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India e-commerce logistics market rewards operators who command scarce automation engineering capabilities and regulatory certification expertise, creating asymmetric returns for early PLI scheme beneficiaries against late adopters facing extended BIS compliance timelines.
For Market Incumbents: Fortify automated hub density in Maharashtra and Karnataka corridors before real estate escalation forecloses expansion options. Deepen backward integration into proprietary route optimization software to defend margins against algorithmic challengers. Prioritize BIS certification capacity to accelerate facility commissioning timelines as compliance bottlenecks lengthen for competitors. For New Entrants and Emerging Players: Lead with specialized reverse logistics infrastructure targeting apparel and electronics return volumes outpacing forward delivery growth. Target tier-two city dark store networks where rapid commerce models remain underpenetrated in Jaipur, Lucknow, and Indore. Pursue asset-light partnerships with existing fulfillment operators rather than greenfield capacity builds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed express networks possessing automated infrastructure but lacking captive volume density. Long-term viability hinges on integration with marketplace ecosystems or specialization in premium temperature-controlled segments. Watch for FSSAI enforcement intensity as the inflection signal separating compliant cold-chain operators from distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Hub Deployment | DPIIT PLI incentives accelerate throughput capacity beyond 10,000 packages per hour in Maharashtra clusters. |
| Dark Store Network Expansion | 15-minute delivery models in Pune and Jaipur create replicable templates for rapid commerce penetration. |
| Temperature-Controlled Infrastructure Investment | FSSAI mandates on perishable shipments standardize cold-chain capabilities for grocery and diagnostic logistics. |
| Reverse Logistics Specialization | Dedicated inspection and refurbishment workflows capture apparel and electronics return volume growth. |
| Cross-Border Documentation Services | DGFT compliance bundling opens export-oriented e-commerce seller relationships through Mundra port connectivity. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with logistics operations directors, warehouse automation engineers, marketplace supply chain managers, and last-mile fleet operators. Secondary validation drew from DPIIT PLI scheme disclosures, BIS certification registries, FSSAI compliance filings, and Dedicated Freight Corridor progress reports. Bottom-up volume modeling triangulated against top-down market sizing across service type, delivery mode, and client type segmentation dimensions.
Across the projection horizon, the analytical framework modeled segment-level growth trajectories incorporating express versus standard delivery splits, captive versus third-party logistics shares, and automated versus manual facility penetration rates. CAGRs were derived from regression analysis of historical throughput expansion correlated with e-commerce GMV growth and fulfillment center density metrics. Forecast inputs included diesel price elasticity coefficients, real estate cost indices for Mumbai and Bengaluru corridors, and PLI incentive uptake schedules.
The analysis sits within stated boundaries; outcomes outside sustained DPIIT policy continuity, stable fuel pricing regimes, or unimpeded Dedicated Freight Corridor completion would require recalibration. Forecasts reflect documented assumptions on digital penetration rates in tier-two and tier-three cities and automation capital deployment timelines. Revision becomes warranted when BIS certification backlogs or sortation technician scarcity crosses thresholds that materially delay facility commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
US Retail Logistics Market