
 India Digital Thermometer Market | 2026-2036
India Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Thermometer Market Insights
Pharmacy-led distribution is reshaping how digital thermometers reach Indian consumers, with medical supply stores and direct hospital procurement channels gaining prominence alongside e-commerce platforms. OMRON Healthcare Inc leverages its established diagnostic brand equity to sustain premium positioning across tier-1 cities. Hicks Thermometers (India) Ltd anchors its competitive stance through localized manufacturing and cost-optimized contact thermometer portfolios. Drtrust competes aggressively on online retail visibility, while BPL Medical Technologies extends its hospital equipment legacy into digital temperature monitoring systems.
Digital thermometers are electronic temperature measurement devices employing thermistors or infrared sensors to convert thermal energy into digital readouts, typically achieving accuracy within ±0.1°C and displaying results within seconds for clinical or household use. Infrared thermometers dominate pharmacy counters and airport screening stations due to non-contact hygiene protocols, while smart thermometers with Bluetooth connectivity and app integration represent the fastest-expanding margin pool among urban millennials. Contact thermometers retain volume leadership in government procurement and rural clinics where cost sensitivity prevails over feature sophistication.
CDSCO's Medical Device Rules classify digital thermometers as Class A or B devices depending on intended use, mandating ISO 13485 quality management and BIS certification for domestic sale. The PLI scheme for medical devices incentivizes local production of electronic components, reducing import dependency for sensor modules and display units. Stakeholders must monitor evolving BIS standards for wireless-enabled thermometers and anticipate state-level health mission tenders that increasingly specify connected-device compatibility for integrated patient record systems.
Market Dynamics
Pharmacy-led distribution networks and CDSCO's escalating accuracy mandates are compressing margins for unbranded imports while elevating certified domestic manufacturers into preferred supplier status across Maharashtra and Tamil Nadu procurement corridors.
Growth Catalysts
- CDSCO Medical Device Rules:Stricter Class A and B classification standards for clinical thermometers are disqualifying uncertified imports from government hospital tenders.
- Home care expansion:Elderly households managing diabetes and hypertension in urban Maharashtra are purchasing secondary temperature monitoring devices for bedroom use.
- Infrared sensor adoption:Non-contact thermometry protocols adopted by airport health screening stations and corporate campuses are normalizing premium device expectations among institutional buyers.
Market Restraints
- Import dependency for sensor modules:Thermistor and infrared sensor supply concentrates among East Asian component suppliers, exposing assemblers to currency volatility and shipping delays.
- Price ceiling in rural clinics:Contact thermometer procurement budgets under National Health Mission tenders cap unit prices below the threshold for Bluetooth-enabled or app-integrated alternatives.
- Mercury thermometer residual stock:Unregistered traditional devices continue circulating in unorganized retail channels, particularly in tier-3 towns with weaker BIS enforcement.
Strategic Opportunities
- PLI scheme localization:Production-linked incentives for medical device electronics are enabling domestic sensor module manufacturing, reducing import bills for display units and PCB assemblies.
- Telemedicine integration:Connected thermometers transmitting readings to electronic health records are capturing interest from hospital chains building remote patient monitoring infrastructure.
- Tamil Nadu manufacturing clusters:Medical device special economic zones around Chennai and Coimbatore offer consolidated component sourcing and testing facilities for export-oriented production.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for CDSCO compliance typically require twelve to eighteen months, delaying market entry for new domestic entrants.
- Wireless BIS standard evolution:Draft specifications for Bluetooth-enabled thermometers remain under committee review, creating uncertainty for product development roadmaps among electronics assemblers.
- Legacy health record integration:Hospital information systems in tier-2 cities operate on fragmented software platforms, complicating API standardization for connected device data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Thermometer Market |
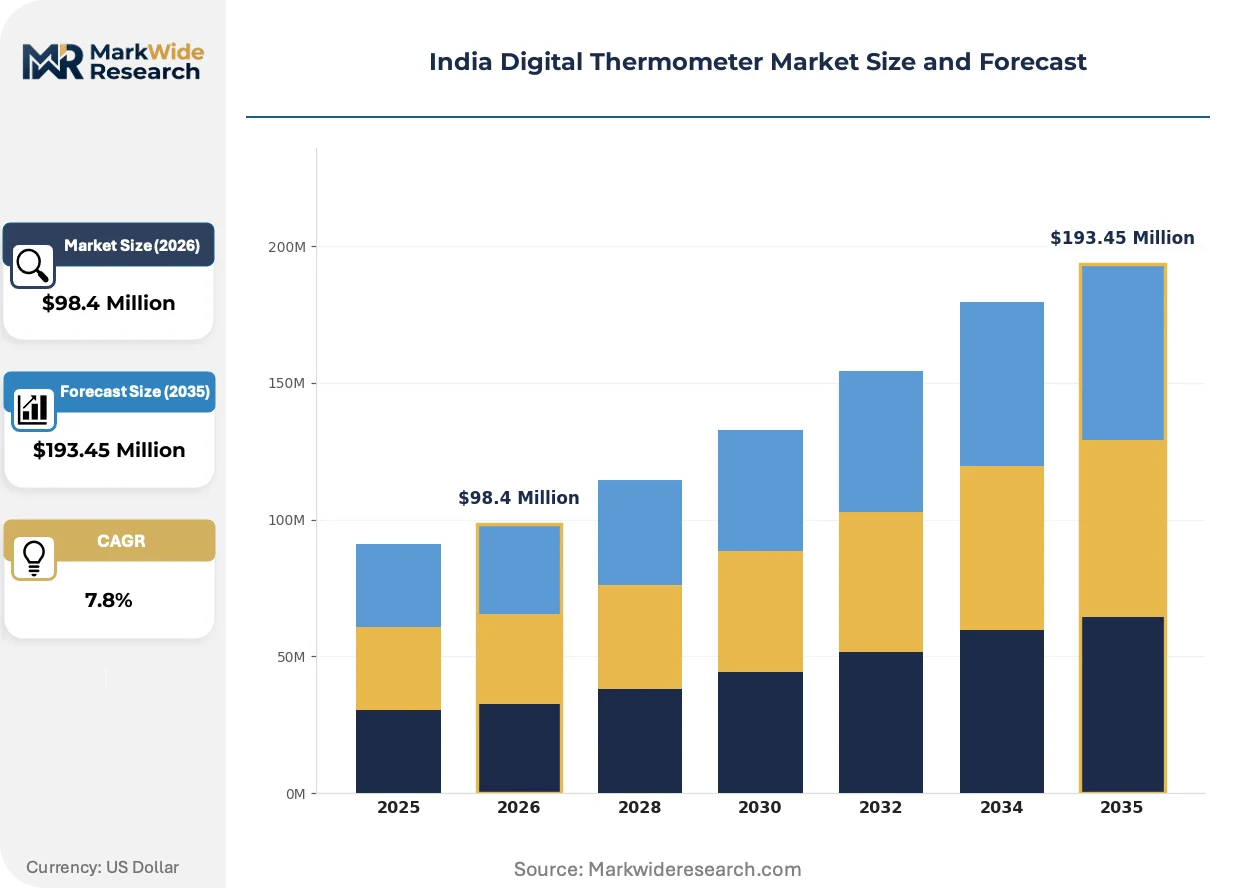
| Market Size in 2026 | $98.4 Million |
| Market Size in 2035 | $193.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Thermometers, Contact Thermometers, Smart Thermometers, Multi-Functional Thermometers End User: Hospitals, Home Care, Clinics, Pharmacies Temperature Measurement Range: Low-Grade Fever, Moderate Fever, High Fever, Hyperthermia Distribution Channel: Online Retail, Offline Retail, Medical Supply Stores, Direct Sales |
| Companies Covered | Microlife Corporation, Hicks Thermometers (India) Ltd, OMRON Healthcare Inc, Koninklijke Philips N.V., BPL Medical Technologies, Thermo Fisher Scientific Inc, Drtrust, Abbott, Braun GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Thermometer Market Trends and Innovations
Sensor miniaturization and connectivity protocols are converging to transform digital thermometers from isolated measurement tools into nodes within integrated health monitoring ecosystems.
Infrared array sensors capable of multi-point temperature mapping are rendering obsolete single-spot forehead thermometers in high-throughput screening environments. Corporate campuses and educational institutions in Bengaluru and Hyderabad are deploying these devices at building entrances. The technology is compressing the addressable market for basic non-contact models while expanding service revenue streams for calibration and fleet management.
CDSCO's draft guidance on software-as-a-medical-device is compelling thermometer manufacturers to validate mobile application algorithms for fever trend analysis and medication reminders. This regulatory expansion is extending quality management obligations beyond hardware assembly into cloud infrastructure and data security protocols. Hospital procurement teams in Mumbai and Delhi are beginning to specify SaMD compliance in connected device tenders.
Direct-to-patient subscription models bundling thermometers with teleconsultation access are disrupting pharmacy-centric distribution in metropolitan markets. Startups partnering with diagnostic chains are offering monthly plans targeting chronic disease households in Pune and Chennai. This channel innovation is reducing working capital requirements for inventory stocking while capturing recurring revenue from health-conscious consumer segments.
India Digital Thermometer Market Segmentation
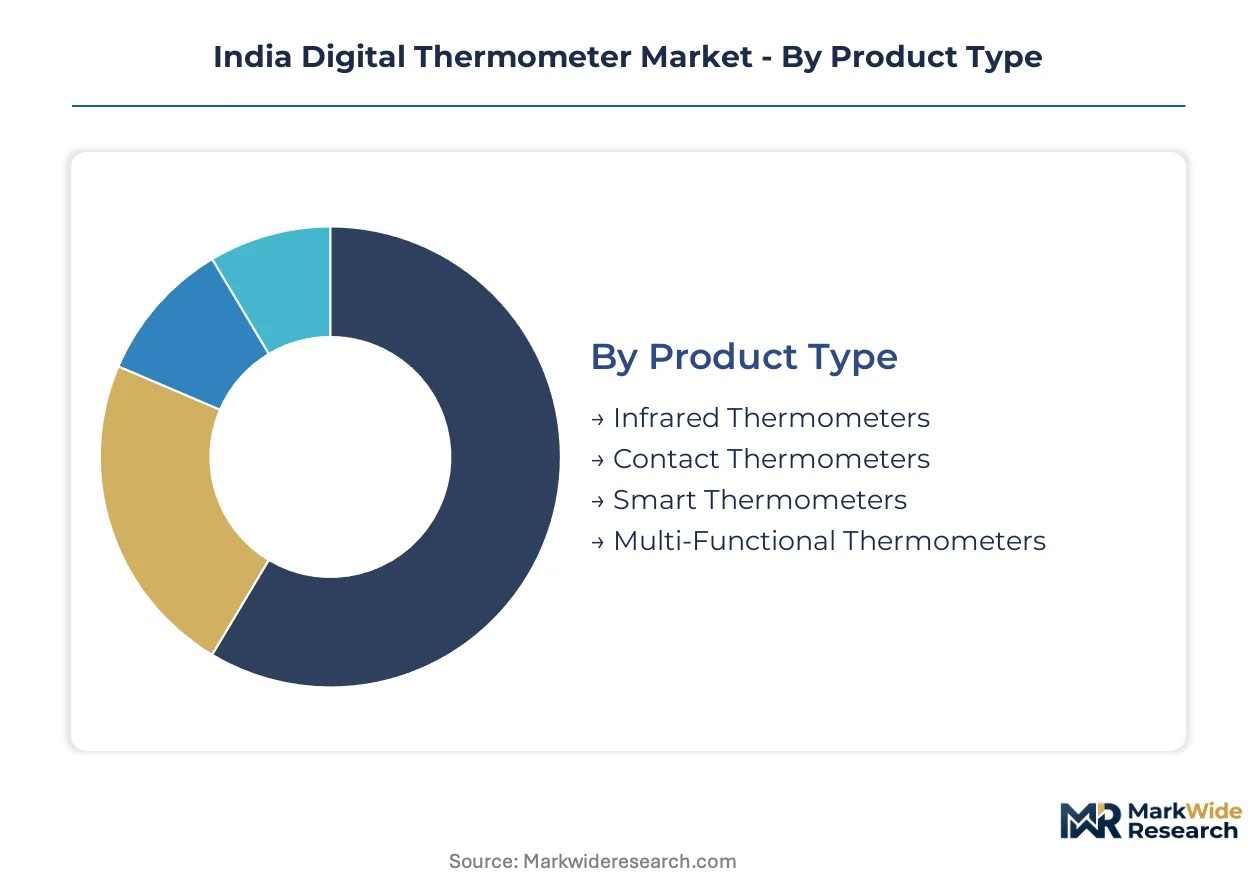
Digital thermometer demand fragments across four intersecting dimensions in India. Product specifications diverge sharply between institutional procurement and household purchase patterns. End-user requirements shape everything from sensor accuracy tolerances to connectivity protocols.
Product Type:
Use-case spectrum spans from basic clinical compliance to connected health ecosystems, with each product category serving distinct temperature monitoring workflows across Maharashtra's hospital corridors and Tamil Nadu's manufacturing clusters.
- Infrared Thermometers:Non-contact devices deploy thermopile or pyroelectric sensors measuring infrared radiation emitted from the forehead or ear canal. Airport health screening stations and corporate campuses in Bengaluru and Hyderabad have normalized these devices for high-throughput hygiene protocols. CDSCO's Class B classification for clinical-grade units mandates stricter calibration documentation than household variants.
- Contact Thermometers:Thermistor-based probes require physical placement under the tongue, in the armpit, or rectally for pediatric applications. National Health Mission tenders for rural clinics in Uttar Pradesh and Bihar specify these units exclusively due to sub-INR 500 price ceilings that exclude sensor sophistication.
- Smart Thermometers:Bluetooth-enabled devices transmitting readings to mobile applications for fever trend logging. Urban millennials in Pune and Chennai drive demand for subscription-bundled models paired with teleconsultation access.
- Multi-Functional Thermometers:Hybrid devices combining infrared surface scanning with contact probe modes for versatile household deployment. Secondary bedroom units purchased by elderly diabetes households in Mumbai's suburban corridors favor this flexibility.
The dominant share belongs to Contact Thermometers, while Smart Thermometers are gaining share fastest among metropolitan chronic disease managers.
End User:
Procurement authority concentrates differently across customer types, with institutional buyers prioritizing ISO 13485 certification and households responding to pharmacy counter visibility and app ecosystem integration.
- Hospitals:Tertiary care centers in Delhi and Mumbai require Class B certified units with centralized calibration records and EMR integration capability. CDSCO audits for these installations demand twelve-to-eighteen-month quality system documentation.
- Home Care:Elderly households managing hypertension and diabetes in urban Maharashtra purchase secondary monitoring devices for bedroom deployment. Direct-to-patient subscription models are disrupting pharmacy-centric distribution in this segment.
- Clinics:Primary health centers under state health missions operate under rigid price ceilings that exclude Bluetooth-enabled alternatives. Tamil Nadu's government procurement corridors favor domestically assembled contact units.
- Pharmacies:Retail medical stores function as the dominant distribution node for household purchasers, with counter placement driving brand recognition for OMRON and Drtrust portfolios.
Hospitals command the premium tier by certification requirements, though Home Care is expanding most quickly through chronic disease demographic shifts.
Temperature Measurement Range:
Clinical severity thresholds determine sensor accuracy specifications and alarm functionality, with hyperthermia detection requiring the most precise thermistor calibration.
- Low-Grade Fever:Readings between 37.5°C and 38.0°C trigger early monitoring protocols in pediatric and geriatric populations. Household devices in Chennai's suburban markets emphasize gentle alert tones for overnight use.
- Moderate Fever:The 38.0°C to 39.0°C band drives the majority of clinical consultations and medication decisions. Pharmacy-sold units optimize display clarity for this diagnostic threshold.
- High Fever:Measurements exceeding 39.0°C activate urgent care referral protocols in hospital emergency departments. Rapid-read infrared arrays in Bengaluru corporate campuses flag these thresholds for security personnel intervention.
- Hyperthermia:Critical temperatures above 40.0°C demand immediate medical intervention with continuous monitoring. ICU-grade contact probes in Mumbai's tertiary centers maintain ±0.1°C accuracy across this range.
Moderate Fever detection dominates unit volume, while Hyperthermia monitoring carries the steepest expansion trajectory in critical care infrastructure builds.
Distribution Channel:
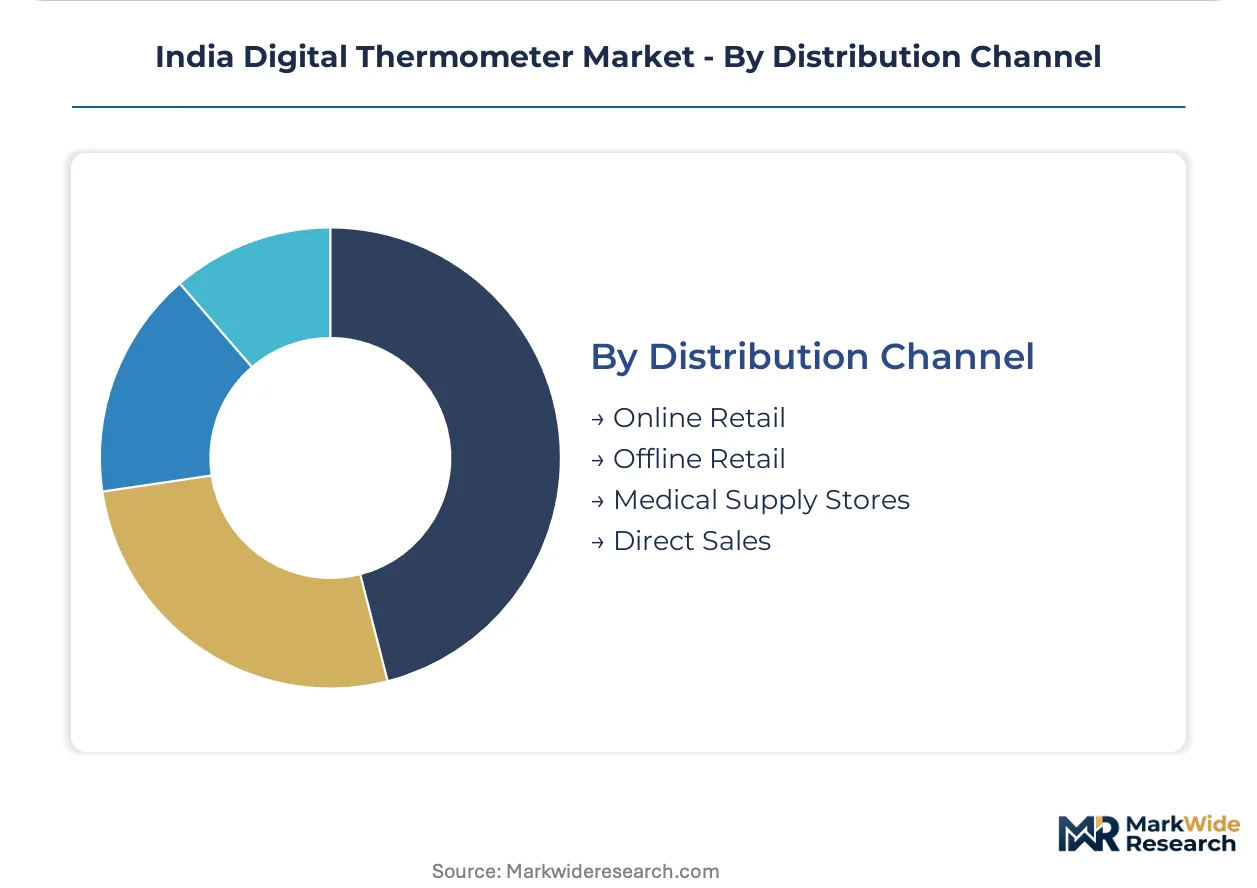
Channel selection reflects purchase urgency, technical consultation needs, and integration complexity, with offline retail retaining volume leadership despite e-commerce visibility gains.
- Online Retail:Amazon India and Flipkart host aggressive price competition for branded household units, with Drtrust leveraging search optimization for visibility. Return policies and review systems reduce perceived risk for first-time smart thermometer purchasers.
- Offline Retail:General electronics stores and supermarket health sections serve impulse purchasers and gift buyers. Tier-2 city consumers in Gujarat and Rajasthan prefer physical inspection before committing.
- Medical Supply Stores:Specialized distributors dominate institutional procurement for hospitals and clinics, offering calibration certificates and bulk pricing. Maharashtra's urban healthcare corridors concentrate these intermediaries.
- Direct Sales:Hospital equipment manufacturers like BPL Medical Technologies bypass distribution margins for large tender fulfillment. Tamil Nadu's medical device SEZs enable factory-direct export shipments.
Medical Supply Stores anchor institutional procurement, though Online Retail is climbing the fastest among metropolitan millennials seeking connected-device bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing for Class B certified thermometers while Uttar Pradesh operates under rigid National Health Mission price ceilings, creating a two-tier procurement landscape across Indian states.
Maharashtra
Mumbai's tertiary care hospitals drive demand for EMR-integrated infrared arrays with centralized calibration documentation. CDSCO's Class B audits for these installations require twelve-to-eighteen-month quality system records. Pune's chronic disease households are adopting subscription-bundled smart thermometers paired with teleconsultation platforms.
Tamil Nadu
Chennai's medical device special economic zones offer consolidated component sourcing for export-oriented thermometer production. The state's PLI scheme beneficiaries are localizing sensor module manufacturing to reduce import dependency. Coimbatore's testing facilities serve domestic assemblers seeking BIS certification for wireless-enabled devices.
Karnataka
Bengaluru's corporate campuses deploy infrared array sensors at building entrances for high-throughput health screening. The state's software-as-a-medical-device startups are validating mobile application algorithms for fever trend analysis. Hyderabad's educational institutions are normalizing premium non-contact thermometry protocols among institutional buyers.
Uttar Pradesh
Primary health centers under the National Health Mission specify contact thermometers exclusively due to sub-INR 500 procurement ceilings. BIS enforcement remains weaker in tier-3 towns where unregistered mercury devices circulate. Lucknow's government medical colleges train procurement officers on CDSCO classification standards for clinical-grade units.
Gujarat
Ahmedabad's pharmacy distribution networks anchor retail visibility for branded household thermometers. The state's electronics manufacturing clusters are attracting PLI scheme investment for PCB assembly localization. Surat's general electronics stores serve impulse purchasers preferring physical inspection before committing to connected-device purchases.
India Digital Thermometer Market Competitive Landscape
Diagnostic multinationals and domestic cost-optimized assemblers split the market between premium certification-heavy hospital tenders and price-capped government procurement corridors. The vendor base concentrates around three strategic archetypes: established diagnostic brands leveraging hospital equipment legacies, localized manufacturers exploiting Tamil Nadu component clusters, and online-native retailers capturing metropolitan millennial demand. Dominant competitive moves include PLI scheme-driven backward integration into sensor module production and subscription-based direct-to-patient models disrupting pharmacy-centric distribution.
Within the premium diagnostic tier, OMRON Healthcare Inc and Koninklijke Philips N.V. occupy positions shaped by established brand equity across tier-1 city hospital corridors. Hicks Thermometers (India) Ltd exemplifies the localized manufacturing archetype through its cost-optimized contact thermometer portfolios. Drtrust represents the online-native competitive vector, competing aggressively on e-commerce platform visibility among metropolitan chronic disease households.
| Leading Market Players |
|---|
| Microlife Corporation |
| Hicks Thermometers (India) Ltd |
| OMRON Healthcare Inc |
| Koninklijke Philips N.V. |
| BPL Medical Technologies |
| Thermo Fisher Scientific Inc |
| Drtrust |
| Abbott |
| Braun GmbH |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic sensor module fabrication is compressing assembler margins while elevating landed costs for East Asian thermistor imports, forcing pricing discipline across Maharashtra's hospital procurement corridors and Tamil Nadu's manufacturing clusters.
Pricing Analysis
The customization-premium spread between configured-to-order EMR-integrated units and standard contact thermometers spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CDSCO Class B certification status and ISO 13485 documentation depth. Cost compression in economy-tier contact units is intensifying because National Health Mission tenders enforce sub-INR 500 price ceilings. Rural clinics under state health missions exhibit the highest price sensitivity, while Mumbai's tertiary care hospitals purchasing infrared arrays with calibration records show the least.
Supply Chain Analysis
Contract-manufacturing concentration rests with domestic EMS providers in Tamil Nadu's medical device SEZs and specialized PCB assemblers in Gujarat's electronics corridors. Geographic supply concentration draws from China for thermopile sensors, Taiwan for display driver ICs, and South Korea for Bluetooth modules. Raw material dependencies center on infrared thermopiles, medical-grade thermistors, and lithium coin cells. Single-source vulnerability for thermopile arrays from East Asian suppliers exposes assemblers to currency volatility. Distribution runs through medical supply stores anchoring institutional procurement and e-commerce platforms capturing metropolitan household demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's digital thermometer market represents an early-cycle expansion story as chronic disease households in urban Maharashtra adopt secondary monitoring devices faster than supply-side certification capacity can expand.
For Market Incumbents: Insulate hospital equipment legacies by accelerating ISO 13485 certification timelines for connected-device portfolios before CDSCO's software-as-a-medical-device guidance hardens. Deepen backward integration into sensor module production through PLI scheme incentives to reduce exposure to East Asian component volatility. Channel control through exclusive medical supply store partnerships defends against online-native entrants capturing metropolitan subscription demand.
For New Entrants and Emerging Players: Build out direct-to-patient subscription models bundling thermometers with teleconsultation access, targeting chronic disease households in Pune and Chennai where pharmacy-centric distribution remains underdeveloped. Penetrate the smart thermometer segment among urban millennials through app ecosystem integration rather than hardware differentiation. Pursue white-label manufacturing partnerships with Tamil Nadu SEZ assemblers to bypass eighteen-month certification timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic-care infrastructure play because household penetration of connected monitoring devices trails clinical adoption by a wide margin. Acquisition targets should emphasize domestic assemblers with PLI scheme approvals and existing BIS certification for wireless-enabled devices. Monitor state-level health mission tender specifications for connected-device compatibility as the inflection signal for telemedicine-integrated demand.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class B Certification Investment | Quality system documentation unlocks government hospital tenders in Maharashtra and Delhi corridors. |
| PLI Scheme Sensor Localization | Domestic thermopile production reduces import dependency and currency exposure for Tamil Nadu assemblers. |
| Software-as-a-Medical-Device Validation | Mobile application algorithms for fever trend analysis extend quality obligations into cloud infrastructure. |
| Direct-to-Patient Subscription Launch | Recurring revenue models disrupt pharmacy-centric distribution in metropolitan chronic disease markets. |
| EMR Integration Partnership | Hospital information system APIs enable connected thermometer data feeds for Mumbai tertiary care chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers at tertiary care centers, CDSCO regulatory affairs specialists, and medical supply store distributors across Maharashtra and Tamil Nadu. Secondary validation drew from CDSCO Medical Device Rules filings, BIS certification databases, National Health Mission tender documentation, and PLI scheme beneficiary disclosures. Bottom-up unit shipment estimates from state-level procurement data were triangulated against top-down market sizing from component import records.
Calibration against historical price trajectories in medical device electronics anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, temperature measurement range, and distribution channel, with additional cross-cutting analysis on certification tier and connectivity protocol adoption. CAGRs were derived from regression analysis of procurement volume trends and demographic penetration curves for chronic disease households. Forecast inputs incorporated PLI scheme capacity buildout timelines and evolving BIS standards for wireless-enabled devices.
Stress conditions across sensor module supply disruptions, CDSCO audit timeline extensions, and state health mission budget reallocations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on chronic disease prevalence growth and telemedicine infrastructure investment. Quarterly review of state tender specifications and PLI scheme utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Exhaust Sensors Market