
 GPU Virtualization Market | 2026-2036
GPU Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
GPU Virtualization Market Foresight
GPU-as-a-service leasing and project finance is fragmenting competitive dynamics by lowering capital barriers for mid-scale entrants. CoreWeave leverages specialized NVIDIA infrastructure to anchor its position in generative AI training workloads. Microsoft Azure sustains broad enterprise reach through integrated software stacks. Lambda Labs differentiates via researcher-centric pricing and direct hardware access models.
GPU virtualization partitions physical graphics processing units into multiple virtual instances, enabling concurrent execution through PCI passthrough, SR-IOV, or time-sliced scheduling with memory isolation down to the frame buffer level. Its primary purpose is to democratize accelerated compute for workloads ranging from real-time rendering to neural network training without dedicated hardware ownership. VGPU technology leads deployment volumes among technology segments, while machine learning applications within the application dimension command the deepest customer commitment and longest contract terms. Public cloud deployment models capture the majority of new capacity additions, though hybrid configurations are gaining traction among enterprises with latency-sensitive inference pipelines.
FCC spectrum allocations and data center energy regulations in the United States, alongside EU GDPR data residency requirements and the EU AI Act risk classification framework, are reshaping where GPU clusters may legally operate and how customer data must traverse virtualized boundaries. ISO/IEC 27001 and SOC 2 Type II certifications increasingly function as table stakes for vendor selection in regulated industries. Stakeholders must weigh sovereign cloud mandates against the latency economics of centralized GPU pools when designing procurement strategies.
Market Dynamics
GPU virtualization is fragmenting capital allocation patterns as hyperscalers and specialized providers compete for finite NVIDIA supply, while the EU AI Act forces architectural decisions about data residency and workload placement.
Growth Catalysts
- EU AI Act risk classification:Tiered compliance requirements are pushing enterprises toward virtualized GPU pools that can demonstrate auditable isolation and geographic containment for high-risk AI systems.
- Machine learning inference pipelines:Real-time model serving demands are expanding addressable workloads beyond training into persistent, latency-optimized virtualized instances.
- Northern Virginia data center cluster:Concentrated fiber and power infrastructure is attracting multi-tenant GPU facilities that achieve economies unreachable in distributed deployments.
Market Restraints
- NVIDIA supply concentration:Foundry capacity constraints at TSMC and packaging bottlenecks limit physical GPU availability, capping virtualization layer expansion regardless of software demand.
- GDPR data residency friction:Cross-border virtual machine migration triggers complex legal reviews that lengthen procurement cycles and reduce operational flexibility for multinational deployments.
- Memory bandwidth ceiling:PCIe Gen4/Gen5 interconnect saturation creates hard performance cliffs for memory-intensive workloads that cannot be fully masked by scheduling algorithms.
Strategic Opportunities
- India BIS certification pathway:Domestic data localization mandates under the Digital Personal Data Protection Act are creating sovereign cloud requirements that favor local GPU virtualization infrastructure.
- Edge inference convergence:5G network slicing combined with containerized GPU runtimes is opening distributed inference nodes that bypass centralized cloud latency penalties.
- ISO/IEC 27001 automation:Automated compliance tooling for virtualized environments is reducing certification timelines from months to weeks, accelerating regulated industry penetration.
Industry Challenges
- CUDA optimization expertise scarcity:Deep familiarity with NVIDIA's proprietary stack remains concentrated among a narrow talent pool, inflating implementation costs and project risk.
- Legacy virtualization stack integration:VMware and Hyper-V environments require complex driver certification cycles that delay new GPU generation support by 6-12 months.
- Multi-tenant security isolation:Side-channel vulnerabilities in shared GPU memory architectures demand continuous microcode and hypervisor patching that strains operational teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPU Virtualization Market |
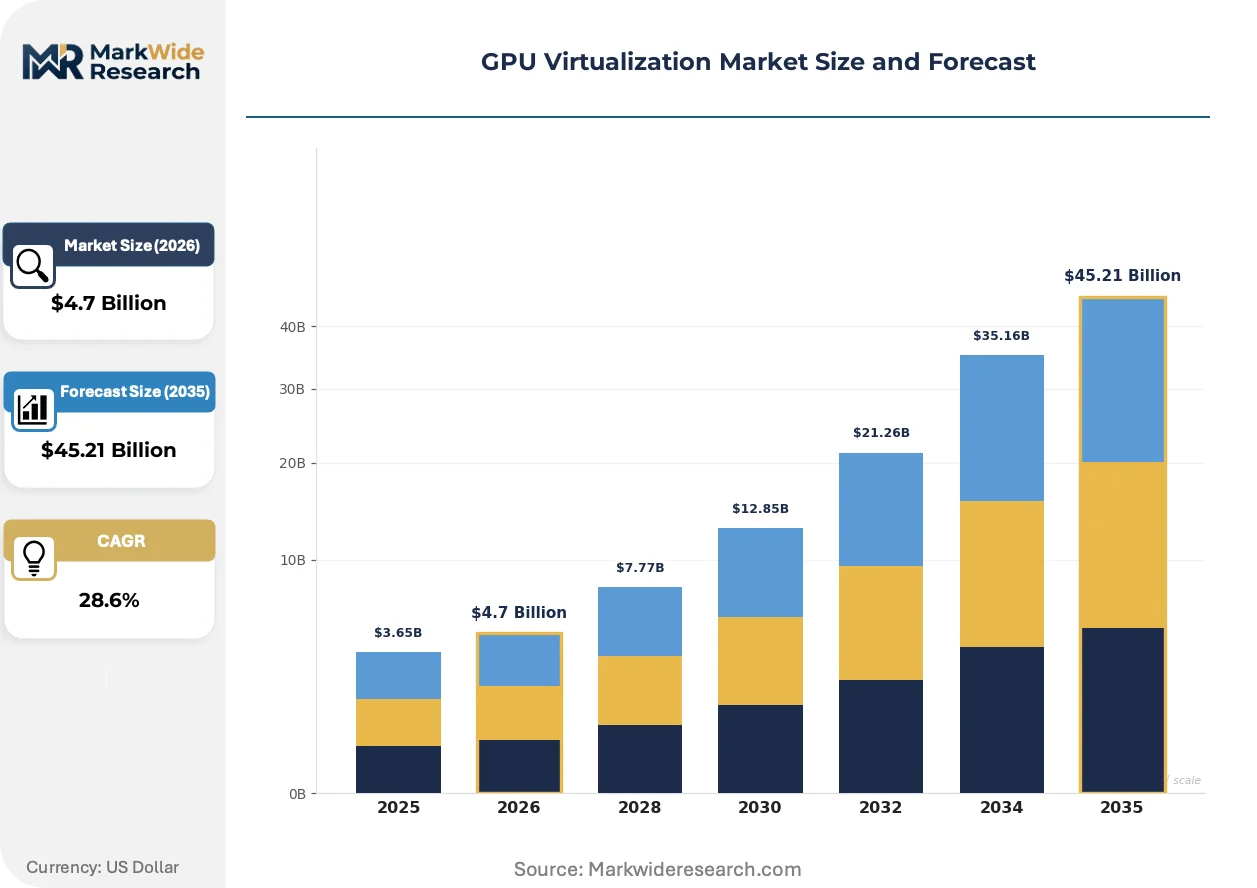
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VGPU, Software GPU, Hardware GPU, Virtual Machine End User: Data Centers, Cloud Providers, Enterprises, Educational Institutions Application: Gaming, Machine Learning, Data Visualization, Graphic Rendering Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | CoreWeave, RunPod, Amazon Web Services (AWS), Oracle Cloud Infrastructure, Lambda Labs, Microsoft Azure, NVIDIA DGX Cloud, Paperspace, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPU Virtualization Market Shifts & Advancements
Software-defined partitioning is displacing hardware-bound allocation models, while regulatory pressure and procurement rationalization are forcing architectural decisions that favor flexibility over peak performance.
Multi-instance GPU technology is virtualizing physical silicon into seven isolated partitions with dedicated memory and compute resources. Financial services firms and healthcare AI developers are adopting this for production inference workloads that demand guaranteed quality-of-service. The approach is virtualizing what previously required discrete hardware, collapsing cost structures for mid-scale deployments.
The EU AI Act's risk classification framework is mandating technical documentation and conformity assessments for high-risk AI systems. Providers must now demonstrate that virtualized environments maintain audit trails and data isolation across tenant boundaries. European enterprises are responding by procuring certified sovereign cloud instances rather than standard public cloud GPU pools.
Consumption-based leasing models are displacing reserved instance commitments for variable training workloads. Research institutions and venture-backed startups are gravitating toward hourly billing with preemption rights rather than multi-year contracts. This pattern is most pronounced in the United States, where project finance vehicles have proliferated to underwrite fleet expansion without traditional corporate balance sheet capacity.
GPU Virtualization Market Segmentation
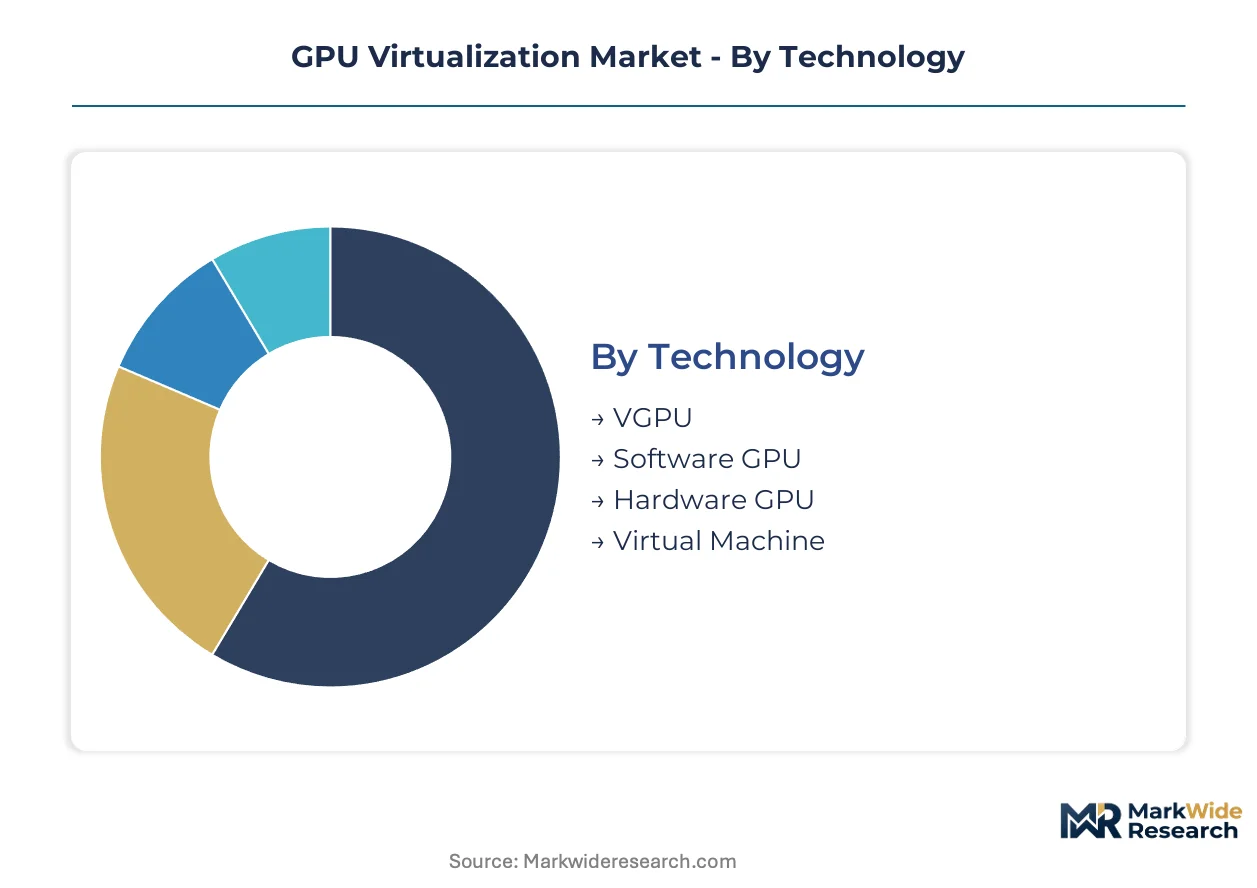
GPU virtualization segments exhibit divergent capital cycle patterns. Technology layers refresh on 18-24 month silicon cadences while deployment models lock in 3-5 year infrastructure commitments. Understanding these temporal mismatches informs procurement timing and vendor negotiation leverage.
Technology:
VGPU turns over fastest at the software layer, while hardware-bound alternatives require longer depreciation cycles and foundry-dependent refresh timelines.
- VGPU:Software-based partitioning creates virtual GPU instances through hypervisor-mediated resource allocation without physical silicon modification. Financial services firms in New York and London deploy this for risk-modeling workloads requiring rapid instance scaling under Basel III stress-testing deadlines.
- Hardware GPU:Physical silicon with firmware-level virtualization support enables bare-metal performance guarantees for latency-sensitive inference. Northern Virginia hyperscaler campuses favor this for generative AI training clusters where memory bandwidth saturation determines model convergence times.
- Software GPU:API abstraction layers emulate GPU functionality on standard compute, sacrificing performance for compatibility in legacy application migration scenarios.
- Virtual Machine:Full-stack virtualization encapsulates GPU drivers within guest operating systems, extending support to unmodified applications at the cost of 15-30% overhead.
VGPU dominates installed base. Hardware GPU is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive infrastructure owners from consumption-based service buyers.
- Cloud Providers:Multi-tenant platforms aggregate GPU capacity into metered services, achieving utilization rates above 70% through statistical multiplexing. AWS, Azure, and Google Cloud regions in Oregon, Iowa, and Belgium anchor procurement volumes as these operators negotiate directly with NVIDIA for H100 allocation priority.
- Data Centers:Colocation and wholesale facilities install GPU-ready power and cooling infrastructure ahead of tenant demand, capturing rent premiums for certified AI-ready white space. Frankfurt and Singapore facilities lead European and Asian deployment respectively.
- Enterprises:Corporate IT organizations balance sovereignty requirements against cloud economics, with hybrid configurations gaining traction among EU-regulated entities.
- Educational Institutions:Universities and research consortia access GPU resources through NSF, Horizon Europe, and national supercomputing allocations rather than commercial procurement.
Cloud providers dominate installed base. Data centers are where expansion concentrates.
Application:
Volume concentration varies by workload persistence, with training tasks demanding continuous allocation and inference permitting granular time-slicing.
- Machine Learning:Neural network training and model serving consume the majority of allocated GPU cycles, with transformer architectures driving memory capacity requirements beyond 80GB per device. Healthcare AI developers at Mayo Clinic and NHS trusts deploy virtualized pools for diagnostic imaging workloads under HIPAA and GDPR constraints.
- Gaming:Cloud gaming services stream rendered frames to thin clients, requiring sub-50ms latency that constrains data center placement to metro-proximate edge nodes. GeForce NOW infrastructure in California and Tokyo exemplifies this geographic tethering.
- Graphic Rendering:Media and entertainment studios burst-render animated features through virtualized render farms, tolerating higher latency for batch processing efficiency.
- Data Visualization:Scientific computing and business intelligence applications leverage GPU acceleration for real-time dataset exploration, with lower compute intensity than ML training.
Machine learning dominates installed base. Gaming is where expansion concentrates.
Deployment Model:
Customer type determines architectural selection, with regulated industries prioritizing control and startups favoring elasticity.
- Public Cloud:Shared infrastructure delivers on-demand GPU access without capital commitment, enabling rapid experimentation. ISO/IEC 27001 and SOC 2 Type II certifications function as table stakes for vendor selection among Fortune 500 procurement teams.
- Hybrid Cloud:Split workloads place training in public cloud while retaining inference on-premises for latency compliance. German automotive manufacturers adopt this pattern to satisfy TISAX information security requirements.
- Private Cloud:Dedicated GPU clusters serve single-tenant environments with guaranteed resource isolation, commanding 40-60% premiums over public cloud equivalents.
- On-Premises:Self-managed infrastructure persists in defense, intelligence, and critical infrastructure sectors where air-gapped operation is mandatory.
Public cloud dominates installed base. Hybrid cloud is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Northern Virginia GPU clusters exceeds equivalent capacity in Frankfurt by 15-20% due to fiber density and NVIDIA allocation priority. European data centers compensate through sovereign cloud premiums tied to EU AI Act compliance.
United States
Hyperscaler campuses in Northern Virginia and Oregon absorb the majority of H100 allocations through direct NVIDIA partnerships. FCC spectrum management and FERC grid interconnection rules shape where multi-tenant GPU facilities may expand. Dallas-Fort Worth and Phoenix are emerging as secondary clusters where power costs undercut coastal metros by 30%.
Germany
Automotive AI developers in Stuttgart and Munich drive demand for TISAX-certified virtualized inference infrastructure. The EU AI Act risk classification framework mandates audit trails that favor domestic sovereign cloud deployments over standard AWS or Azure regions. Frankfurt's data center concentration now specializes in financial services GPU workloads under ECB operational resilience guidelines.
India
Domestic machine learning teams at Flipkart, Reliance Jio, and AI4Bharat are scaling training workloads that previously routed to Singapore. BIS certification requirements and Digital Personal Data Protection Act localization mandates favor local GPU-as-a-service providers over foreign hyperscalers. Mumbai and Bangalore data centers are capturing premiums for certified sovereign infrastructure.
United Kingdom
London's quantitative hedge funds and NHS AI diagnostic programs compete for A100 and H100 capacity through specialized providers. NHS information governance requirements and Financial Conduct Authority operational resilience rules restrict cross-border virtual machine migration. Slough and Docklands facilities are densifying GPU-ready power infrastructure ahead of anticipated demand from generative AI startups.
Japan
Manufacturing AI for quality inspection and robotics simulation drives enterprise GPU virtualization adoption in Nagoya and Osaka industrial corridors. METI's semiconductor revitalization strategy includes domestic advanced packaging capacity that will eventually reduce reliance on TSMC-bound silicon. Tokyo's Otemachi financial district hosts specialized inference nodes for real-time risk calculations under JFSA guidelines.
GPU Virtualization Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the silicon and virtualization software layers. The market exhibits concentrated supply-side dynamics where NVIDIA allocation agreements determine competitive positioning more than software differentiation. Three archetypes dominate: hyperscale cloud platforms with integrated software stacks, specialized GPU-as-a-service providers with project finance backing, and sovereign cloud operators serving regulated European and Asian markets. Capacity expansion through direct foundry relationships and strategic partnerships for memory subsystem sourcing represent the dominant competitive moves.
Within the specialized GPU-as-a-service tier, CoreWeave and Lambda Labs exemplify the project finance-backed model that has displaced traditional corporate balance sheet expansion. CoreWeave occupies a position anchored in NVIDIA infrastructure specialization for generative AI training workloads. Lambda Labs sits within the researcher-centric segment where direct hardware access and pricing transparency differentiate against bundled enterprise offerings. Among hyperscale platforms, Microsoft Azure represents the integrated software stack approach that sustains broad enterprise reach through existing procurement relationships.
| Leading Market Players |
|---|
| CoreWeave |
| RunPod |
| Amazon Web Services (AWS) |
| Oracle Cloud Infrastructure |
| Lambda Labs |
| Microsoft Azure |
| NVIDIA DGX Cloud |
| Paperspace |
| Google Cloud Platform |
| Others |
Supply & Pricing Matrix
Sub-100% utilization at Northern Virginia hyperscaler campuses is compressing spot pricing for H100 clusters while tightening contract terms for reserved capacity. This slack permits aggressive discounting on short-term leases even as long-term offtake agreements harden pricing power for TSMC-bound silicon allocation.
Pricing Analysis
Configured-to-order premiums for TISAX-certified sovereign instances in Frankfurt exceed standard public cloud GPU pricing by substantial margins. Three-tier pricing structure across premium certified, standard multi-tenant, and economy preemptible levels captures divergent risk tolerances. Price differentiation rests on ISO/IEC 27001 certification grade and guaranteed memory isolation rather than raw compute throughput. Pricing pressure stems from CoreWeave and Lambda Labs project finance vehicles flooding mid-market capacity. Research institutions exhibit highest price sensitivity; financial services under ECB operational resilience guidelines show lowest.
Supply Chain Analysis
TSMC foundry concentration in Taiwan, CoWoS packaging capacity in Taiwan and South Korea, and HBM memory supply from Samsung and SK Hynix in South Korea anchor physical GPU output. Raw material dependencies span advanced silicon wafers, EUV photoresist chemicals, and high-bandwidth memory stacks. Supply chain risk centers on single-source vulnerability at TSMC's leading-edge nodes where alternative qualified sources remain absent. Distribution runs through direct NVIDIA allocation agreements to hyperscalers, specialized GPU-as-a-service providers, and sovereign cloud operators rather than traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU virtualization sits in early-cycle expansion as machine learning inference pipelines broaden addressable workloads beyond training into persistent production deployments.
For Market Incumbents: Insulate NVIDIA allocation priority through multi-year supply agreements and captive packaging capacity reservations. Defend margin position by deepening backward integration into HBM memory sourcing rather than relying on merchant supply. Counter specialized GPU-as-a-service entrants by embedding virtualization layers within existing enterprise software procurement relationships. For New Entrants and Emerging Players: Establish a beachhead in India BIS-certified sovereign cloud infrastructure where Digital Personal Data Protection Act mandates favor local operators over foreign hyperscalers. Target edge inference convergence in 5G network slicing deployments that bypass centralized cloud latency economics. Pursue researcher-centric direct hardware access models with transparent pricing to differentiate against bundled enterprise offerings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialized GPU-as-a-service infrastructure as project finance vehicles displace traditional corporate balance sheet expansion. Long-term viability favors operators with direct foundry relationships and strategic memory subsystem partnerships over pure software virtualization plays. Monitor NVIDIA allocation agreement announcements as the critical signal for competitive positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Relationship | TSMC capacity reservations secure H100 silicon allocation ahead of merchant market competitors. |
| Sovereign Cloud Certification | EU AI Act audit trail capabilities capture compliance premiums from German automotive and financial services. |
| Edge Inference Node Deployment | 5G network slicing partnerships in Japan and India bypass centralized cloud latency penalties. |
| Project Finance Vehicle Structuring | Off-balance-sheet fleet expansion enables mid-scale entrants to compete against hyperscaler balance sheets. |
| Memory Subsystem Integration | HBM sourcing partnerships with Samsung or SK Hynix reduce exposure to CoWoS packaging bottlenecks. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and NVIDIA quarterly shipment reports anchors the qualitative findings. Primary interviews with cloud infrastructure architects, GPU-as-a-service procurement leads, enterprise IT directors, and sovereign cloud compliance officers were combined with secondary validation from SEC filings, EIA data center energy reports, EU AI Act technical documentation, and BIS certification registries. Bottom-up tenant demand modeling and top-down silicon supply triangulation were reconciled across the analysis window.
Calibration against historical utilization rates at Northern Virginia, Oregon, and Frankfurt facilities informed capacity expansion assumptions. Segmentation dimensions modeled include technology layer, deployment model, end-user archetype, application workload type, and regional regulatory cluster. CAGRs were derived from supply-constrained growth ceilings rather than unconstrained demand extrapolation. Forecast inputs incorporated TSMC foundry capacity roadmaps and FCC spectrum allocation timelines.
Stress conditions across NVIDIA allocation priority shifts, EU AI Act enforcement intensity, and TSMC CoWoS capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about machine learning workload persistence and sovereign cloud procurement acceleration. Quarterly review of hyperscaler capex guidance and BIS certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloudifier Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Community Cloud Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Hybrid Cloud Services Market