
 Industrial Metaverse Market | 2026-2036
Industrial Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Metaverse Market Analytics
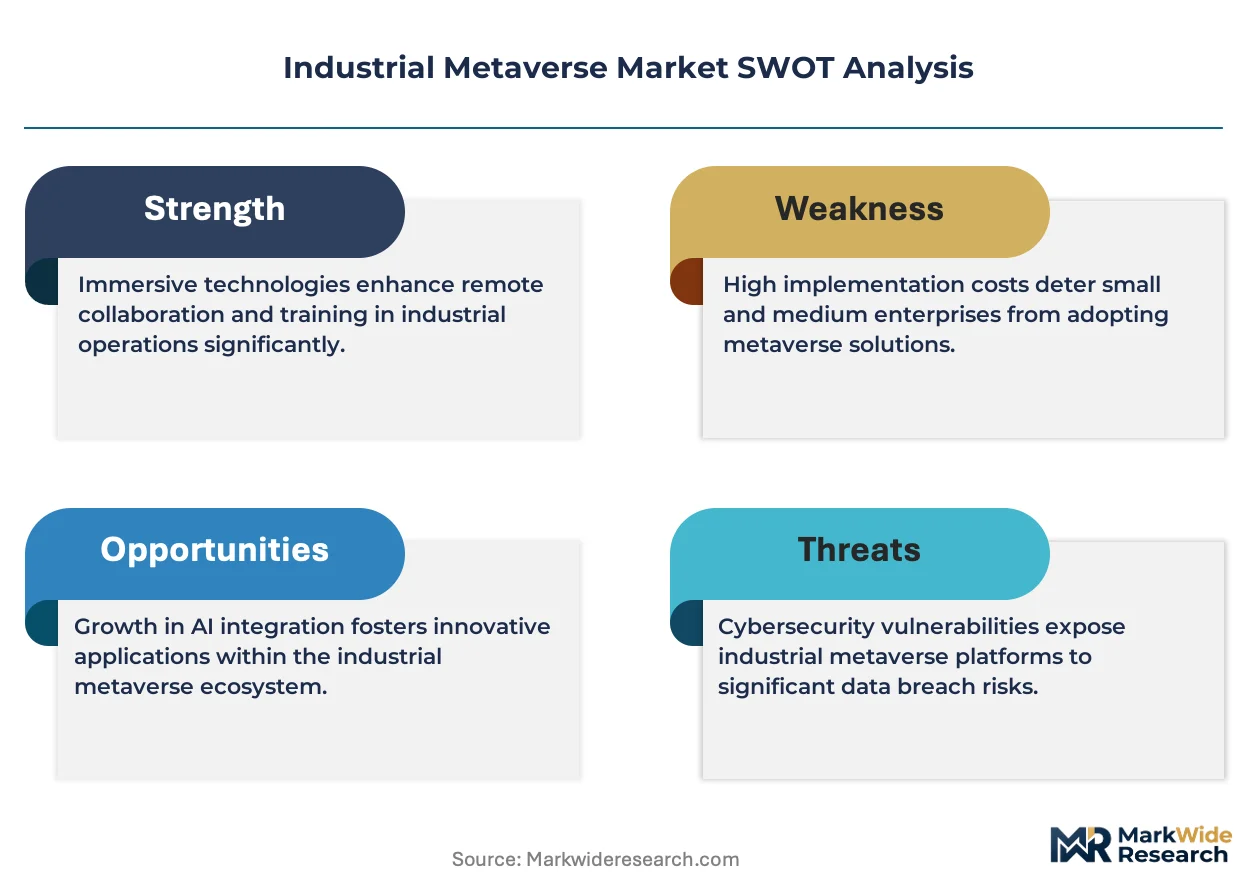
Real-time 3D rendering married to physics-based simulation is tilting industrial software away from static CAD toward persistent virtual environments. NVIDIA Corporation leverages GPU-accelerated omniverse platforms to anchor high-fidelity digital twin pipelines. Siemens sustains deep ties to European manufacturing through its industrial automation software stack. Microsoft competes by extending Azure cloud infrastructure into mixed-reality workspaces for factory operators.
The industrial metaverse denotes an interconnected ecosystem of persistent virtual environments where physical assets, processes, and human operators co-exist as real-time digital counterparts, typically requiring sub-50 millisecond latency and ISO 23247-compliant digital twin frameworks to synchronize sensor data with geometric models. Its primary purpose centers on reducing physical prototyping costs while enabling predictive maintenance and remote expert collaboration across distributed production networks. Digital twins within the Feature segment capture the deepest margin pools because they lock customers into recurring software subscriptions tied to operational-critical assets. AR and VR within the Technology dimension split sharply: AR dominates shop-floor maintenance guidance while VR leads immersive training scenarios for hazardous environments. Manufacturing within the Application category absorbs the largest deployment spend as discrete automation lines justify upfront platform investments through downtime reduction.
The EU AI Act, GDPR, and Germany's BSI IT baseline protection standards shape how platform vendors architect data residency and algorithmic transparency into industrial metaverse offerings. The EPA and OSHA in the United States impose parallel requirements for worker safety simulations and emissions tracking within virtual commissioning environments. Stakeholders must weigh sovereign cloud mandates against interoperability standards when selecting platform partners for multi-site deployments.
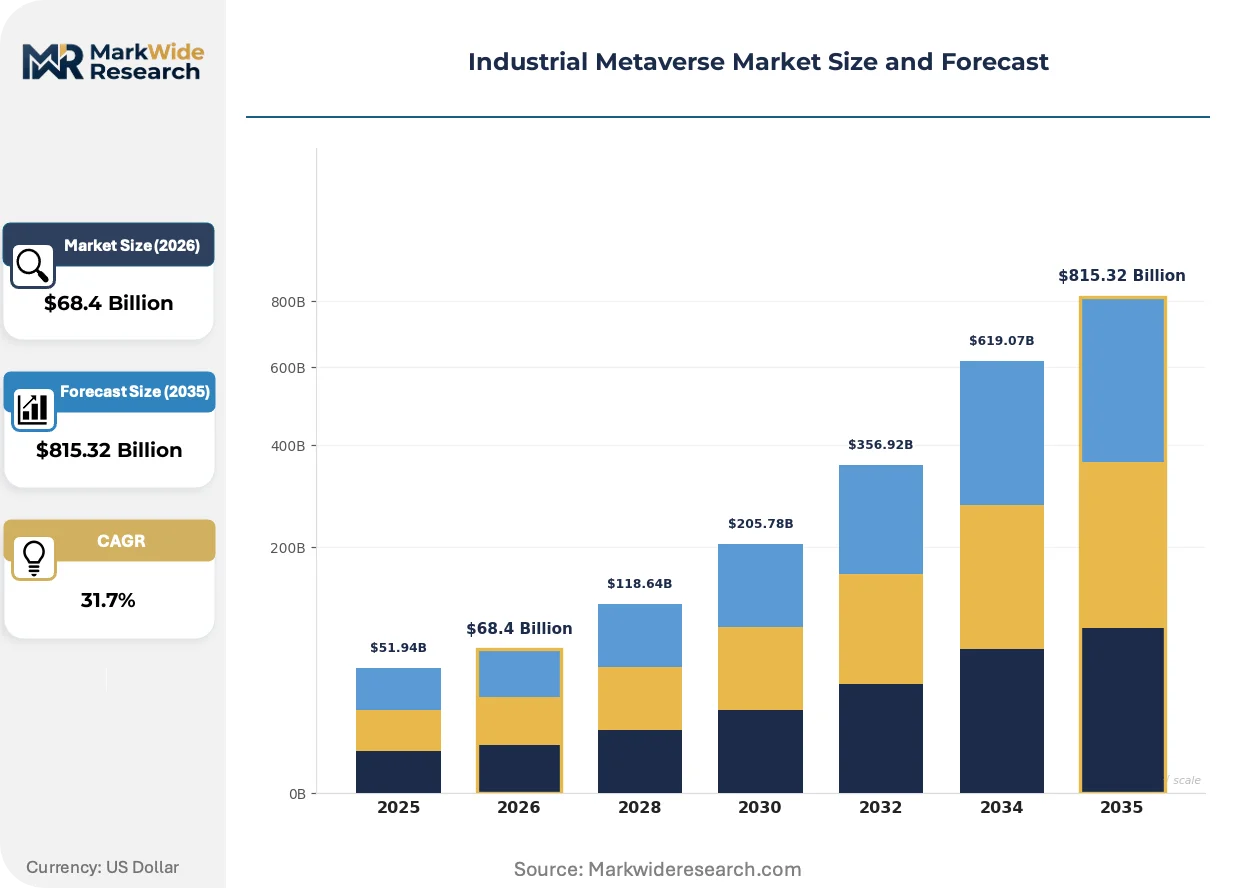
Market Dynamics
Physics-based simulation engines are compressing industrial prototyping cycles from months to days, forcing asset-heavy manufacturers to restructure R&D budgets around persistent virtual environments rather than physical test facilities.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers accelerate digital twin adoption to document algorithmic decision trails for automated quality systems.
- Aerospace training simulation:Commercial aviation and defense contractors deploy immersive VR environments to cut hazardous procedure certification costs.
- Germany's industrial automation corridor:Automotive OEMs in Baden-Württemberg and Bavaria anchor early metaverse deployments for supplier coordination.
Market Restraints
- GPU supply concentration:Taiwan and South Korea foundries control advanced semiconductor fabrication for real-time rendering hardware.
- GDPR data residency friction:Cross-border digital twin synchronization faces sovereign cloud fragmentation across EU member states.
- Sub-50ms latency requirements:Edge infrastructure gaps in Eastern European industrial zones limit remote expert collaboration feasibility.
Strategic Opportunities
- India's PLI scheme for manufacturing:Greenfield automotive and electronics plants offer native metaverse architecture without legacy system drag.
- ISO 23247 framework maturation:Standardized digital twin interoperability opens multi-vendor platform integration for mid-scale manufacturers.
- Digital thread convergence:Product lifecycle management vendors merge with industrial IoT platforms to capture maintenance subscription revenue.
Industry Challenges
- Mechatronics-engineering scarcity:Cross-functional talent combining physics simulation, sensor fusion, and 3D pipeline engineering commands premium compensation.
- OT-IT integration complexity:Brownfield facilities struggle to map legacy SCADA architectures into API-driven metaverse middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Metaverse Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $815.32 Billion |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Logistics, Training, Quality Assurance Technology: AR, VR, AI, Blockchain End User: OEMs, Tier-1 Suppliers, Service Providers, System Integrators Feature: Collaboration Tools, Simulation, Digital Twins, Analytics |
| Companies Covered | NVIDIA Corporation, Microsoft, Siemens, Amazon Web Services, IBM, Meta, HTC Corporation, ABB, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Metaverse Market Evolving Landscape
Real-time rendering pipelines are absorbing physics simulation workloads that previously required dedicated HPC clusters, collapsing the boundary between visualization and computational engineering tools.
Neural radiance fields (NeRFs) are hybridizing photogrammetry with synthetic data generation for digital twin initialization. Automotive manufacturers scan physical production lines to seed virtual environments, then augment with simulated failure modes for predictive maintenance training. This compression of asset digitization timelines is displacing manual CAD reconstruction for brownfield facilities.
The EU AI Act's risk-classification framework is mandating explainability layers for AI-driven simulations used in safety-critical commissioning. German automotive suppliers now document decision pathways within virtual collision-testing environments. France's CNIL coordinates with BSI to align algorithmic transparency requirements with existing IT baseline protection standards.
Capital equipment buyers are unbundling software subscriptions from hardware procurement, treating metaverse platforms as operational expenditures rather than capital investments. Discrete manufacturing purchasers in Japan's automotive supply base negotiate usage-based pricing for digital twin instances. This shift pressures legacy vendors to restructure revenue recognition around consumption metrics rather than perpetual licenses.
Industrial Metaverse Market Segmentation
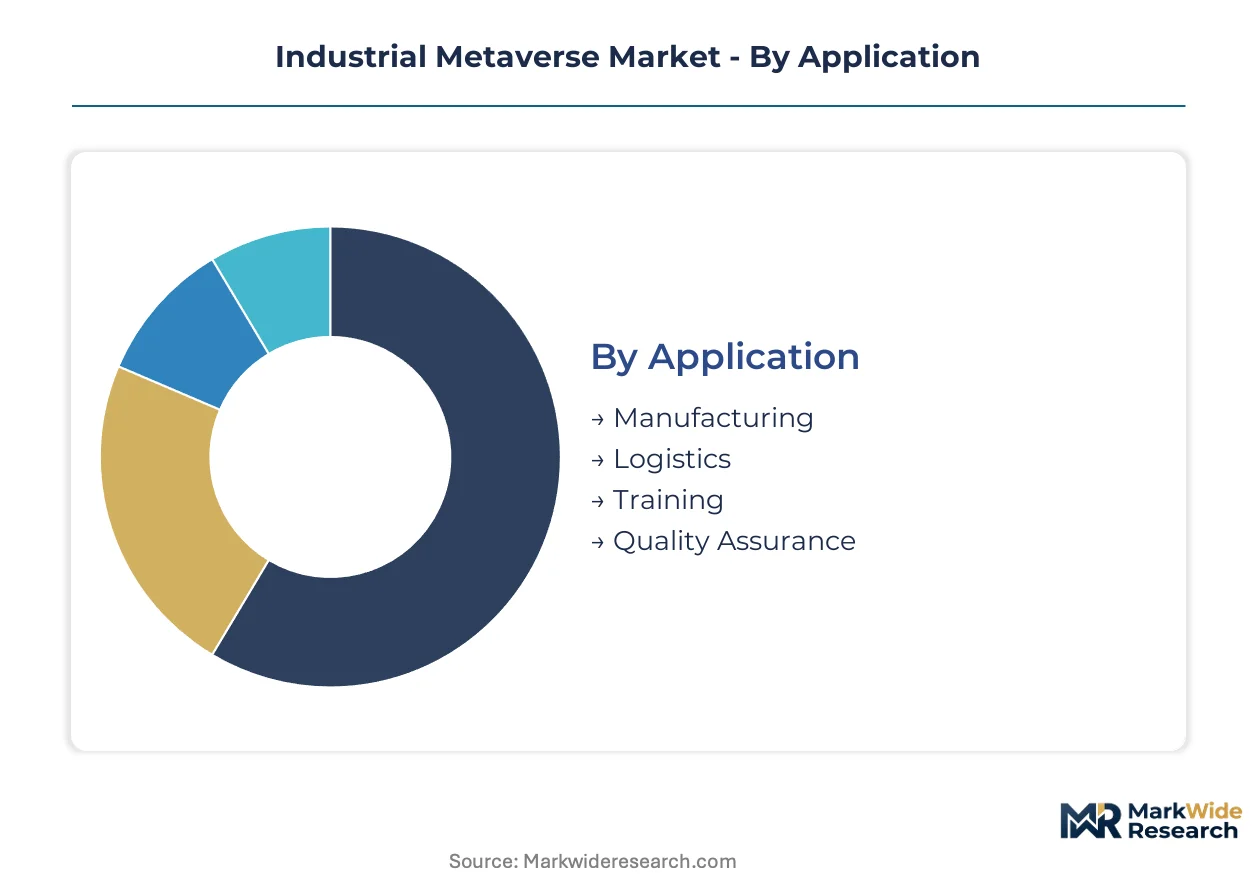
Segmentation in the industrial metaverse reveals how deployment cycles vary sharply by use case and buyer sophistication. Manufacturers with discrete automation lines justify platform investments through downtime reduction, while training applications compress procurement timelines through SaaS delivery models.
Application:
Manufacturing cycles turn over slowest due to capital intensity and OT-IT integration complexity, while training applications refresh fastest as content libraries expand quarterly.
- Manufacturing:Discrete automation lines and process industries deploy persistent virtual environments for virtual commissioning and predictive maintenance. German automotive OEMs in Baden-Württemberg anchor early deployments, justifying upfront platform investments through unplanned downtime reduction.
- Training:Immersive VR environments compress hazardous procedure certification cycles from months to weeks. Aerospace manufacturers and defense contractors in France and Germany drive demand as EU AI Act documentation requirements push simulation-based training for automated quality systems.
- Logistics:Warehouse digital twins optimize slotting algorithms and AGV path planning.
- Quality Assurance:Real-time defect detection feeds algorithmic decision trails for compliance documentation.
Manufacturing dominates installed base. Training is where expansion concentrates.
Technology:
Cost tiering separates hardware-dependent modalities from software-centric layers, with GPU-accelerated rendering commanding premium positioning against lightweight AR overlays.
- AR:Shop-floor maintenance guidance overlays procedural checklists onto physical assets through tablet or headset displays. German industrial automation corridors deploy AR for supplier coordination across distributed production networks, constrained by sub-50ms latency requirements in Eastern European zones.
- VR:Fully immersive environments isolate operators for hazardous scenario training without physical risk exposure. Commercial aviation training centers in France and defense contractors across Europe drive adoption as GDPR data residency rules fragment cross-border deployment architectures.
- AI:Physics-based simulation engines and predictive analytics layers automate decision pathways within virtual environments.
- Blockchain:Distributed ledger architectures document asset provenance and algorithmic audit trails for regulatory compliance.
AR captures broadest deployment volume. VR is climbing the fastest as training budgets restructure around immersive certification.
End User:
Customer type determines procurement authority and integration complexity, with OEMs controlling architecture decisions while service providers absorb implementation risk.
- OEMs:Original equipment manufacturers specify platform architectures and mandate supplier compliance. Automotive OEMs in Germany's industrial corridor anchor multi-site deployments, driving standardization requirements that cascade through tiered supply chains.
- Tier-1 Suppliers:Direct component suppliers inherit platform mandates from OEM customers while negotiating usage-based pricing for digital twin instances. Japan's automotive supply base leads consumption-metric contracting models.
- Service Providers:Third-party maintenance and facility operators adopt metaverse tools for remote expert collaboration.
- System Integrators:Engineering firms bridge legacy SCADA architectures into API-driven metaverse middleware for brownfield facilities.
OEMs control architecture specifications. Tier-1 Suppliers represent the fastest-growing procurement segment as outsourcing pressure intensifies.
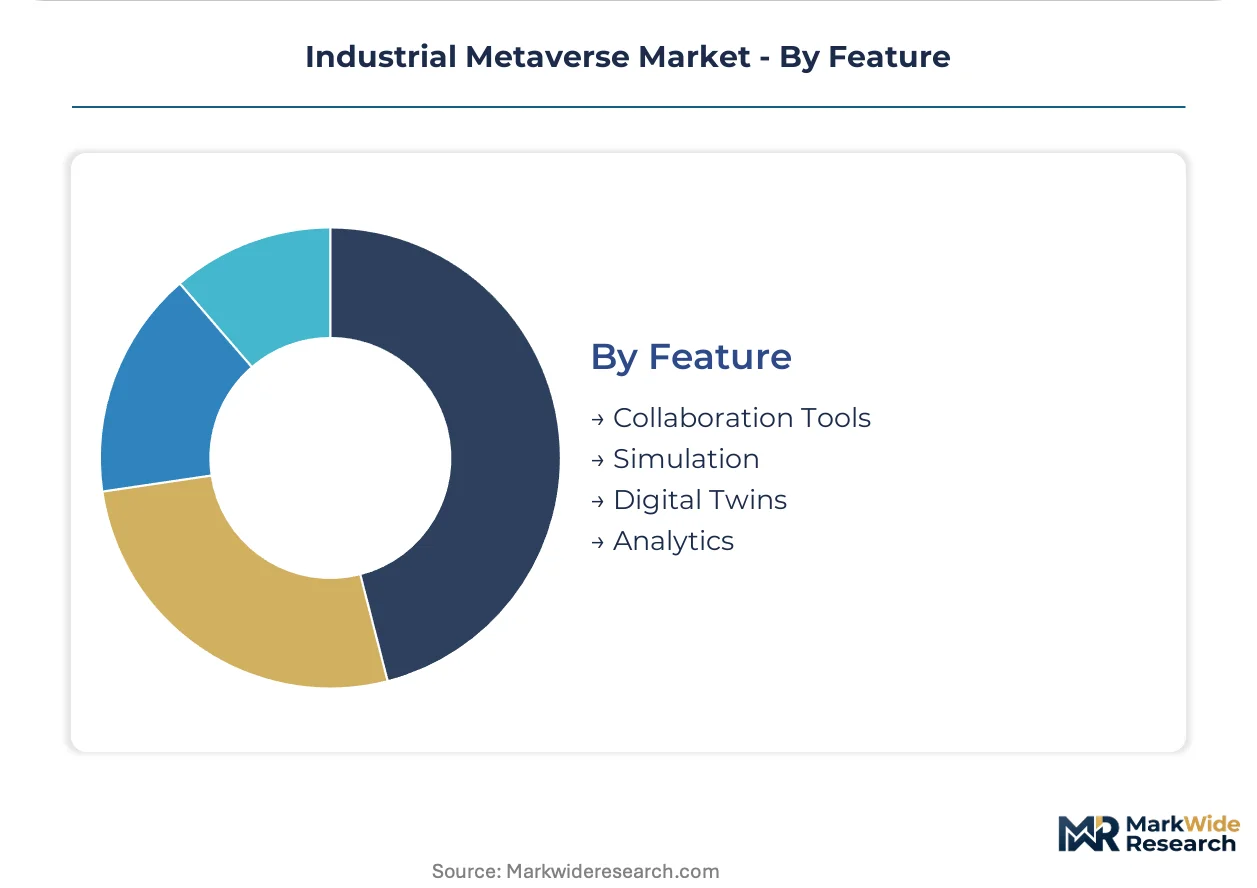
Feature:
Margin pools concentrate in operational-critical capabilities that lock customers into recurring subscriptions, while collaboration tools face commoditization from horizontal software vendors.
- Digital Twins:ISO 23247-compliant frameworks synchronize sensor data with geometric models for persistent virtual representations of physical assets. These capabilities capture the deepest recurring revenue pools by tying subscriptions to operational-critical infrastructure.
- Simulation:Physics-based engines compress prototyping cycles from months to days, forcing R&D budget restructuring around virtual rather than physical test facilities. Aerospace applications drive fidelity requirements for collision-testing and aerodynamic modeling.
- Collaboration Tools:Real-time multi-user environments enable remote expert guidance across distributed production networks.
- Analytics:Predictive maintenance algorithms and operational dashboards extract insight from digital twin data streams.
Digital Twins dominate subscription revenue. Simulation is gaining share fastest as physics engine capabilities expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs concentrate procurement authority for industrial metaverse platforms, while aerospace manufacturers in France and defense contractors across Europe drive training-application demand through EU AI Act compliance mandates.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria anchor multi-site deployments for supplier coordination. The BSI IT baseline protection standards mandate sovereign cloud architectures for digital twin data residency. Stuttgart's industrial automation corridor justifies upfront platform investments through unplanned downtime reduction on discrete automation lines.
United States
Aerospace manufacturers deploy immersive VR environments to compress hazardous procedure certification cycles. EPA and OSHA requirements impose worker safety simulation standards for virtual commissioning environments. Seattle-area defense contractors and commercial aviation training centers in Dallas-Fort Worth drive fidelity requirements for collision-testing simulations.
France
CNIL coordinates with EU AI Act implementation to align algorithmic transparency requirements for automated quality systems. ANSM oversight extends to safety-critical commissioning simulations in pharmaceutical manufacturing. Toulouse aerospace clusters and Paris-Saclay defense research facilities concentrate immersive training procurement for hazardous environment certification.
Japan
Automotive tier-1 suppliers in Toyota City and Yokohama lead consumption-metric contracting models for digital twin instances. METI industrial digitization programs subsidize brownfield SCADA-to-middleware integration. Nagoya manufacturing corridors negotiate usage-based pricing that treats metaverse platforms as operational expenditures rather than capital investments.
India
Greenfield automotive and electronics plants under the PLI scheme offer native metaverse architecture without legacy system drag. DGFT export incentive structures accelerate digital twin adoption for supplier qualification documentation. Tamil Nadu and Gujarat manufacturing zones deploy persistent virtual environments for virtual commissioning of new production lines.
Industrial Metaverse Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where cloud infrastructure providers and industrial automation incumbents anchor opposing strategic poles. The vendor base clusters around three archetypes: GPU-accelerated platform orchestrators, legacy automation software extenders, and hyperscale cloud service integrators. Dominant competitive moves include strategic partnerships binding hardware-software stacks and geographic expansion through sovereign cloud localization.
Within the GPU-accelerated tier, NVIDIA Corporation anchors high-fidelity digital twin pipelines, while Siemens exemplifies the legacy automation extender archetype through deep European manufacturing ties. Microsoft occupies a position among hyperscale cloud integrators extending infrastructure into mixed-reality workspaces. These three represent the strategic poles around which mid-scale specialists and regional system integrators orbit.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft |
| Siemens |
| Amazon Web Services |
| IBM |
| Meta |
| HTC Corporation |
| ABB |
| PTC |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Duisburg freight corridor anchors GPU and edge-server logistics for industrial metaverse deployments, with container rates feeding directly into platform subscription pricing and downstream cost-plus contracting for German automotive OEMs.
Pricing Analysis
Cost-plus contracts with GPU price indexation dominate industrial metaverse procurement, linking platform fees to NVIDIA A100/H100 spot markets and Taiwan foundry output. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud-compliant deployments from latency-tolerant configurations, with ISO 23247 certification tiers adding margin. Pricing pressure stems from foundry concentration in Taiwan and South Korea, compressing hardware margins for system integrators. Tier-1 automotive suppliers in Japan exhibit highest price sensitivity through usage-based SaaS negotiations, while aerospace OEMs absorb premium pricing for collision-simulation fidelity.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung Electronics anchors GPU supply for real-time rendering, with backend packaging concentrated in Malaysia and Vietnam. Advanced substrates, HBM memory, and precision optics constitute critical input dependencies. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure for sub-5nm node production. Distribution runs through hyperscale cloud integrators and industrial automation distributors, with direct OEM procurement gaining share for sovereign cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial metaverse economics are shifting toward platform-ecosystem winner-take-most dynamics, with ISO 23247 interoperability maturation determining which vendor stacks capture maintenance-subscription lock-in across multi-site manufacturing networks.
For Market Incumbents: Build switching-cost moats through digital twin data gravity and API ecosystem density. Siemens and NVIDIA should deepen industrial automation software integration to capture recurring revenue from predictive maintenance subscriptions. Defend against hyperscaler cloud integrators by certifying sovereign cloud architectures for EU AI Act compliance in Germany and France.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme greenfield automotive plants, where native metaverse architecture avoids brownfield SCADA integration complexity. Target tier-1 supplier procurement committees in Japan's Toyota City corridor with consumption-metric pricing models. Pursue ISO 23247 certification as a go-to-market wedge for mid-scale European manufacturers.
For Investors and Strategic Acquirers: Physics-simulation specialists with automotive-aerospace dual certification represent the highest-conviction acquisition archetype. Long-term viability hinges on digital thread convergence with product lifecycle management platforms. Monitor GPU supply normalization at Taiwan foundries as the inflection signal for platform margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | NVIDIA Omniverse-Siemens Xcelerator binding captures German automotive digital twin procurement. |
| Sovereign Cloud Localization | Microsoft Azure Germany deployment satisfies BSI IT baseline protection for Stuttgart OEMs. |
| ISO 23247 Certification Investment | Standardized interoperability opens multi-vendor integration for mid-scale French manufacturers. |
| Acquisition of Physics Simulation Specialist | Collision-testing fidelity targets aerospace training budgets in Toulouse and Seattle. |
| Geographic Expansion via India's PLI Scheme | Tamil Nadu greenfield plants offer native architecture without legacy SCADA drag. |
Research Methodology
A standing panel of industrial automation software executives, OEM digital transformation leads, tier-1 supplier procurement managers, and hyperscaler cloud architects provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings, EU AI Act implementation guidance, BSI IT baseline protection standards, and customs data tracking GPU and edge-server import flows. Bottom-up deployment sizing triangulated against top-down platform revenue estimates.
Scenario bracketing anchored low-case assumptions around GPU supply disruption at Taiwan foundries and high-case assumptions around ISO 23247 rapid adoption. The analytical framework modeled deployment trajectories across the analysis window by application, technology, end user, and feature dimensions, with regional regulatory clusters as an overlay. CAGRs derived from slope-intercept modeling of historical adoption curves adjusted for sovereign cloud mandate acceleration. Physics engine capability maturation and mechatronics-engineering wage inflation served as industry-specific forecast inputs.
Sensitivities concentrate around EU AI Act enforcement timing, Taiwan semiconductor supply stability, and Eastern European edge infrastructure buildout. Forecasts reflect documented assumptions on OEM procurement cycle lengths and tier-1 supplier SaaS conversion rates. Quarterly review of GPU spot pricing, ISO 23247 certification velocity, and PLI scheme disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market