
 Augmented Reality Solutions Market | 2026-2036
Augmented Reality Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality Solutions Market Analysis
Enterprise buyer concentration is rebalancing as defense contractors and automotive OEMs consolidate procurement while mid-sized manufacturers fragment across specialized AR tool vendors. Microsoft Corporation leverages its HoloLens industrial ecosystem to anchor enterprise-grade mixed reality deployments. Meta Platforms Inc. competes aggressively on consumer headset affordability but sustains developer loyalty through its Quest platform investments. PTC Inc. dominates industrial AR software with its Vuforia suite, controlling the maintenance and training application layer for manufacturing clients.
Augmented reality solutions overlay computer-generated imagery, spatial data, and real-time sensor feeds onto physical environments through optical see-through or video see-through displays operating at 60–120 Hz refresh rates with sub-20 millisecond motion-to-photon latency. These systems primarily enable hands-free workflow guidance, remote expert collaboration, and spatial analytics across industrial and commercial operations. Marker-less tracking technology leads deployment growth as simultaneous localization and mapping eliminates fiducial dependency for warehouse logistics and field service applications. Cloud-based deployment captures expanding margin pools by offloading rendering workloads and enabling cross-site content synchronization for distributed enterprise users.
The FDA regulates AR surgical navigation systems under software-as-medical-device pathways while the EU AI Act imposes conformity assessment obligations on high-risk immersive healthcare applications. FCC spectrum allocations for millimeter-wave and unlicensed 60 GHz bands directly shape wireless AR headset performance specifications and market access conditions. Stakeholders must monitor evolving interoperability standards between hardware platforms and enterprise software stacks as procurement decisions increasingly hinge on open ecosystem commitments rather than proprietary vertical integration.
Market Dynamics
Marker-less tracking systems are compressing deployment timelines for industrial AR applications, eliminating fiducial infrastructure costs and enabling same-day activation across warehouse and field service environments. This technological inflection is redrawing competitive boundaries between hardware-anchored and software-centric platform providers.
Growth Catalysts
- EU AI Act conformity pathways:High-risk healthcare AR applications now face structured assessment frameworks, accelerating investment in compliant surgical navigation systems across German and French hospital networks.
- Millimeter-wave spectrum allocation:FCC rulings on unlicensed 60 GHz bands enable untethered headset performance specifications, unlocking wireless deployment in US manufacturing facilities previously constrained by cable management.
- Automotive OEM consolidation:Tier-1 suppliers in Germany and Japan are bundling AR-guided assembly validation into production line contracts, creating captive demand for mixed reality quality assurance tools.
Market Restraints
- Optical component supply concentration:Waveguide manufacturing for see-through displays clusters with specialized foundries in Taiwan and South Korea, exposing hardware vendors to single-source disruption risk.
- EU MDR software classification:AR surgical systems face extended conformity assessment timelines under medical device regulations, delaying European market entry for non-EU developers by 12-18 months versus FDA 510(k) pathways.
- Smartphone AR substitution:Handheld spatial computing on iOS and Android devices satisfies basic visualization needs for price-sensitive training applications, compressing entry-level headset demand.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for wearable device manufacturing are attracting AR hardware assembly to Tamil Nadu and Karnataka, creating localized supply hubs for South Asian markets.
- Remote expert collaboration platforms:Oilfield services in the UAE and Saudi Arabia are piloting AR-enabled maintenance support, replacing fly-in technician dispatch with real-time guided repair workflows.
- ISO/IEC 27001 convergence:Enterprise security certification for cloud-rendered AR content is becoming a procurement gate, favoring vendors with pre-certified infrastructure over point solutions.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with SLAM optimization expertise command 40-60% salary premiums, constraining R&D velocity for mid-sized platform developers.
- Legacy ERP integration friction:Manufacturing clients require custom middleware to connect AR work instructions with SAP and Oracle systems, extending deployment cycles and professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality Solutions Market |
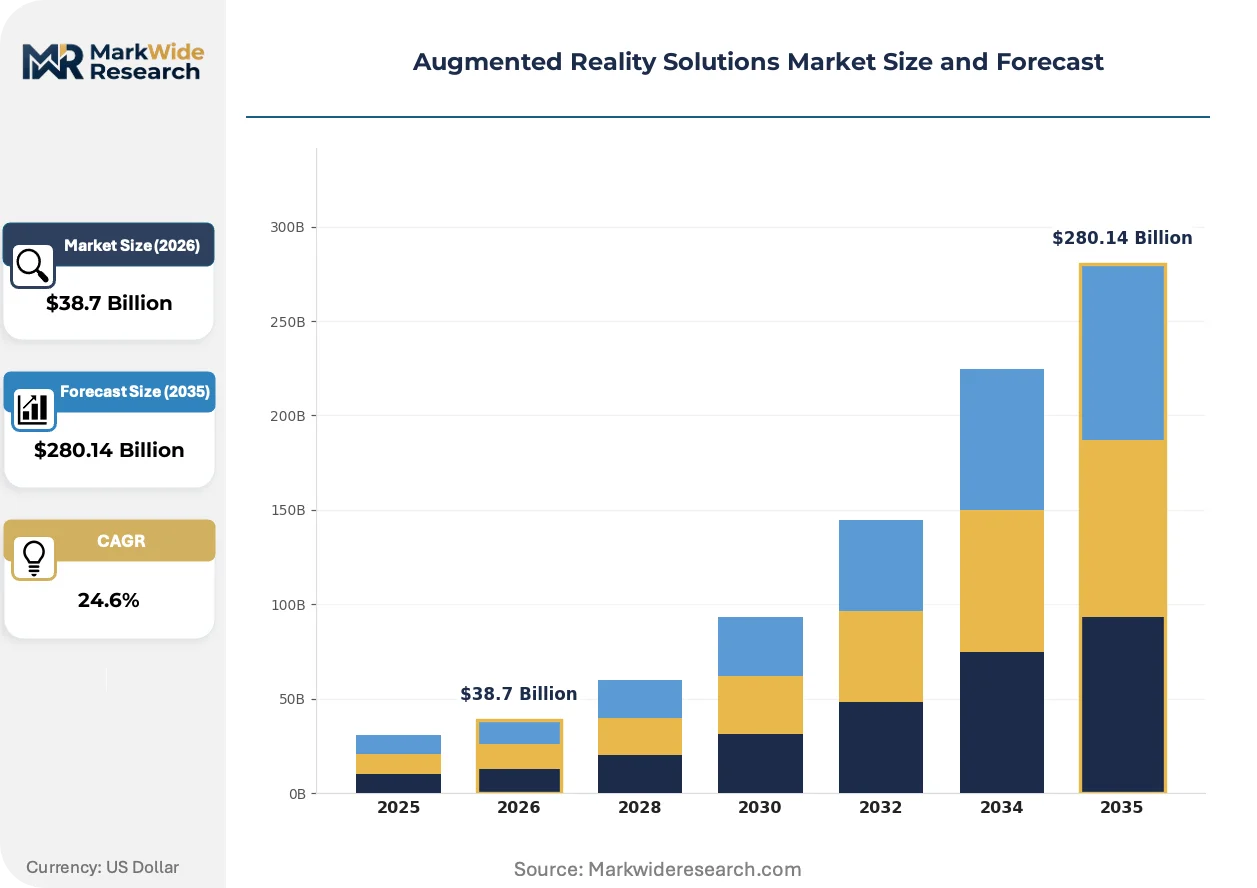
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-Based, Marker-Less, Projection-Based, Superimposition-Based End User: Retail, Healthcare, Education, Entertainment Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Application: Gaming, Training, Maintenance, Navigation |
| Companies Covered | Microsoft Corporation, Apple Inc., Meta Platforms Inc., Google LLC, Samsung Electronics Co. Ltd., Sony Corporation, Magic Leap Inc., Vuzix Corporation, PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality Solutions Market Emerging Trajectories
Edge-native rendering architectures are redistributing computational load across AR deployments, reducing headset power requirements while preserving visual fidelity. This infrastructure shift is enabling all-day industrial use cases previously blocked by thermal and battery constraints.
Optical waveguide displays are overtaking birdbath optics in enterprise headset designs, delivering superior transparency and field-of-view for hands-free assembly guidance. Automotive manufacturers in Germany and Japan are specifying waveguide-based systems for production line integration, compressing procurement cycles for legacy video-see-through hardware. The transition is overtaking established supply relationships and forcing component vendors to retool manufacturing lines.
The EU AI Act's high-risk system classification for surgical AR imposes documented risk management and post-market monitoring obligations on developers. French and German notified bodies are building specialized assessment capacity for immersive healthcare software, creating regulatory capacity bottlenecks. Device manufacturers are responding by pre-submission engagement with BSI Germany and TÜV SÜD to compress approval timelines.
Defense contractors are consolidating procurement authority for AR training systems under centralized acquisition offices, displacing fragmented unit-level purchasing. This concentration is compressing vendor qualification cycles and favoring platforms with existing security clearances and FedRAMP authorization. The pattern is most visible in US Army and Air Force maintenance training programs, where single-source indefinite-delivery contracts are replacing multiple-award task orders.
Augmented Reality Solutions Market Segmentation
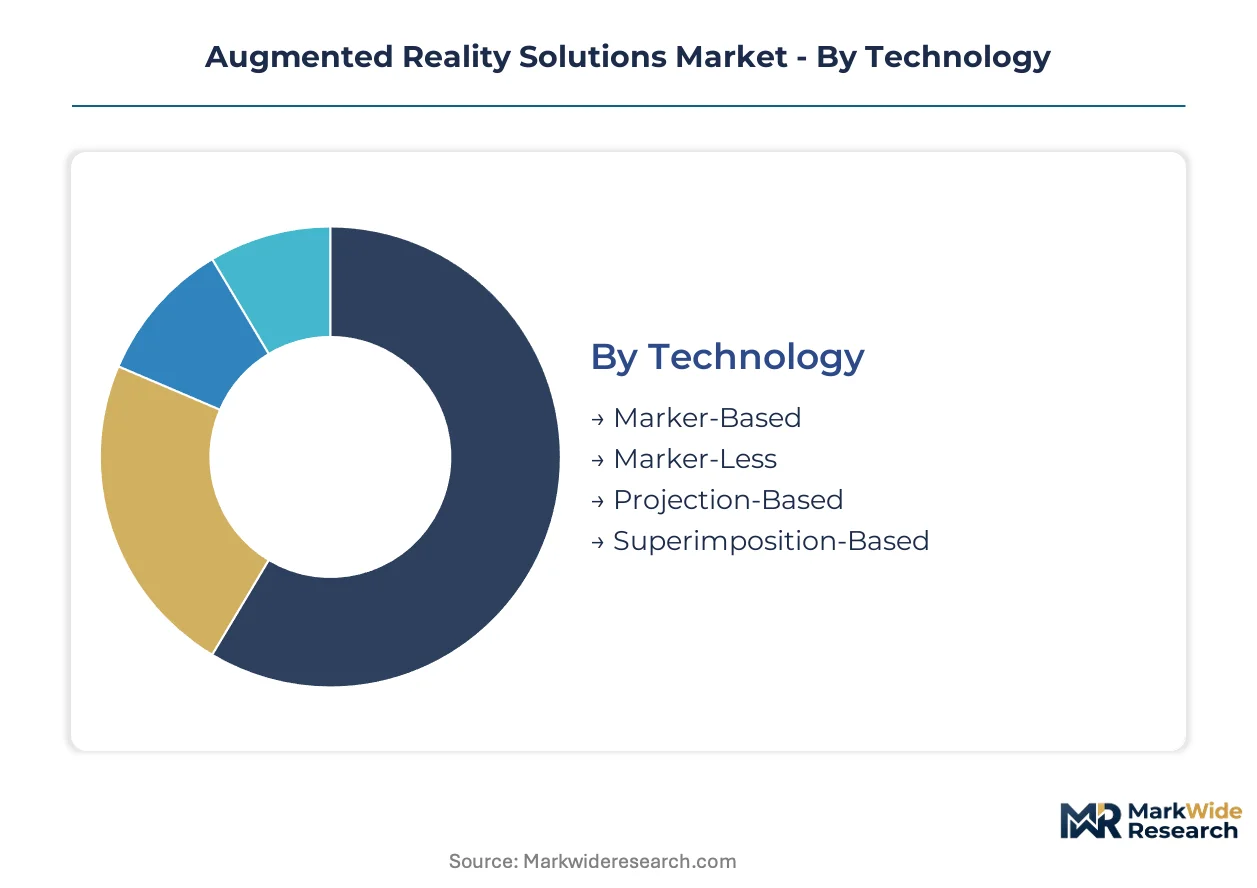
AR solution architectures diverge sharply between standardized hardware platforms and vertically customized software stacks. Procurement patterns cluster around deployment flexibility and regulatory compliance requirements rather than pure technology specifications.
Technology:
Standardization pressure from enterprise IT departments favors modular tracking architectures over proprietary closed systems.
- Marker-Less:Simultaneous localization and mapping eliminates fiducial infrastructure costs. Warehouse operators in Germany and the United States prioritize same-day deployment capability over legacy marker-dependent systems. SLAM optimization demands compress vendor selection to specialists with proven industrial field performance.
- Marker-Based:Optical fiducial tracking delivers sub-millimeter precision at lower computational overhead. Medical device manufacturers in Japan retain marker-based surgical navigation for FDA 510(k) pathway compatibility. Image recognition libraries from established computer vision vendors reduce integration risk.
- Projection-Based:Spatial light projection onto physical surfaces enables shared collaborative environments without individual headsets. Automotive assembly lines in Germany deploy projection AR for multi-operator quality verification stations.
- Superimposition-Based:Direct object replacement visualization supports complex equipment teardown procedures. Oilfield maintenance contractors in Saudi Arabia pilot superimposition systems for valve assembly guidance.
Leading the category by volume: Marker-Less. Expanding most quickly: Projection-Based.
End User:
Customer procurement maturity spans from experimental pilot budgets to production-scale enterprise contracts.
- Healthcare:Surgical navigation and clinical training applications face EU AI Act high-risk classification requirements. French and German notified bodies are building specialized assessment capacity for immersive healthcare software, creating regulatory capacity bottlenecks. FDA software-as-medical-device pathways offer faster US market entry.
- Retail:Virtual try-on and spatial merchandising drive consumer-facing deployment. Furniture retailers in the United States and China deploy room-scale visualization to reduce return rates. Cloud-rendered content synchronization enables rapid catalog updates across distributed store networks.
- Education:Institutional procurement cycles favor multi-year licensing over per-seat subscriptions. Technical vocational programs in India integrate AR assembly guidance into manufacturing skills curricula.
- Entertainment:Location-based experience venues demand high-refresh-rate optical systems for motion sickness mitigation. Theme park operators in Japan specify waveguide-based designs for outdoor durability.
Dominant by contract value: Healthcare. Gaining share fastest: Retail.
Deployment:
Infrastructure control preferences split between data sovereignty mandates and operational agility requirements.
- Cloud-Based:Rendering workload offloading reduces headset thermal constraints and extends battery life. Enterprise security certification under ISO/IEC 27001 is becoming a procurement gate for cloud-rendered AR content. Manufacturing clients with multi-site operations prioritize cross-site content synchronization.
- On-Premise:Air-gapped installations satisfy defense contractor security clearance requirements. US Army and Air Force maintenance training programs mandate on-premise deployment for classified technical data handling.
- Hybrid:Edge-native architectures redistribute computational load between local rendering and cloud augmentation. This infrastructure shift enables all-day industrial use cases previously blocked by thermal constraints.
- Mobile:Smartphone AR on iOS and Android devices satisfies basic visualization needs for price-sensitive training applications. Handheld spatial computing compresses entry-level headset demand in emerging markets.
Widest enterprise adoption: Cloud-Based. Steepest expansion trajectory: Hybrid.
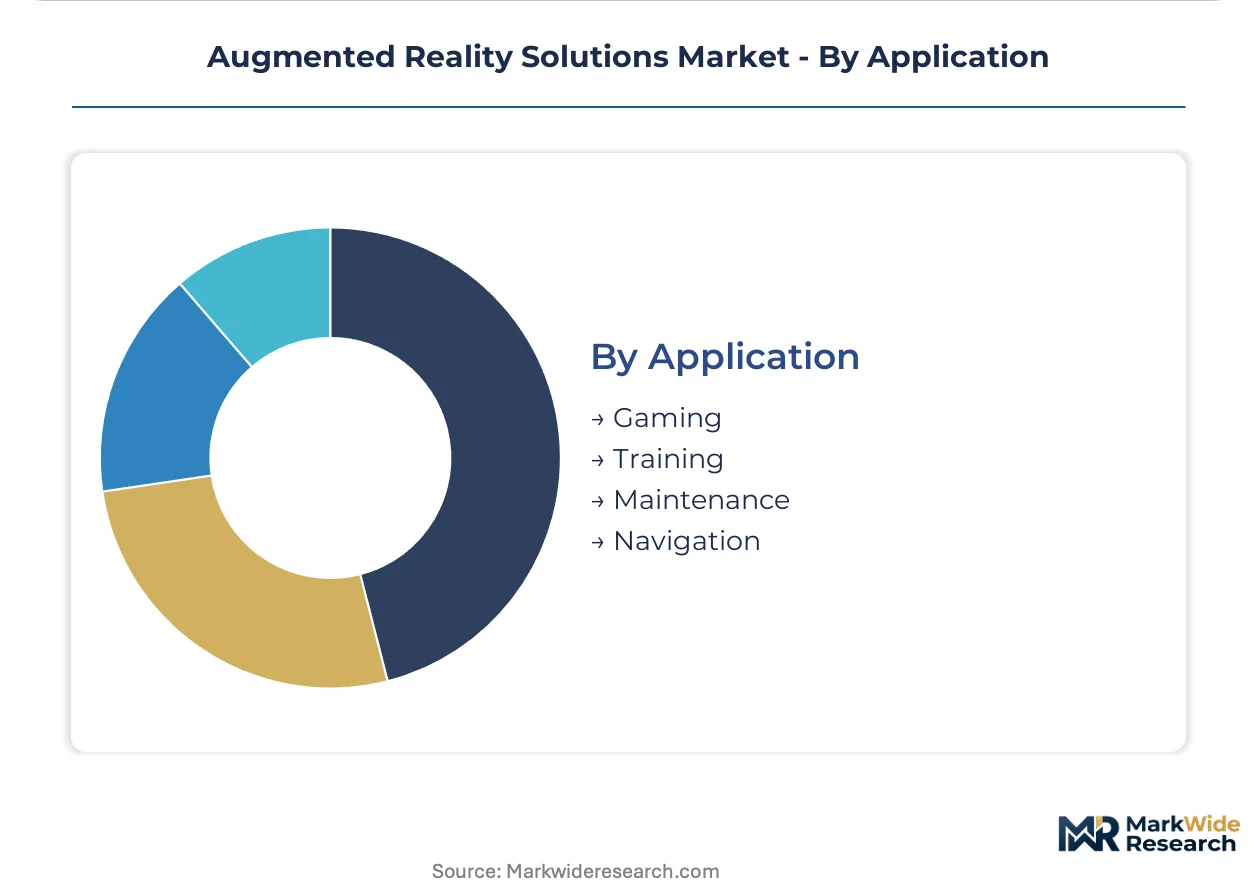
Application:
Use case complexity ranges from consumer entertainment to safety-critical industrial procedures.
- Maintenance:Remote expert collaboration platforms replace fly-in technician dispatch with real-time guided repair workflows. Oilfield services in the UAE and Saudi Arabia pilot AR-enabled maintenance support for offshore platform equipment. Custom middleware requirements to connect with SAP and Oracle systems extend deployment cycles.
- Training:Defense contractors consolidate procurement authority under centralized acquisition offices. Existing security clearances and FedRAMP authorization compress vendor qualification cycles. The pattern displaces fragmented unit-level purchasing in US military programs.
- Gaming:Consumer headset affordability drives volume demand through mass retail channels. Developer platform investments sustain content ecosystem loyalty.
- Navigation:Outdoor AR wayfinding requires GPS-IMU fusion robust to urban canyon multipath effects. Logistics operators in China deploy indoor navigation for automated warehouse picker guidance.
Highest contract value concentration: Maintenance. Climbing the fastest: Training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical waveguide manufacturing concentrates in specialized foundries across Taiwan and South Korea, anchoring hardware supply chains for AR headset production. Enterprise demand clusters in industrial corridors where automotive, aerospace, and logistics operators pilot immersive workflow systems.
United States
Defense contractors and automotive OEMs consolidate procurement for AR training and assembly validation systems. FCC spectrum rulings on unlicensed 60 GHz bands enable wireless headset deployment in manufacturing facilities across Michigan and Ohio. The US Army and Air Force maintenance programs in Georgia and Texas mandate FedRAMP-authorized platforms for classified technical data handling.
Germany
Tier-1 automotive suppliers bundle AR-guided quality assurance into production line contracts, creating captive demand for mixed reality tools. EU AI Act conformity pathways through BSI Germany and TÜV SÜD reshape approval timelines for surgical navigation systems. Industrial clusters in Bavaria and Baden-Württemberg host waveguide display integration facilities serving European automotive OEMs.
China
Logistics operators deploy indoor AR navigation for automated warehouse picker guidance in the Yangtze River Delta. MIIT standards for wearable device interoperability shape domestic headset specifications and market access conditions. Manufacturing hubs in Shenzhen and Shanghai concentrate optical component assembly for both domestic consumption and export markets.
Japan
Medical device manufacturers retain marker-based surgical navigation systems for PMDA pathway compatibility and precision requirements. METI funding for spatial computing R&D accelerates SLAM optimization research in Tokyo and Osaka clusters. Theme park operators specify waveguide-based designs for outdoor durability in Kyoto and Chiba entertainment venues.
India
Technical vocational programs integrate AR assembly guidance into manufacturing skills curricula across Karnataka and Tamil Nadu. PLI scheme incentives for wearable device manufacturing attract hardware assembly to Bengaluru and Chennai hubs. Institutional procurement cycles favor multi-year licensing arrangements for educational deployment.
Augmented Reality Solutions Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized vertical applications and regional price positioning. The vendor base stratifies across three maturity tiers: diversified technology conglomerates with platform ecosystems, industrial software specialists with vertical integration capabilities, and component-focused hardware fabricators. Hardware-anchored providers compete on optical performance specifications while software-centric platforms emphasize enterprise integration depth. Dominant competitive moves include strategic partnerships with automotive OEMs and defense contractors, plus capacity expansion in optical waveguide manufacturing.
Within the diversified technology tier, Microsoft Corporation and Meta Platforms Inc. anchor enterprise and consumer platform strategies respectively. PTC Inc. exemplifies the industrial software specialist archetype, occupying a position centered on manufacturing workflow integration. These three entities represent the primary competitive anchors around which mid-sized specialists and regional assemblers organize their market positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple Inc. |
| Meta Platforms Inc. |
| Google LLC |
| Samsung Electronics Co. Ltd. |
| Sony Corporation |
| Magic Leap Inc. |
| Vuzix Corporation |
| PTC Inc. |
| Others |
Supply Flow & Price Mechanics
Captive waveguide manufacturing in Taiwan and South Korea anchors both component availability and pricing power for optical see-through headsets. This upstream control allows established hardware vendors to command premium positioning while constraining margin compression for mid-tier competitors dependent on merchant supply.
Pricing Analysis
Warranty and multi-year service bundling separate enterprise-grade AR deployments from unbundled hardware transactions. Pricing stratifies across premium, standard, and economy tiers based on optical waveguide certification grade and ISO/IEC 27001 security certification status. Cost compression in the economy tier is intensifying because smartphone AR substitution satisfies basic visualization needs. Price-sensitive mid-sized manufacturers fragment across specialized tool vendors, while defense contractors and automotive OEMs demonstrate lowest price sensitivity due to mission-critical deployment requirements.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Shanghai, and Taoyuan handle waveguide display integration and headset assembly for global markets. Optical component manufacturing concentrates in Taiwan, South Korea, and China, with waveguide foundries representing a single-source vulnerability for see-through display supply. The supply chain draws from rare earth phosphors, precision glass substrates, and millimeter-wave RF modules as critical inputs. Tariff exposure on optical components shipped between Asia-Pacific assembly hubs and North American end markets threatens cost structures. Distribution runs through direct enterprise sales teams for large contracts and specialized industrial distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical waveguide foundry capacity constraints prop pricing power for vendors with captive supply arrangements or long-term supply agreements. Supply scarcity in precision glass substrate processing sustains margin premiums across the analysis window.
For Market Incumbents: Hedge against smartphone AR substitution by deepening software platform stickiness through SAP and Oracle ERP integration investments. Secure waveguide foundry capacity via long-term offtake agreements with Taiwan-based suppliers to defend against single-source disruption. Prioritize FedRAMP authorization and existing security clearance maintenance as procurement gates tighten among defense contractors.
For New Entrants and Emerging Players: Industrial software integrators represent the most accessible channel partnership for bypassing direct hardware competition. Target technical vocational programs in India and Saudi Arabian oilfield maintenance services as underpenetrated deployment environments. Pursue white-label AR training module development for defense contractors consolidating procurement under centralized acquisition offices.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified technology conglomerates seeking industrial software integration capabilities. Long-term viability favors industrial AR software specialists with proven SLAM optimization expertise and established automotive OEM relationships. Monitor EU AI Act notified body capacity expansion in France and Germany as an inflection signal for surgical navigation system approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Foundry Capacity Expansion | Captive supply from Taiwan-based foundries reduces single-source vulnerability for see-through display production. |
| FedRAMP Authorization Investment | Security certification compresses vendor qualification cycles for US Army and Air Force maintenance training contracts. |
| ERP Integration Partnership | SAP and Oracle middleware development extends deployment cycles but deepens enterprise customer switching costs. |
| EU AI Act Pre-Submission Engagement | Early notified body interaction with BSI Germany and TÜV SÜD accelerates surgical navigation system approval timelines. |
| Edge-Native Rendering Architecture | Computational load redistribution enables all-day industrial use cases previously blocked by thermal constraints. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR conformity assessment databases, FCC spectrum allocation rulings, and hyperscaler capex disclosures, complemented by interviews with AR platform engineering leads, hospital biomedical equipment procurement managers, automotive Tier-1 supplier quality directors, and defense contractor training system acquisition officers. Secondary validation drew from SEC filings, MIIT wearable device standards, and customs trade data for optical component flows. Bottom-up deployment estimates triangulated against top-down market sizing across technology, end-user, deployment, and application dimensions.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework across the projection horizon. Segmentation modeling incorporated tracking architecture type, end-user industry regulatory cluster, deployment infrastructure preference, and application complexity tier. CAGRs derived from installed base growth rates, replacement cycle assumptions, and average selling price trajectory analysis. Forecast inputs included waveguide display yield improvements, SLAM algorithm computational efficiency gains, and enterprise IT security certification adoption patterns.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on semiconductor manufacturing equipment, unanticipated EU AI Act enforcement intensity variations, and breakthrough alternative display technologies displacing waveguide architectures. Forecasts reflect documented assumptions regarding optical component supply continuity and regulatory pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market