
 Canada Data Center Power Market | 2026-2036
Canada Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Power Market Insights
Lithium-ion battery chemistry is broadening its share against traditional valve-regulated lead-acid systems in Canada data center UPS installations. Schneider Electric SE leverages its local manufacturing footprint to anchor large-scale projects in Quebec. Eaton Corporation competes through specialized medium-voltage power distribution architectures. Vertiv Group Corp. dominates thermal-electrical integration, a capability that sustains pricing power in hyperscale bids.
Canada data center power encompasses electrical infrastructure purpose-built to deliver uninterruptible, conditioned electricity to server environments, typically operating at 480V/277V or 400V/230V with tiered redundancy from N to 2N configurations. The equipment spans UPS modules, diesel and natural gas generators, static inverters, and emerging proton-exchange-membrane fuel cells designed to bridge utility outages from seconds to hours. Generator systems remain the largest revenue pool across Canadian facilities, though fuel cell segments are gaining share as provincial clean-energy mandates tighten. Edge computing applications are expanding fastest by application type, driven by latency-sensitive workloads in secondary Canadian cities where grid stability varies seasonally.
Health Canada and Environment and Climate Change Canada shape emissions standards for on-site generation, while provincial regulators including the Ontario Energy Board and Hydro-Québec influence interconnection rules and rate structures for data center loads. The Canadian Standards Association certifies electrical equipment to CSA C22.2 standards, creating a compliance threshold distinct from UL-listed US products that affects procurement decisions. Stakeholders must monitor hydrogen supply chain readiness and carbon pricing trajectory to time fuel cell capital commitments against diesel generator refresh cycles.
Market Dynamics
The transition from diesel backup generators to hydrogen-compatible fuel cells is compressing capital planning cycles across Canadian data center portfolios, forcing operators to synchronize equipment refresh schedules with provincial clean energy mandates and hydrogen supply chain maturation.
Growth Catalysts
- Federal carbon pricing:The Greenhouse Gas Pollution Pricing Act escalates operating costs for diesel-dependent facilities, redirecting capital toward proton-exchange-membrane fuel cell trials in Ontario and Quebec.
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning multi-hundred-megawatt facilities in Toronto, Montreal, and Vancouver corridors, concentrating demand for medium-voltage switchgear and modular UPS architectures.
- Lithium-ion density improvements:Higher energy density chemistries are reducing battery room footprints by half, unlocking real estate value in constrained urban sites where land scarcity limits traditional lead-acid deployments.
Market Restraints
- Copper and silicon carbide supply concentration:Power semiconductor fabrication concentrates in Taiwan and Germany, exposing Canadian UPS and rectifier procurement to geopolitical transit risks and extended lead times.
- Hydrogen infrastructure gaps:Provincial hydrogen hub development lags behind fuel cell procurement timelines, forcing operators to maintain dual-fuel capabilities and duplicate capital reserves.
- CSA C22.2 certification timelines:Canadian electrical equipment certification requires 8-14 months for novel fuel cell integration packages, delaying revenue recognition on innovative backup power projects.
Strategic Opportunities
- Atlantic Canada latency arbitrage:Newfoundland and Labrador offer sub-30ms transatlantic fiber routes to Europe with abundant hydroelectric capacity, creating positioning advantages for financial services co-location.
- Alberta carbon capture co-location:Oil sands carbon capture utilization and storage infrastructure enables negative-emission data center claims, differentiating facilities for ESG-constrained enterprise tenants.
- Edge computing in secondary cities:Latency-sensitive manufacturing automation and autonomous vehicle mapping in Kitchener-Waterloo, Calgary, and Edmonton is generating distributed power requirements below 10MW per site.
Industry Challenges
- Medium-voltage technician scarcity:Specialized skills for 15kV-35kV switchgear commissioning and maintenance concentrate among retiring utility workforces, constraining project velocity in hyperscale builds.
- Legacy DC plant integration:Existing 48V and 400V direct current infrastructure in carrier hotels and enterprise colocation facilities complicates hybrid AC-DC power architecture standardization during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Power Market |
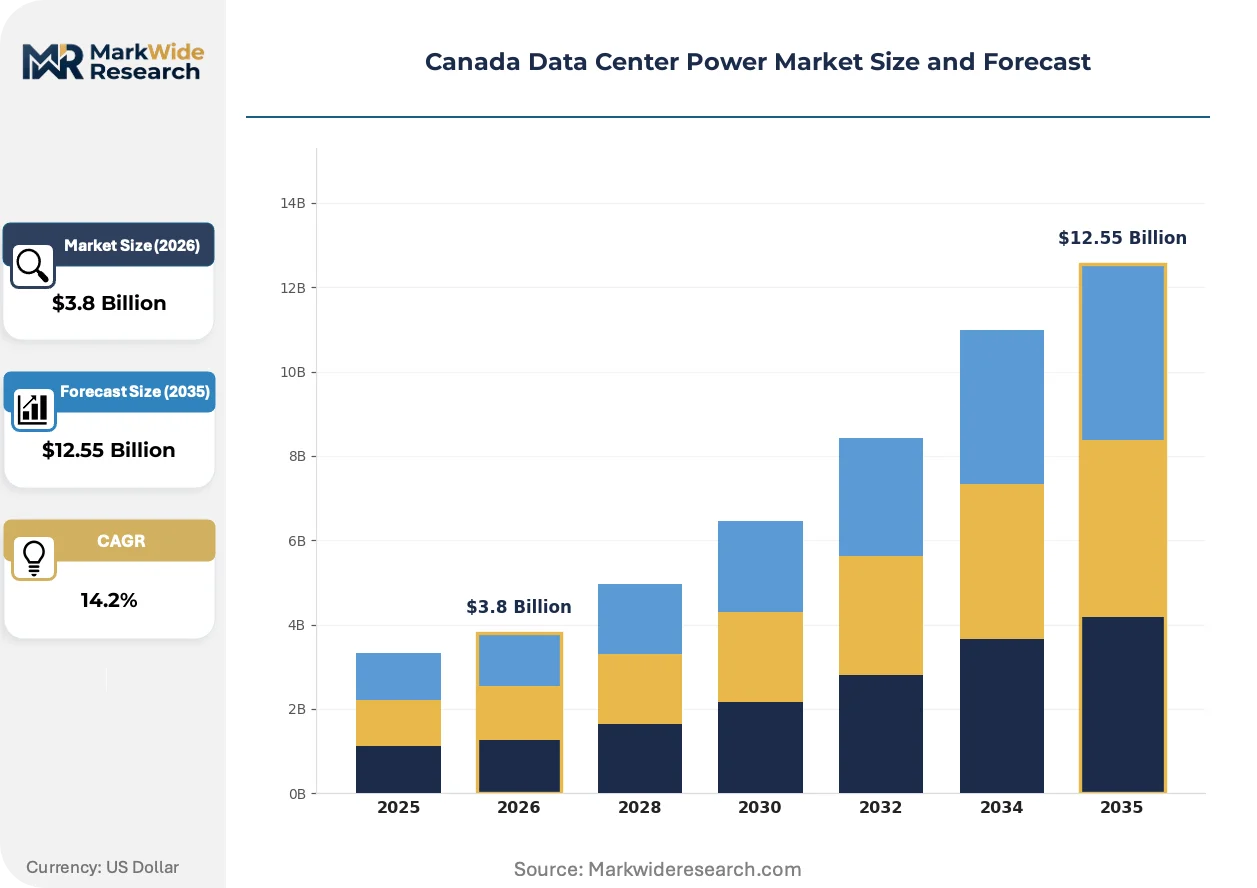
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Generator, Inverter, Fuel Cell Application: Colocation, Cloud Computing, Enterprise, Edge Computing End User: IT Services, Telecommunications, Financial Services, Healthcare Size: Small, Medium, Large, Hyperscale |
| Companies Covered | Schneider Electric SE, ABB Ltd., Eaton Corporation, Vertiv Group Corp., Cummins Inc., Delta Electronics, Generac Holdings Inc., Legrand SA, Cisco Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Power Market Trends and Innovations
Hydrogen fuel cell systems are moving from pilot validation to procurement specifications, while provincial regulators tighten emissions disclosure requirements and hyperscale operators compress equipment replacement cycles to meet carbon neutrality commitments.
Solid-oxide fuel cells operating on reformed natural gas are absorbing mid-duration backup requirements previously served by diesel generators in Ontario facilities. Colocation operators in the Toronto corridor are specifying 10-20 minute fuel cell bridging capacity for grid outage events. This technology is absorbing capital allocations that would have flowed to generator set upgrades, compressing the addressable market for traditional reciprocating engine suppliers.
Environment and Climate Change Canada's proposed Clean Electricity Regulations are mandating net-zero emissions from new natural gas-fired generation by 2035, with interim reporting obligations beginning in 2025. Data center operators are pre-positioning fuel cell and battery storage combinations to avoid stranded asset risk on gas turbine investments. The regulation most directly affects planned facilities in Alberta and Saskatchewan where grid carbon intensity remains highest.
Power purchase agreement structures are evolving from volumetric energy contracts to 24/7 carbon-free energy matching, requiring hourly generation source verification. Financial services and SaaS tenants in Montreal and Vancouver are demanding time-stamped renewable energy certificates tied to specific hydroelectric or wind assets. This behavioral shift is most visible among hyperscale operators with public net-zero commitments, who are now rejecting annual-matched renewable energy claims as insufficient for scope 2 accounting.
Canada Data Center Power Market Segmentation
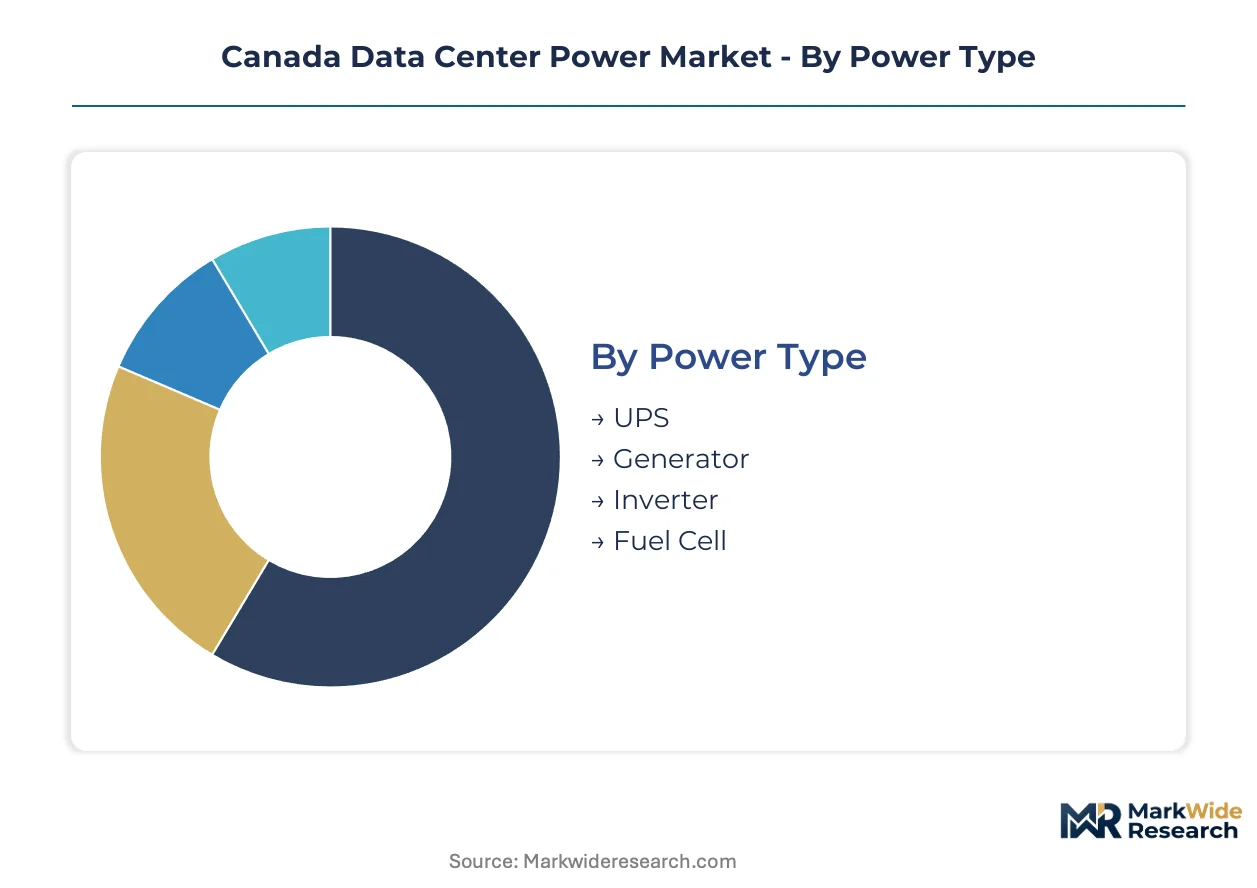
Power infrastructure segmentation in Canada data centers reveals how equipment selection varies with facility scale and workload criticality. Distinct procurement patterns emerge across backup duration requirements, tenant density models, and provincial grid reliability profiles.
Power Type:
Standalone power systems dominate capital expenditure in greenfield hyperscale builds, while embedded UPS modules integrate into prefabricated electrical skids for faster deployment timelines.
- UPS:Lithium-ion battery chemistry now displaces valve-regulated lead-acid in Toronto and Montreal facilities, cutting battery room footprints by half while extending runtime at higher discharge rates. Health Canada electrical safety standards govern these installations.
- Generator:Diesel and natural gas reciprocating engines remain the largest revenue pool, though Environment and Climate Change Canada emissions regulations are compressing replacement cycles in Alberta and Saskatchewan.
- Inverter:Static inverter systems bridge sub-cycle power interruptions in carrier hotels and financial services colocation facilities across Vancouver.
- Fuel Cell:Proton-exchange-membrane systems are gaining procurement traction in Ontario and Quebec as provincial hydrogen hub development accelerates.
Volume placements concentrate in Generator systems; the faster expansion belongs to Fuel Cell technology.
Application:
Cost tier stratification separates mission-critical cloud workloads from latency-tolerant enterprise deployments, with edge sites occupying a distinct value band below ten megawatts.
- Colocation:Multi-tenant facilities in Toronto and Montreal corridors specify modular UPS architectures to accommodate diverse tenant redundancy requirements without overprovisioning.
- Cloud Computing:Hyperscale operators commission dedicated medium-voltage switchgear and 2N electrical topologies for single-tenant campuses exceeding one hundred megawatts.
- Enterprise:Private data centers in Calgary and Edmonton favor hybrid fuel cell-battery combinations to meet internal carbon neutrality commitments.
- Edge Computing:Distributed sites in Kitchener-Waterloo and secondary cities demand sub-10MW power systems with rapid deployment timelines for autonomous vehicle mapping workloads.
Revenue concentration sits with Cloud Computing deployments; Edge Computing is climbing the fastest as manufacturing automation spreads beyond primary metros.
End User:
Customer type determines redundancy tier selection, with financial services and healthcare mandating 2N configurations while telecommunications tolerates N+1 architectures in less critical routing facilities.
- IT Services:SaaS providers in Vancouver prioritize 24/7 carbon-free energy matching through time-stamped renewable certificates tied to specific hydroelectric assets.
- Telecommunications:Carrier hotels in Toronto maintain legacy 48V DC plant infrastructure, complicating hybrid AC-DC standardization during technology transitions.
- Financial Services:Trading co-location facilities in Montreal demand sub-30ms transatlantic latency, driving power system selection alongside fiber route proximity.
- Healthcare:Hospital data centers in Ontario and Quebec face Health Canada emissions disclosure requirements for on-site generation.
Procurement volume clusters with IT Services; Healthcare is gaining share fastest as provincial health authorities consolidate digital infrastructure.
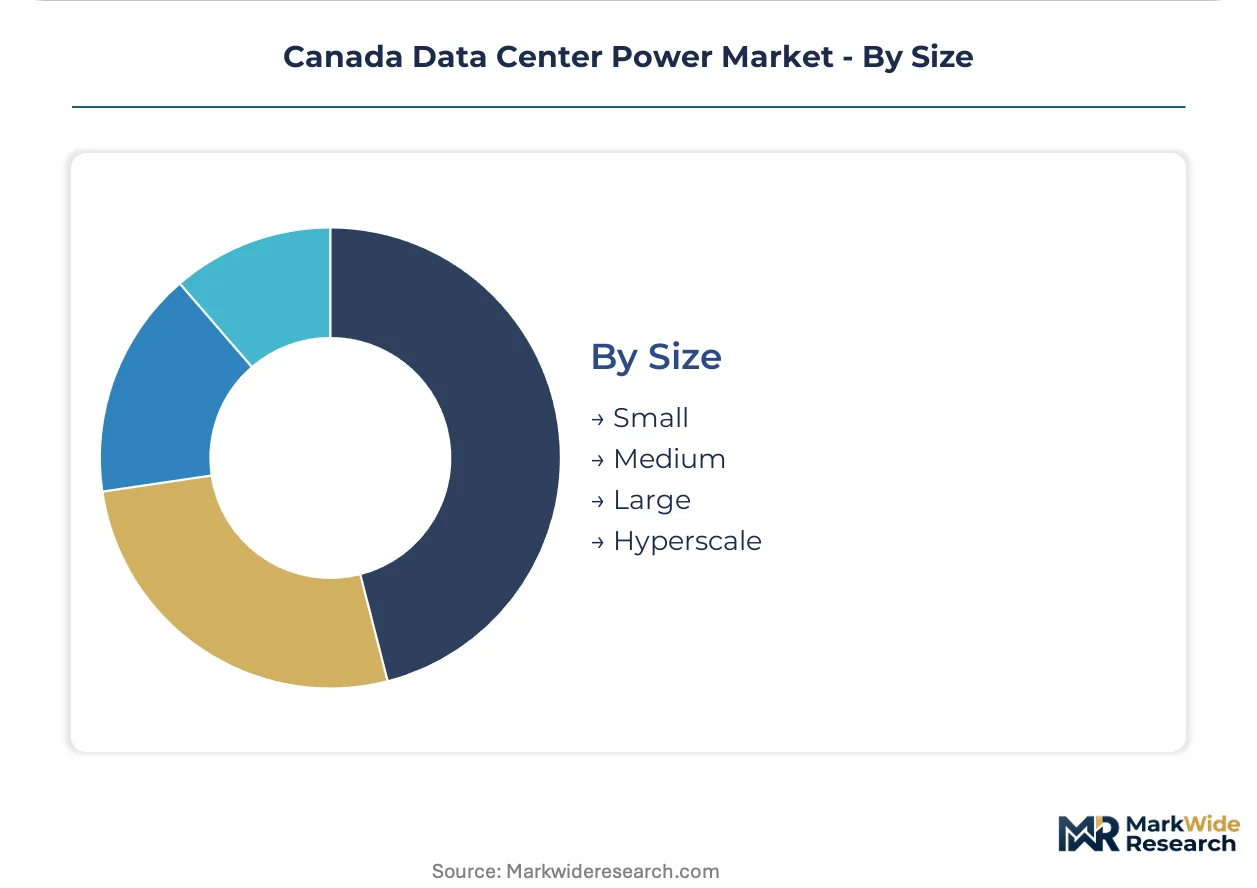
Size:
Maturity gradients separate established hyperscale design patterns from emerging standardization in small and medium facilities, where equipment refresh cycles lag larger counterparts.
- Small:Facilities below one megawatt in secondary cities rely on packaged UPS-generator sets with limited fuel cell integration due to capital constraints.
- Medium:Ten-to-fifty megawatt sites in Calgary and Edmonton are piloting solid-oxide fuel cells for mid-duration backup previously served by diesel.
- Large:Enterprise campuses in Vancouver specify 10-20 minute fuel cell bridging capacity to satisfy tenant ESG requirements.
- Hyperscale:Multi-hundred-megawatt facilities in Toronto and Montreal corridors concentrate demand for specialized medium-voltage power distribution architectures.
Capital deployment concentrates in Hyperscale facilities; Medium-sized sites are expanding most quickly as edge computing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate new capacity in three provincial corridors where hydroelectric baseload and fiber connectivity converge. Provincial carbon pricing regimes and interconnection rules now determine site selection as much as latency targets.
Ontario
Amazon Web Services and Microsoft Azure commission multi-hundred-megawatt campuses in the Toronto corridor, driving procurement of medium-voltage switchgear and modular UPS architectures. The Ontario Energy Board governs interconnection timelines for data center loads exceeding 50MW. Toronto's financial services co-location density creates hybrid demand for both hyperscale cloud and low-latency trading infrastructure.
Quebec
Hydro-Québec's surplus baseload capacity and sub-5 cents per kilowatt-hour industrial rates attract carbon-conscious hyperscale operators. The province's hydrogen hub development accelerates fuel cell pilot programs in Montreal-area facilities. Schneider Electric SE leverages local manufacturing to anchor large-scale electrical infrastructure projects serving cloud campuses.
British Columbia
Vancouver's Pacific fiber landing points and seismic risk profiles shape redundant power architecture specifications for SaaS providers. BC Hydro's clean energy mandate aligns with tenant demands for 24/7 carbon-free energy matching through time-stamped renewable certificates. Enterprise campuses in the Lower Mainland specify fuel cell bridging capacity to satisfy ESG requirements.
Alberta
Calgary and Edmonton facilities pilot solid-oxide fuel cells for mid-duration backup as oil sands carbon capture infrastructure enables negative-emission claims. The province's grid carbon intensity remains highest nationally, exposing operators to federal clean electricity regulations mandating net-zero generation by 2035. Edge computing demand from autonomous vehicle mapping spreads distributed power requirements across secondary cities.
Atlantic Canada
Newfoundland and Labrador offer sub-30ms transatlantic fiber routes to Europe with abundant hydroelectric capacity from Churchill Falls. Financial services co-location targeting European latency arbitrage drives specialized power system selection alongside fiber route proximity. Provincial energy boards in Nova Scotia and New Brunswick evaluate interconnection rules for emerging data center clusters.
Canada Data Center Power Market Competitive Landscape
Capacity expansion dominates the current landscape as hyperscale procurement timelines compress vendor qualification cycles. The vendor base stratifies across three tiers: integrated electrical infrastructure platforms, specialized power quality and thermal-electrical integration specialists, and generator set and fuel cell engine manufacturers. Strategic archetypes include full-stack platform providers, component specialists, and backup power engine suppliers. Geographic proximity to provincial manufacturing incentives and CSA C22.2 certification capabilities determine competitive positioning.
Within the integrated platform tier, Schneider Electric SE and ABB Ltd. anchor procurement decisions for hyperscale campuses requiring unified electrical and digital infrastructure. Eaton Corporation occupies a position among specialized power distribution architects competing through medium-voltage expertise. Vertiv Group Corp. exemplifies thermal-electrical integration specialists sustaining pricing power in large-scale bids. Cummins Inc. represents backup power engine manufacturers navigating the transition from diesel reciprocating systems to hydrogen-compatible fuel cell platforms.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd. |
| Eaton Corporation |
| Vertiv Group Corp. |
| Cummins Inc. |
| Delta Electronics |
| Generac Holdings Inc. |
| Legrand SA |
| Cisco Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into hydrogen fuel cell stack manufacturing anchors both supply security and margin protection for Canadian data center power vendors navigating CSA C22.2 certification requirements. Equipment suppliers with captive production of proton-exchange-membrane components command pricing power against modular competitors dependent on Taiwanese semiconductor foundries.
Pricing Analysis
Volume placements concentrate in diesel generator systems with compressed margins; margin-rich fuel cell integrations capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates CSA-certified integrated platforms from uncertified imports and refurbished equipment. Cost compression in standard-tier UPS modules is intensifying because lithium-ion cell supply concentrates among South Korean and Chinese producers. Edge computing deployments below 10MW demonstrate highest price sensitivity; hyperscale cloud operators with 2N redundancy requirements show lowest sensitivity to per-kilowatt capital costs.
Supply Chain Analysis
CSA C22.2 certification timelines of 8-14 months gate supplier qualification and compress the vendor pool to established players with Canadian regulatory expertise. Power semiconductor fabrication concentrates in Taiwan and Germany; battery cell production centers on South Korea and China. Copper busbar and silicon carbide wafer dependencies expose procurement to geopolitical transit risks. Distribution runs through electrical infrastructure EPCs with provincial utility relationships rather than direct OEM-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada data center power functions as a cost-of-compliance market where CSA C22.2 certification and provincial hydrogen hub alignment create barrier-to-entry moats for prepared vendors. Environment and Climate Change Canada's Clean Electricity Regulations force capital commitment timing decisions that favor incumbent certification holders.
For Market Incumbents: Cement market position by accelerating CSA C22.2 pre-certification of hydrogen-compatible fuel cell integration packages before provincial mandates tighten. Lock in multi-year service contracts with Toronto and Montreal hyperscale operators to defend against emerging solid-oxide fuel cell specialists. Priority lever: captive technician training programs addressing medium-voltage switchgear scarcity. For New Entrants and Emerging Players: Solid-oxide fuel cells operating on reformed natural gas offer a technology-first wedge into Alberta's oil sands carbon capture corridor where incumbent presence remains thin. Target medium-scale enterprise campuses in Calgary and Edmonton piloting hybrid fuel cell-battery combinations. Go-to-market angle: negative-emission data center claims leveraging provincial carbon capture infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated electrical infrastructure platforms seeking fuel cell capabilities. Long-term viability favors vendors with demonstrated CSA certification velocity and Hydro-Québec interconnection relationships. Signal to watch: provincial hydrogen hub procurement timelines accelerating fuel cell adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| CSA C22.2 Pre-Certification Investment | Eight-to-fourteen-month approval gates favor early movers with established Health Canada relationships. |
| Provincial Hydrogen Hub Partnership | Ontario and Quebec hub development accelerates fuel cell procurement specifications for backup power. |
| Medium-Voltage Technician Apprenticeship | Retiring utility workforces create scarcity premium for commissioning and maintenance capabilities. |
| 24/7 Carbon-Free Energy Matching | Time-stamped renewable certificates satisfy hyperscale tenant scope 2 accounting requirements. |
| Edge Computing Power System Miniaturization | Sub-10MW distributed sites in Kitchener-Waterloo demand rapid-deployment electrical skids. |
Research Methodology
SEC filings from hyperscale cloud operators, Hydro-Québec interconnection disclosure documents, and Environment and Climate Change Canada regulatory dockets formed the secondary backbone for market sizing. Primary fieldwork encompassed interviews with data center facility directors, electrical infrastructure procurement managers, medium-voltage switchgear commissioning specialists, and provincial utility interconnection planners. Bottom-up equipment shipment analysis triangulated against top-down hyperscale capex disclosure to validate revenue estimates.
Historical trendline analysis of generator set, UPS, and fuel cell procurement patterns informed projection assumptions across the analysis window. Segmentation dimensions modeled include power type, application tier, end-user vertical, and facility size class alongside provincial regulatory framework clusters. CAGRs derived from equipment replacement cycle compression rates and provincial clean energy mandate adoption curves. Forecast inputs incorporated hydrogen supply chain maturation timelines and CSA certification queue lengths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated federal carbon pricing escalation or Taiwan semiconductor supply disruption scenarios. Model outputs reflect documented assumptions regarding provincial hydrogen hub development schedules and hyperscale cloud expansion commitments. A model refresh is warranted upon material change in Clean Electricity Regulations implementation timelines or Hydro-Québec industrial rate structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Poland Data Center Construction Market