
 Robotic Air Purifier Market | 2026-2036
Robotic Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Air Purifier Market Analysis
Chinese electronics manufacturing is recalibrating component sourcing for autonomous mobility platforms. Ecovacs Robotics Co. Ltd. leverages its established robot vacuum supply chain to anchor production scale for purification units. Dyson Group Co. differentiates through proprietary cyclone filtration integrated with SLAM navigation. Coway Co. Ltd. sustains brand strength in Asian residential channels through localized filter ecosystems.
A robotic air purifier combines autonomous mobile robotics with multi-stage filtration systems, typically incorporating HEPA media rated at 99.97% efficiency for 0.3-micron particles, UV-C germicidal chambers, and real-time particulate sensors to navigate contaminated zones without human intervention. The device serves commercial and institutional environments where fixed-position units leave coverage gaps. The residential segment leads unit volume due to smart home integration demand, while the HEPA technology category captures premium pricing through medical-grade certification requirements. Hospitals and schools represent the fastest-growing end user verticals as post-pandemic building standards mandate continuous air turnover.
The US EPA enforces National Ambient Air Quality Standards that push commercial facilities toward continuous monitoring solutions, while the EU Ecodesign Directive and REACH frameworks constrain filter material composition and disposal pathways. China's SAMR oversees robotic product safety certifications under GB standards that govern autonomous navigation reliability. Stakeholders must monitor evolving interoperability protocols between building management systems and mobile purification fleets.
Market Dynamics
Autonomous navigation reliability is consolidating as the decisive technical barrier separating viable commercial deployments from pilot-stage failures. EPA indoor air quality enforcement and OSHA ventilation mandates are compressing upgrade timelines for institutional buyers, while Chinese manufacturing clusters concentrate component supply for mobility platforms.
Growth Catalysts
- OSHA ventilation standards:Commercial facilities in the United States face mandatory air turnover compliance, forcing building managers toward continuous monitoring solutions that mobile purification units provide.
- HEPA media certification:Medical-grade filtration requirements from healthcare accreditation bodies are elevating specification floors for hospital procurement teams evaluating robotic systems.
- Urban pollution clusters:Manufacturing zones in China generate concentrated demand for autonomous air quality management where fixed-position units cannot achieve coverage.
Market Restraints
- LiDAR sensor cost volatility:Autonomous navigation depends on optical components whose pricing fluctuates with semiconductor foundry capacity allocation.
- Filter supply concentration:Activated carbon and HEPA media production clusters in Southeast Asia create single-source vulnerability for assembly operations.
- EU Ecodesign Directive:REACH framework constraints on filter material composition and disposal pathways extend product development timelines for European market entry.
Strategic Opportunities
- US school infrastructure:Post-pandemic building standards mandate continuous air turnover in educational facilities, creating a procurement wave for mobile purification fleets.
- SLAM-IoT convergence:Simultaneous localization and mapping integration with building management systems enables predictive contamination response and premium service tiers.
- India BIS certification pathway:Bureau of Indian Standards robotic safety frameworks are formalizing, opening regulated market access for compliant manufacturers ahead of competitor entry.
Industry Challenges
- Autonomous systems engineering talent:Mobile robotics firmware development requires specialized skill sets that compete with autonomous vehicle and drone sectors for limited personnel.
- GB standard navigation certification:China's SAMR reliability testing protocols for robotic product safety extend validation timelines before commercial deployment authorization.
- Legacy HVAC integration:Building management system interoperability protocols vary across facility vintages, complicating fleet coordination software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Air Purifier Market |
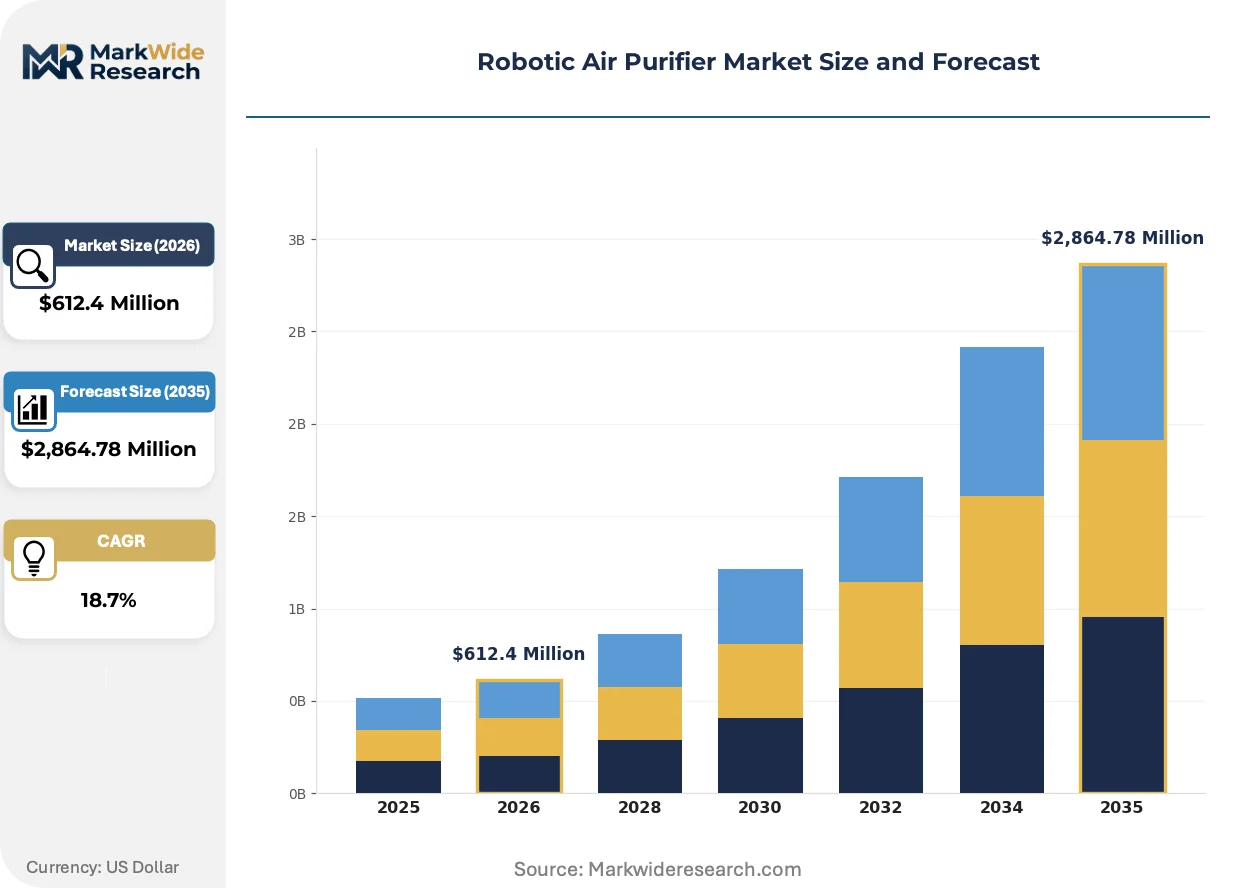
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Residential, Industrial, Portable Technology: HEPA, UV-C, Activated Carbon, Ionizer Application: Indoor Air Quality, Odor Removal, Allergy Relief, Smoke Elimination End User: Households, Offices, Hospitals, Schools |
| Companies Covered | Diqee Intelligent Henan Corp. Ltd., Coway Co. Ltd., Ecovacs Robotics Co. Ltd., Milagrow Humantech, Unilever PLC, iRobot Corp., Samsung Electronics Co. Ltd., Partnering Robotics, Dyson Group Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Air Purifier Market Emerging Trajectories
Sensor fusion architectures are compressing the technical gap between consumer-grade robot vacuums and institutional air purification platforms. Multi-modal environmental detection is enabling context-aware navigation that distinguishes between particulate zones and obstacle fields.
UV-C germicidal chamber integration with HEPA filtration stages is consolidating as the standard configuration for healthcare-adjacent deployments. Hospitals and outpatient clinics specify this dual-mode decontamination to satisfy joint commission accreditation requirements. The technology is consolidating premium pricing tiers previously reserved for fixed-installation medical-grade systems.
EPA National Ambient Air Quality Standards enforcement is tightening continuous monitoring obligations for commercial facilities above specified occupancy thresholds. Building operators must document air turnover rates and particulate levels, creating compliance documentation requirements that mobile sensor platforms address. United States healthcare and education verticals are responding with pilot programs that validate autonomous purification against fixed-unit baselines.
Institutional procurement teams are compressing vendor evaluation cycles through pre-certified equipment lists. Hospital purchasing cooperatives and school district consortiums aggregate demand around interoperability-tested platforms, displacing single-facility pilot programs. This concentration is most visible in United States metropolitan healthcare systems where standardization reduces facility management complexity across distributed real estate portfolios.
Robotic Air Purifier Market Segmentation
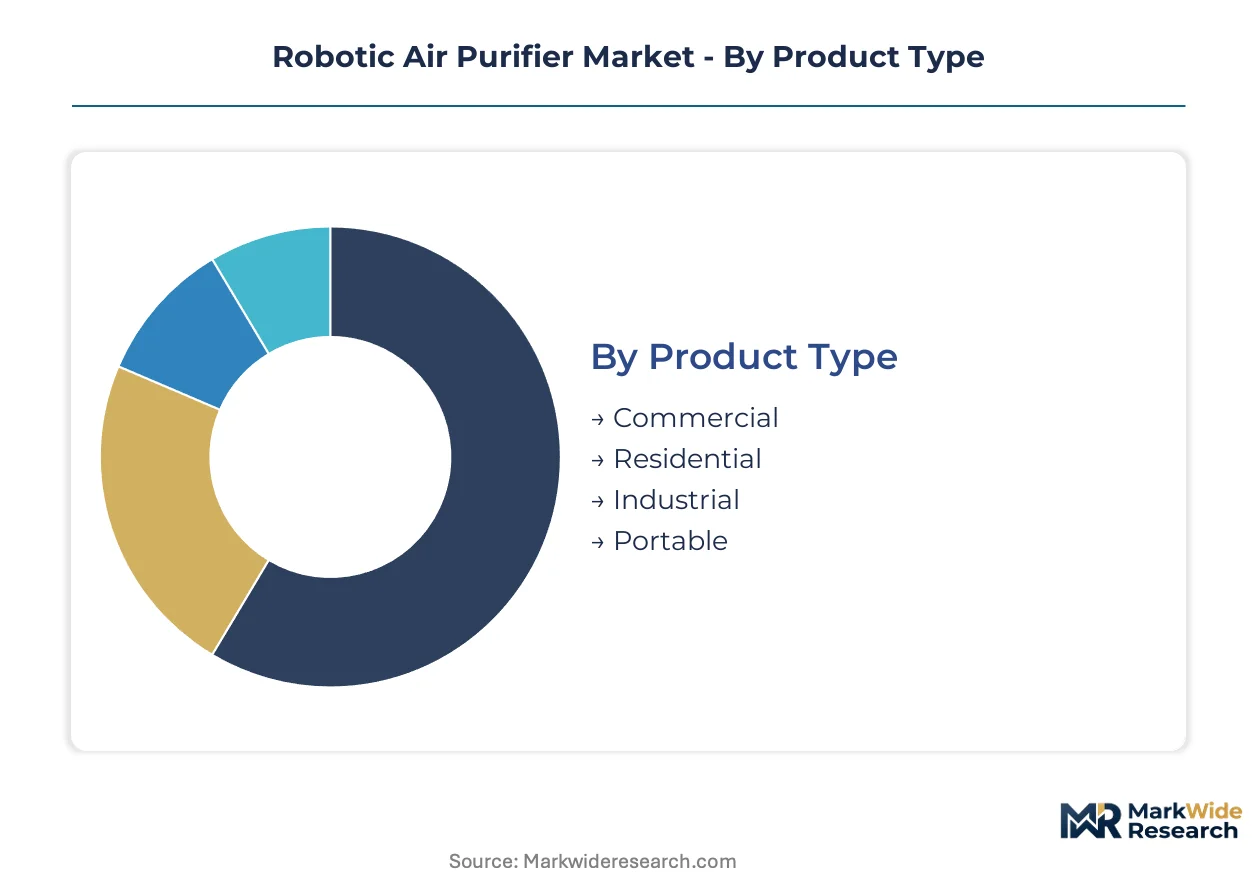
Segmentation in the robotic air purifier market reveals how autonomous mobility requirements diverge across deployment contexts. Component sourcing strategies and certification pathways differ materially between residential convenience applications and institutional compliance mandates.
Product Type:
Supply concentration for navigation modules and filtration media varies sharply across installation scales, with component vendors calibrating production runs to match replacement cycle economics.
- Commercial:Units integrate enterprise fleet management software with SLAM-based multi-room coverage protocols. Demand concentrates in United States healthcare systems where joint commission accreditation mandates continuous air turnover documentation.
- Residential:Devices emphasize smart home interoperability and compact form factors for apartment deployment. China absorbs the dominant share of unit volume through manufacturing cluster proximity and urban pollution sensitivity.
- Industrial:Heavy-duty filtration assemblies address manufacturing floor contaminant loads with extended service intervals.
- Portable:Battery-powered variants serve temporary event spaces and construction remediation with reduced autonomy ranges.
Commercial installations absorb the bulk of installed capacity; residential units are expanding most quickly.
Technology:
Cost tier differentiation separates medical-grade certification premiums from consumer accessibility, with filter replacement economics driving total cost of ownership calculations.
- HEPA:99.97% efficiency at 0.3 microns remains the specification baseline for institutional procurement. Hospitals in the United States require medical-grade certification that elevates pricing through validation documentation.
- UV-C:Germicidal chambers target biological contamination in healthcare-adjacent environments. Outpatient clinics specify dual-mode HEPA-UV configurations to satisfy accreditation requirements.
- Activated Carbon:Adsorption media addresses volatile organic compounds in commercial renovation contexts.
- Ionizer:Electrostatic precipitation offers maintenance-reduced operation for residential price-sensitive segments.
HEPA configurations command the premium tier; UV-C integration is climbing the fastest through healthcare specification expansion.
Application:
Customer type priorities determine sensor fusion complexity, with compliance-driven buyers funding particulate specificity that convenience-oriented segments bypass.
- Indoor Air Quality:Multi-parameter sensing platforms monitor PM2.5, CO2, and VOC concentrations for building management system integration. United States school districts deploy fleets to satisfy post-pandemic ventilation mandates.
- Odor Removal:Activated carbon loading targets hospitality and food service environments with rapid saturation detection.
- Allergy Relief:HEPA-dominant configurations address residential pollen and dust mite sensitivities.
- Smoke Elimination:High-CADR designs serve wildfire-prone geographies in the western United States.
Indoor air quality monitoring dominates institutional procurement; smoke elimination is gaining share fastest through climate-driven demand spikes.
End User:
Volume concentration in consumer channels contrasts with margin concentration in regulated institutional verticals where certification barriers limit vendor competition.
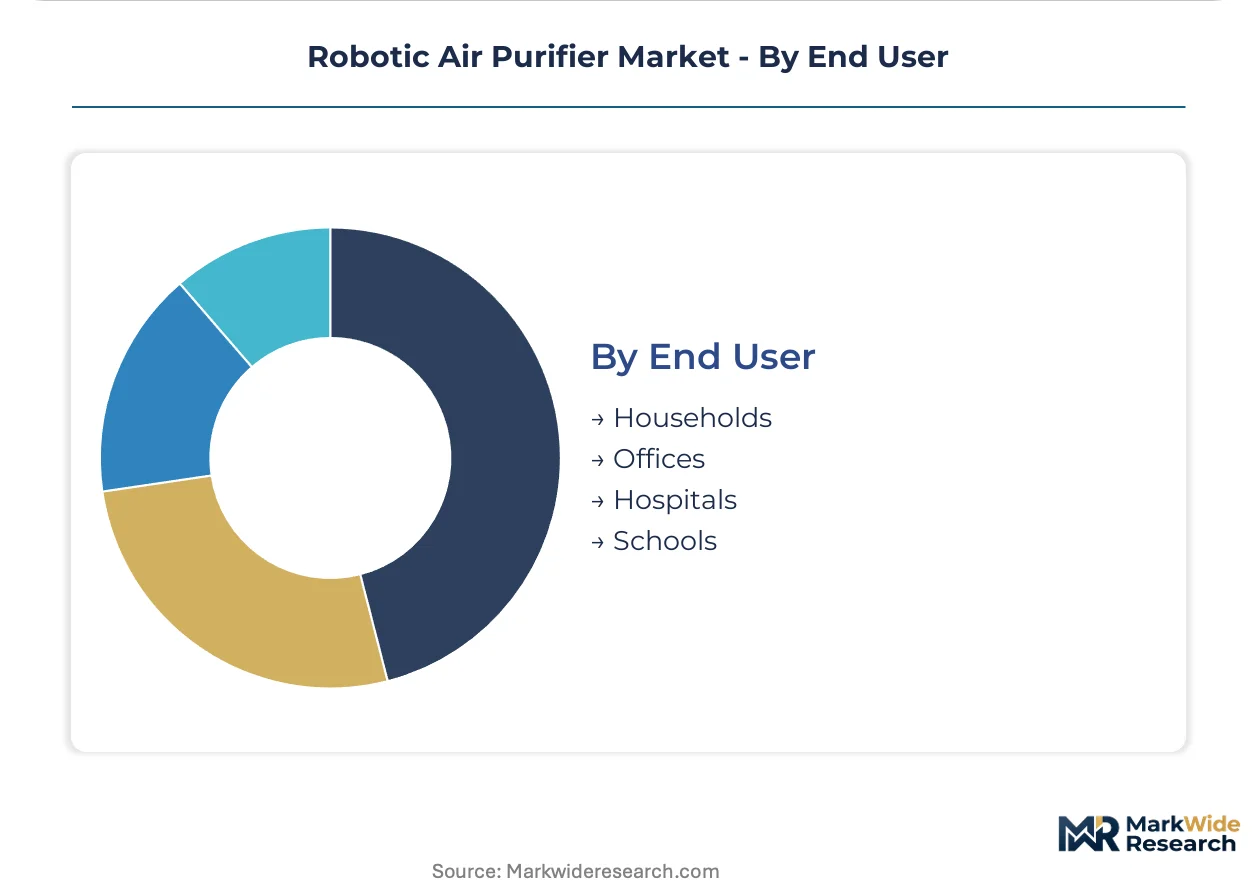
- Hospitals:Infection control protocols specify autonomous purification for isolation room turnover and surgical suite preparation. EPA indoor air quality guidelines and joint commission standards compress evaluation timelines.
- Schools:District-level purchasing cooperatives aggregate demand around interoperability-tested platforms. United States metropolitan systems standardize across distributed real estate portfolios to reduce facility management complexity.
- Households:Smart home integration drives replacement cycles through filter subscription services.
- Offices:Corporate real estate managers evaluate mobile units against fixed-installation HVAC upgrades.
Hospitals anchor the premium tier; schools represent the steepest expansion trajectory through infrastructure modernization funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Activated carbon and HEPA media production clusters in Southeast Asia anchor component sourcing for robotic air purifier assembly. Manufacturing gravity for navigation modules concentrates in East Asian semiconductor foundries. Regulatory divergence across major economies is fragmenting certification pathways and compressing product development timelines.
United States
Healthcare systems in Texas and California are expanding pilot programs for autonomous purification fleets in surgical suites. EPA indoor air quality enforcement and OSHA ventilation mandates compress upgrade timelines for institutional buyers. The Boston metropolitan area anchors hospital procurement consortiums that aggregate demand around interoperability-tested platforms.
China
Manufacturing clusters in the Yangtze River Delta and Pearl River Delta generate concentrated demand for autonomous air quality management. SAMR oversees robotic product safety certifications under GB standards that govern autonomous navigation reliability. Shenzhen-based electronics fabricators recalibrate component sourcing for mobility platforms serving both domestic and export markets.
Germany
Commercial real estate managers in Frankfurt and Munich evaluate mobile units against fixed-installation HVAC upgrades. The EU Ecodesign Directive and REACH frameworks constrain filter material composition and disposal pathways. The Baden-Württemberg industrial corridor hosts precision engineering firms supplying sensor fusion components for navigation systems.
Japan
Residential smart home integration drives replacement cycles through filter subscription services in Tokyo and Osaka. METI energy efficiency guidelines influence product specification floors for domestic appliance certification. The Nagoya manufacturing belt supplies compact motor assemblies for robotic mobility platforms.
India
Urban pollution sensitivity in Delhi-NCR and Mumbai accelerates deployment of autonomous purification robots in commercial complexes. BIS robotic safety frameworks are formalizing under Bureau of Indian Standards pathways, opening regulated market access. The Maharashtra industrial corridor is emerging as an assembly location for mobility platforms targeting South Asian distribution.
Robotic Air Purifier Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent robotics applications for air quality management. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive robotics divisions, pure-play autonomous appliance specialists, and contract manufacturers serving white-label procurement. Three archetypes dominate: vacuum-to-purification extenders leveraging existing SLAM navigation stacks, HVAC incumbents adding mobility modules to filtration portfolios, and industrial automation firms repurposing warehouse robotics for environmental monitoring. Capacity expansion and strategic partnerships represent the dominant competitive moves, with tier-one players securing exclusive component allocation from Southeast Asian filter suppliers.
Among Asia-Pacific-based fabricators, Ecovacs Robotics Co. Ltd. and Coway Co. Ltd. exemplify the vacuum-to-purification extension archetype, while Dyson Group Co. occupies a position within the premium-tier engineering cluster. Samsung Electronics Co. Ltd. represents diversified conglomerate participation, and iRobot Corp. anchors the North American specialist tier. These named entities serve as reference points for understanding competitive positioning without attributing specific strategic actions or market share claims to individual firms.
| Leading Market Players |
|---|
| Diqee Intelligent Henan Corp. Ltd. |
| Coway Co. Ltd. |
| Ecovacs Robotics Co. Ltd. |
| Milagrow Humantech |
| Unilever PLC |
| iRobot Corp. |
| Samsung Electronics Co. Ltd. |
| Partnering Robotics |
| Dyson Group Co. |
| Others |
Supply Flow & Price Mechanics
LiDAR sensor modules flow from East Asian semiconductor foundries through three distinct pricing tiers before reaching institutional buyers in United States healthcare systems. Component cost volatility in optical navigation hardware compresses margins for mid-tier assemblers while medical-grade certification documentation elevates premium-tier pricing for hospital procurement teams.
Pricing Analysis
Warranty bundling separates commercial fleet contracts from residential direct-to-consumer sales, with institutional buyers purchasing multi-year service agreements that include filter replacement logistics and SLAM navigation recalibration. Pricing stratifies across premium, standard, and economy tiers based on HEPA certification grade and sensor fusion complexity. Cost compression in the residential segment intensifies because Chinese manufacturing clusters generate surplus capacity for compact mobility platforms. School districts exhibit highest price sensitivity due to aggregated procurement budgets, while hospital infection control departments prioritize accreditation compliance over unit cost.
Supply Chain Analysis
Ocean freight routing from Southeast Asian filter media plants to Shenzhen assembly hubs adds cost volatility that ripples through finished goods pricing. HEPA media production draws from Thailand and Vietnam, while LiDAR components source from Taiwan and South Korea. Single-source vulnerability concentrates in activated carbon supply where Indonesian mining operations feed specialty chemical processors. Distribution runs through electronics wholesale channels for residential units and direct OEM contracting for institutional fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component cost volatility and certification documentation burdens are forcing subscale assemblers toward exit or acquisition, consolidating viable vendor participation around capitalized platform specialists.
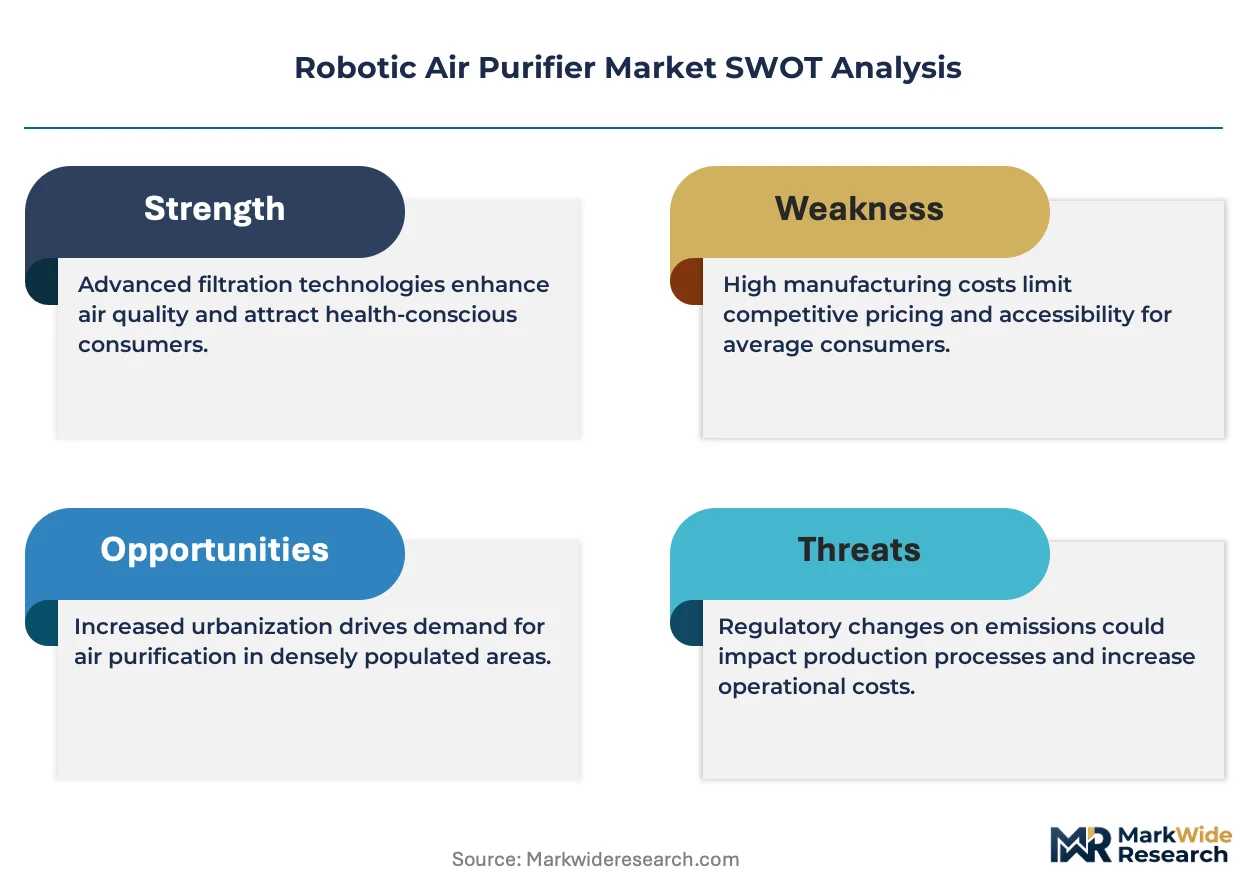
For Market Incumbents: Hedge against LiDAR supply disruption by securing dual-source optical component agreements with Taiwanese and South Korean foundries. Deepen backward integration into HEPA media finishing operations to capture margin from Thailand-based substrate suppliers. Prioritize GB standard pre-certification for autonomous navigation reliability to accelerate SAMR approval timelines ahead of competitor submissions. For New Entrants and Emerging Players: Begin with white-label contract manufacturing for United States school district consortiums where aggregated demand reduces customer acquisition cost and standardization requirements limit feature competition. Target portable battery-powered variants for event services and construction remediation, segments where reduced autonomy range requirements lower technical barriers to viable product-market fit. Pursue direct procurement relationships with Indian commercial real estate developers ahead of formal BIS robotic safety framework completion. For Investors and Strategic Acquirers: SAMR navigation certification backlog clearance is the leading indicator that Chinese market access is tightening and acquisition premiums for pre-certified asset bases will expand. Frame long-term viability around captive filter ecosystem control and SLAM-IoT software stack ownership rather than hardware assembly margin. Monitor EPA enforcement action intensity against commercial facility indoor air quality violations as the signal for institutional procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SLAM-IoT Platform Integration | Enables predictive contamination response for hospital building management system interoperability. |
| GB Standard Pre-Certification | Accelerates SAMR commercial deployment authorization for autonomous navigation reliability claims. |
| Filter Media Backward Integration | Captures margin from Thai and Vietnamese HEPA substrate suppliers serving Southeast Asian production clusters. |
| School District Consortium Partnership | Aggregates United States educational procurement demand around interoperability-tested fleet platforms. |
| Indian BIS Compliance Pathway | Opens regulated market access ahead of competitor entry as Bureau of Indian Standards frameworks formalize. |
Methodological Framework
Document review covered EPA enforcement databases, OSHA ventilation standard guidance documents, SAMR robotic product safety circulars, and EU Ecodesign Directive implementation texts, complemented by interviews with hospital biomedical engineering directors, school district facilities managers, commercial real estate portfolio operators, and robotics OEM procurement leads. Secondary validation drew from customs trade data for LiDAR and filtration media imports, SEC filings of listed appliance manufacturers, and building management system interoperability protocol documentation. Bottom-up unit shipment estimates triangulated against top-down addressable facility counts across healthcare, education, and commercial verticals.
Historical volume trajectories cross-referenced against panel input from component suppliers and fleet operators informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, filtration technology tier, end-user vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates and replacement cycle compression in institutional settings. Industry-specific inputs incorporated EPA indoor air quality enforcement intensity indices and hospital accreditation mandate adoption curves.
Underlying measurement precision varies by segment; hospital and school procurement data carry tighter precision than residential channel estimates where distributor reporting gaps persist. Forecasts reflect assumptions about SAMR certification timeline stability and OSHA ventilation mandate enforcement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market