
 United Kingdom Bariatric Surgery Market | 2026-2036
United Kingdom Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Bariatric Surgery Market Analytics
UK surgical device manufacturers is broadening capacity for minimally invasive bariatric platforms. Medtronic PLC leverages its laparoscopic instrument portfolio to anchor hospital supply contracts across NHS trusts. Johnson & Johnson sustains competitive positioning through its Ethicon division's specialized energy devices for gastric tissue sealing. Intuitive Surgical Inc dominates robotic-assisted bariatric procedures with its da Vinci system installations in tertiary referral centers.
Bariatric surgery encompasses metabolic and gastrointestinal interventions that alter stomach anatomy or digestive physiology to induce sustained weight reduction, typically employing stapling devices, adjustable bands, or intestinal rerouting with specific restrictions on staple line integrity and anastomotic diameter. Sleeve gastrectomy leads procedural volume among product type categories, while gastric bypass retains higher reimbursement intensity in private payer segments. Robotic-assisted technology commands premium positioning in hospital accounts, whereas laparoscopic approaches occupy mainstream clinical adoption across NHS-funded programs.
The MHRA enforces post-market surveillance for implantable gastric devices under UK medical device regulations, while NICE publishes evidence-based commissioning guidelines that shape regional funding allocation for metabolic surgery. NHS England's specialized commissioning framework restricts bariatric procedure authorization to designated centers meeting minimum annual volume thresholds. Stakeholders must monitor evolving MHRA recognition routes for EU-CE marked devices and NICE technology appraisal updates that could redistribute access between NHS and private surgical pathways.
Market Dynamics
NHS England's metabolic surgery expansion is compressing patient flow into designated high-volume centers while MHRA post-market surveillance requirements reshape device procurement criteria across hospital trusts.
Growth Catalysts
- Metabolic Surgery Criteria Expansion:NHS England's broadened referral protocols for type 2 diabetes remission are channeling eligible patients toward hospital-based sleeve gastrectomy and gastric bypass procedures.
- Robotic Platform Diffusion:Tertiary referral centers in Greater London and the West Midlands are installing da Vinci surgical systems to capture premium reimbursement for minimally invasive bariatric interventions.
- NICE Technology Appraisals:Evidence-based commissioning guidelines from the National Institute for Health and Care Excellence are standardizing regional funding allocation and reducing postcode variation in metabolic surgery access.
Market Restraints
- Specialized Center Concentration:NHS England's minimum annual volume thresholds restrict bariatric procedure authorization to designated centers, limiting geographic access and creating patient travel burdens.
- Implantable Device Surveillance:MHRA post-market surveillance requirements under UK medical device regulations impose extended clinical follow-up obligations and compliance documentation costs on gastric device manufacturers.
- Laparoscopic Stapler Supply:Hospital supply contracts for specialized energy devices and stapling platforms concentrate procurement leverage with established instrument portfolios, raising barriers for novel device entrants.
Strategic Opportunities
- West Midlands Patient Flow:Private clinic chains are concentrating demand for robotic-assisted bariatric interventions in Birmingham and surrounding metropolitan areas underserved by NHS-designated centers.
- EU-CE Mark Recognition Routes:Evolving MHRA recognition pathways for EU-CE marked devices could accelerate market entry timelines for continental European manufacturers seeking UK hospital contracts.
- Adjustable Band Conversion:Secondary revision procedures for patients with prior gastric band implants represent an emerging application segment as sleeve gastrectomy displaces earlier-generation devices.
Industry Challenges
- Bariatric Surgeon Pipeline:NHS training program capacity constraints limit the annual output of fellowship-qualified metabolic surgeons capable of meeting minimum volume thresholds for designated center accreditation.
- Anastomotic Leak Surveillance:Staple line integrity monitoring and post-operative complication tracking require specialized nursing protocols and extended length-of-stay protocols that compress hospital bed utilization.
- Legacy Band Device Liability:Long-term follow-up obligations for explanted adjustable gastric bands create ongoing litigation exposure and insurance cost pressures for historical device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Bariatric Surgery Market |
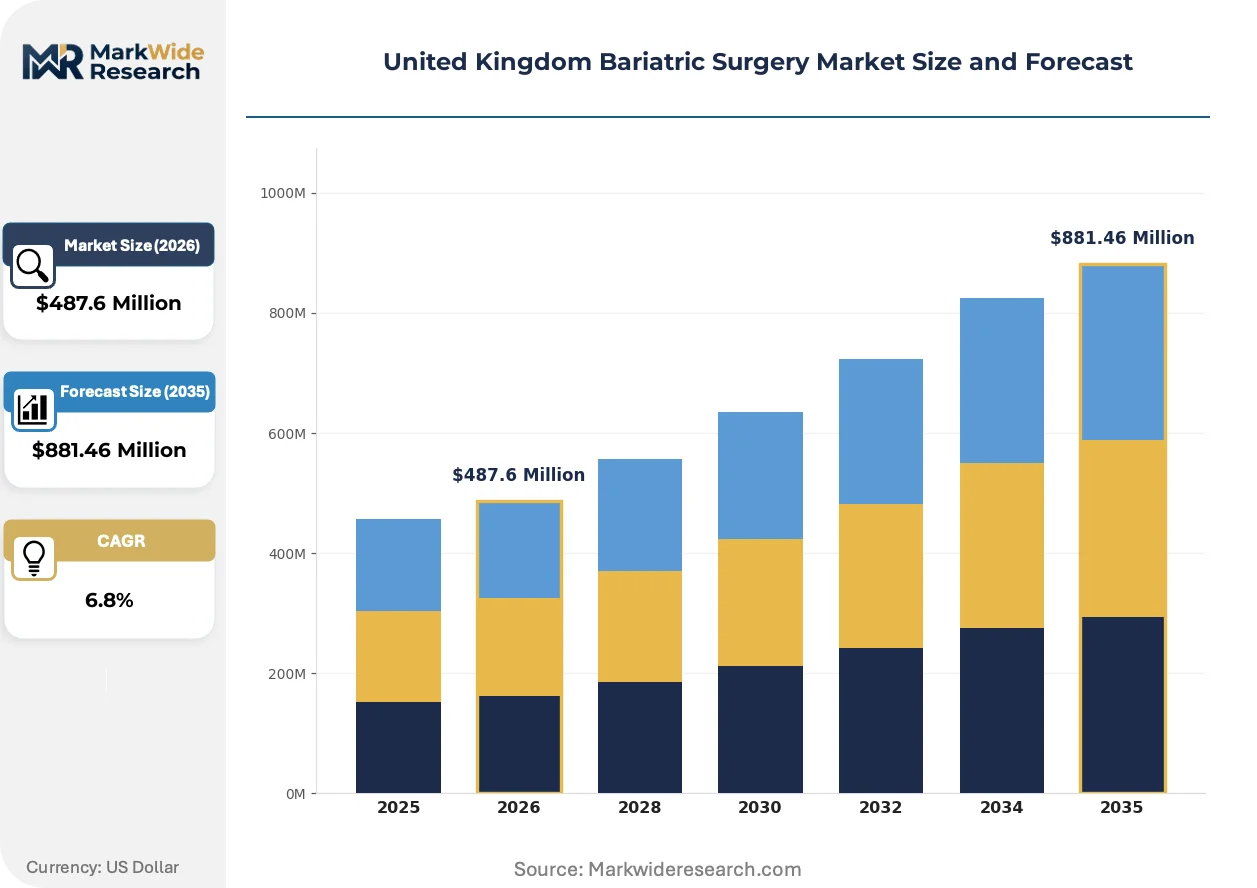
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sleeve Gastrectomy, Gastric Bypass, Adjustable Gastric Banding, Biliopancreatic Diversion End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Technology: Laparoscopic, Robotic-Assisted, Open Surgery, Endoscopic Age Group: Adults, Adolescents, Seniors, Others |
| Companies Covered | Olympus Corporation, Apollo Endosurgery Inc, Johnson & Johnson, Cook Medical, Conmed Corporation, Medtronic PLC, B Braun SE, Teleflex, Intuitive Surgical Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Bariatric Surgery Market Evolving Landscape
Robotic surgical platforms and single-anastomosis techniques are reshaping procedural economics while regulatory recognition frameworks realign cross-border device supply chains.
Single-anastomosis gastric bypass is consolidating technical preference among metabolic surgeons seeking reduced operative time and comparable weight loss outcomes to traditional Roux-en-Y configurations. NHS trusts with established robotic programs are adopting this modification for appropriate patient cohorts. The technique is consolidating market share from conventional bypass approaches in high-volume tertiary centers.
NICE technology appraisals for implantable gastric devices are tightening evidence thresholds for NHS commissioning, requiring randomized trial data for novel mechanisms of action. MHRA recognition routes for EU-CE marked devices are creating parallel assessment pathways that delay UK market entry for continental innovations. Private payer segments are responding faster than NHS-funded programs to device category expansions.
Hospital procurement committees are consolidating vendor relationships for laparoscopic instrument portfolios around supply contracts that bundle energy devices with stapling platforms. NHS trusts are displacing standalone device negotiations in favor of multi-year agreements with guaranteed service levels and training support. This concentration is most visible in Greater London academic medical centers managing high bariatric case volumes.
United Kingdom Bariatric Surgery Market Segmentation
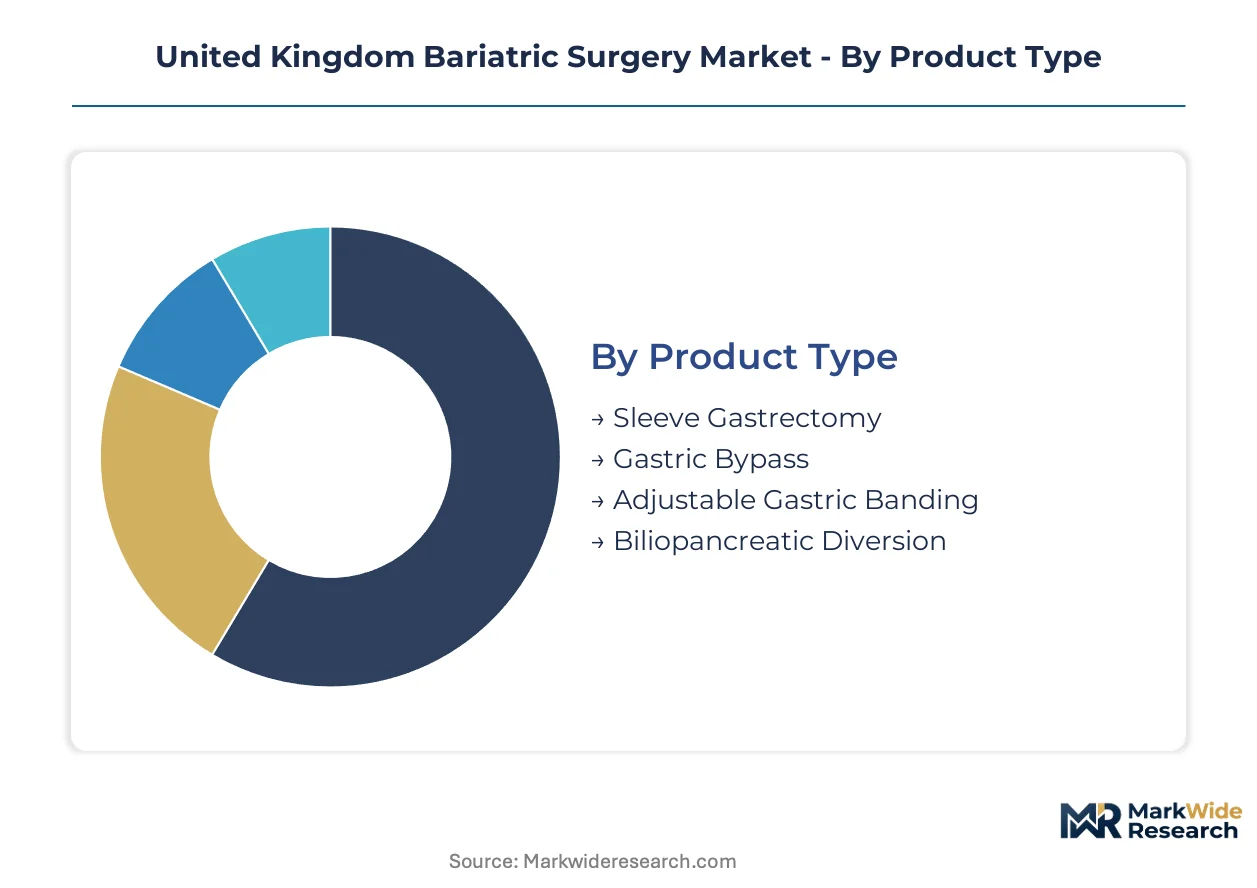
Segmentation in the United Kingdom bariatric surgery market reveals how NHS commissioning frameworks and MHRA device regulations concentrate demand across distinct procedural and institutional categories. Each segment carries differentiated approval burdens and reimbursement intensity that shape manufacturer strategy and hospital procurement priorities.
Product Type:
MHRA device classification determines pre-market authorization intensity, with implantable gastric systems requiring extended clinical follow-up protocols under UK medical device regulations compared to purely stapling-based interventions.
- Sleeve Gastrectomy:This procedure removes approximately 80% of the stomach along the greater curvature, creating a tubular gastric reservoir. NHS England's metabolic surgery expansion has concentrated demand for sleeve gastrectomy in designated high-volume centers across Greater London and the West Midlands, where minimum annual volume thresholds concentrate surgeon expertise and compress patient waiting lists.
- Gastric Bypass:Roux-en-Y gastric bypass creates a small gastric pouch and reroutes the small intestine to induce malabsorption alongside restriction. Private payer segments in Birmingham and Manchester metropolitan areas sustain premium reimbursement rates for this technically demanding procedure, particularly where robotic-assisted platforms reduce operative time and anastomotic complication rates.
- Adjustable Gastric Banding:Legacy device category with declining NHS commissioning volumes; MHRA post-market surveillance obligations for explanted bands create ongoing liability exposure for historical manufacturers.
- Biliopancreatic Diversion:Most technically complex metabolic procedure with restricted NHS authorization; reserved for super-obese patients in tertiary referral centers with specialized nutritional support protocols.
Leading the category by volume: Sleeve Gastrectomy. Expanding most quickly: Gastric Bypass in private hospital segments.
End User:
Institutional purchasing power varies sharply across the National Health Service's specialized commissioning framework versus independent sector treatment centers.
- Hospitals:NHS trusts and private hospital groups dominate procedural volume through multi-year supply contracts bundling laparoscopic instruments with energy devices. Academic medical centers in Greater London leverage da Vinci system installations to capture tertiary referrals for complex revision cases.
- Clinics:Independent sector treatment centers concentrate demand for straightforward sleeve gastrectomy procedures, particularly in West Midlands metropolitan corridors where NHS-designated centers remain geographically sparse.
- Ambulatory Surgical Centers:Limited penetration in bariatrics due to MHRA requirements for overnight monitoring of staple line integrity and anastomotic leak surveillance.
- Home Care:Emerging post-discharge monitoring segment for nutritional counseling and complication triage; NICE guidelines increasingly emphasize structured follow-up protocols outside acute settings.
Procurement concentration favors: Hospitals. Fastest institutional expansion: Clinics in underserved metropolitan zones.
Technology:
Capital intensity and training requirements create tiered adoption patterns across NHS-funded and private reimbursement pathways.
- Laparoscopic:Standard-of-care approach occupying mainstream clinical adoption across NHS-funded programs; hospital supply contracts for specialized stapling platforms concentrate vendor relationships with established instrument portfolios.
- Robotic-Assisted:Premium positioning in tertiary referral centers with established da Vinci programs; Greater London academic medical centers capture differential reimbursement for minimally invasive precision in complex bypass procedures.
- Open Surgery:Reserved for revision cases and super-obese patients where laparoscopic access proves technically unfeasible; declining volume share as minimally invasive platforms diffuse.
- Endoscopic:Emerging category for primary obesity intervention without gastric incision; NICE technology appraisals require randomized trial evidence before NHS commissioning authorization.
Dominant platform by case volume: Laparoscopic. Steepest expansion trajectory: Robotic-Assisted in private hospital accounts.
Age Group:
Eligibility criteria and metabolic comorbidity profiles shape referral patterns across NHS England's specialized commissioning framework.
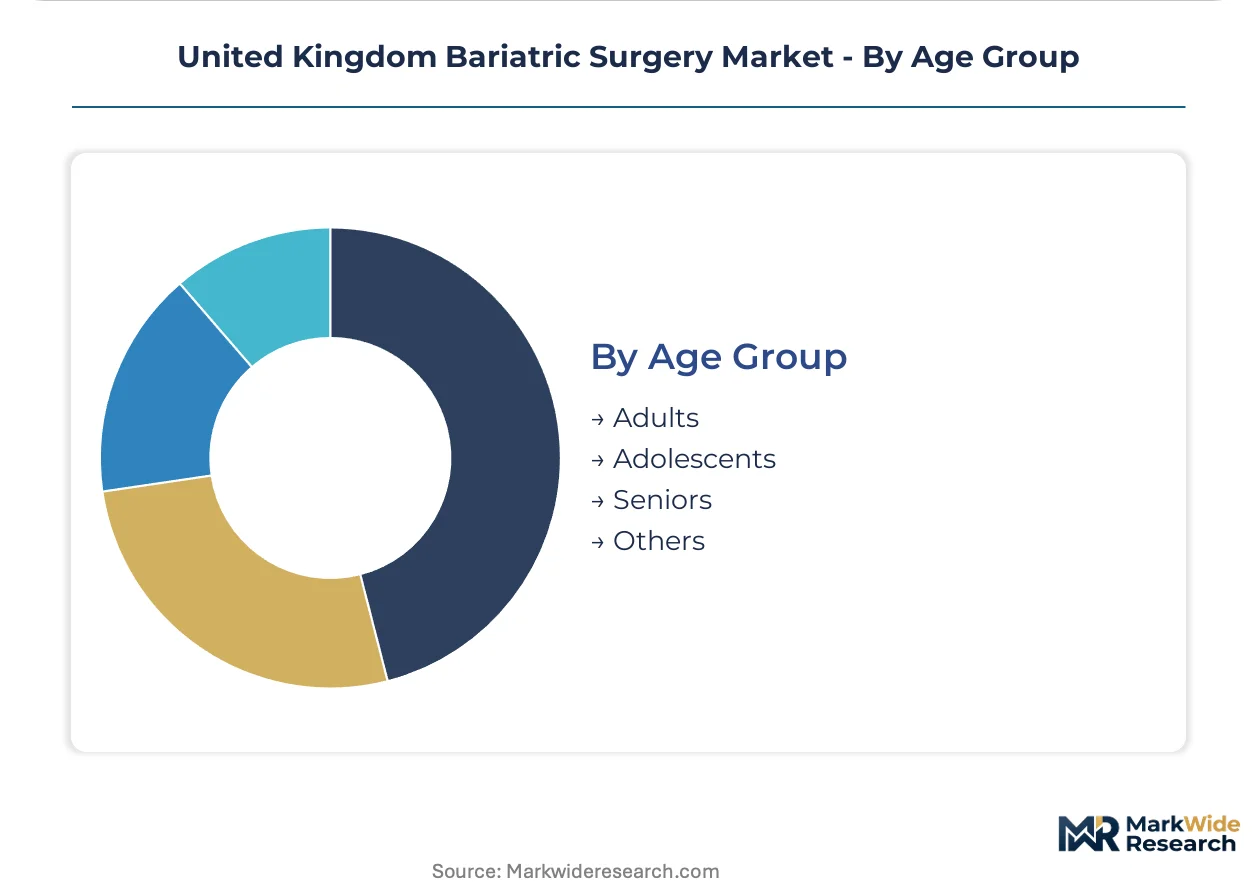
- Adults:Core demographic with established NICE referral protocols for type 2 diabetes remission; NHS trusts prioritize this cohort for sleeve gastrectomy and gastric bypass procedures.
- Adolescents:Restricted authorization requiring multidisciplinary team assessment and pediatric metabolic surgery expertise; concentrated in designated national centers with extended follow-up obligations.
- Seniors:Growing referral segment as metabolic surgery criteria expand to older patients with cardiovascular risk profiles; perioperative risk stratification protocols concentrate demand in high-volume centers.
- Others:Captures exceptional cases including pre-transplant optimization and secondary prevention populations; requires individual funding request pathways outside standard NHS commissioning.
Largest treated population: Adults. Gaining share fastest: Seniors as referral thresholds relax.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metabolic surgery demand concentrates in England's urban corridors where NHS commissioning frameworks and private hospital networks overlap. London anchors the largest procedural volume through academic medical centers and independent sector treatment centers.
London and the Southeast
NHS England's specialized commissioning framework channels sleeve gastrectomy and gastric bypass referrals into designated high-volume centers across Greater London. NICE technology appraisals standardize evidence thresholds for metabolic surgery authorization across Barts Health and Guy's and St Thomas' NHS Foundation Trusts. Tertiary referral centers in central London deploy da Vinci surgical systems to capture complex revision cases and premium private payer segments.
West Midlands
Private clinic chains concentrate demand for robotic-assisted bariatric interventions in Birmingham and surrounding metropolitan areas underserved by NHS-designated centers. The MHRA's post-market surveillance requirements for implantable gastric devices shape procurement criteria across University Hospitals Birmingham NHS Foundation Trust. Metropolitan corridors between Birmingham and Coventry attract independent sector investment in ambulatory metabolic surgery capacity.
North England
Manchester and Leeds academic medical centers sustain regional metabolic surgery networks through NHS England's minimum annual volume thresholds. NHS specialized commissioning restricts bariatric procedure authorization to designated centers, compressing patient flow into Manchester University NHS Foundation Trust and Leeds Teaching Hospitals NHS Trust. Surgeon training pipelines through Health Education England's North West and Yorkshire programs feed fellowship-qualified specialists into these high-volume centers.
Scotland
NHS Scotland's territorial health boards coordinate metabolic surgery referrals through centralized bariatric services in Glasgow and Edinburgh. Scottish Health Technologies Group assessments parallel NICE appraisals in evaluating evidence for novel gastric devices. NHS Greater Glasgow and Clyde operates the largest procedural volume north of the border, with private Edinburgh clinics capturing cross-border referrals from northern England.
United Kingdom Bariatric Surgery Market Competitive Landscape
Global majors compete with regional champions across device portfolios and hospital supply contracting. The United Kingdom bariatric surgery market structures around three tiers: diversified surgical conglomerates anchoring multi-year NHS trust agreements, specialized metabolic device manufacturers, and robotic platform specialists capturing premium private accounts. Consolidation pressures favor vendors bundling stapling instruments with energy devices and service support. Strategic moves concentrate on securing designated center supply contracts and navigating MHRA recognition pathways for EU-CE marked innovations.
Among diversified surgical conglomerates, Medtronic PLC and Johnson & Johnson occupy positions anchoring hospital supply contracts across NHS trusts through laparoscopic instrument portfolios and specialized energy devices. Intuitive Surgical Inc exemplifies the robotic platform specialist archetype, with da Vinci system installations in tertiary referral centers capturing differential reimbursement for minimally invasive precision. Olympus Corporation represents the endoscopic and visualization equipment segment serving both NHS-funded and private metabolic surgery pathways.
| Leading Market Players |
|---|
| Olympus Corporation |
| Apollo Endosurgery Inc |
| Johnson & Johnson |
| Cook Medical |
| Conmed Corporation |
| Medtronic PLC |
| B Braun SE |
| Teleflex |
| Intuitive Surgical Inc |
| Others |
Value Network & Pricing Analysis
Fellowship-qualified metabolic surgeons concentrated in Greater London and the West Midlands command substantial labor-cost premiums that propagate through three-tier pricing spreads across NHS and private reimbursement pathways. Their scarcity relative to minimum-volume center accreditation requirements compresses supply-side flexibility and anchors pricing power with established high-volume providers.
Pricing Analysis
Warranty and extended-service bundling separate premium robotic-assisted procedure tiers from unbundled laparoscopic alternatives in hospital supply contracts. Three-tier pricing structure across premium, standard, and economy levels reflects da Vinci system availability, surgeon accreditation status, and post-operative monitoring intensity. Cost compression in standard laparoscopic tiers intensifies because NHS procurement committees consolidate multi-year vendor agreements with guaranteed training support. Private payer segments in Birmingham and Manchester metropolitan areas exhibit least price sensitivity for robotic platforms, while NHS-funded programs prioritize standard laparoscopic approaches with stringent cost controls.
Supply Chain Analysis
Titanium alloy and surgical-grade polymer inputs rest on German, Swiss, and US specialty materials producers with MHRA-recognized quality certifications. Robotic instrument consoles, laparoscopic stapling cartridges, and energy-sealing devices anchor procurement dependencies for UK hospital trusts. Single-source vulnerability concentrates in da Vinci system maintenance contracts and proprietary instrument disposables. Distribution runs through centralized NHS Supply Chain frameworks for public hospitals alongside direct manufacturer agreements with private hospital groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
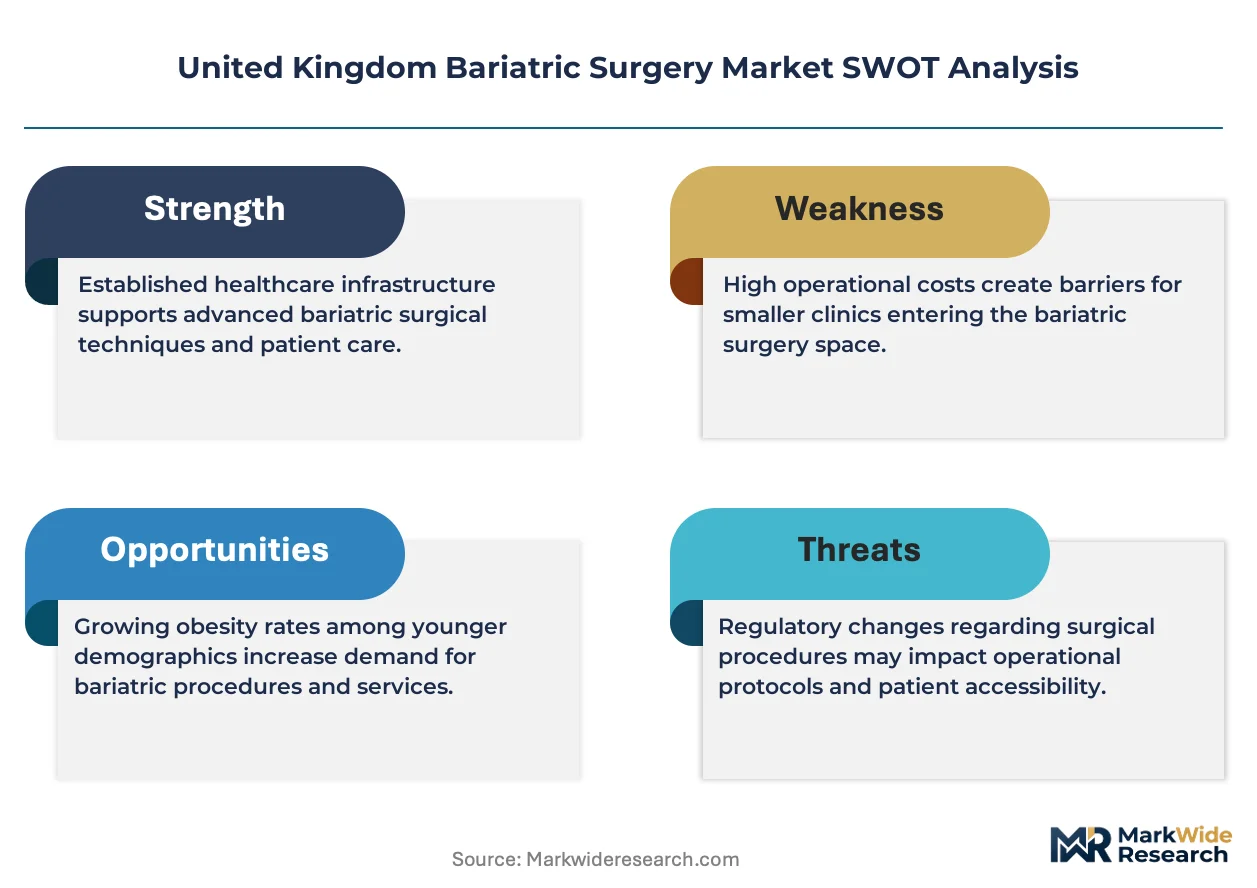
MHRA post-market surveillance obligations for implantable gastric devices erect substantial compliance-cost barriers that protect accredited incumbents while filtering undercapitalized entrants from designated center supply contracts.
For Market Incumbents: Hedge against robotic platform commoditization by securing exclusive service-level agreements with Greater London academic medical centers before EU-CE mark recognition routes accelerate continental competitor entry. Deepen backward integration into specialized energy-device manufacturing to defend margin position against bundled procurement consolidation. Monitor NICE technology appraisal timelines for endoscopic device categories that could displace stapling-based procedures in diabetes remission protocols. For New Entrants and Emerging Players: Capture unmet demand in West Midlands metropolitan corridors where NHS-designated center geographic sparsity channels patients toward independent sector treatment centers. Target adjustable gastric band conversion and revision procedure segments as sleeve gastrectomy displaces legacy implants. Pursue GPO contracts with private clinic chains as the most penetrable institutional pathway outside NHS trust procurement concentration. For Investors and Strategic Acquirers: The window for entry favors specialized metabolic device manufacturers with MHRA-authorized quality management systems and established surgeon training infrastructure. Long-term viability hinges on consolidation plays that bundle stapling platforms with energy devices and robotic service contracts. Watch NICE commissioning guideline updates for type 2 diabetes remission criteria as the signal indicating reimbursement expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Authorized Representative Appointment | Establishes UK regulatory presence for EU-CE marked device manufacturers seeking hospital contracts. |
| Surgeon Training Program Accreditation | Health Education England fellowship partnerships secure pipeline access for high-volume center staffing. |
| NICE Technology Appraisal Submission | Evidence-based commissioning guidelines determine NHS funding allocation for novel gastric interventions. |
| Multi-Year NHS Trust Supply Agreement | Procurement consolidation favors vendors bundling instruments with service support and training protocols. |
| Private Clinic Chain Partnership | Independent sector treatment centers in underserved metropolitan zones accelerate market access outside NHS frameworks. |
Research Methodology
NHS England specialized commissioning frameworks, MHRA device registration databases, and NICE technology appraisal records formed the secondary backbone for market sizing and regulatory pathway mapping. Primary interviews with bariatric surgeons, hospital procurement managers, biomedical engineers, and GPO contracts specialists validated procedural volume estimates and supply contract structures. Bottom-up procedure counts across designated centers triangulated against top-down expenditure data from NHS Digital and private hospital group disclosures.
Historical trendline analysis of sleeve gastrectomy and gastric bypass volumes informed projection modeling across the analysis window. Segmentation dimensions encompassed product type, end user institution, technology platform, and patient age cohort alongside regional commissioning cluster variations. CAGRs derived from weighted average of procedure volume trajectories and reimbursement rate evolution, with robotic-assisted platform diffusion and metabolic surgery criteria expansion as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NICE guideline revisions, MHRA recognition route negotiations with EU regulators, and training program capacity constraints. Forecasts reflect documented assumptions regarding NHS funding continuity and private payer premium sustainability. A small set of named triggers—surgeon pipeline output, anastomotic leak surveillance protocol changes, and EU-CE mark mutual recognition agreements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market