
 Functional Milk Replacers Market | 2026-2036
Functional Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Milk Replacers Market Foresight
China is narrowing its functional milk replacer capacity gap through investments in domestic spray-drying facilities and whey protein processing infrastructure. Cargill leverages backward integration into soy protein concentrate production to secure formulation consistency across Asian supply chains. FrieslandCampina anchors European demand through specialized calf nutrition portfolios developed at its Dutch research campus. Archer Daniels Midland competes on oilseed processing scale, converting canola and soy into lipid fractions optimized for young animal digestion.
Functional milk replacers are nutritionally engineered substitutes formulated from plant proteins, dairy derivatives, lipids, carbohydrates, and micronutrients to replicate the growth-supporting properties of whole milk in neonatal animals and targeted human populations. Spray-drying at controlled inlet temperatures preserves protein denaturation thresholds critical for amino acid bioavailability in monogastric digestive systems. Protein-Enriched formulations dominate value pools due to premium positioning in performance livestock segments and sports nutrition applications. Probiotic-Infused products represent the fastest-expanding category as microbiome research validates gut colonization benefits in pre-weaned calves. Powder formulations sustain manufacturing margin advantages through extended shelf stability and reduced logistics costs relative to liquid alternatives.
The FDA's Center for Veterinary Medicine oversees ingredient safety claims and manufacturing standards for animal-directed milk replacers in the United States. The European Food Safety Authority evaluates novel protein sources and additive approvals under the EU Feed Additives Regulation, directly shaping product development timelines for formulations entering continental markets. China's National Health Commission and Ministry of Agriculture and Rural Affairs coordinate standards for cross-border nutritional products, creating compliance complexity for imported formulations. Stakeholders must monitor evolving microbiome health claims regulation and regional protein self-sufficiency targets to anticipate formulation investment priorities.
Market Dynamics
The functional milk replacers sector pivots on protein sourcing concentration, as spray-drying infrastructure and whey processing capacity cluster in select dairy-producing regions, forcing formulators to secure captive supply chains or absorb volatile input costs.
Growth Catalysts
- EU Feed Hygiene Regulation:Mandatory safety protocols across member states compel investment in quality-assured manufacturing, elevating barrier to entry for subscale producers and consolidating demand around certified suppliers.
- Probiotic microbiome science:Validated gut colonization benefits in pre-weaned calves accelerate category expansion as dairy operations prioritize neonatal health outcomes over cost-minimization.
- China's domestic herd expansion:Accelerated dairy cow inventory growth generates concentrated demand for specialized nutritional inputs that domestic supply chains cannot yet fully satisfy.
Market Restraints
- Whey protein supply concentration:Processing capacity clusters in European and North American dairy belts, exposing Asian formulators to freight cost volatility and currency risk.
- EFSA novel protein evaluation timelines:Extended additive approval processes under EU Feed Additives Regulation delay product launches by 18-36 months, compressing commercialization windows.
- Whole milk price arbitrage:Regional dairy surplus periods erode milk replacer cost advantage, particularly in pasture-based systems with direct farmgate supply.
Strategic Opportunities
- Spray-drying localization in China:Greenfield investments in domestic whey fractionation and drying infrastructure reduce import dependency and capture margin from growing calf nutrition demand.
- Sports nutrition cross-application:Protein-enriched formulations developed for livestock performance segments migrate to human athletic recovery products, opening dual-use revenue streams.
- USDA conservation program alignment:Environmental Quality Incentives Program incentives for reduced antibiotic use create regulatory tailwind for probiotic-infused calf nutrition protocols.
Industry Challenges
- Spray-drying thermal control expertise:Precise inlet temperature management to preserve protein denaturation thresholds requires specialized process engineering talent scarce outside established dairy processing regions.
- Dual jurisdiction compliance:China's National Health Commission and Ministry of Agriculture coordinate overlapping standards for cross-border nutritional products, creating documentation complexity and inspection redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Milk Replacers Market |
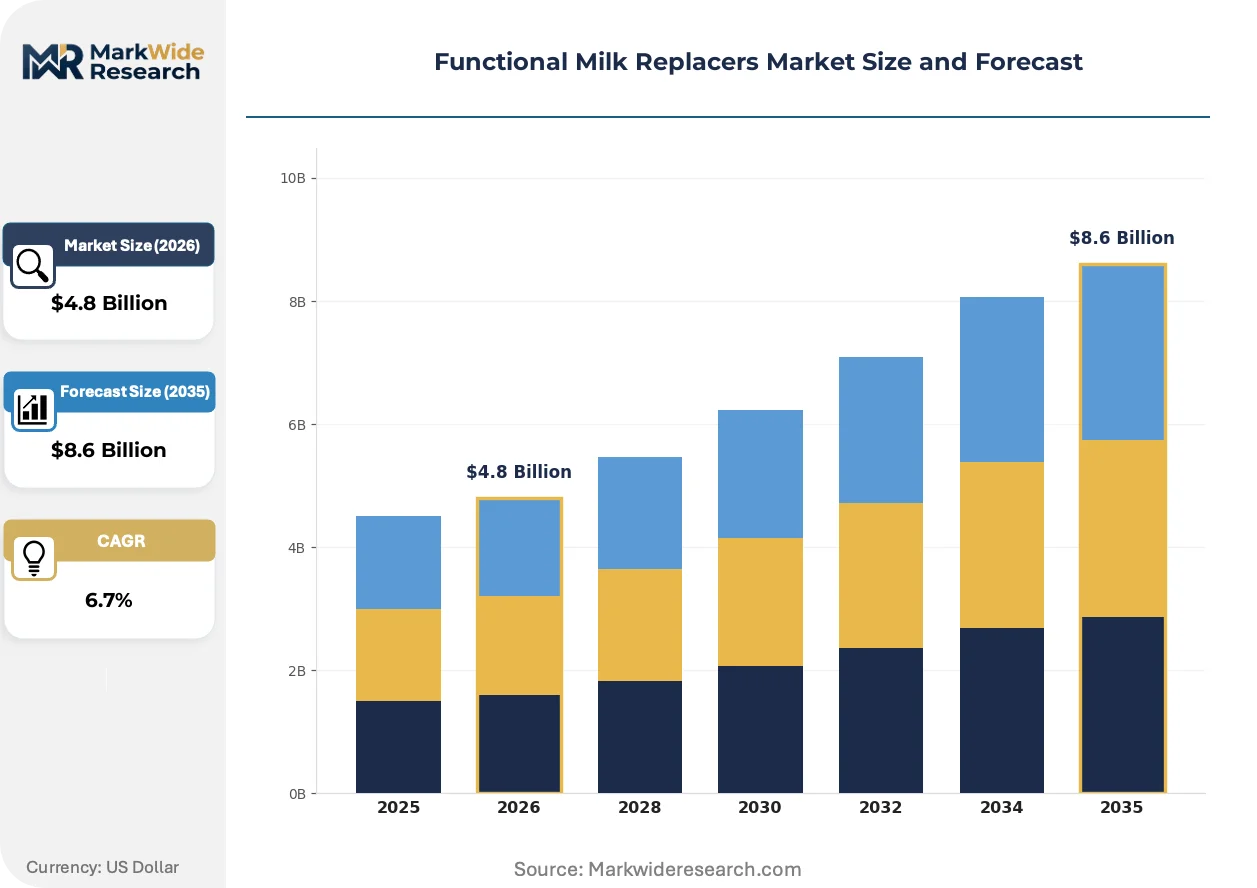
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein-Enriched, Vitamin-Fortified, Mineral-Enhanced, Probiotic-Infused, Hormone-Free, Organic Application: Lactation Support, Calf Nutrition, Pet Nutrition, Infant Formula, Nutritional Supplements, Clinical Nutrition End User: Dairy Farms, Veterinary Clinics, Animal Feed Manufacturers, Pediatric Hospitals, Sports Nutrition Centers Formulation Type: Powder, Liquid, Concentrate, Tablet, Ready-to-Feed |
| Companies Covered | Cargill, Archer Daniels Midland, FrieslandCampina, Nutreco, Land O'Lakes, Lactalis Group, CHS Inc., Glanbia, Denkavit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Milk Replacers Market Shifts & Advancements
Formulation science and manufacturing process control are converging to redefine competitive advantage, as precision nutrition replaces commodity substitution and regulatory compliance becomes a product design input rather than post-hoc certification.
Spray-drying technology is migrating from conventional dairy processing toward specialized neonatal nutrition applications with exacting protein preservation requirements. Calf nutrition programs in the United States and European Union are adopting these systems at accelerated replacement cycles. The shift is compressing equipment supplier margins while elevating formulation consistency as the primary vendor selection criterion.
EFSA's evolving framework for microbiome health claims is tightening evidentiary standards for probiotic efficacy assertions in animal feed. Manufacturers must now generate colonization studies and performance trial data before market entry. Pre-weaned calf nutrition products face the steepest compliance burden, driving consolidation toward research-capable formulators with captive clinical trial infrastructure.
Buyer concentration among large-scale dairy cooperatives is compressing procurement cycles and unbundling technical advisory services from product supply. North American and European dairy operations now separate nutrition consulting from ingredient purchasing, forcing milk replacer vendors to compete on transparent cost structures rather than bundled service relationships. This disintermediation pressures mid-tier suppliers lacking direct farm relationships.
Functional Milk Replacers Market Segmentation
Segmentation in functional milk replacers reveals how formulation science diverges across species-specific digestive requirements and regulatory compliance tiers. Understanding these divisions exposes where margin concentrates and which technology platforms command premium positioning.
Product Type:
Formulations span from commodity protein fortification to microbiome-targeted interventions, with cost structures scaling steeply toward bioactive complexity.
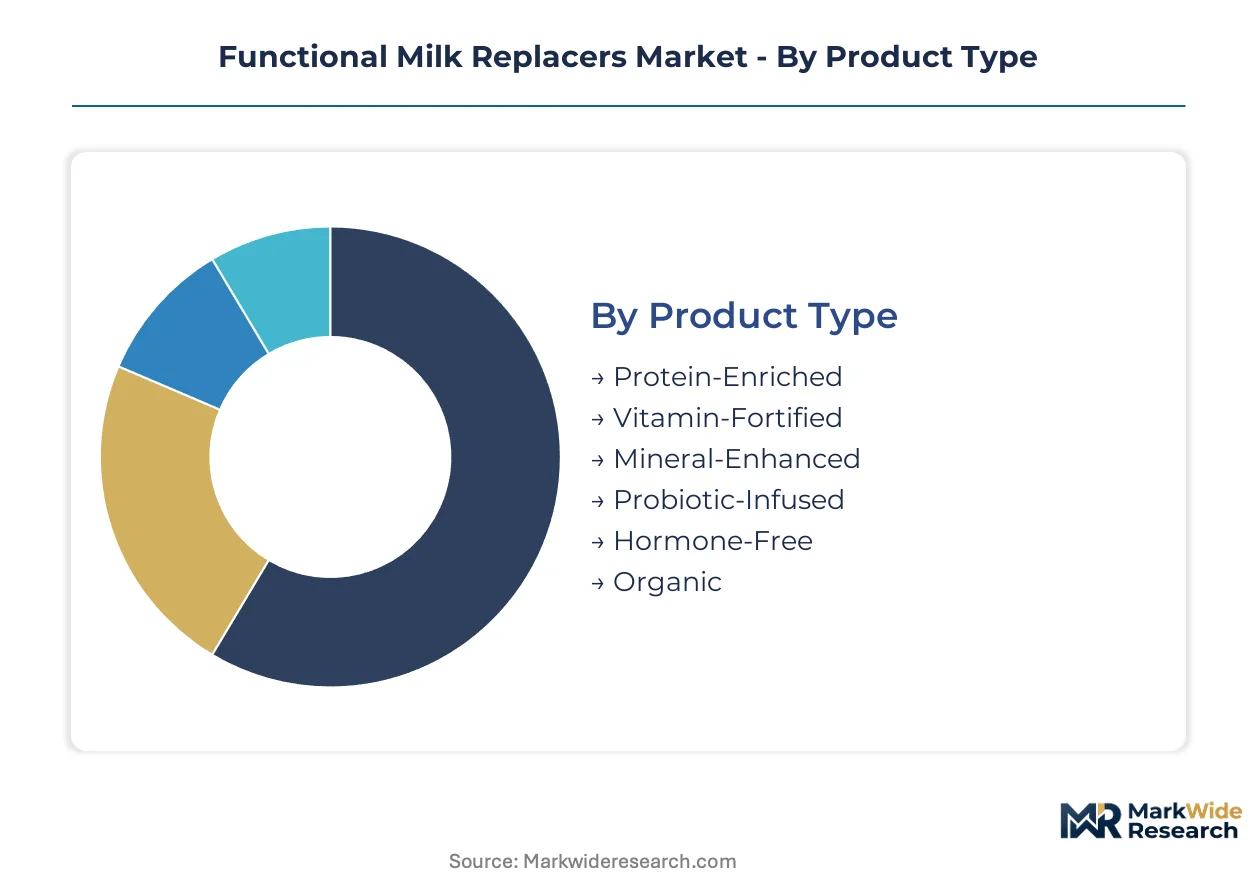
- Protein-Enriched:High-concentration whey and soy protein isolates engineered for amino acid density exceeding 22% crude protein. Dairy farms in the United States prioritize these formulations for accelerated calf weight gain protocols, absorbing premium pricing where feed conversion ratios justify input costs.
- Probiotic-Infused:Live culture formulations containing Lactobacillus and Bifidobacterium strains selected for gut colonization persistence. Demand concentrates in European Union calf nutrition programs where EFSA-validated health claims support veterinary prescribing patterns and antibiotic reduction mandates.
- Vitamin-Fortified:Fat-soluble vitamin matrices (A, D, E, K) stabilized against oxidation during spray-drying.
- Mineral-Enhanced:Chelated trace element complexes optimized for bioavailability in neonatal monogastric systems.
- Hormone-Free:Certification-compliant formulations excluding exogenous growth promoters, required for EU export eligibility.
- Organic:Ingredient sourcing restricted to certified organic dairy derivatives and plant proteins with full chain-of-custody documentation.
The dominant share belongs to Protein-Enriched, while Probiotic-Infused is closing the gap fastest.
Application:
End-use fragmentation tracks species physiology divergence and regulatory jurisdiction boundaries.
- Calf Nutrition:Neonatal ruminant formulations balancing rumen development support with abomasal digestibility, typically 20-24% protein with controlled osmolality. Dairy cooperatives in the Netherlands and Wisconsin drive specification standards through bulk procurement power.
- Infant Formula:Human-directed formulations governed by Codex Alimentarius and national food safety regulators, requiring extensive clinical validation. China's pediatric nutrition market absorbs imported formulations where domestic whey fractionation capacity remains insufficient.
- Lactation Support:Maternal nutrition products bridging human and veterinary applications with shared micronutrient platforms.
- Pet Nutrition:Canine and feline milk replacers adapted for orphan neonate survival rates in breeding operations.
- Nutritional Supplements:Adult human applications in fitness and geriatric segments with lower regulatory barriers than infant use.
- Clinical Nutrition:Hospital-directed enteral feeding under medical supervision with reimbursement-dependent distribution.
Calf Nutrition commands volume leadership, though Infant Formula generates superior per-kilogram margins.
End User:
Customer concentration patterns split between production agriculture and clinical care settings with divergent procurement logics.
- Dairy Farms:Large-scale operations with in-house nutritionists specifying custom blends against total cost of ownership metrics. Herd sizes exceeding 500 head in California and Wisconsin drive direct manufacturer relationships bypassing distributor markups.
- Animal Feed Manufacturers:Compound feed producers integrating milk replacers into complete ration formulations for integrated protein supply chains.
- Veterinary Clinics:Small-animal practices dispensing orphan nutrition products with clinical advisory bundling.
- Pediatric Hospitals:Neonatal intensive care units with formulary committees and group purchasing organization contracts.
- Sports Nutrition Centers:Retail channels for adult protein supplementation with consumer-direct e-commerce growth.
Dairy Farms represent the largest volume purchasers, while Pediatric Hospitals impose the steepest quality certification requirements.
Formulation Type:
Physical form selection trades manufacturing margin against logistics efficiency and shelf stability requirements.
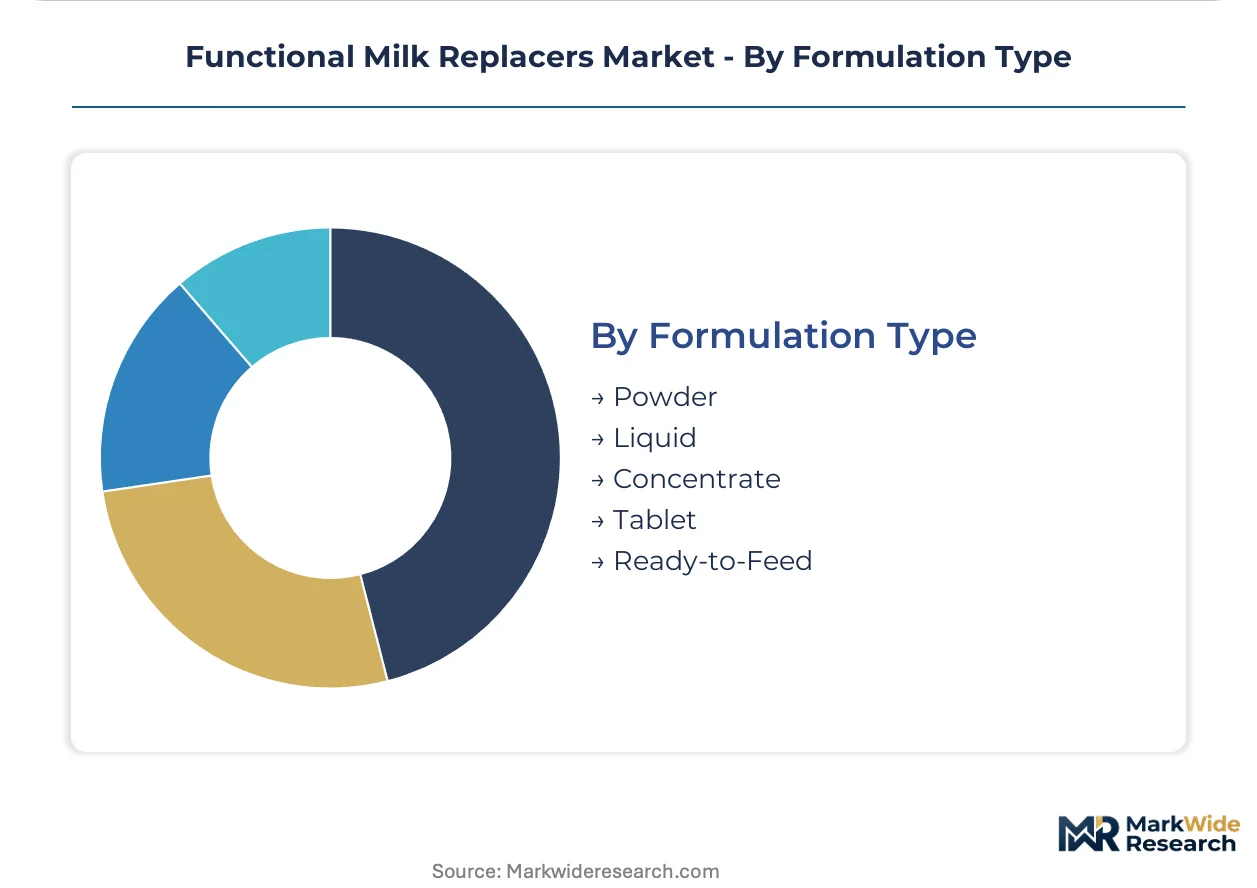
- Powder:Spray-dried particulates with moisture content below 5%, enabling extended ambient storage and containerized ocean freight. Cargill and FrieslandCampina production facilities in the Netherlands and United States optimize powder throughput for intercontinental supply to Chinese dairy operations.
- Liquid:Ready-to-use emulsions requiring cold chain integrity but eliminating reconstitution error in field application.
- Concentrate:Reduced-moisture intermediates requiring dilution before feeding, balancing storage efficiency with preparation flexibility.
- Tablet:Compressed solid doses for precise individual-animal administration in clinical settings.
- Ready-to-Feed:Terminal consumer packaging with highest convenience premium and corresponding logistics cost burden.
Powder formulations dominate manufacturing output, while Liquid formats are expanding most quickly in premium calf nutrition segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Center for Veterinary Medicine anchors the United States regulatory framework, while EFSA's additive evaluation protocols shape European formulation timelines. China's National Health Commission and Ministry of Agriculture coordinate overlapping standards that complicate cross-border product entry.
United States
Dairy cooperatives in Wisconsin and California specify custom calf nutrition blends against total cost of ownership metrics. USDA's Environmental Quality Incentives Program incentivizes reduced antibiotic use, creating regulatory tailwind for probiotic-infused protocols. Large-scale operations exceeding 500 head drive direct manufacturer relationships that bypass traditional distributor markups.
Netherlands
FrieslandCampina anchors European demand through specialized calf nutrition portfolios developed at its Dutch research campus. EFSA's novel protein evaluation timelines under EU Feed Additives Regulation delay product launches by 18-36 months. Spray-drying infrastructure clusters in the northern dairy belt, forcing Asian formulators to absorb freight cost volatility.
China
Domestic dairy herd expansion accelerates need for specialized nutritional inputs that domestic supply chains cannot yet fully satisfy. National Health Commission and Ministry of Agriculture coordinate standards for cross-border nutritional products, creating compliance complexity. Investments in domestic spray-drying facilities and whey protein processing infrastructure narrow the capacity gap in coastal provinces.
Germany
Compound feed producers integrate milk replacers into complete ration formulations for integrated protein supply chains. EU Feed Hygiene Regulation mandates safety protocols that elevate barrier to entry for subscale producers. Bavarian dairy operations prioritize neonatal health outcomes over cost-minimization in pre-weaned calf programs.
Brazil
Pasture-based systems with direct farmgate supply experience periodic whole milk price arbitrage that erodes milk replacer cost advantage. ANVISA evaluates novel protein sources for animal nutrition applications with timelines shorter than European counterparts. São Paulo state dairy cooperatives consolidate procurement around certified suppliers with quality-assured manufacturing.
Functional Milk Replacers Market Competitive Landscape
Integrated agribusiness conglomerates and specialized dairy nutrition houses split the market between scale-driven commodity supply and research-intensive formulation development. The vendor base concentrates around established dairy processing regions where spray-drying expertise and whey fractionation capacity co-locate. Three archetypes dominate: backward-integrated crop processors, cooperative-owned dairy processors, and independent nutrition specialists. Competitive moves center on captive supply chain construction and clinical trial infrastructure acquisition to satisfy tightening microbiome health claims standards.
Among agribusiness conglomerates with oilseed processing scale, Cargill and Archer Daniels Midland occupy positions that leverage upstream control over soy and canola into lipid fraction supply. FrieslandCampina exemplifies the cooperative-owned model, anchoring European demand through research campus capabilities. These three represent distinct strategic postures: crop processor diversification, dairy cooperative verticalization, and regional formulation specialization.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| FrieslandCampina |
| Nutreco |
| Land O'Lakes |
| Lactalis Group |
| CHS Inc. |
| Glanbia |
| Denkavit |
| Others |
Supply & Pricing Matrix
The northern Dutch dairy belt concentrates spray-drying infrastructure and whey fractionation capacity, granting processors leverage over Asian formulators who absorb freight volatility and currency risk in procurement negotiations.
Pricing Analysis
Price spreads between European-origin protein concentrates and Asian-blended alternatives compress during periods of euro weakness, forcing buyers to arbitrage sourcing decisions in real time. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with large dairy cooperatives extracting standard-tier pricing on premium-grade specifications through consolidated procurement power. Cost compression in economy-tier formulations is intensifying because Brazilian and Argentine whole milk surges periodically erode milk replacer cost advantage in pasture-based systems. Small-scale dairy operations remain most price-sensitive, while neonatal intensive care procurement committees prioritize clinical validation over unit cost.
Supply Chain Analysis
Whey protein concentrate and skim milk powder feed from dairy processing streams concentrated in the Netherlands, United States, and New Zealand, where co-located spray-drying infrastructure preserves protein denaturation thresholds critical for amino acid bioavailability. Lipid fractions draw from North American and European oilseed crushing capacity, with soy and canola protein isolates anchoring plant-based formulation cost structures. Single-source vulnerability concentrates in EU whey fractionation facilities, where EFSA novel protein evaluation timelines delay alternative ingredient qualification. Distribution runs through compound feed manufacturers and direct manufacturer relationships with large-scale dairy operations exceeding five hundred head.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment, as EFSA-validated health claims and FDA Center for Veterinary Medicine registrations create switching costs that lock dairy cooperatives into certified supplier relationships.
For Market Incumbents: Harden formulation consistency advantages by backward integration into captive spray-drying capacity in coastal Chinese provinces, insulating margin from freight volatility while preempting domestic competitor scale-up. Deepen microbiome clinical trial infrastructure to satisfy tightening EFSA evidentiary standards before subscale rivals achieve compliance parity. Anchor procurement relationships with Wisconsin and California dairy cooperatives through embedded nutrition advisory services that resist unbundling pressures. For New Entrants and Emerging Players: Build out regional whey processing infrastructure in China's Hebei and Shandong provinces, where domestic dairy herd expansion outpaces local spray-drying capacity and import dependency creates white-space opportunity. Target veterinary clinics and small-animal breeding operations with orphan nutrition products, where regulatory barriers fall below infant formula thresholds and clinical advisory bundling supports premium positioning. Pursue sports nutrition cross-application as the most penetrable human segment, leveraging livestock-performance formulation science with lower clinical validation burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core nutrition portfolios, where milk replacer divisions lack strategic fit with oilseed processing or grain trading parent companies. Long-term viability hinges on microbiome health claims validation capability, as regulatory evidentiary standards concentrate demand around research-capable formulators. Monitor EFSA approval velocity for novel protein sources as the inflection indicator for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Processing | Cargill's soy protein concentrate production secures formulation consistency across Asian supply chains. |
| Microbiome Clinical Trial Infrastructure | Denkavit's research campus validates gut colonization claims that satisfy EFSA antibiotic reduction mandates. |
| Spray-Drying Localization in China | Domestic drying facilities in Shandong reduce import dependency for calf nutrition demand growth. |
| Sports Nutrition Cross-Application | Protein-enriched livestock formulations migrate to human athletic recovery with dual-use revenue streams. |
| Direct Manufacturer Relationships | Land O'Lakes bypasses distributor markups through embedded nutritionists at large Wisconsin cooperatives. |
Research Methodology
A standing panel of dairy cooperative nutritionists, veterinary procurement managers, spray-drying plant engineers, and regulatory affairs specialists provided ongoing calibration against operational realities across the analysis window. Primary interviews with formulation scientists at Dutch and American research campuses combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EFSA feed additive opinions, and Chinese National Health Commission standards. Bottom-up volume modeling triangulated against top-down protein consumption forecasts.
Scenario bracketing around whey protein price volatility, EFSA approval timeline compression, and Chinese domestic capacity buildout bounded forecast sensitivity across the projection horizon. Segmentation dimensions spanned product type, application species, formulation physical state, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to documented herd expansion rates and protein inclusion ratio trends in neonatal nutrition protocols.
Stress conditions across euro-dollar exchange rate swings, Brazilian whole milk surplus periods, and EFSA evidentiary requirement tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory approval velocity and supply chain localization timelines. Cross-checking against USDA National Agricultural Statistics Service dairy herd inventory data and Chinese Ministry of Agriculture feed industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market