
 United States Freight and Logistics Market | 2026-2036
United States Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Freight and Logistics Market Analytics
The gap between premium expedited services and baseline freight is expanding across the United States freight and logistics landscape, as shippers separate time-critical inventory from bulk commodity flows. FedEx leverages its integrated express-ground network to sustain premium positioning in medical and high-value electronics lanes. J.B. Hunt Transport anchors intermodal scale through its container fleet and rail partnerships, dominating the middle ground between truckload flexibility and rail economics. C.H. Robinson competes as a digital freight broker, using its Navisphere platform to connect fragmented carrier capacity with enterprise shipper demand.
United States freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and maritime modes, typically measured by ton-miles, dwell time, and cost per hundredweight. The sector functions as the circulatory system of domestic commerce, with just-in-time manufacturing and omnichannel retail depending on predictable transit windows and real-time visibility. Transportation services command the largest revenue pool, though margin compression in truckload brokerage is pushing capital toward warehousing automation and contracted dedicated fleets. E-commerce verticals within the industry vertical segment are absorbing disproportionate infrastructure investment, as fulfillment nodes multiply and delivery windows compress to same-day or next-day thresholds. Technology adoption clusters around IoT-enabled fleet telematics and AI-driven route optimization, where early deployers capture fuel savings and insurance reductions that compound across network scale.
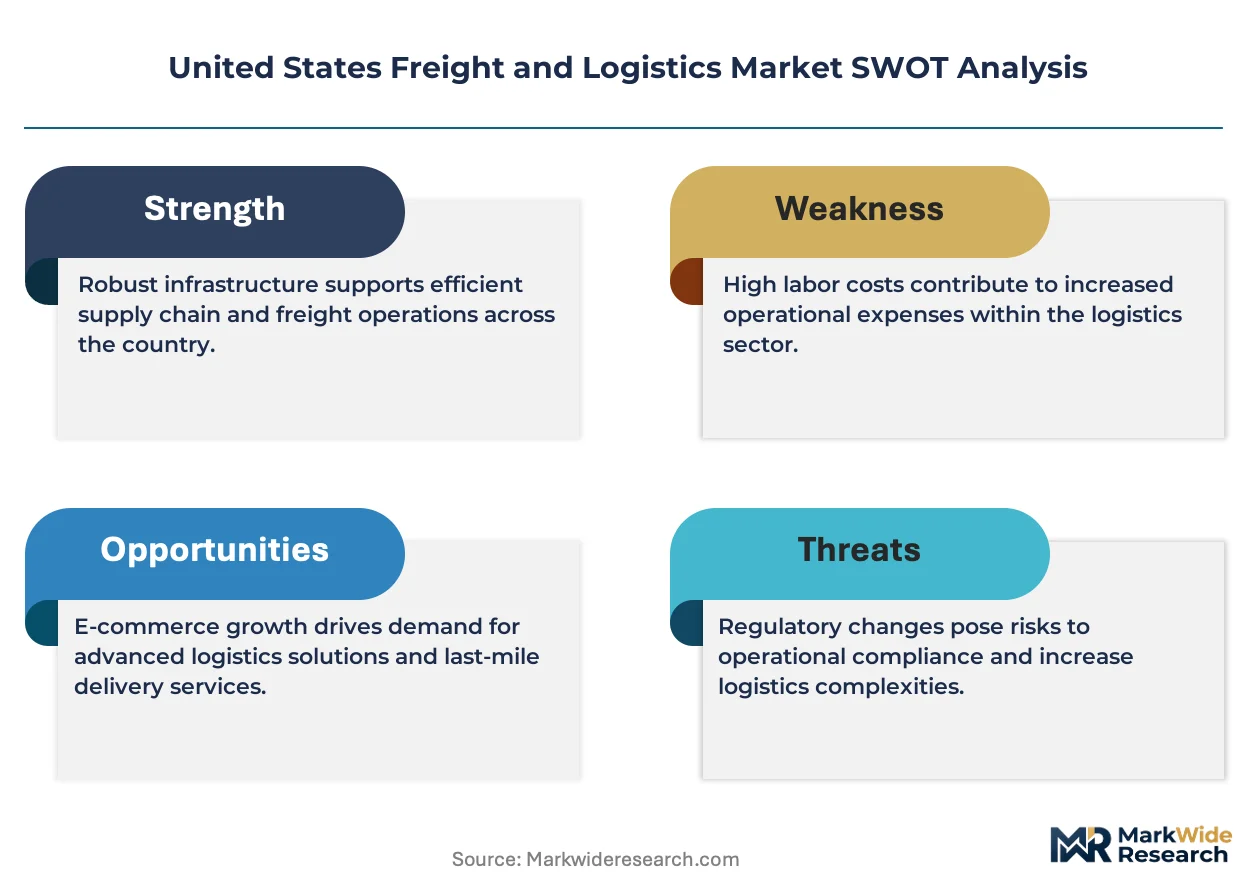
The Federal Motor Carrier Safety Administration governs hours-of-service rules and electronic logging device mandates that constrain driver availability and reshape fleet scheduling economics. The EPA's evolving emissions standards for heavy-duty trucks, alongside the Department of Transportation's infrastructure grant programs, are redirecting capital toward alternative-fuel vehicles and corridor electrification. Stakeholders must monitor how the Surface Transportation Board's rate reasonableness proceedings and potential rail merger reviews alter modal competition, as these regulatory levers will determine whether trucking or intermodal rail captures incremental volume through the decade.
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing diesel fleet economics while forcing capital reallocation toward electrified corridors, with the Dallas-Fort Worth logistics cluster absorbing disproportionate infrastructure investment as national distribution gravity shifts.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery mandates from omnichannel retailers are pulling automated sortation and micro-fulfillment investment into secondary metros. Robotic last-mile deployment concentrates in Texas and California distribution corridors.
- Intermodal rail incentives:The Department of Transportation's infrastructure grant programs are lowering access costs for inland port development. Shippers in the Midwest are migrating truckload volume to rail-truck combinations.
- Fleet telematics penetration:IoT-enabled visibility platforms are reducing insurance premiums and fuel burn. Large asset-based carriers capture network effects that compound across dedicated contract lanes.
Market Restraints
- Driver availability constraints:FMCSA hours-of-service rules and electronic logging device mandates limit tractor utilization rates. Small fleet operators face scheduling compression that larger dedicated networks absorb.
- Battery supply concentration:Lithium-ion cell production for electric heavy-duty trucks clusters in Asian manufacturing hubs. Domestic pack assembly remains import-dependent, exposing fleet electrification timelines to trade friction.
- Charging infrastructure gaps:Corridor electrification along I-10 and I-35 remains patchy outside Texas and California. Long-haul electric adoption stalls where megawatt charging station density falls below operational thresholds.
Strategic Opportunities
- Midwest cold-chain expansion:Underpenetrated temperature-controlled warehousing in Ohio and Indiana offers first-mover positioning. Pharmaceutical and protein shippers seek alternatives to saturated East Coast distribution.
- Renewable diesel blending:California's Low Carbon Fuel Standard creates arbitrage opportunities for fleets operating across state lines. Biomass-based fuels extend existing asset life while satisfying EPA compliance pathways.
- Warehouse robotics convergence:Autonomous mobile robots integrated with warehouse management systems are compressing fulfillment labor costs. Third-party logistics providers in Georgia and Pennsylvania are piloting human-robot collaborative picking.
Industry Challenges
- Technician skill scarcity:High-voltage electric drivetrain repair certification lags fleet electrification timelines. Community college programs in Texas and Michigan are racing to close the gap.
- Legacy TMS integration:Transportation management systems deployed during the 2010s lack API connectivity for real-time visibility platforms. Mid-size brokers face stranded IT assets that impede digital freight matching.
- Insurance market tightening:Nuclear verdicts in commercial auto liability are compressing carrier balance sheets. Excess liability coverage costs are rising fastest for for-hire truckload operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Freight and Logistics Market |
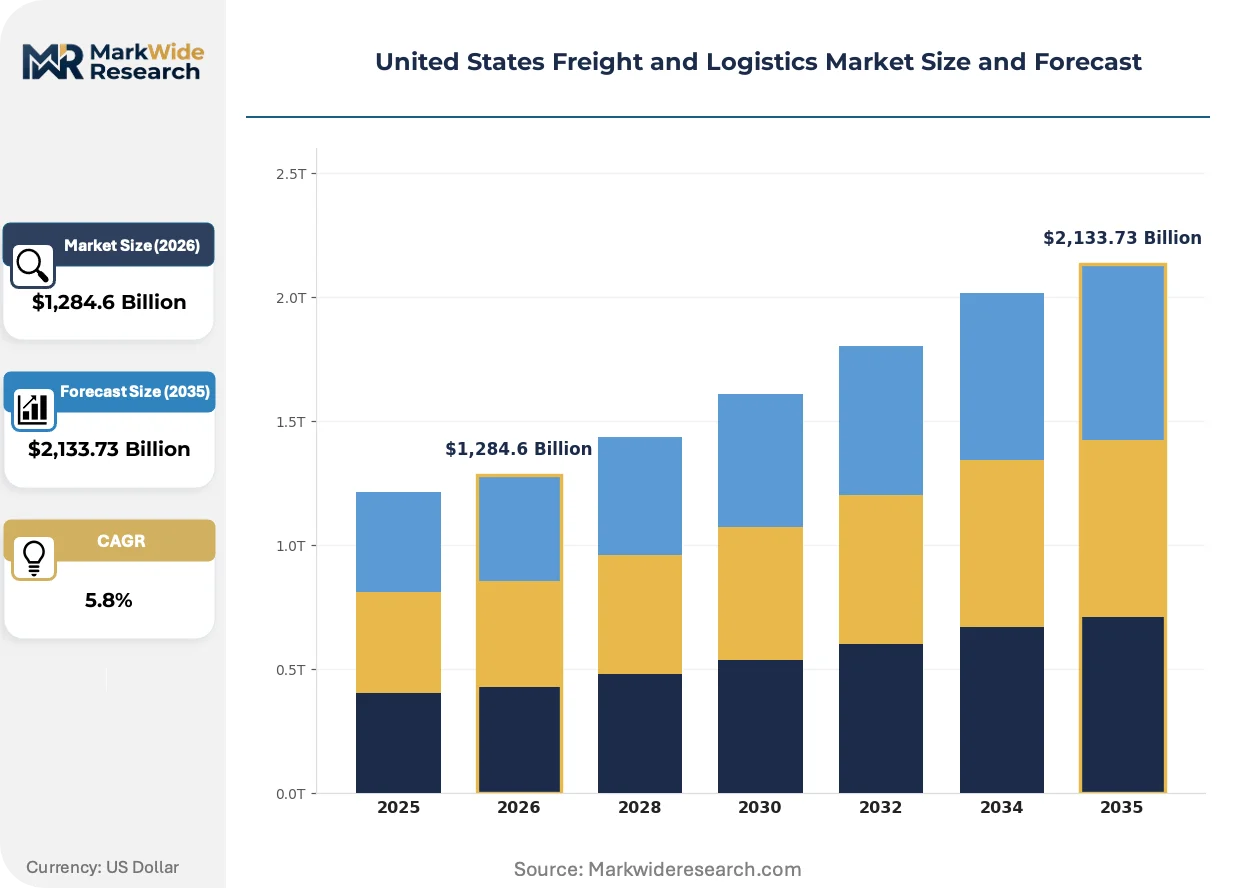
| Market Size in 2026 | $1,284.6 Billion |
| Market Size in 2035 | $2,133.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Last Mile Delivery Industry Vertical: Retail, Manufacturing, Automotive, E-Commerce Technology: IoT, Blockchain, AI, Robotics Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | United Parcel Service (UPS), FedEx, Amazon Logistics, C.H. Robinson, J.B. Hunt Transport, XPO Logistics, Total Quality Logistics, Expeditors International of Washington, Schneider, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Freight and Logistics Market Evolving Landscape
Digital freight matching and autonomous vehicle pilots are redrawing the boundary between asset-light brokerage and capital-intensive fleet ownership, with technology adoption clustering around corridors where regulatory clarity and infrastructure investment align.
Blockchain-enabled document verification is decentralizing trust mechanisms between shippers and carriers. Food and pharmaceutical logistics adopters are deploying distributed ledger systems to satisfy FDA traceability mandates. Smart contracts are compressing payment cycles and reducing dispute resolution overhead in temperature-controlled lanes.
The EPA's Phase 3 greenhouse gas standards are accelerating zero-emission vehicle procurement timelines. Fleet operators are pre-ordering electric and hydrogen fuel cell tractors to secure production slots ahead of compliance deadlines. Heavy-duty segments serving California ports and Texas distribution hubs face the most compressed transition schedules.
Shippers are unbundling transportation management from execution, selecting specialized software vendors for optimization while retaining carrier direct relationships. This procurement pattern is displacing traditional freight brokerage in high-volume lanes. Consumer packaged goods verticals in the Southeast are most advanced in this disintermediation.
United States Freight and Logistics Market Segmentation
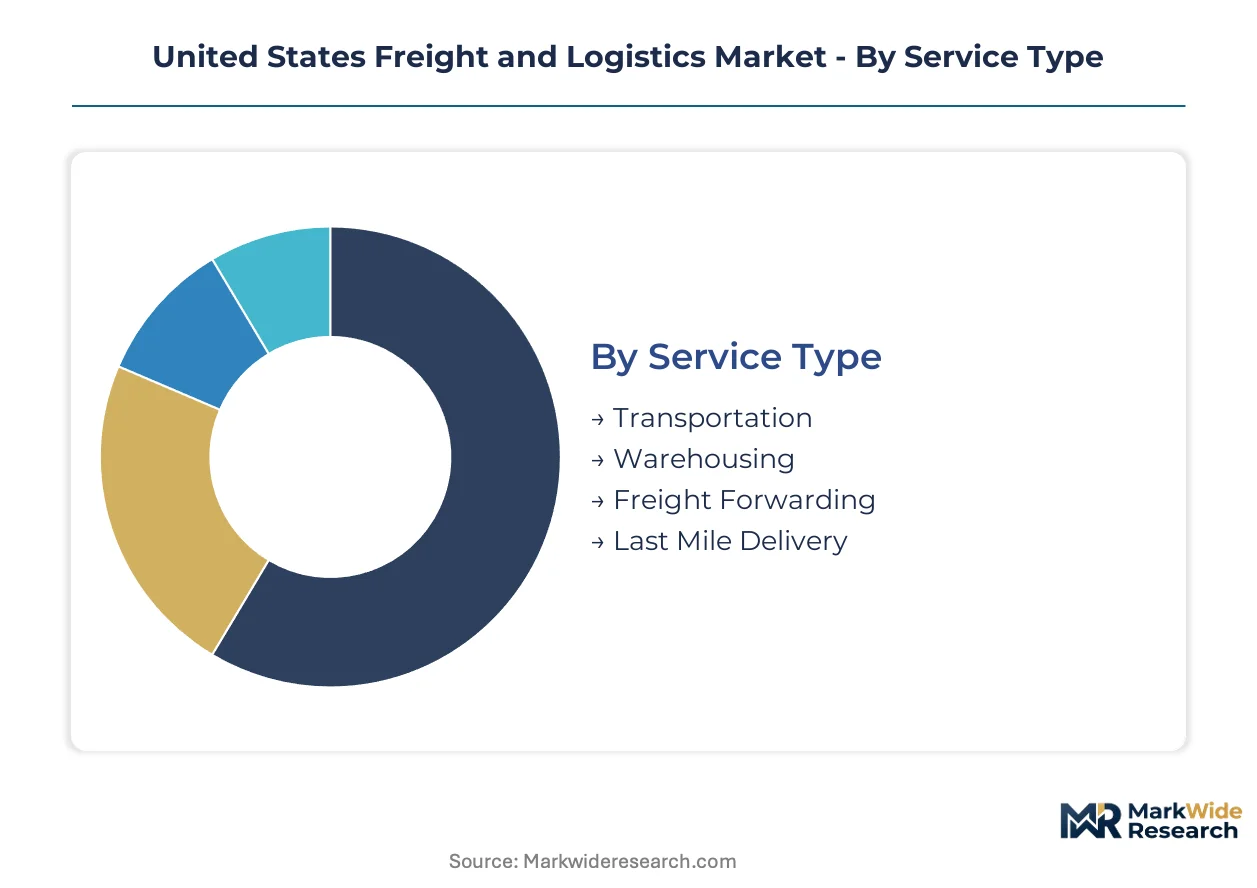
Service configuration determines capital intensity and margin structure across the United States freight and logistics landscape. Technology adoption clusters differently by operational layer, creating distinct competitive arenas within transportation execution versus warehouse automation.
Service Type:
Technology integration depth varies sharply across service layers, with asset-heavy segments resisting automation while asset-light intermediaries deploy software aggressively.
- Transportation:Motor carrier operations dominate ton-mile volume, with fleet telematics now standard among large asset-based providers. The EPA's Phase 3 standards are compressing diesel tractor residual values and accelerating alternative-fuel procurement timelines. Texas and California corridors absorb disproportionate electrification investment.
- Warehousing:Automated storage and retrieval systems compress labor costs in e-commerce fulfillment nodes. The Dallas-Fort Worth logistics cluster anchors national distribution capacity with dense robotic deployment. Pharmaceutical and cold-chain verticals drive temperature-controlled specification.
- Freight Forwarding:Customs brokerage and international documentation coordination serve importers at major ports. Digital platforms are displacing traditional intermediary relationships in high-volume lanes.
- Last Mile Delivery:Micro-fulfillment networks and crowdsourced driver pools compress delivery windows to same-day thresholds. Urban density in California and Texas metros enables route optimization algorithms.
Transportation leads on scale; Last Mile Delivery leads on momentum.
Industry Vertical:
Customer procurement patterns diverge by inventory velocity requirements, with time-critical verticals absorbing premium pricing while bulk commodity flows optimize for cost.
- Retail:Omnichannel inventory positioning demands flexible warehousing contracts with seasonal surge capacity. Major distributors concentrate fulfillment investment in Georgia and Pennsylvania distribution corridors.
- Manufacturing:Just-in-time assembly plants require contracted dedicated fleets with guaranteed transit windows. Automotive suppliers in Michigan and Ohio anchor intermodal rail volume.
- Automotive:Finished vehicle logistics and inbound parts sequencing operate on rigid production schedules. Electric vehicle battery transport faces emerging hazmat classification requirements.
- E-Commerce:Same-day delivery mandates pull automated sortation into secondary metros. Robotic last-mile deployment concentrates in Texas and California.
E-Commerce climbs the fastest; Retail retains the largest volume base.
Technology:
Deployment economics favor software-over-hardware models in fragmented carrier markets, while capital-intensive automation concentrates among large warehouse operators.
- IoT:Fleet telematics platforms reduce insurance premiums and fuel burn through real-time visibility. Large carriers capture network effects across dedicated contract lanes.
- Blockchain:Distributed ledger systems satisfy FDA traceability mandates in food and pharmaceutical logistics. Smart contracts compress payment cycles in temperature-controlled lanes.
- AI:Route optimization algorithms and demand forecasting tools displace manual dispatch decisions. Machine learning procurement is shifting toward specialized software vendors.
- Robotics:Autonomous mobile robots integrated with warehouse management systems compress fulfillment labor costs. Human-robot collaborative picking pilots operate in Georgia and Pennsylvania.
IoT leads on penetration; Robotics gains share fastest.
Delivery Mode:
Modal choice reflects the tension between truckload flexibility and rail economics, with regulatory levers determining incremental volume capture.
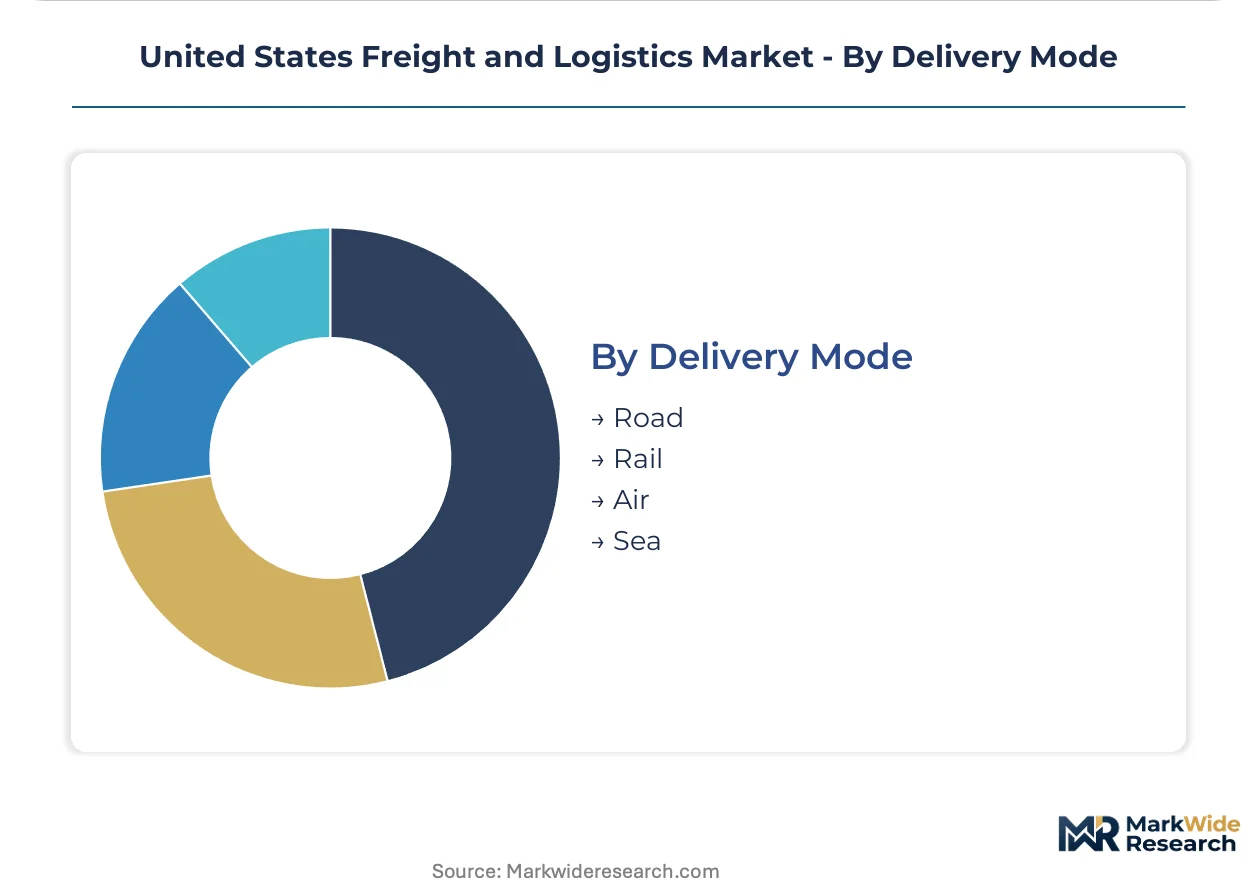
- Road:Truckload and less-than-truckload services provide door-to-door coverage with minimal handling. FMCSA hours-of-service rules constrain driver availability and reshape fleet scheduling economics.
- Rail:Intermodal combinations capture middle-distance volume between truckload flexibility and rail unit costs. The Surface Transportation Board's rate proceedings alter competitive positioning.
- Air:Expedited services command premium pricing for medical and high-value electronics lanes. Cargo capacity constraints at major hubs limit volume expansion.
- Sea:Coastal container movements and inland waterway barge services handle bulk commodity flows. Port congestion at California gateways creates modal arbitrage opportunities.
Road dominates absolute volume; Intermodal rail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas concentrates more freight infrastructure investment than any other state, while California's regulatory compression is accelerating fleet turnover timelines. The Dallas-Fort Worth corridor anchors national distribution capacity, absorbing disproportionate automation and electrification capital.
Texas
E-commerce fulfillment velocity and energy sector logistics dominate demand across the Dallas-Fort Worth and Houston metros. The Texas Department of Transportation's freight corridor prioritization directs infrastructure grants toward I-35 and I-10 electrification. The Dallas-Fort Worth logistics cluster hosts the densest concentration of automated warehousing and robotic sortation systems nationwide.
California
Port congestion at Los Angeles and Long Beach drives modal arbitrage toward inland rail corridors, while last-mile density in the Bay Area enables route optimization algorithms. The California Air Resources Board's Advanced Clean Trucks regulation mandates escalating zero-emission vehicle procurement percentages through 2035. The Inland Empire warehouse submarket leads national absorption of autonomous mobile robots in fulfillment nodes.
Illinois
Intermodal rail volume from Chicago anchors Midwest manufacturing supply chains, with just-in-time automotive parts sequencing demanding contracted dedicated fleets. The Illinois Commerce Commission's freight rail access programs lower terminal costs for shippers migrating truckload volume to rail-truck combinations. The Chicago metropolitan area concentrates cold-chain warehousing investment serving pharmaceutical distribution to the eastern seaboard.
Ohio
Underpenetrated temperature-controlled warehousing attracts first-mover positioning from protein and pharmaceutical shippers seeking alternatives to saturated East Coast distribution. The Ohio Department of Development's logistics facility incentive programs accelerate speculative industrial construction in the Columbus and Cleveland corridors. The Rickenbacker intermodal terminal anchors air cargo and rail-truck convergence for time-critical inventory positioning.
Georgia
The Port of Savannah's container volume expansion pulls warehousing investment into the Atlanta exurbs, with omnichannel retailers demanding seasonal surge capacity. The Georgia Department of Transportation's infrastructure grant programs support inland port development linking Savannah to Midwest manufacturing. The Atlanta metropolitan area pilots human-robot collaborative picking in third-party logistics facilities serving Southeast consumer packaged goods distribution.
United States Freight and Logistics Market Competitive Landscape
Top-tier vendors anchor integrated express-ground networks and intermodal scale, while mid-tier digital brokers and specialized truckload operators compete on technology deployment and lane density. Asset-heavy incumbents resist full automation while asset-light intermediaries deploy software aggressively. Two strategic archetypes dominate: integrated carriers with owned infrastructure and digital platforms matching fragmented capacity. Competitive moves concentrate on warehouse robotics convergence and dedicated fleet contracting to capture e-commerce volume.
Within the integrated carrier tier, United Parcel Service and FedEx exemplify network economies that compound across express, ground, and freight segments. C.H. Robinson occupies a position as the archetypal digital freight broker, its platform-based model representing the displacement of traditional intermediary relationships by software-driven capacity matching. These three entities collectively illustrate the tension between capital-intensive infrastructure ownership and asset-light technology leverage that defines competitive positioning across the analysis window.
| Leading Market Players |
|---|
| United Parcel Service (UPS) |
| FedEx |
| Amazon Logistics |
| C.H. Robinson |
| J.B. Hunt Transport |
| XPO Logistics |
| Total Quality Logistics |
| Expeditors International of Washington |
| Schneider |
| Others |
Value Network & Pricing Analysis
Certified diesel technician concentration in Texas and Michigan compresses labor-cost differentials between premium dedicated fleet contracts and spot-market brokerage rates. Fleet operators with in-house maintenance capabilities capture pricing power that asset-light intermediaries cannot match.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated carriers with guaranteed capacity from digital brokers matching fragmented supply. Three-tier pricing structure across premium expedited, standard contract, and economy spot levels stratifies by transit reliability and visibility depth. Cost compression in the spot brokerage tier intensifies as FMCSA hours-of-service rules constrain driver availability. Small fleet operators exhibit highest price sensitivity, while pharmaceutical shippers absorb premium rates for temperature-validated lanes.
Supply Chain Analysis
Direct-to-shipper contracted lanes handle hyperscale retail and automotive demand, while freight brokers aggregate fragmented carrier capacity for mid-market accounts. Lithium-ion cell production for electric heavy-duty tractors clusters in China, South Korea, and Japan. Domestic pack assembly draws from cobalt, nickel, and electrolyte chemical feedstocks. Single-source vulnerability in battery supply exposes fleet electrification timelines to trade friction. Distribution runs through Texas and California corridor electrification hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States freight and logistics market functions as a regulatory compounder, with EPA Phase 3 greenhouse gas standards forcing capital reallocation toward zero-emission fleet procurement and corridor electrification.
For Market Incumbents: Deploy dedicated fleet contracting as the primary defensive lever. Lock in multi-year agreements with omnichannel retailers seeking guaranteed capacity for seasonal surge windows. Absorb threatened brokerage margin compression by deepening warehouse robotics integration in the Dallas-Fort Worth corridor. Capture stranded digital broker volume as shippers unbundle transportation management from execution. For New Entrants and Emerging Players: Begin with underpenetrated temperature-controlled warehousing in Ohio and Indiana as the most penetrable white-space target. Target protein and pharmaceutical shippers seeking alternatives to saturated East Coast distribution nodes. Pilot human-robot collaborative picking systems to differentiate against legacy third-party logistics providers. For Investors and Strategic Acquirers: Asset-based carriers with electrified corridor positioning are the most active acquirer in this space. Long-term viability hinges on dedicated fleet scale and warehouse automation density rather than brokerage technology. Monitor pre-ordered electric tractor production slot allocation as the inflection signal for compliance-driven fleet turnover velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement | EPA Phase 3 compliance deadlines force zero-emission tractor pre-orders ahead of production constraints. |
| Corridor Electrification Partnership | Megawatt charging station deployment along I-35 and I-10 enables long-haul electric adoption. |
| Warehouse Robotics Integration | Autonomous mobile robots compress fulfillment labor costs in Dallas-Fort Worth distribution nodes. |
| Dedicated Fleet Expansion | Contracted capacity agreements capture e-commerce volume seeking guaranteed transit windows. |
| Renewable Diesel Supply Agreement | California Low Carbon Fuel Standard arbitrage extends existing diesel asset life while satisfying compliance. |
Research Methodology
Multiple input streams — fleet operator interviews, shipper procurement surveys, regulatory filing analysis, and infrastructure grant documentation — were reconciled through bottom-up and top-down triangulation. Primary conversations engaged fleet operations directors, transportation procurement managers at omnichannel retailers, intermodal rail planners, warehouse automation engineers, and EPA compliance officers. Secondary validation drew from FMCSA enforcement data, DOT infrastructure grant disclosures, carrier SEC filings, and state transportation department freight plans.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated service type, industry vertical, technology deployment, and delivery mode dimensions. CAGRs were derived from ton-mile demand elasticity, fleet turnover timelines, and automation adoption curves. Forecast inputs included e-commerce fulfillment velocity projections, electrification infrastructure buildout schedules, and regulatory compliance deadline impacts.
Several conditions sit outside the modeled scope, including unforeseen trade policy shifts affecting battery supply chains, abrupt FMCSA regulatory changes to hours-of-service rules, and accelerated autonomous vehicle deployment timelines. Forecasts reflect assumptions about corridor electrification investment continuity and lithium-ion production scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
France Cold Chain Logistics Market