
 Asia Pacific (APAC) Contract Logistics Market | 2026-2036
Asia Pacific (APAC) Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific (APAC) Contract Logistics Market Outlook
Software-defined warehouse management is repositioning contract logistics offerings across APAC, transforming static storage contracts into dynamic, data-driven service relationships. Deutsche Post DHL Group leverages its regional technology infrastructure to anchor multi-country fulfillment networks. Kerry Logistics Network Limited dominates cross-border road and rail corridors linking Greater China with ASEAN manufacturing zones. Nippon Express Co Ltd sustains specialized pharmaceutical cold-chain operations that meet Japan PMDA and international GDP standards.
Contract logistics encompasses the outsourcing of supply-chain execution functions—transportation, warehousing, inventory management, and value-added services—under long-term agreements with measurable service-level parameters such as order-fulfillment accuracy and dock-to-stock cycle times. Its primary purpose is to replace fixed logistics assets with variable-cost structures that scale with manufacturing and retail demand fluctuations. Warehousing services command the deepest margin pools in APAC due to land scarcity near port cities and the capital intensity of automated facilities. Value-added services, including kitting, labeling, and reverse logistics, represent the fastest-expanding segment as electronics and pharmaceutical end users seek bundled solutions. Transport management remains the most mature category, with rate transparency compressing standalone profitability.
Japan's METI enforces stringent energy-efficiency standards for logistics facilities, accelerating warehouse automation investments that reshape provider capital allocation. India's CEA mandates cold-chain infrastructure compliance for pharmaceutical distribution, directly expanding temperature-controlled contract logistics demand. The EU AI Act's extraterritorial reach into supply-chain software used by European-headquartered multinationals operating in APAC adds algorithmic transparency requirements. Stakeholders must monitor how divergent national automation incentives and cross-border data-localization rules reshape the economics of integrated regional networks.
Market Dynamics
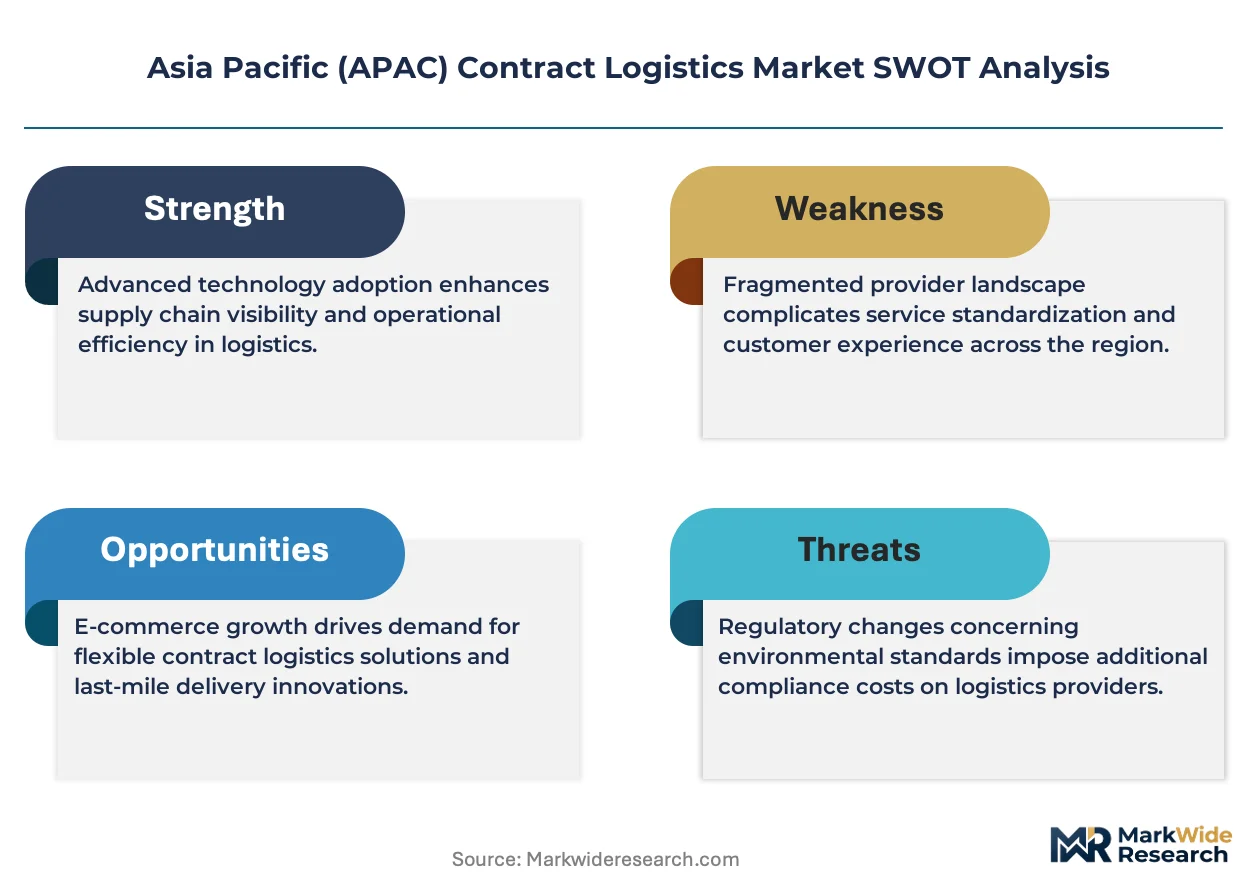
Software-defined warehouse management is compressing contract margins while expanding service attach rates across APAC, forcing providers to restructure asset-light operating models around data monetization rather than square-meter rentals.
Growth Catalysts
- India's PLI scheme for electronics:Manufacturing incentives are pulling contract logistics capacity toward semiconductor and component hubs in Gujarat and Tamil Nadu.
- Pharmaceutical cold-chain mandates:India's CEA compliance requirements for temperature-controlled distribution are expanding specialized warehousing demand.
- Vietnam's northern industrial corridor:Electronics assembly clusters around Bac Ninh and Hai Phong require integrated just-in-time delivery networks.
Market Restraints
- Land scarcity premiums:Warehouse development costs near Shanghai, Singapore, and Tokyo ports absorb 35-45% of facility operating budgets.
- Cross-border data localization:Divergent national rules on supply-chain software hosting fragment regional network economics.
- Rate transparency in transport:Digital freight platforms have commoditized standalone trucking margins across ASEAN corridors.
Strategic Opportunities
- Underpenetrated Indonesian e-fulfillment:Archipelago geography and fragmented retail create whitespace for multi-island distribution networks.
- Japan's METI automation incentives:Energy-efficiency standards for logistics facilities accelerate demand for automated warehouse solutions.
- Pharmaceutical value-added bundling:Kitting, serialization, and reverse logistics integration offer margin expansion beyond pure storage.
Industry Challenges
- Warehouse automation talent scarcity:Robotics integration and WMS configuration skills outpace vocational training output in Vietnam and Indonesia.
- EU AI Act compliance overhead:Algorithmic transparency requirements for supply-chain software used by European-headquartered multinationals add implementation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific (APAC) Contract Logistics Market |
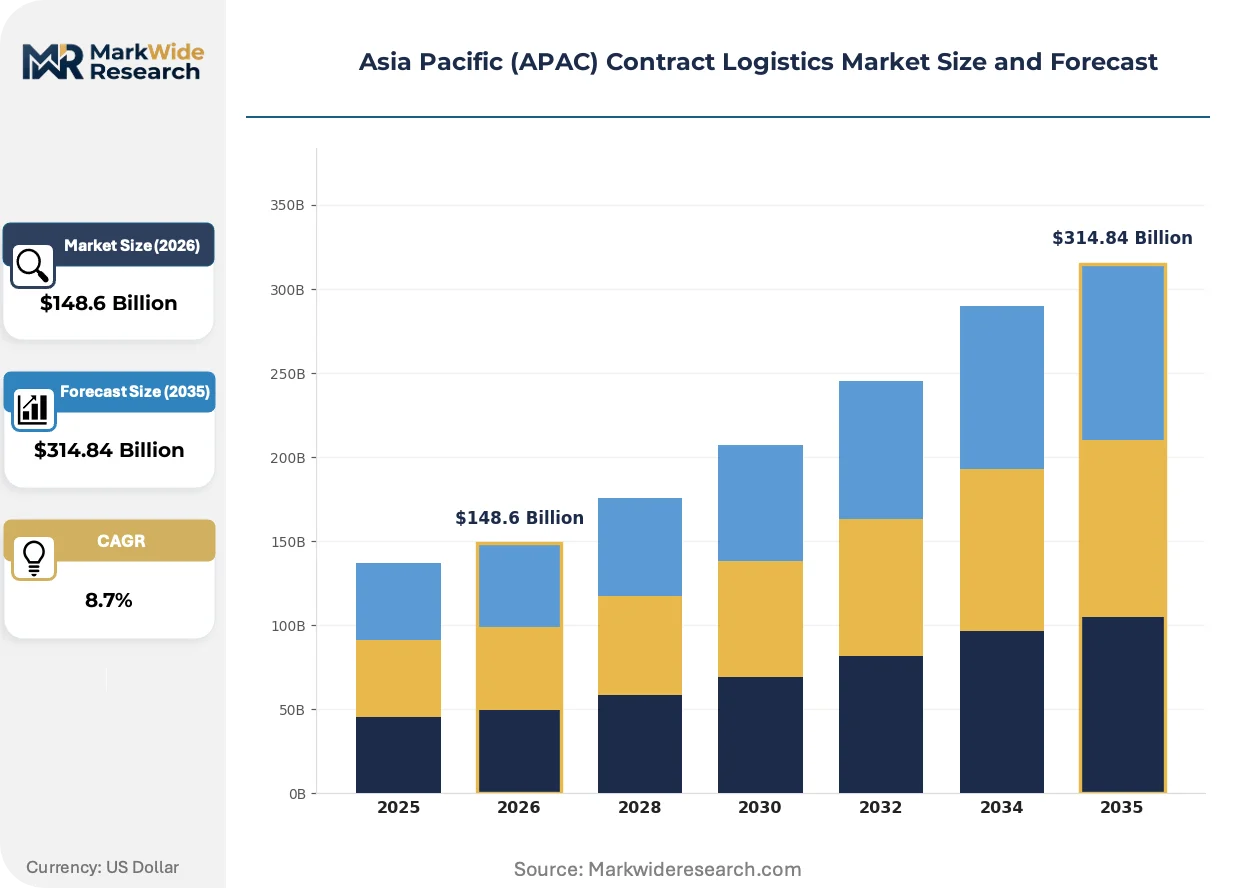
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $314.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Management, Warehousing, Freight Forwarding, Value-Added Services End User: Retail, Automotive OEMs, Pharmaceuticals, Electronics Distribution Channel: Direct Sales, E-Commerce, Third-Party Logistics Providers, Brokers Technology: Warehouse Management System, IoT Solutions, Track & Trace, Robotics |
| Companies Covered | Nippon Express Co Ltd, Kuehne + Nagel, Deutsche Post DHL Group, Kerry Logistics Network Limited, CJ Logistics, DSV, DB Schenker, Yusen Logistics Co Ltd, CEVA Logistics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific (APAC) Contract Logistics Market Strategic Shifts
Digital twin technology and predictive inventory positioning are redefining service level agreements across APAC contract logistics, shifting provider value from space provision to demand-sensing accuracy.
Autonomous mobile robots (AMRs) with fleet orchestration software are consolidating fragmented material handling operations in high-throughput electronics fulfillment centers. Korean and Taiwanese contract logistics providers are deploying these systems at scale in response to semiconductor manufacturing cycle compression. The technology is consolidating previously siloed receiving, put-away, and picking workflows into unified robotic cells that reduce labor dependency during peak seasons.
Japan's METI enforcement of stringent energy-efficiency standards for logistics facilities is accelerating warehouse automation investments that reshape provider capital allocation. Compliance mandates are driving retrofit demand for LED lighting, solar roofing, and smart HVAC systems in existing facilities. Pharmaceutical and electronics verticals face the steepest retrofit timelines as METI inspection cycles tighten.
Electronics manufacturers are compressing supplier-managed inventory cycles from quarterly to weekly replenishment rhythms. This behavioral shift is displacing traditional bonded warehousing models with vendor-hub arrangements positioned inside assembly plant perimeters. Vietnam's northern industrial corridor exhibits the most acute manifestation of this pattern as Samsung and Apple supply chain partners co-locate inventory buffers.
Asia Pacific (APAC) Contract Logistics Market Segmentation
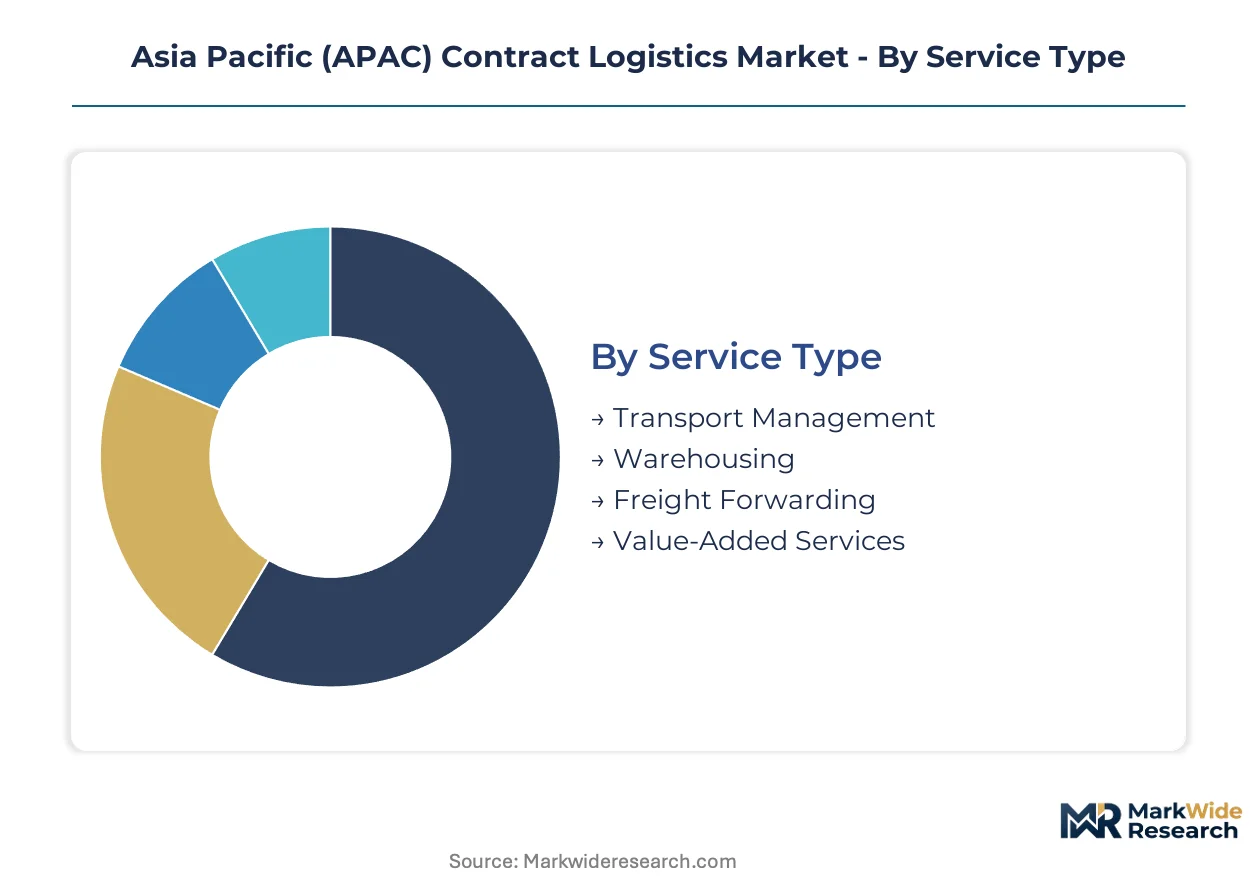
Contract logistics providers across APAC configure service portfolios around distinct operational capabilities and buyer risk profiles. Segmentation reveals where capital concentrates, which technologies command premium pricing, and how regulatory pressures reshape service bundling across electronics corridors and pharmaceutical cold chains.
Service Type:
Buyers differentiate primarily by asset ownership preference—those seeking variable-cost structures favor transport-centric contracts, while inventory-heavy manufacturers prioritize warehouse control.
- Transport Management:Route optimization and carrier procurement services dominate mature ASEAN trucking corridors. Digital freight platforms have compressed standalone margins, pushing providers toward bundled warehouse-transport contracts in Vietnam's northern industrial corridor.
- Warehousing:Automated storage and retrieval systems anchor the deepest margin pools due to land scarcity premiums near Shanghai, Singapore, and Tokyo ports. India's PLI scheme for electronics is pulling capacity toward semiconductor hubs in Gujarat and Tamil Nadu.
- Freight Forwarding:Customs brokerage and multimodal coordination services face rate transparency from digital booking platforms.
- Value-Added Services:Kitting, labeling, and reverse logistics integration commands fastest expansion as electronics and pharmaceutical end users seek bundled solutions.
Warehousing leads volumes today; value-added services is gaining share fastest.
End User:
Vertical specialization determines compliance burden and technology investment intensity, with pharmaceutical and electronics buyers driving divergent facility specifications.
- Pharmaceuticals:Temperature-controlled distribution networks must satisfy India's CEA mandates and Japan PMDA GDP standards. Cold-chain infrastructure compliance is expanding specialized warehousing demand across the region.
- Electronics:Just-in-time delivery networks serve compressed supplier-managed inventory cycles in Vietnam's Bac Ninh and Hai Phong clusters. Samsung and Apple supply chain partners co-locate inventory buffers inside assembly plant perimeters.
- Retail:Multi-island distribution requirements in Indonesia's archipelago create whitespace for integrated fulfillment networks.
- Automotive OEMs:Sequenced parts delivery and production-line feeding contracts require precise dock-to-stock cycle time guarantees.
Electronics anchors contract value today; pharmaceuticals shows steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale and internal logistics sophistication—large manufacturers negotiate direct, while mid-tier firms rely on intermediaries.
- Direct Sales:Long-term agreements with measurable service-level parameters dominate electronics and automotive verticals. Providers embed dedicated operations teams inside client facilities.
- Third-Party Logistics Providers:Multi-client facility sharing reduces capital commitment for pharmaceutical and retail buyers with seasonal demand fluctuations.
- E-Commerce:Platform-integrated fulfillment services are expanding most quickly in underpenetrated Indonesian markets.
- Brokers:Spot-market capacity procurement serves ad-hoc transport requirements with limited strategic value.
Direct sales commands largest contract value; e-commerce channels are climbing the fastest.
Technology:
Technology adoption separates asset-heavy automation investors from software-defined service providers competing on data monetization.
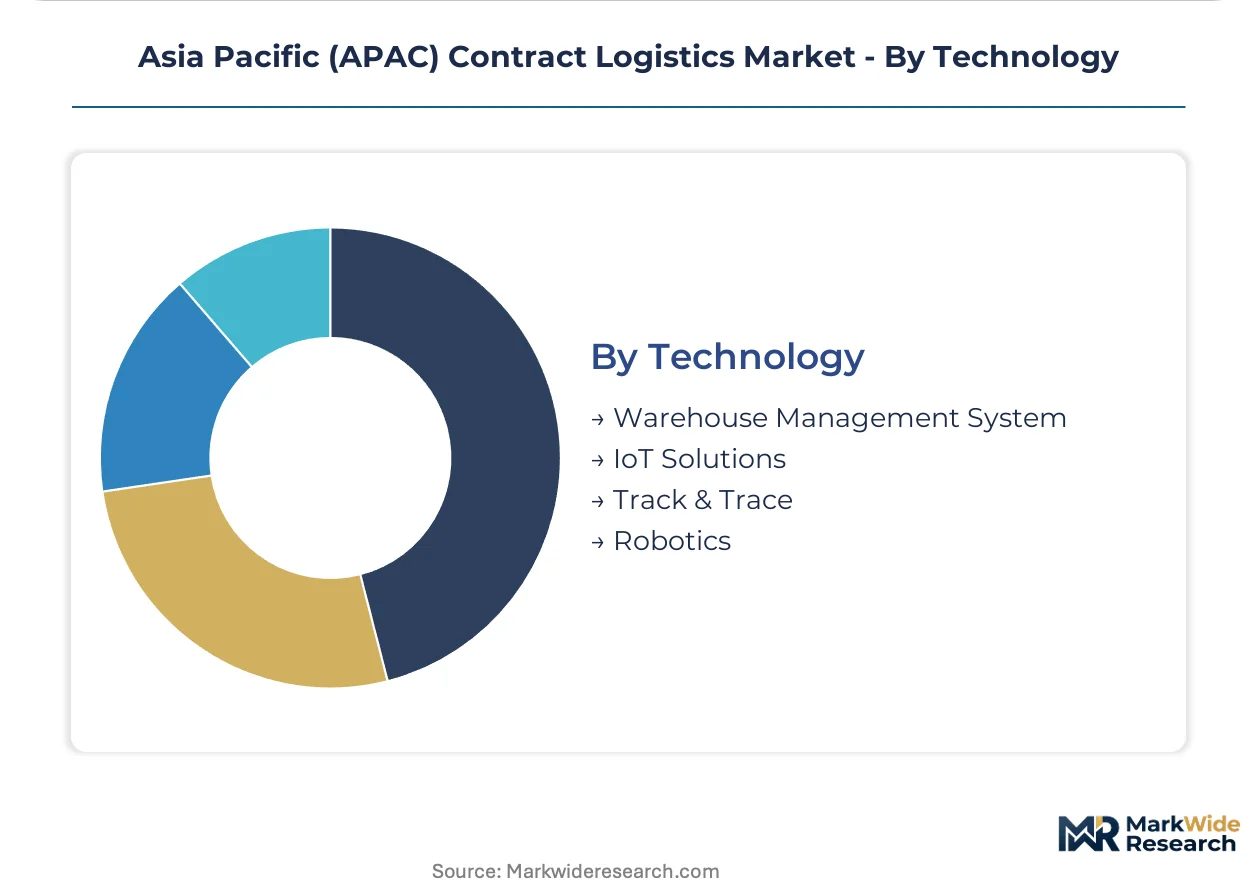
- Warehouse Management System:Cloud-native platforms with predictive inventory positioning are redefining service level agreements. Software-defined warehouse management transforms static storage contracts into dynamic, data-driven relationships.
- Robotics:Autonomous mobile robots with fleet orchestration consolidate fragmented material handling in Korean and Taiwanese semiconductor fulfillment centers. METI energy-efficiency standards accelerate retrofit demand across Japan.
- IoT Solutions:Sensor networks enable real-time environmental monitoring for pharmaceutical cold chains.
- Track & Trace:Serialization compliance supports pharmaceutical value-added bundling beyond pure storage.
Warehouse management systems dominate installed base; robotics adoption is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI-driven electronics manufacturing surge contrasts with Vietnam's northern corridor concentration, revealing divergent contract logistics capacity deployment patterns across the region.
China
Electronics assembly clusters in the Yangtze River Delta and Pearl River Delta drive integrated warehousing demand. MIIT's dual carbon goals accelerate automated facility retrofits. Shanghai port proximity commands 35-45% land scarcity premiums in facility operating budgets.
India
Semiconductor and component manufacturing in Gujarat and Tamil Nadu pulls contract logistics capacity toward PLI scheme hubs. CEA cold-chain mandates expand temperature-controlled warehousing requirements. The Delhi-NCR corridor anchors pharmaceutical distribution networks serving domestic and export markets.
Japan
Specialized pharmaceutical cold-chain operations must satisfy PMDA GDP standards alongside international compliance. METI energy-efficiency standards accelerate warehouse automation investments. The Kanto region around Tokyo sustains the deepest automated facility concentration.
Vietnam
Electronics assembly clusters around Bac Ninh and Hai Phong require just-in-time delivery networks with compressed supplier-managed inventory cycles. Samsung and Apple supply chain partners co-locate inventory buffers inside assembly plant perimeters. Cross-border road corridors link northern industrial zones with ASEAN manufacturing networks.
Indonesia
Archipelago geography and fragmented retail create whitespace for multi-island distribution networks. E-commerce platform integration expands most quickly in underpenetrated markets. Java-based fulfillment centers face last-mile complexity spanning 17,000 islands.
Asia Pacific (APAC) Contract Logistics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers commanding electronics corridors while pharmaceutical cold-chain specialists defend niche positions. The vendor base organizes around three archetypes: asset-heavy automation investors, software-defined platform operators, and cross-border corridor specialists. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion into underpenetrated ASEAN markets.
Within the integrated logistics tier, Deutsche Post DHL Group and Kerry Logistics Network Limited exemplify divergent regional strategies. DHL leverages multi-country fulfillment infrastructure across Greater China and ASEAN zones. Kerry dominates cross-border road and rail corridors linking Chinese manufacturing with Southeast Asian assembly networks. Nippon Express Co Ltd occupies a specialized position in pharmaceutical cold-chain compliance, anchoring Japan PMDA-certified operations that extend into regional temperature-controlled networks.
| Leading Market Players |
|---|
| Nippon Express Co Ltd |
| Kuehne + Nagel |
| Deutsche Post DHL Group |
| Kerry Logistics Network Limited |
| CJ Logistics |
| DSV |
| DB Schenker |
| Yusen Logistics Co Ltd |
| CEVA Logistics |
| Others |
Value Chain & Pricing Dynamics
Electronics OEMs with quarterly supplier-managed inventory cycles anchor contract logistics pricing through bundled warehouse-transport agreements rather than standalone square-meter rentals. Their procurement leverage compresses pure storage margins while elevating value-added service premiums.
Pricing Analysis
Capacity additions in Vietnam's northern industrial corridor are reshaping price floors for integrated fulfillment services. Three-tier pricing structure across premium automation, standard bonded warehousing, and economy transport-only levels dominates buyer negotiations. Price differentiation centers on certification tier (CEA cold-chain compliance versus standard GDP) and geographic delivery radius from port cities. Cost compression in standard warehousing is intensifying because digital freight platforms have commoditized standalone trucking margins. Mid-tier electronics manufacturers show highest price sensitivity; pharmaceutical multinationals with PMDA mandates accept premium automation tiers.
Supply Chain Analysis
Reverse logistics flows for electronics returns and pharmaceutical recalls are consolidating into specialized provider networks across China, Vietnam, and India. Component sourcing draws from semiconductor fabs in Taiwan and South Korea, with final assembly tethered to Vietnamese contract manufacturers. Single-source vulnerability concentrates in automated storage and retrieval systems imported from Japanese and German OEMs. Distribution runs through bonded warehouse zones near Shanghai, Singapore, and Tokyo ports before final-mile injection into assembly plant perimeters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's CEA cold-chain mandates and Japan's METI energy-efficiency standards continuously expand compliant facility demand.
For Market Incumbents: Acquire automated warehouse assets in Vietnam's Bac Ninh corridor to defend against regional platform operators digitizing freight procurement. Secure CEA certification ahead of India's pharmaceutical distribution enforcement timeline. Backward integration into robotics maintenance capabilities locks in retrofit revenue from METI compliance cycles. For New Entrants and Emerging Players: Indonesian e-commerce fulfillment networks represent the most penetrable whitespace given archipelago geography fragmenting incumbent coverage. Target multi-island distribution contracts with platform-integrated inventory positioning. Lead with cloud-native warehouse management systems that bypass capital-heavy facility ownership. For Investors and Strategic Acquirers: Integrated logistics providers with cross-border ASEAN road corridors are the most active acquirer in this space, consolidating fragmented cold-chain specialists. Five-to-ten year viability hinges on software-defined service attach rates outpacing pure storage commoditization. Watch for India's PLI scheme expanding beyond electronics into pharmaceutical manufacturing as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Retrofit | METI energy standards drive LED, solar, and smart HVAC upgrades across Japan's Kanto logistics zones. |
| Cross-Border Corridor Acquisition | Road and rail links between Chinese manufacturing and ASEAN assembly consolidate under regional platform operators. |
| Pharmaceutical Cold-Chain Certification | CEA compliance investments in India expand addressable market for temperature-controlled distribution networks. |
| Software-Defined Platform Launch | Cloud-native WMS with predictive inventory positioning transforms static storage contracts into data-driven relationships. |
| Multi-Island Distribution Buildout | Indonesian e-commerce penetration creates whitespace for integrated fulfillment spanning 17,000 islands. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions included logistics facility operators, pharmaceutical supply chain directors, electronics procurement managers, and customs brokerage specialists. Secondary validation drew from DGFT trade statistics, MIIT automation investment disclosures, CEA compliance bulletins, and bonded warehouse utilization reports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Historical reference periods anchored projections across the analysis window without year-specific anchoring. Segmentation dimensions modeled include service type, end-user vertical, distribution channel, and technology deployment tier. CAGRs derived from logistics capacity expansion rates, electronics manufacturing output indices, and pharmaceutical cold-chain infrastructure investment flows. Forecast inputs incorporated PLI scheme disbursement trajectories and METI inspection cycle timelines.
Inputs from Indian customs authorities and Vietnamese industrial zone operators were available through the study window; gaps in real-time bonded warehouse occupancy data introduce uncertainty bands around capacity utilization assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and automation adoption curves. Practitioners should monitor India's PLI scheme expansion announcements and METI energy audit schedules for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market