
 Shape Measuring Devices Market | 2026-2036
Shape Measuring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Shape Measuring Devices Market Analysis
Equipment leasing and performance-based contracting is reconfiguring capital deployment across the metrology sector. Hexagon AB leverages its software-hardware integration to sustain recurring revenue streams. ZEISS Group anchors premium positioning through captive optical component production. Mitutoyo Corporation competes on manufacturing scale across Asian industrial clusters.
Shape measuring devices are instruments that capture dimensional, geometric, and surface characteristics of physical objects using contact probes, laser triangulation, or structured light projection with typical resolution thresholds below one micron. These systems verify conformance to engineering tolerances in production environments where deviation directly impacts assembly fit or functional performance. Coordinate measuring machines retain the largest installed base but face margin compression as optical measurement devices capture share in electronics and medical component inspection. Laser scanners represent the fastest-expanding technology segment driven by portable deployment models and reduced setup times for complex freeform surfaces.
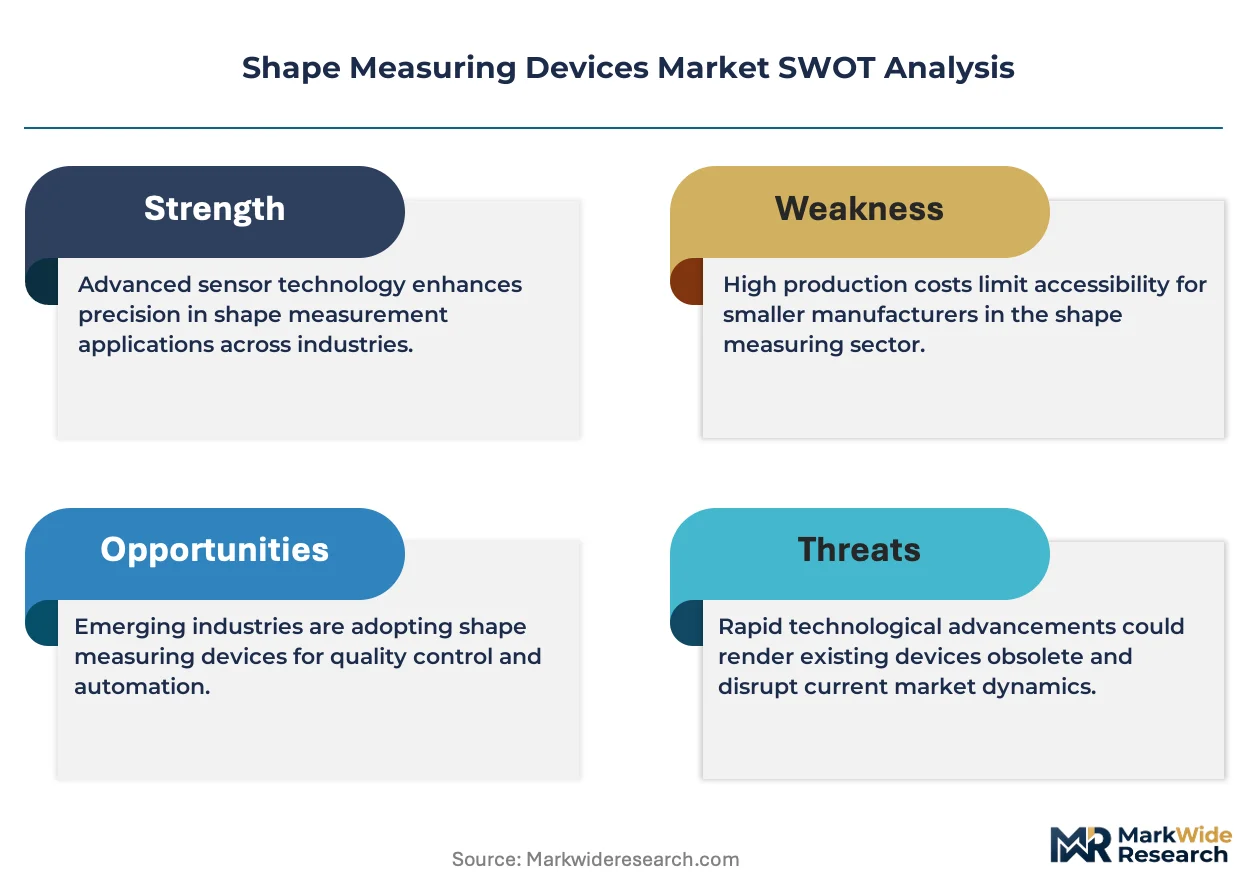
FDA device manufacturing regulations, ISO 10360 calibration protocols, and EU MDR medical device traceability requirements collectively elevate measurement documentation burdens across regulated industries. The EPA and OSHA frameworks in the United States further shape workplace deployment standards for laser-based systems. Stakeholders must weigh capital ownership against subscription service models while tracking harmonization gaps between regional certification regimes.
Market Dynamics
ISO 10360 calibration tightening is forcing automotive powertrain manufacturers to replace legacy coordinate measuring machines with sub-micron optical systems, compressing replacement cycles and redirecting capital toward metrology infrastructure.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers across Germany and Switzerland must document dimensional conformance at every production stage, expanding inspection station density in orthopedic implant machining facilities.
- Stuttgart-Nagoya-Detroit manufacturing corridors:Precision component clusters in these three cities concentrate demand for in-line laser triangulation systems that verify electric motor stator geometry without production stoppage.
- Laser scanner portability:Battery enclosure manufacturers deploy handheld structured light systems directly onto assembly floors, eliminating part transport to quality labs and shrinking inspection turnaround from hours to minutes.
Market Restraints
- Optical component supply concentration:German and Japanese precision lens suppliers control critical supply chains for interferometric sensors, exposing buyers to 12-16 week lead time volatility.
- Skilled metrology engineer scarcity:Programming complex freeform surface analysis on multi-sensor CMMs requires specialized training that outpaces vocational pipeline output in industrial Midwestern states.
- Calibration infrastructure cost:Maintaining ISO 10360-2 artifact libraries and climate-controlled laboratories imposes fixed cost burdens that exclude smaller tier-three suppliers from certified inspection capabilities.
Strategic Opportunities
- India PLI scheme manufacturing:Production-linked incentives for automotive and electronics OEMs in Tamil Nadu and Gujarat are creating first-time demand for entry-level optical comparators among domestic component suppliers.
- Cloud-native measurement software:Browser-based dimensional analysis platforms enable real-time supplier collaboration, allowing tier-one manufacturers to audit sub-tier conformance without physical audit travel.
- Additive manufacturing qualification:Powder bed fusion part certification requires novel surface roughness and internal geometry validation protocols that existing CMM touch-probe architectures cannot execute efficiently.
Industry Challenges
- Multi-sensor integration complexity:Combining tactile probe, laser scanner, and white light interferometer data streams into unified coordinate frames demands software engineering capabilities that traditional quality departments rarely possess.
- FDA 21 CFR Part 11 compliance timelines:Electronic signature and audit trail requirements for medical device measurement records extend validation cycles by 6-9 months, delaying revenue recognition for new system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shape Measuring Devices Market |
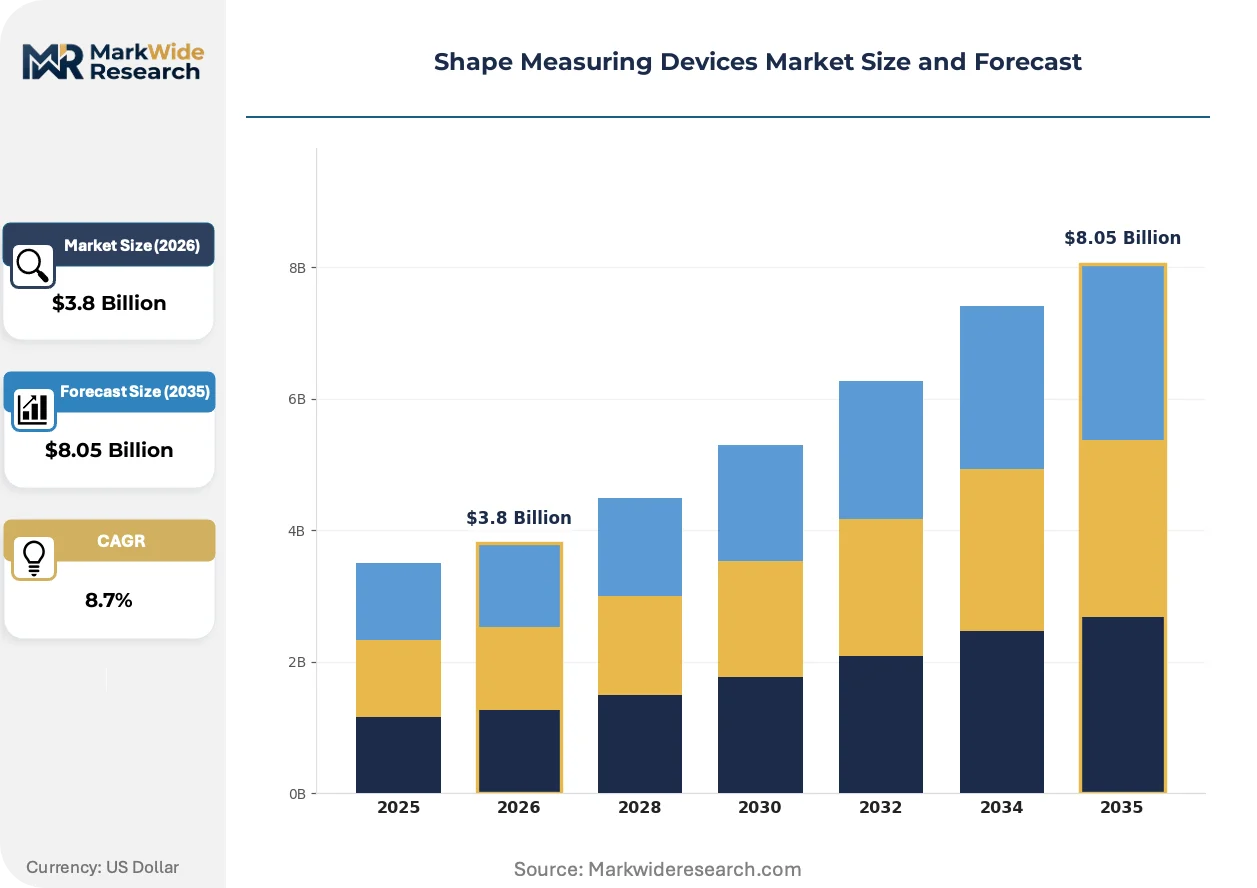
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Coordinate Measuring Machines, Optical Measurement Devices, 3D Profilers Technology: Optical, Laser-Based, Contact Measurement, Digital Image Processing End User: Aerospace, Automotive, Electronics, Manufacturing Application: Quality Control, Prototyping, Research & Development, Reverse Engineering |
| Companies Covered | Hexagon AB, ZEISS Group, Mitutoyo Corporation, KEYENCE Corporation, Ametek, Inc., Horiba Ltd., Bruker Corporation, FARO, Nikon Metrology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shape Measuring Devices Market Emerging Trajectories
Photogrammetry and AI-driven point cloud analysis are compressing the boundary between production equipment and quality infrastructure, embedding dimensional verification directly into machining centers rather than maintaining separate inspection cells.
Structured light projection is digitizing turbine blade and impeller inspection workflows in aerospace foundries across Ohio and South Carolina. Foundry engineers now capture complete surface geometry in single 30-second scans rather than executing hundreds of discrete touch-probe points. This digitizing capability is collapsing the traditional separation between rough machining and finishing quality gates, allowing real-time toolpath compensation based on as-cast dimensional variation.
REACH substance restrictions on hexavalent chromium coatings are compelling German automotive suppliers to validate alternative surface treatments through enhanced roughness measurement protocols. Coating vendors must now submit profilometry data demonstrating equivalent tribological performance, expanding demand for non-contact areal surface texture analyzers throughout Bavarian supply chains. Tier-one drivetrain manufacturers are responding by mandating supplier certification to ISO 21920 surface texture standards.
Leasing arrangements for portable measurement arms are displacing capital purchase models among Midwestern job shops serving automotive and agricultural equipment OEMs. Equipment financiers now bundle calibration services and software subscriptions into per-inspection pricing, aligning metrology costs with production volume rather than fixed asset depreciation. This transformation is most visible in Michigan and Indiana, where contract manufacturers face unpredictable order flow from electric vehicle platform launches.
Shape Measuring Devices Market Segmentation
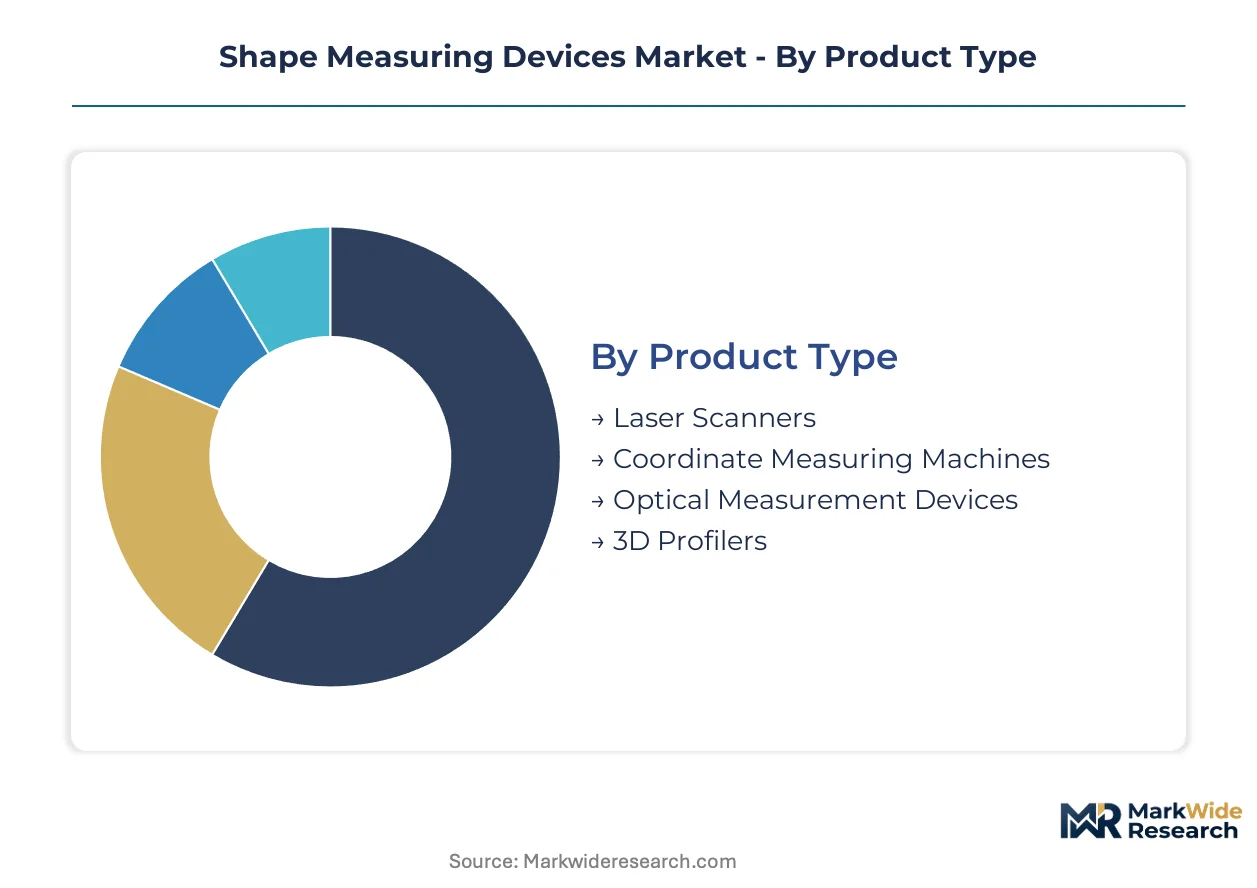
Shape measuring devices serve radically different precision requirements across automotive powertrains, medical implants, and semiconductor packaging. Segmentation reveals where sub-micron optical systems command premium pricing versus where portable laser scanners displace legacy coordinate measuring machines.
Product Type:
Equipment selection tracks the tension between absolute accuracy and shop-floor mobility.
- Coordinate Measuring Machines:Bridge and gantry architectures deliver sub-micron repeatability through granite structures and air-bearing guideways. Stuttgart and Nagoya automotive suppliers retain these systems for ISO 10360-certified powertrain verification despite longer cycle times.
- Laser Scanners:Handheld triangulation and structured light systems capture complex freeform surfaces in seconds without fixture investment. Battery enclosure manufacturers in Detroit deploy these directly onto assembly floors, eliminating quality lab transport delays.
- Optical Measurement Devices:Video measuring systems with automated edge detection serve electronics PCB and connector inspection where throughput exceeds CMM capacity.
- 3D Profilometers:Non-contact areal surface texture analyzers validate REACH-compliant coating alternatives for German automotive drivetrain suppliers.
The dominant share belongs to Coordinate Measuring Machines, while Laser Scanners is closing the gap fastest.
Technology:
Measurement modality determines capital intensity and operator skill requirements.
- Laser-Based:Triangulation and time-of-flight sensors enable portable deployment without climate-controlled environments. Aerospace foundries in Ohio and South Carolina digitize turbine blade castings in 30-second scans versus hundreds of touch-probe points.
- Optical:Structured light and white light interferometry achieve nanometer resolution for medical device surface finish validation under EU MDR traceability mandates.
- Contact Measurement:Tactile probing remains essential for internal features and hard-to-access geometries that optical systems cannot interrogate.
- Digital Image Processing:AI-driven point cloud analysis compresses programming time for complex freeform comparisons against CAD nominal.
Laser-Based systems command the steepest expansion trajectory as portability requirements reshape deployment patterns.
End User:
Industry-specific tolerance regimes and regulatory burdens dictate system specification.
- Automotive:Electric vehicle motor stator geometry and battery enclosure flatness drive demand for in-line laser triangulation without production stoppage across Stuttgart, Nagoya, and Detroit corridors.
- Aerospace:Powder bed fusion part certification requires novel internal geometry validation protocols beyond conventional CMM capabilities.
- Electronics:Miniaturized connector and semiconductor packaging inspection favors high-throughput optical comparators over tactile measurement.
- Manufacturing:Midwestern job shops serving agricultural equipment OEMs adopt leased portable measurement arms to align metrology costs with unpredictable electric vehicle platform order flow.
Automotive retains the largest installed base, though Electronics is gaining share fastest as PCB density increases.
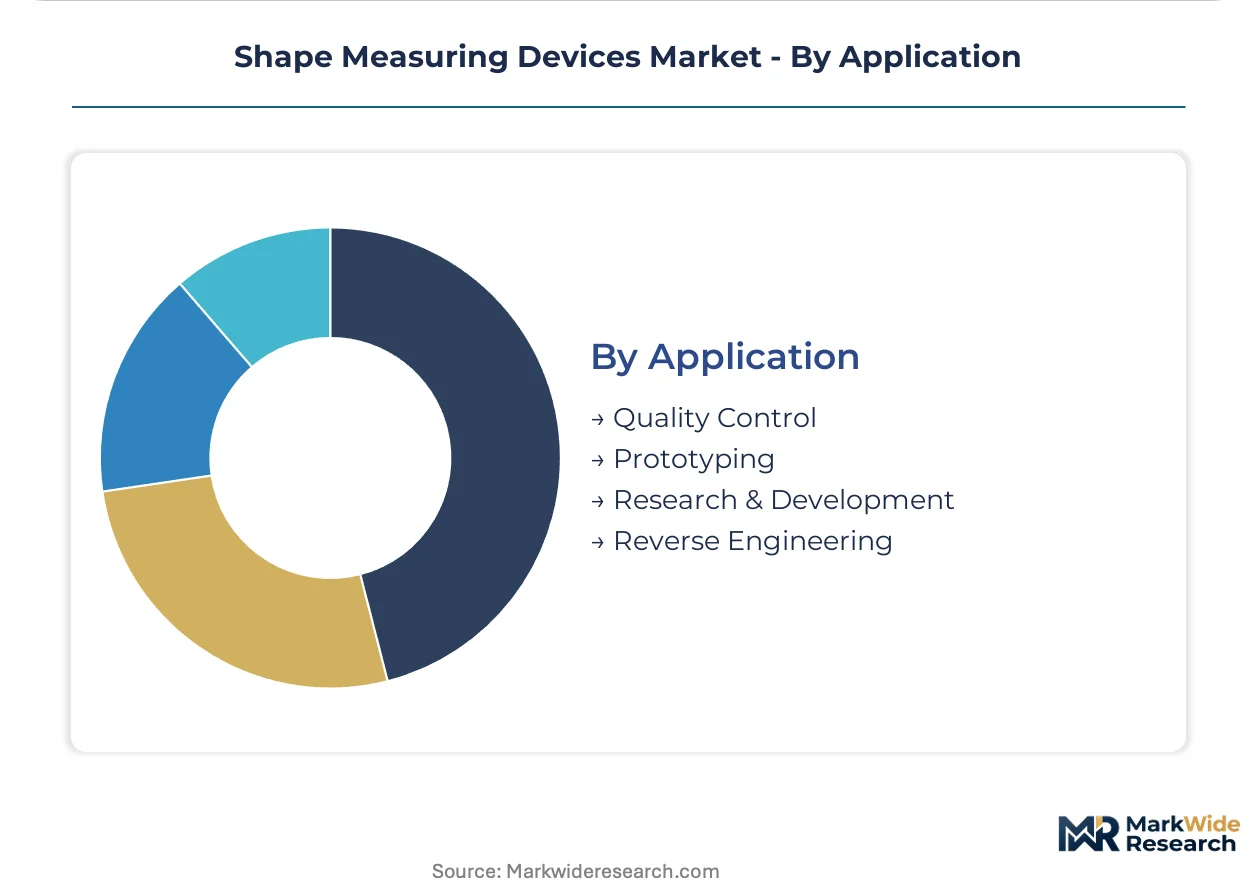
Application:
Use case determines whether measurement serves compliance documentation or process feedback.
- Quality Control:In-line verification stations must match production takt time while maintaining ISO 10360 calibration chains for automotive and medical device audit trails.
- Reverse Engineering:Handheld laser scanners digitize legacy tooling and competitor components for aftermarket part reproduction without original CAD data.
- Prototyping:Rapid iteration cycles demand immediate dimensional feedback before hard tooling commitment, favoring portable systems with minimal setup.
- Research & Development:Metrology laboratories investigate novel measurement uncertainties for additive manufacturing qualification and advanced material characterization.
Quality Control absorbs the dominant equipment volume, while Reverse Engineering is expanding most quickly as digitization penetrates legacy manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metrology suppliers extract 40-60% price premiums over Asian competitors for ISO 10360-certified systems, while Chinese manufacturers undercut on portable laser scanners by 25-35% in Southeast Asian markets.
United States
Electric vehicle battery enclosure manufacturers in Detroit and aerospace foundries across Ohio and South Carolina drive demand for handheld structured light systems. OSHA workplace safety standards govern laser deployment on assembly floors. Michigan job shops lease portable measurement arms to align metrology costs with unpredictable EV platform order flow.
Germany
Automotive powertrain suppliers in Stuttgart and Bavarian drivetrain manufacturers face REACH substance restrictions on hexavalent chromium coatings. ISO 21920 surface texture standards now mandate enhanced roughness measurement protocols. Tier-one suppliers throughout Baden-Württemberg require sub-micron optical systems to meet tightening ISO 10360 calibration requirements.
Japan
Precision component clusters in Nagoya and Tokyo-Yokohama corridor concentrate demand for in-line laser triangulation systems. METI industrial standards shape domestic metrology equipment specifications. Automotive OEMs in Aichi Prefecture verify electric motor stator geometry without production stoppage using shop-floor optical measurement.
China
Domestic automotive and electronics OEMs in Yangtze River Delta and Pearl River Delta drive volume demand for entry-level optical comparators. MIIT equipment standards and GB calibration protocols govern local certification requirements. Shenzhen and Suzhou manufacturing hubs prioritize high-throughput video measuring systems for PCB and connector inspection.
India
Production-linked incentive schemes for automotive and electronics OEMs in Tamil Nadu and Gujarat create first-time demand among domestic component suppliers. BIS standards and CDSCO medical device traceability requirements elevate measurement documentation burdens. Chennai and Ahmedabad industrial corridors adopt leased metrology equipment to conserve capital.
Shape Measuring Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying precision optics and sensor modules. The vendor base stratifies across three tiers: multinational conglomerates with software-hardware integration capabilities, mid-scale specialists focused on single-modality excellence, and regional fabricators competing on price-accessibility. Two dominant competitive moves are reshaping positioning: strategic partnerships between metrology vendors and cloud software platforms, and backward integration into captive optical component production.
Among the integrated platform tier, Hexagon AB, ZEISS Group, and Mitutoyo Corporation exemplify contrasting geographic and strategic positioning. Hexagon AB represents the software-centric archetype with recurring revenue models. ZEISS Group anchors premium positioning through in-house optical component production. Mitutoyo Corporation occupies a scale-driven position across Asian industrial clusters. These three entities collectively illustrate how metrology vendors are diverging between subscription service models and capital equipment ownership structures.
| Leading Market Players |
|---|
| Hexagon AB |
| ZEISS Group |
| Mitutoyo Corporation |
| KEYENCE Corporation |
| Ametek, Inc. |
| Horiba Ltd. |
| Bruker Corporation |
| FARO |
| Nikon Metrology |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting Stuttgart to Nagoya absorb elevated container rates that cascade through precision optics supply chains, amplifying price spreads between ISO 10360-certified systems and uncertified alternatives while compressing margins for tier-three component suppliers.
Pricing Analysis
The customization-premium spread separates configured-to-order metrology systems from standard catalog configurations by substantial margins. Subscription-based leasing with bundled calibration services now dominates capital deployment among Midwestern contract manufacturers. Price differentiation hinges on ISO 10360 certification tier and captive optical component production. Cost compression in entry-level optical comparators is intensifying because Chinese manufacturers undercut German and Japanese suppliers. Tier-one automotive OEMs exhibit lowest price sensitivity; domestic job shops in India and Southeast Asia remain most price-sensitive.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for interferometric sensor modules. Precision lens production concentrates in Germany, Japan, and Taiwan. Critical inputs include calcium fluoride crystal substrates, laser diode arrays, and granite metrology frames. Single-source vulnerability persists for sub-nanometer interferometer optics from Bavarian suppliers. Distribution runs through authorized dealer networks with captive service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ISO 10360 certification entrenchment creates switching costs that lock automotive OEMs into established supplier relationships for multi-year replacement cycles.
For Market Incumbents: Harden certification moats by accelerating ISO 10360-2 artifact library investments ahead of anticipated tolerance tightening. Deepen backward integration into precision optical component production to insulate margin structures from German and Japanese lens supplier lead time volatility. The threat of Chinese portable laser scanner entrants with 25-35% price undercuts demands preemptive channel control in Southeast Asian manufacturing corridors.
For New Entrants and Emerging Players: Mid-market job shops in India's Tamil Nadu and Gujarat industrial corridors represent the most penetrable entry point for leased portable measurement arms with per-inspection pricing. Cloud-native measurement software platforms enabling real-time supplier collaboration offer a SaaS wedge into tier-one manufacturer audit workflows. Target equipment financiers as channel partners to bypass direct capital sales resistance.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate metrology divisions lacking software-hardware integration capabilities. Long-term viability favors vendors with recurring revenue streams from calibration subscriptions and performance-based contracting. Watch for harmonization gaps between FDA 21 CFR Part 11 and EU MDR traceability requirements as inflection indicators for documentation burden expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captive supply of precision lenses insulates ZEISS and Hexagon from 12-16 week lead time volatility. |
| Cloud-Native Measurement Software Launch | Browser-based platforms enable real-time supplier collaboration without physical audit travel. |
| Performance-Based Contracting Expansion | Per-inspection pricing aligns metrology costs with unpredictable electric vehicle platform order flow. |
| ISO 10360 Certification Pre-Investment | Early artifact library deployment secures automotive powertrain replacement cycle positioning. |
| Leasing Partnership with Equipment Financiers | Capital conservation appeals to tier-three suppliers excluded from certified inspection capabilities. |
Methodological Framework
Desk research of ISO 10360 calibration protocols, FDA 21 CFR Part 11 guidance documents, and EU MDR traceability requirements preceded structured interviews with metrology equipment procurement managers at tier-one automotive OEMs, quality engineering directors at orthopedic implant manufacturers, and service heads at authorized dealer networks. Secondary validation drew from SEC filings of listed metrology vendors, customs data on precision optical component trade flows, and production statistics from Stuttgart-Nagoya-Detroit manufacturing corridors. Bottom-up equipment shipment analysis and top-down industrial capital expenditure estimates were triangulated.
Assumptions held fixed include continued ISO 10360 tolerance tightening trajectory, sustained electric vehicle platform launch schedules, and stable REACH substance restriction enforcement. Variables included India PLI scheme uptake rates and cloud-native software adoption curves across supplier tiers. Segmentation modeling spanned product architecture, measurement modality, end-use industry tolerance regimes, and application purpose across the projection horizon. CAGR derivation incorporated replacement cycle compression from optical system displacement of legacy CMMs and additive manufacturing qualification protocol emergence.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or semiconductor equipment investment trajectories would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization progress and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
One-Box Testers Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
LAN Tester Market
Test and Measurement
Digital Inspection Market
Test and Measurement
EMC Testing Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market