
 Antithrombin Market | 2026-2036
Antithrombin Market Size, Share, and Industry Trends Forecast 2026-2036
Antithrombin Market Intelligence
The transition towards recombinant manufacturing techniques is narrowing the reliance on human plasma donors for antithrombin production. This shift challenges established players like Grifols, S.A., which specializes in large-scale plasma collection and fractionation. CSL Behring leverages its deep expertise in protein therapeutics to develop both plasma-derived and recombinant options. Takeda Pharmaceutical Company Limited competes through its focus on rare hematological disorders.
Antithrombin is a serine protease inhibitor that functions as a natural anticoagulant by inactivating thrombin and other coagulation factors. Its primary therapeutic purpose is to manage and prevent thromboembolic events in patients with hereditary or acquired antithrombin deficiency. While plasma-derived products continue to dominate the market, recombinant antithrombin represents the fastest-growing product type due to its consistent supply chain. Demand is highest within the venous thromboembolism and cardiopulmonary bypass therapy areas.
Market access is governed by stringent regulatory frameworks, with the U.S. FDA, the European Medicines Agency (EMA), and China's NMPA enforcing rigorous standards for clinical efficacy and manufacturing safety. These regulations directly influence development timelines and costs for both plasma-derived and recombinant products. Consequently, manufacturers must strategically balance investments in securing plasma supply chains against the high costs of recombinant technology research and development.
Market Dynamics
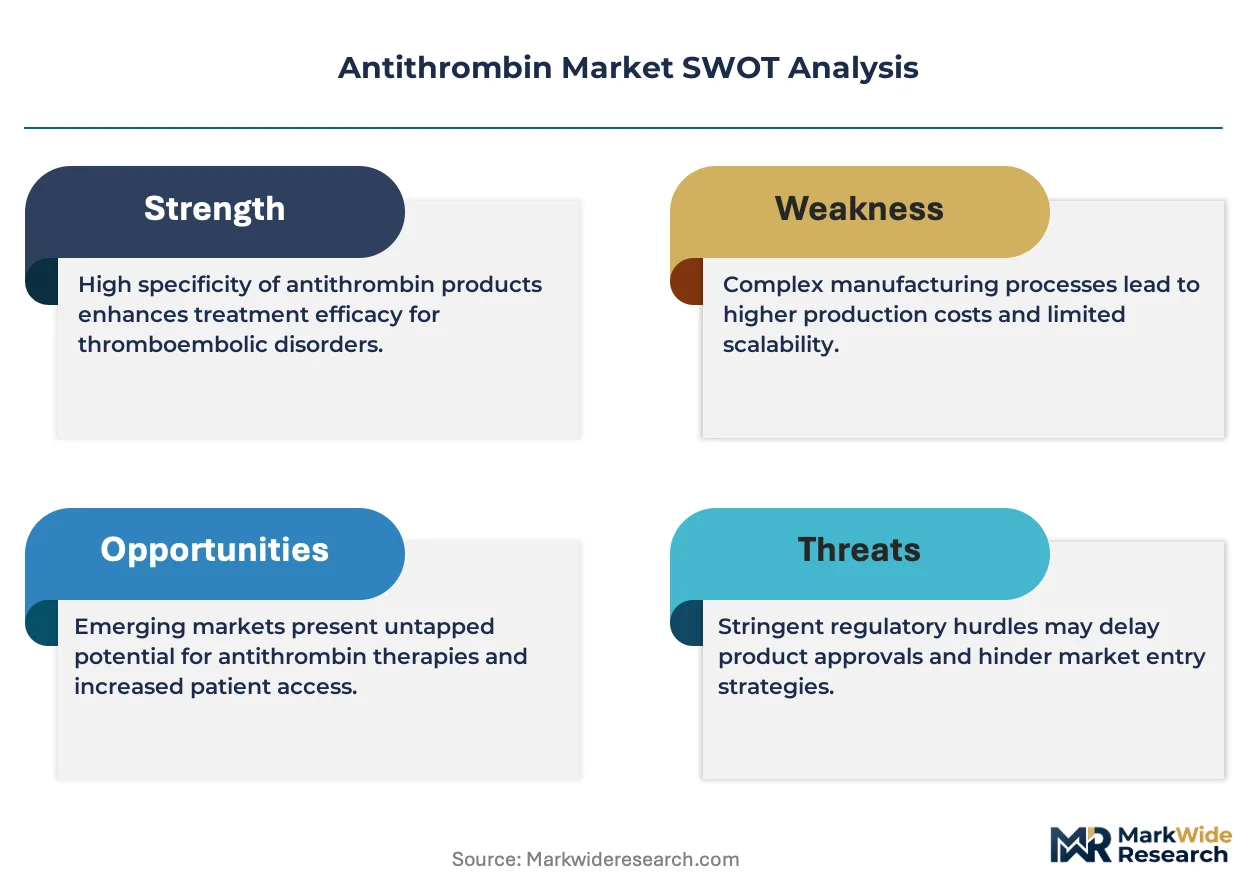
The fundamental dynamic shaping the antithrombin market is the technological pivot from human plasma-derived products to recombinant manufacturing. This transition is actively reconfiguring supply chain dependencies, altering cost structures, and shifting the competitive balance between established plasma fractionators and biotechnology innovators.
Growth Catalysts
- Recombinant Technology Adoption:The development of recombinant antithrombin offers a consistent and scalable alternative to plasma-derived products, mitigating supply chain volatility tied to human plasma donation.
- Surgical Procedure Volume:Expanding use in complex surgeries, especially cardiopulmonary bypass and organ transplantation, provides a steady source of demand from specialized hospital centers.
- Supportive Research Infrastructure:Advanced healthcare systems, exemplified by Germany's network of university hospitals and research institutes, facilitate clinical trials and promote therapeutic guideline development, accelerating adoption.
Market Restraints
- High Development Costs:The research, clinical trials, and manufacturing scale-up for recombinant antithrombin demand significant capital investment, creating high barriers to entry.
- Plasma Supply Vulnerability:Plasma-derived products remain dependent on a limited pool of human donors, creating inherent logistical and ethical challenges that can constrain supply.
- Stringent Regulatory Scrutiny:Regulatory bodies like the U.S. FDA and the EMA impose rigorous safety and efficacy standards, leading to lengthy and costly approval processes for new products.
Strategic Opportunities
- Therapeutic Area Expansion:Investigating antithrombin's efficacy in treating conditions beyond hereditary deficiency, such as sepsis-induced coagulopathy, could open significant new clinical applications.
- Underpenetrated Market Entry:Focusing on markets in Latin America and Southeast Asia, where diagnostic rates for antithrombin deficiency are low, presents an opportunity for market education and growth.
- Personalized Medicine Integration:Combining antithrombin therapies with advanced coagulation diagnostics can enable more precise, patient-specific dosing strategies, improving outcomes and justifying premium pricing.
Industry Challenges
- Dual Supply Chain Management:Manufacturers must simultaneously manage the complex logistics of both human plasma collection and sophisticated biopharmaceutical production for recombinant products.
- Global Regulatory Harmonization:Navigating divergent requirements for product approval and manufacturing between the NMPA in China, the EMA in Europe, and the FDA in the U.S. complicates global commercialization strategies.
- Specialized Talent Scarcity:A shortage of technicians and scientists with expertise in large-scale recombinant protein purification and cell culture engineering can hinder production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antithrombin Market |
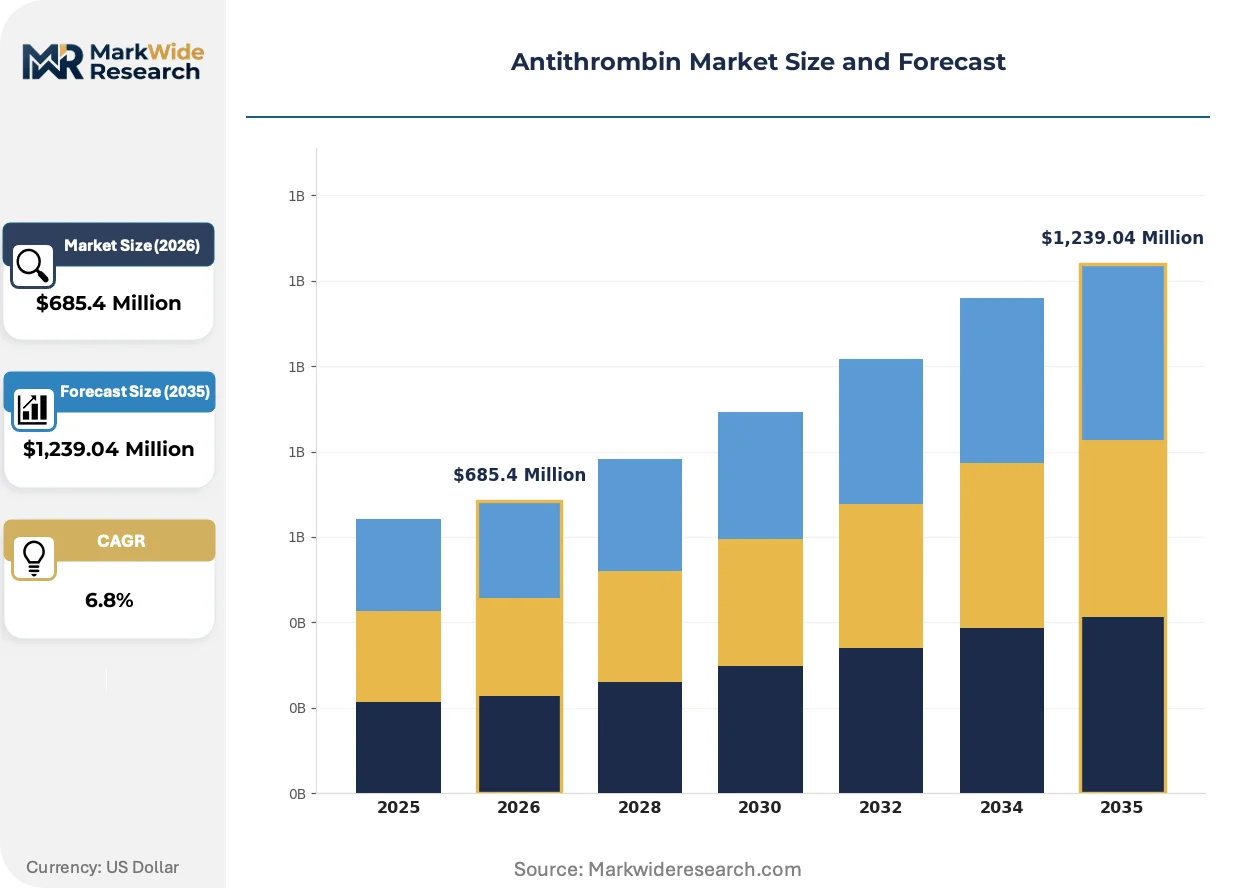
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Antithrombin, Plasma-Derived Antithrombin, Synthetic Antithrombin, Biosimilar Antithrombin Therapy Area: Venous Thromboembolism, Disseminated Intravascular Coagulation, Heparin Resistance, Cardiopulmonary Bypass End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutes Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Treatment |
| Companies Covered | CSL Behring, Grifols, S.A., Octapharma AG, Takeda Pharmaceutical Company Limited, LFB USA, Kedrion S.p.A., rEVO Biologics, Shire plc, Sobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antithrombin Market Strategic Shifts & Innovations
The evolution of antithrombin therapy is defined by a deliberate move towards greater manufacturing control and clinical precision. This shift prioritizes supply chain stability and patient safety, influencing both product development pipelines and clinical practice guidelines across major healthcare systems.
Recombinant antithrombin is a bioengineered protein providing a consistent, non-human-derived source of the critical anticoagulant. Hospitals and specialized clinics are adopting it for surgical and therapeutic applications due to its reliable supply and reduced risk of plasma-borne pathogens. The market is migrating from a dependency on the volatile human plasma supply chain toward more predictable and scalable biotechnological production methods.
European Medicines Agency (EMA) guidelines for plasma-derived medicinal products set high safety and efficacy benchmarks. This regulatory pressure compels manufacturers to invest in advanced pathogen inactivation technologies and provide robust clinical data for both product types. Plasma-derived product specialists face the most significant impact, confronting increased compliance costs related to donor screening and fractionation processes.
A clear shift toward protocol-driven utilization of antithrombin is becoming standard within hospital formularies. This change is replacing individual clinician preference with institutional guidelines for use in high-risk procedures like cardiopulmonary bypass, driven by risk management and cost-effectiveness goals. This trend is most prominent in large academic medical centers in North America and Germany.
Antithrombin Market Segmentation
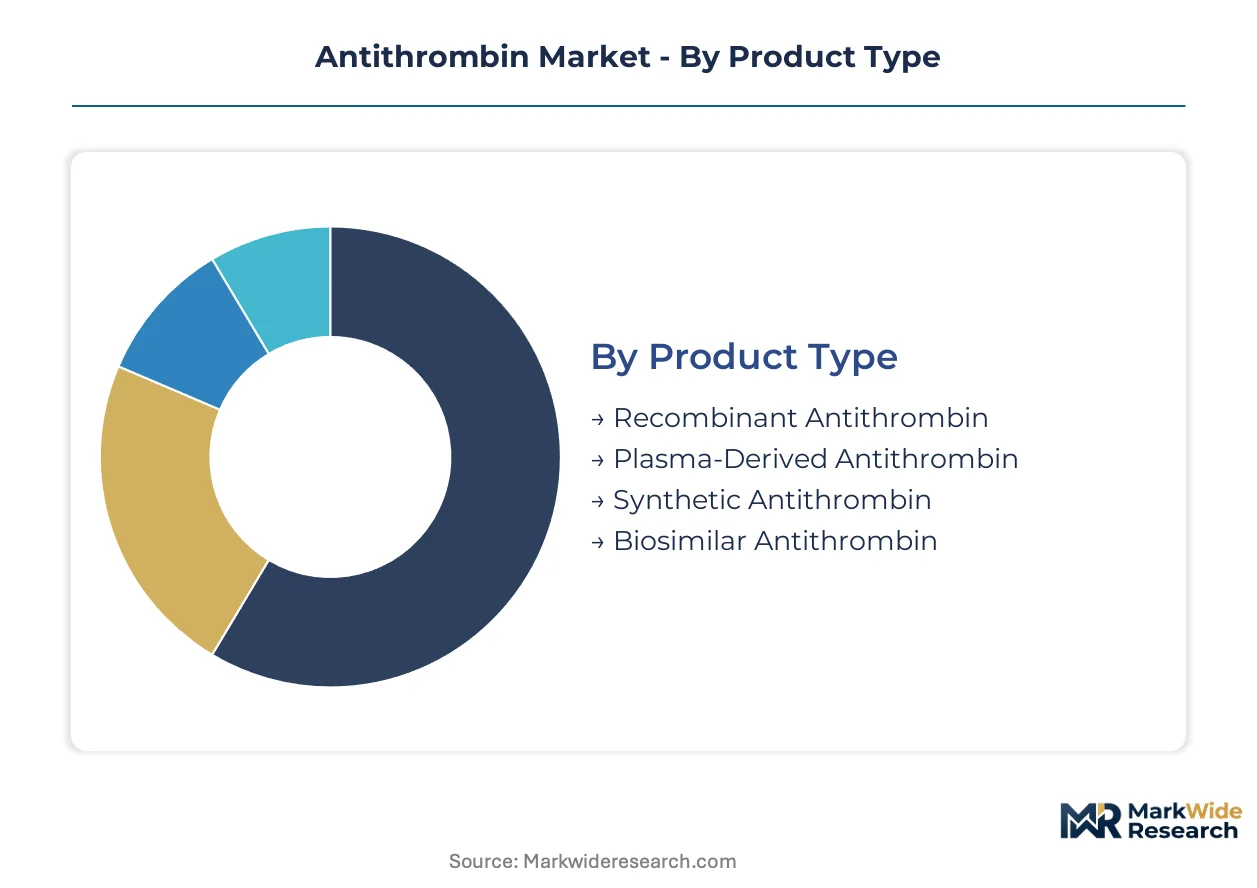
Understanding the Antithrombin Market through its various segments reveals critical insights into product adoption patterns and therapeutic demand. This granular view helps stakeholders identify specific growth vectors and allocate resources effectively across different product types and end-user applications. The market's segmentation highlights the evolving landscape of antithrombin therapies.
Product Type:
The intensity of after-sales service and ongoing patient management varies significantly across antithrombin product types, influencing their market penetration and long-term viability.
- Recombinant Antithrombin:This bioengineered protein provides a consistent, non-human-derived source of the critical anticoagulant. Demand concentrates in specialized hospital centers in Germany, driven by reliable supply chains during complex surgeries like cardiopulmonary bypass.
- Plasma-Derived Antithrombin:Sourced from human plasma, this product type relies on extensive collection and fractionation processes. Its demand remains strong in established markets like the United States, where clinical history supports widespread use.
- Synthetic Antithrombin:These chemically synthesized compounds mimic antithrombin's anticoagulant activity, offering potential for novel therapeutic approaches.
- Biosimilar Antithrombin:These products are highly similar to an approved reference biological antithrombin, aiming to provide cost-effective alternatives to established therapies.
By volume, Plasma-Derived Antithrombin leads. By growth pace, Recombinant Antithrombin is ahead.
Therapy Area:
Antithrombin therapies are often stratified by cost-effectiveness across different clinical indications, with critical care applications justifying higher expenditure.
- Venous Thromboembolism:This therapy area involves managing and preventing blood clots in veins, including deep vein thrombosis and pulmonary embolism. Demand is high in hospital settings across North America, driven by an aging population.
- Cardiopulmonary Bypass:Antithrombin is critical during open-heart surgeries requiring temporary heart-lung machine support to prevent thrombotic complications. Specialized cardiac centers in Europe, particularly Germany, represent a significant demand cluster.
- Disseminated Intravascular Coagulation:Antithrombin addresses this complex systemic disorder characterized by widespread clotting and bleeding, often seen in sepsis patients.
- Heparin Resistance:Antithrombin supplementation helps restore the anticoagulant effect of heparin in patients who exhibit reduced response to standard heparin doses.
Venous Thromboembolism treatment accounts for a substantial share of antithrombin utilization. Cardiopulmonary Bypass applications show consistent adoption in critical care units.
End User:
The application of antithrombin products varies significantly across different end-user settings, reflecting diverse patient populations and treatment protocols.
- Hospitals:These institutions are the primary end-users for antithrombin, administering therapies for both prophylactic and acute treatment of thromboembolic events. Large academic medical centers in the United States drive significant volume.
- Research Institutes:These entities utilize antithrombin for preclinical and clinical studies, exploring new therapeutic indications and product formulations. European research centers contribute to understanding antithrombin's role in novel conditions.
- Diagnostic Laboratories:These facilities use antithrombin for specialized coagulation testing and deficiency screening, supporting clinical decision-making.
- Ambulatory Surgical Centers:These centers increasingly perform less invasive procedures, requiring antithrombin for specific patient cohorts needing thrombosis prevention.
Hospitals establish the dominant procurement patterns for antithrombin products. Research Institutes influence future market directions through ongoing clinical investigations.
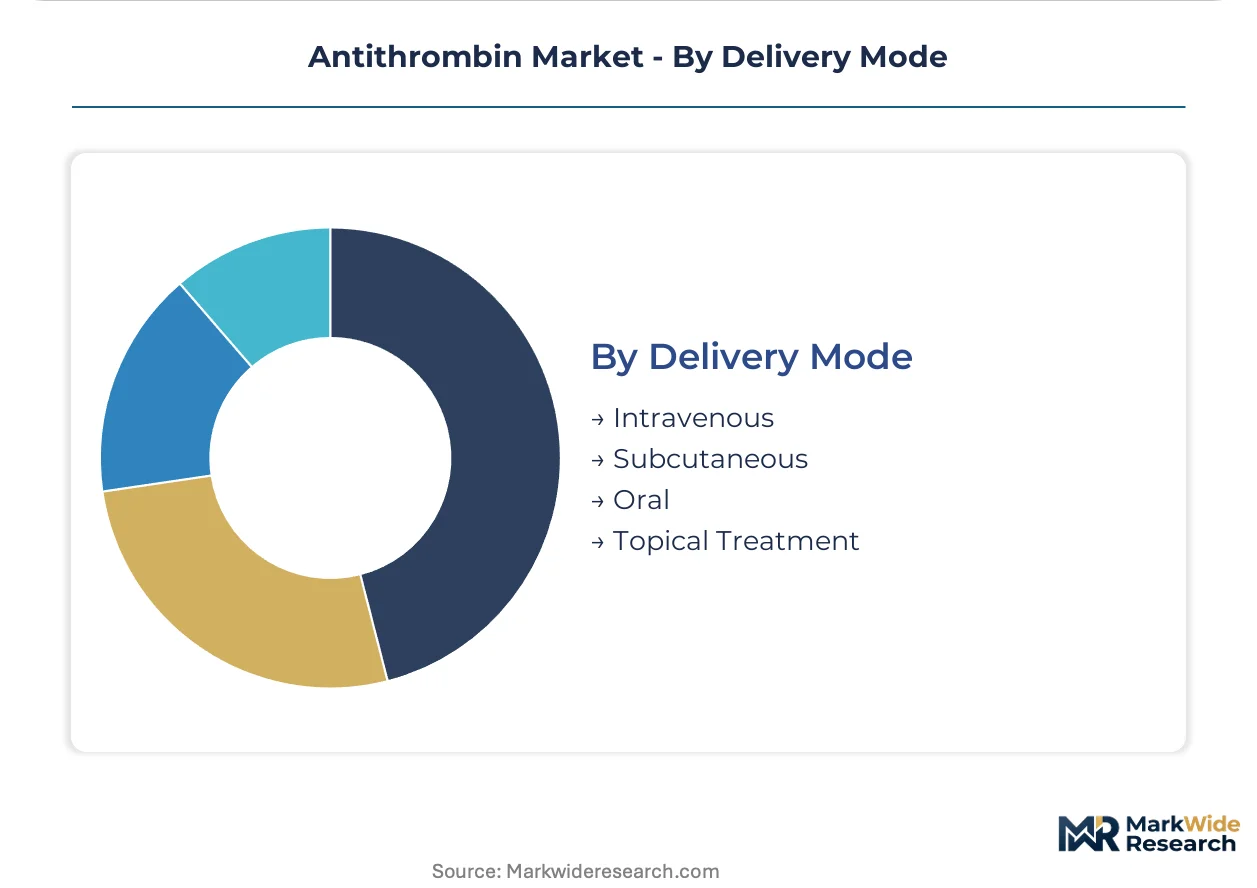
Delivery Mode:
The choice of antithrombin delivery mode is often dictated by patient acuity and the specific clinical setting, catering to distinct customer needs.
- Intravenous:This delivery mode ensures rapid systemic distribution of antithrombin, crucial for acute thromboembolic events and during surgical procedures like cardiopulmonary bypass. Hospitals globally primarily utilize intravenous administration for critical care.
- Subcutaneous:This mode allows for slower absorption and sustained release, suitable for prophylactic use and long-term management of antithrombin deficiency. Demand for subcutaneous options is emerging in home care settings in developed economies.
- Oral:Oral antithrombin formulations are currently limited but represent a future area of research for chronic management, aiming for improved patient convenience.
- Topical Treatment:This localized application of antithrombin is primarily in experimental stages for specific indications, such as wound healing or localized thrombosis prevention.
Intravenous administration represents the most mature delivery method for antithrombin. Subcutaneous options are gaining traction for their convenience in certain patient groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced healthcare infrastructure drives significant demand for antithrombin, particularly in complex surgical procedures. This demand often pulls products from global manufacturers, including those with substantial operations in the United States and Switzerland. The market observes a shift in supply dynamics from plasma-derived to recombinant sources.
Germany
Germany exhibits strong demand for antithrombin, driven by its high volume of complex surgical procedures, especially cardiopulmonary bypass. The European Medicines Agency (EMA) guidelines set rigorous standards for product approval, influencing market access. Specialized cardiac centers in Berlin actively adopt advanced antithrombin therapies for critical care management.
United States
The United States maintains significant demand for antithrombin, primarily for venous thromboembolism treatment and established plasma-derived products. U.S. FDA regulations govern product development and market entry, ensuring strict safety and efficacy standards. Large academic medical centers in Boston lead in therapeutic guideline development and clinical trials for new antithrombin applications.
China
China presents a growing market for antithrombin, fueled by an expanding patient base with rare hematological disorders and improving diagnostic capabilities. China's NMPA enforces stringent regulatory frameworks for both imported and domestically produced antithrombin products. Biopharmaceutical hubs in Shanghai are increasing research into recombinant antithrombin manufacturing and local clinical adoption.
Japan
Japan's market for antithrombin is influenced by its aging population and a high prevalence of advanced medical procedures requiring anticoagulation. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict quality control and approval processes for antithrombin products. Research institutes in Tokyo contribute significantly to clinical studies on novel antithrombin formulations and therapeutic applications.
Switzerland
Switzerland holds importance for high-value protein therapeutics, including antithrombin, due to its strong pharmaceutical industry. Swissmedic maintains rigorous standards for medicinal products, aligning with European benchmarks. Biotech clusters in Basel are centers for developing advanced protein therapeutics and supporting clinical research into antithrombin's broader applications.
Antithrombin Market Key Industry Players
Channel-controlling players compete with product-specialist players in the antithrombin market, creating a tiered competitive structure. The market sees a mix of established plasma fractionators with extensive collection networks and emerging biotechnology innovators focused on recombinant technologies. Archetypes include large diversified pharmaceutical companies with broad portfolios, specialized rare disease biotechs, and dedicated plasma collection and fractionation network operators. Strategic partnerships for technology transfer and geographic expansion into underpenetrated markets represent dominant competitive moves.
Among established plasma fractionators, Grifols, S.A., a Spanish company, exemplifies the deep vertical integration required for plasma-derived antithrombin production. CSL Behring, operating from Switzerland, represents a diversified protein therapeutics specialist, leveraging expertise in both plasma-derived and recombinant options. Takeda Pharmaceutical Company Limited, a Japanese multinational, occupies a position focused on rare hematological disorders, which often includes antithrombin deficiencies. These companies anchor different segments of the supply chain and product innovation.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols, S.A. |
| Octapharma AG |
| Takeda Pharmaceutical Company Limited |
| LFB USA |
| Kedrion S.p.A. |
| rEVO Biologics |
| Shire plc |
| Sobi |
| Others |
Cost & Logistics Intelligence
The transition to recombinant antithrombin manufacturing represents a significant upstream concentration shift. This shift influences where profit margins can be captured within the supply chain, moving from plasma collection to biopharmaceutical production.
Pricing Analysis
The pricing gap between established plasma-derived antithrombin and newer recombinant versions is significant. Per-unit transactional pricing dominates, with differentiation stemming from consistent supply and reduced risk of plasma-borne pathogens. Pricing pressure stems from the high research and development costs associated with recombinant technologies. Hospitals for routine prophylactic use exhibit higher price sensitivity, while specialized cardiac centers prioritize product efficacy for critical procedures.
Supply Chain Analysis
Single-source vulnerability from human plasma collection remains a primary supply chain risk for a significant market segment. Geographic supply concentrates in the United States for plasma-derived products and Germany for recombinant technology development. Raw material dependencies include human plasma, cell culture media, and specialized purification reagents. Regulatory restrictions on manufacturing and import represent a structural risk. Distribution channels primarily involve direct sales to hospitals and specialized pharmaceutical distributors globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antithrombin market is experiencing a platform-economics inflection point, driven by the shift towards integrated coagulation diagnostics and personalized medicine strategies.
For Market Incumbents:
Entrenching market leadership requires established players to diversify their product portfolios. Investing in advanced pathogen inactivation technologies for plasma-derived products strengthens their existing base against biosimilar competition. Accelerating recombinant pipeline research and development in novel expression systems mitigates long-term reliance on plasma supply. Vertical integration into plasma collection networks provides upstream control, while R&D in next-generation recombinant technologies secures future market share.
For New Entrants and Emerging Players:
Underpenetration in diagnostic capabilities across Latin America and Southeast Asia offers a significant entry point. Focusing on early-stage antithrombin deficiency diagnosis in these regions represents a penetrable segment. A go-to-market strategy centered on educational initiatives, coupled with diagnostic partnerships, can drive initial adoption. Targeting specific regional healthcare systems with unmet needs for consistent antithrombin supply provides a clear white-space opportunity.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with specialized biopharmaceutical firms focusing on novel recombinant protein expression. The long-term viability of the antithrombin market is sustained by critical care demand and expanding therapeutic indications. Acquisition targets should include advanced diagnostic firms that enable personalized medicine integration. A key signal to watch is the successful completion of Phase 3 clinical trials for antithrombin in new indications, indicating significant market expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands therapeutic scope for antithrombin beyond current indications, validating new patient populations. |
| Manufacturing Scale-Up | Ensures consistent, high-volume supply of recombinant antithrombin, mitigating plasma dependency. |
| Licensing Agreement | Facilitates market entry into regulated regions like China, leveraging local expertise and distribution networks. |
| Pipeline Diversification | Addresses evolving clinical needs by developing antithrombin variants or combination therapies. |
| Hospital System Partnership | Secures formulary inclusion and streamlines product adoption within major healthcare networks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, and clinical trial registries. Primary interviews were conducted with regulatory affairs leads, hospital procurement managers, R&D directors, and specialized clinicians. This approach enabled bottom-up and top-down triangulation of market data, ensuring comprehensive validation. Industry association reports and academic publications further informed the analysis.
Forecast inputs considered include historical market performance, technological advancements, and evolving regulatory landscapes. The analytical framework projects market trends across the analysis window, modeling segmentation dimensions such as product type, therapy area, end user, and delivery mode. Compound annual growth rates were derived from historical trends and projected market dynamics, incorporating incidence rates of thromboembolic events and adoption rates of recombinant technologies.
Practitioners should monitor unforeseen clinical trial outcomes and major shifts in plasma availability for early signals. Forecasts reflect assumptions regarding market evolution and technological progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Anti-Infective Vaccines Market