
 Human Genetics Market | 2026-2036
Human Genetics Market Size, Share, and Industry Trends Forecast 2026-2036
Human Genetics Market Outlook
Direct-to-consumer genetic testing distribution is narrowing as regulatory scrutiny intensifies and physician-mediated channels gain preference. Illumina dominates sequencing instrument placement across academic and clinical settings, leveraging installed-base economics to sustain recurring revenue from consumables. Thermo Fisher Scientific competes through integrated workflow solutions spanning sample preparation to data analysis. CRISPR Therapeutics anchors gene-editing pipelines with therapeutic programs targeting inherited blood disorders, positioning the company at the forefront of curative modalities.
Human genetics encompasses the study of DNA variation, inheritance patterns, and gene-environment interactions, employing technologies that resolve nucleotide-level differences across genomes ranging from single-gene targets to whole-genome assemblies exceeding three billion base pairs. Its primary commercial purpose spans diagnostic classification, therapeutic target identification, and predictive risk stratification for precision intervention. Next-Generation Sequencing leads product-type value generation through declining per-base costs and expanding reimbursement for tumor profiling and hereditary cancer panels. Gene Therapy represents the fastest-expanding application segment, with one-time curative constructs commanding premium pricing and attracting concentrated venture funding. Genetic Testing through microarray platforms retains relevance in consumer ancestry and carrier screening segments where regulatory barriers remain lower than clinical diagnostic categories.
The FDA oversees gene therapy investigational new drug applications and breakthrough therapy designations, while HIPAA governs patient genetic data privacy and interoperability constraints affecting clinical laboratory information exchange. The EPA regulates reagent manufacturing waste streams and facility emissions from large-scale sequencing operations, adding compliance cost layers to production economics. Stakeholders must monitor evolving reimbursement policies from CMS and private payers, as coverage determinations for whole-genome sequencing and somatic tumor profiling will dictate accessible market size and investment allocation across diagnostic versus therapeutic development priorities.
Market Dynamics
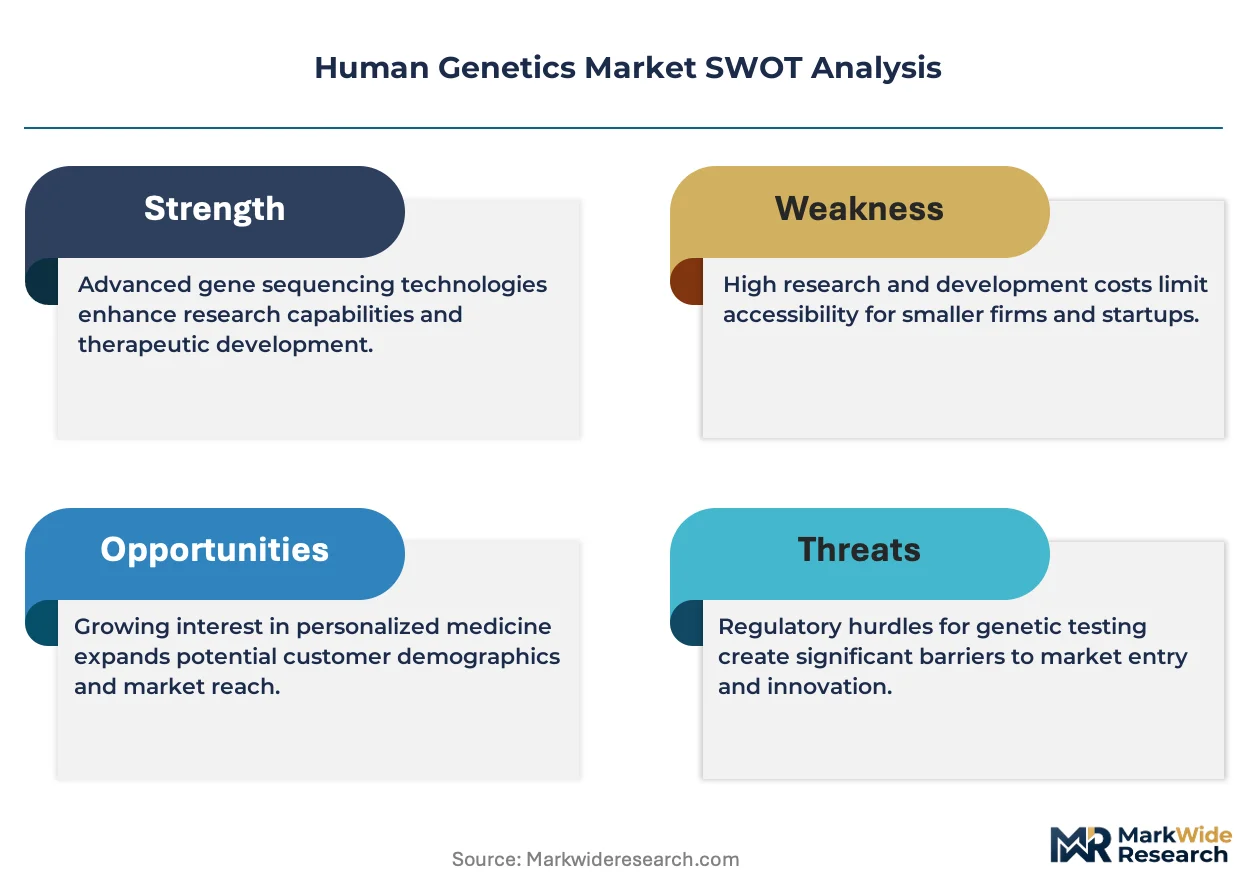
The FDA's evolving framework for gene therapy approvals is compressing product development timelines while simultaneously elevating compliance costs, creating divergent commercial pathways that favor well-capitalized developers over emerging entrants.
Growth Catalysts
- CMS reimbursement expansion:Coverage determinations for somatic tumor profiling and hereditary cancer panels are unlocking clinical laboratory volumes across academic medical centers in the United States.
- CRISPR platform maturation:Gene-editing workflows are reducing therapeutic development timelines for inherited blood disorders, attracting concentrated venture funding into curative modalities.
- Boston-San Francisco cluster density:Geographic concentration of biotech R&D infrastructure is accelerating talent migration and cross-institutional collaboration in precision medicine.
Market Restraints
- Reagent supply concentration:Sequencing consumables depend on a limited supplier base, creating vulnerability to price volatility and allocation constraints.
- HIPAA interoperability friction:Patient genetic data privacy rules are constraining clinical laboratory information exchange, fragmenting diagnostic workflows.
- Whole-genome sequencing cost floor:Per-base economics plateau below the reimbursement threshold for routine screening applications, limiting addressable market expansion.
Strategic Opportunities
- Physician-mediated channel preference:Regulatory scrutiny on direct-to-consumer distribution is redirecting demand toward clinical diagnostic pathways with higher margin capture.
- Integrated workflow convergence:Sample preparation-to-analysis platforms are compressing hands-on time and reducing error rates in high-throughput oncology screening.
- Rare disease screening mandates:State-level newborn screening expansions are creating captive demand for carrier detection and early intervention protocols.
Industry Challenges
- Bioinformatics talent scarcity:Computational genomics and variant interpretation expertise is concentrated in coastal academic clusters, constraining scaling for mid-market laboratories.
- EPA reagent manufacturing compliance:Waste stream regulations and facility emission controls are adding fixed cost layers to large-scale sequencing operations.
- Installed-base lock-in dynamics:Instrument placement economics create switching friction for laboratories seeking to migrate between sequencing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Genetics Market |
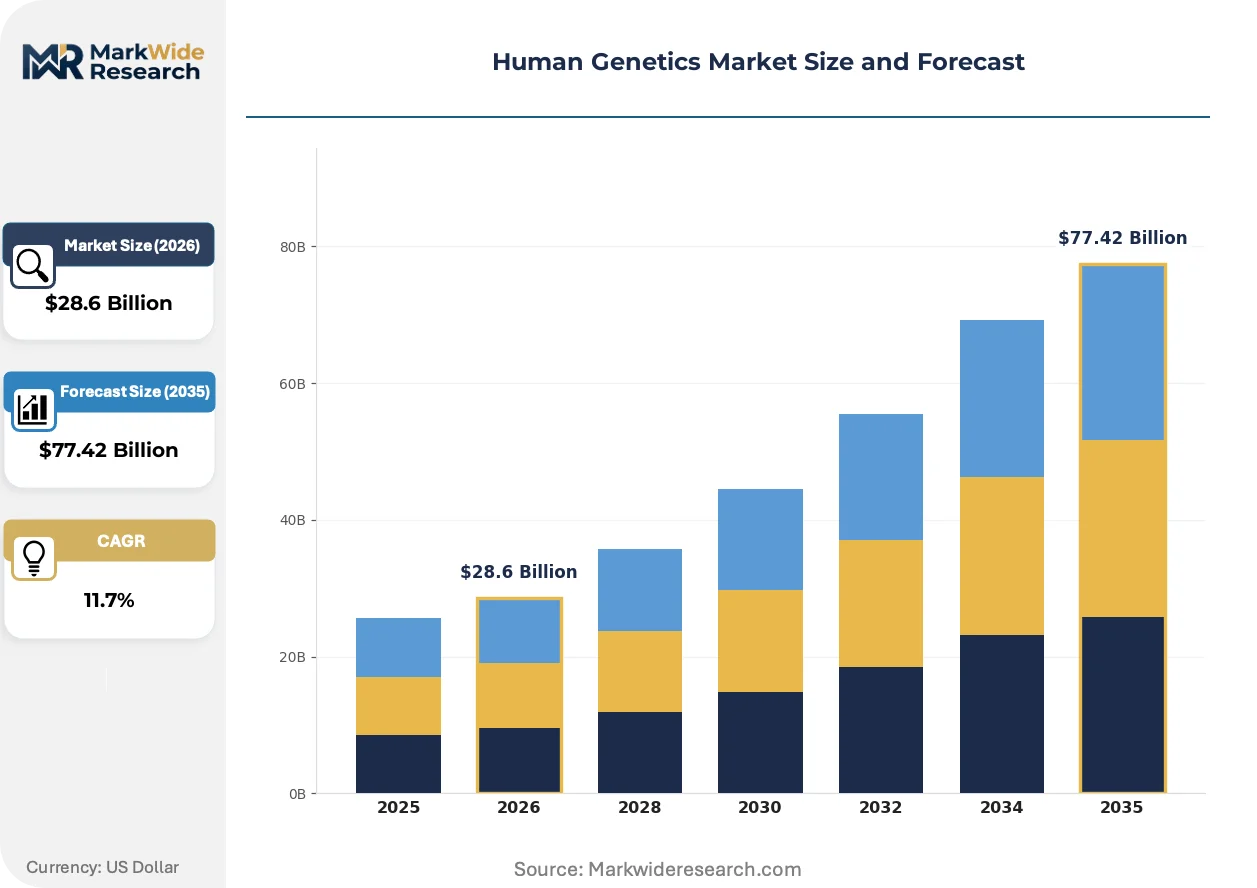
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomic Sequencing, Gene Editing, Genetic Testing, Gene Therapy End User: Research Laboratories, Clinical Laboratories, Hospitals, Pharmaceutical Companies Technology: CRISPR, Next-Generation Sequencing, PCR, Microarray Application: Diagnostics, Drug Discovery, Personalized Medicine, Prenatal Testing |
| Companies Covered | Vertex Pharmaceuticals, Gilead Sciences, Thermo Fisher Scientific, CRISPR Therapeutics, Agilent Technologies, Illumina, Amgen, Alnylam Pharmaceuticals, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Genetics Market Strategic Shifts
Technological convergence between sequencing hardware and AI-driven variant calling is compressing diagnostic turnaround times while elevating analytical accuracy thresholds. Regulatory frameworks are simultaneously tightening data governance requirements and accelerating therapeutic approval pathways.
Long-read sequencing platforms are hybridizing with short-read workflows to resolve structural variants and repetitive regions previously inaccessible to conventional methods. Clinical laboratories in oncology and rare disease programs are adopting these hybrid approaches to reduce ambiguous variant calls. The technology is hybridizing diagnostic confidence levels with reimbursement requirements, enabling definitive classification of pathogenic variants that previously required orthogonal confirmation.
The FDA's breakthrough therapy designation pathway is compressing gene therapy development timelines by enabling earlier and more intensive agency engagement. Sponsors are restructuring clinical trial designs to accommodate accelerated approval mechanisms, prioritizing surrogate endpoints and post-marketing commitment frameworks. Gene therapy programs targeting inherited blood disorders are most affected, with developers reallocating resources toward manufacturing scale-up earlier in the development cycle.
Hospital procurement committees are consolidating vendor relationships around integrated workflow providers capable of spanning sample preparation through clinical reporting. Academic medical centers are displacing point-solution vendors with platform partnerships that bundle instruments, consumables, and bioinformatics support. This concentration is most visible in the United States, where IDN consolidation is amplifying purchasing leverage and compressing switching cycles for sequencing infrastructure.
Human Genetics Market Segmentation
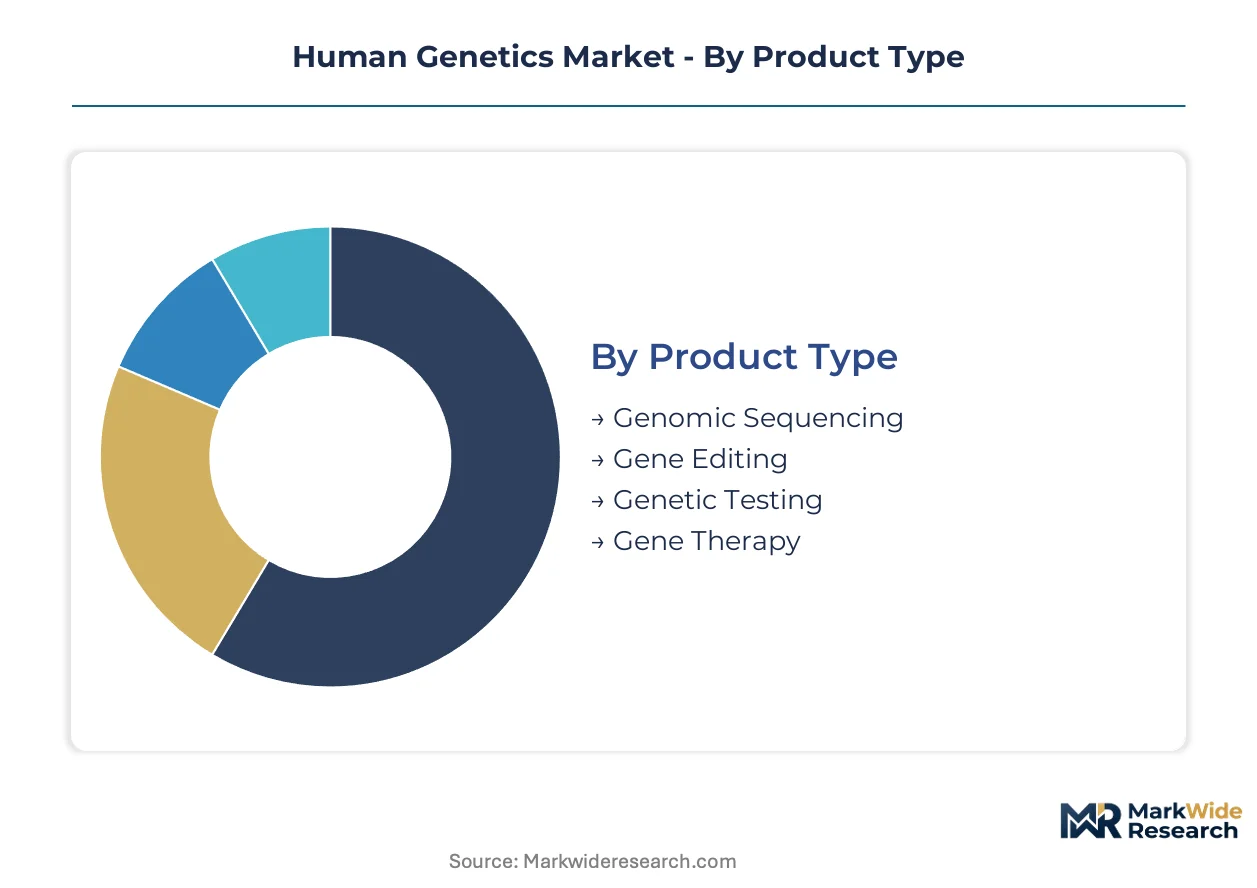
Segmentation in human genetics reveals divergent margin profiles and capital intensity across technology platforms. Product type determines recurring revenue potential, while end-user concentration shapes regulatory exposure and reimbursement pathways.
Product Type:
Cycle times vary dramatically across product categories, with consumable-heavy platforms turning inventory fastest and capital equipment experiencing extended replacement intervals.
- Genomic Sequencing:Instruments and consumables resolving nucleotide-level variation across whole genomes or targeted panels. Academic medical centers in Boston and San Francisco are concentrating procurement around Illumina's installed base, locking in multi-year consumable commitments.
- Gene Editing:CRISPR-based therapeutic constructs and research reagents enabling precise DNA modification. Venture funding is flooding into curative programs targeting sickle cell disease and beta-thalassemia, compressing development timelines through FDA breakthrough designations.
- Genetic Testing:Clinical and consumer-facing assays spanning carrier screening to tumor profiling. Physician-mediated channels are displacing direct-to-consumer distribution as FDA scrutiny intensifies on health-related claims.
- Gene Therapy:One-time curative viral vector deliveries commanding premium pricing. Manufacturing scale-up constraints are creating supply bottlenecks for approved therapies treating inherited retinal diseases and spinal muscular atrophy.
Genetic Testing anchors the volume base while Gene Therapy gains share at the steepest rate.
End User:
Customer type stratifies by reimbursement sophistication and regulatory burden, with clinical settings demanding higher compliance investment than research environments.
- Research Laboratories:Academic and government facilities conducting basic science and translational studies. Funding from NIH and NSF is concentrating in coastal biotech clusters, with equipment refresh cycles tied to grant award timelines.
- Clinical Laboratories:CAP-accredited facilities processing diagnostic samples under CLIA oversight. CMS reimbursement expansion for somatic tumor profiling is unlocking test volumes across integrated delivery networks.
- Hospitals:In-house molecular pathology departments and precision medicine programs. IDN consolidation is amplifying purchasing leverage, favoring integrated workflow vendors over point-solution providers.
- Pharmaceutical Companies:Biopharma R&D and companion diagnostic co-development. Gene therapy sponsors are restructuring trial designs around accelerated approval pathways, prioritizing surrogate endpoints.
Clinical Laboratories capture the highest throughput volumes while Pharmaceutical Companies deliver the steepest margin expansion.
Technology:
Platform maturity determines competitive dynamics, with established methods defending installed bases against disruptive alternatives.
- CRISPR:Programmable nuclease systems enabling targeted gene knockout, insertion, or base editing. CRISPR Therapeutics and Editas Medicine are anchoring therapeutic pipelines in inherited blood disorders, attracting concentrated venture allocation.
- Next-Generation Sequencing:Massively parallel short-read platforms dominating clinical and research applications. Per-base cost declines have plateaued above reimbursement thresholds for routine screening, constraining addressable market expansion.
- PCR:Amplification-based targeted detection retaining dominance in infectious disease and forensic applications. qPCR instruments occupy lower-cost niches where sequencing economics remain prohibitive.
- Microarray:Hybridization-based genotyping platforms sustaining relevance in consumer ancestry and agricultural breeding. Regulatory barriers remain lower than clinical diagnostic categories, preserving distribution flexibility.
Next-Generation Sequencing commands the largest installed base while CRISPR platforms are expanding most quickly into therapeutic development.
Application:
Use case differentiation reflects reimbursement granularity and regulatory classification complexity across diagnostic versus therapeutic domains.
- Diagnostics:Disease classification through germline or somatic variant detection. Hereditary cancer panels and rare disease exome sequencing are gaining CMS coverage, driving clinical laboratory adoption.
- Drug Discovery:Target identification and validation through functional genomics screens. Biopharma is outsourcing sequencing infrastructure to CROs with integrated bioinformatics capabilities.
- Personalized Medicine:Treatment selection based on pharmacogenomic or tumor profiling data. Oncology programs are leading adoption, with companion diagnostics required for targeted therapy approval.
- Prenatal Testing:Non-invasive fetal aneuploidy screening and carrier detection. State-level newborn screening mandates are creating captive demand for expanded panel testing.
Diagnostics generates the highest test volumes while Personalized Medicine is climbing the fastest as reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of Germany by a factor of two, reflecting divergent reimbursement frameworks and regulatory risk appetites. Japan commands premium positioning for gene therapy approvals, while China leverages manufacturing scale to compress reagent costs. Geographic concentration of clinical trial infrastructure and venture capital pools determines competitive access across major markets.
United States
FDA breakthrough therapy designations for gene editing programs are accelerating development timelines for sickle cell interventions. CMS reimbursement expansion for somatic tumor profiling is unlocking test volumes across integrated delivery networks. Boston and San Francisco biotech clusters concentrate venture funding and academic medical center procurement power.
Germany
EMA centralized marketing authorizations for advanced therapy medicinal products are streamlining commercial pathways across EU member states. Germany's national reimbursement framework for molecular diagnostics is expanding coverage for hereditary cancer panels. Heidelberg and Munich research institutes anchor EU-wide genomic data sharing initiatives under GDPR-compliant architectures.
China
NMPA accelerated approval pathways for innovative biologics are compressing regulatory timelines for domestic gene therapy developers. The country's dual carbon goals are reshaping reagent manufacturing facility emissions compliance requirements. Shanghai and Suzhou biotech parks concentrate CDMO capacity for viral vector production serving Asia-Pacific markets.
United Kingdom
MHRA post-Brexit regulatory autonomy is enabling differentiated approval timelines for gene therapy products versus EU procedures. NHS England genomic medicine service expansion is driving centralized procurement for whole-genome sequencing infrastructure. Cambridge and London research corridors concentrate CRISPR patent licensing activity and spin-out formation.
Japan
PMDA sakigake designation system is prioritizing review resources for regenerative medicine and gene therapy applications. Japan's national health insurance price listing for companion diagnostics is stabilizing revenue predictability for oncology testing. Kanto region academic medical centers lead Asia-Pacific adoption of long-read sequencing platforms for rare disease classification.
Human Genetics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in consumables and reagent supply. The vendor base stratifies between instrument manufacturers defending installed-base economics and emerging entrants attacking specific workflow steps. Three archetypes dominate: sequencing platform incumbents leveraging consumable recurring revenue, gene therapy developers pursuing curative premium pricing, and integrated workflow providers bundling sample-to-analysis solutions. Competitive dynamics center on M&A consolidation of point-solution vendors and strategic partnerships between instrument manufacturers and clinical laboratory networks.
Among platform-integrated players, Illumina and Thermo Fisher Scientific exemplify the instrument-to-consumable revenue model anchoring academic and clinical laboratory procurement. CRISPR Therapeutics occupies a distinct position within the gene editing archetype, representing the therapeutic development pathway targeting inherited blood disorders. These three entities collectively illustrate the divergence between diagnostic infrastructure economics and curative modality development timelines reshaping capital allocation across the sector.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| Gilead Sciences |
| Thermo Fisher Scientific |
| CRISPR Therapeutics |
| Agilent Technologies |
| Illumina |
| Amgen |
| Alnylam Pharmaceuticals |
| Regeneron Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Reagent manufacturing concentration in China and South Korea anchors cost structures for sequencing consumables, pushing margin pools toward instrument manufacturers with locked-in installed bases and gene therapy developers commanding curative premiums. The interaction between upstream chemical synthesis capacity and downstream pricing power creates divergent profitability across platform types.
Pricing Analysis
Configured-to-order gene therapy constructs command substantial premiums over standard diagnostic reagent pricing. The market operates on a hybrid model combining per-unit transactional sales for consumables with value-based arrangements for one-time curative treatments. Price differentiation hinges on regulatory certification tier and customization complexity, with FDA breakthrough-designated therapies capturing the widest spreads. Pricing pressure stems from CMS reimbursement compression on tumor profiling panels. Academic medical centers exhibit the highest price sensitivity, while pharmaceutical sponsors demonstrate the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for sequencing instrument components. Manufacturing concentrates in China, Singapore, and Germany for reagent production and precision optics. Raw material dependencies include semiconductor-grade silicon, fluorescent dyes, and viral vector production cell lines. Single-source vulnerability persists for CRISPR guide RNA synthesis and proprietary polymerase enzymes. Distribution runs through integrated delivery network procurement committees consolidating vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The human genetics market is entering a cyclical recovery phase as FDA gene therapy approval velocity accelerates and CMS reimbursement frameworks expand coverage for precision diagnostics. Venture funding concentration in Boston and San Francisco clusters signals capital rotation back toward curative modalities.
For Market Incumbents: Insulate consumable revenue streams through multi-year service contracts with academic medical centers facing instrument refresh cycles. Lock in CLIA-certified laboratory partnerships before emerging entrants achieve CAP accreditation. Prioritize backward integration into reagent manufacturing to offset supplier concentration risk from Chinese chemical synthesis dependence.
For New Entrants and Emerging Players: Pursue white-space opportunities in long-read sequencing bioinformatics services where talent scarcity constrains incumbent scaling. Target mid-market clinical laboratories in secondary US metropolitan areas lacking integrated workflow vendors. Deploy cloud-native variant interpretation platforms as the primary go-to-market angle to bypass installed-base switching friction.
For Investors and Strategic Acquirers: Capital is best deployed toward gene editing platform companies with IND-ready inherited blood disorder programs and manufacturing scale-up partnerships already established. Long-term viability over the coming decade rests on regulatory approval velocity rather than pipeline breadth alone. Watch FDA breakthrough therapy designation grant rates as the critical inflection signal for sector-wide valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO partnerships for viral vector production alleviate supply bottlenecks constraining approved gene therapy distribution. |
| Regulatory Approval Pathway | FDA breakthrough therapy designations compress development timelines for sickle cell and beta-thalassemia interventions. |
| Platform Integration | Sample-to-analysis workflow bundling displaces point-solution vendors from IDN procurement committees. |
| Strategic Partnership | Academic medical center alliances secure captive demand for sequencing infrastructure and bioinformatics support. |
| Reimbursement Strategy | CMS coverage determinations for whole-genome sequencing unlock addressable market expansion beyond research applications. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with sequencing platform executives, clinical laboratory directors, gene therapy regulatory leads, and hospital procurement managers; and secondary validation against FDA filings, CMS national coverage determinations, ClinicalTrials.gov records, and SEC 10-K disclosures from publicly traded instrument manufacturers. Bottom-up segment sizing triangulated against top-down market aggregation from NIH funding allocations and venture capital flow data.
Forecast inputs incorporated technology adoption curves across the projection horizon, with segmentation modeling across product type, end-user concentration, and application area. CAGRs derived from regression analysis of historical instrument placement rates, consumable pull-through ratios, and therapeutic approval velocity. Industry-specific inputs included gene therapy manufacturing capacity buildout timelines and state-level newborn screening mandate expansion patterns.
Sensitivities concentrate around FDA approval timeline shifts and CMS reimbursement reversals for molecular diagnostic categories. Forecasts reflect assumptions about regulatory pathway stability and venture funding continuity in coastal biotech clusters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Dna Polymerase Market
Genomics
DNA Gene Chip Market
Genomics
Microarray Scanners Market
Genomics
Genome Sequencing Market
Genomics
Nutrigenomics Testing Market
Genomics
Digital Genome Market
Genomics
Rare Disease Genetic Testing Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Latin America Gene Expression Market
Genomics
SNP Genotyping Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Global Nutrigenomics Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Mrna Sequencing Market
Genomics
Pre-Pregnancy Genetic Testing Market