
 Global Imaging Chemicals Market | 2026-2036
Global Imaging Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Imaging Chemicals Market Foresight
EU REACH restrictions on silver compound discharge is broadening reformulation mandates across European photographic chemical suppliers. FUJIFILM Holdings Corporation leverages captive emulsion manufacturing to control raw material quality across its medical imaging supply chain. Eastman Kodak Company sustains legacy film processing chemistry production while navigating declining consumer film volumes. Agfa-Gevaert N.V. dominates hospital radiology departments through long-term service contracts bundled with X-ray developer chemistry.
Imaging chemicals encompass light-sensitive formulations—principally silver halide emulsions, redox developer solutions, and thiosulfate fixers—engineered to capture, amplify, or stabilize latent images across analog and hybrid digital-analog workflows. Photographic emulsions retain structural importance in high-resolution holographic and archival applications where pixel-based sensors fail to match dynamic range. Digital printing inks represent the fastest-expanding application segment, absorbing pigment dispersion advances from adjacent graphic arts chemistry. Medical diagnostic centers anchor end-user demand through recurring consumable contracts for radiographic film processing, while holography studios occupy a premium niche requiring custom-formulated panchromatic emulsions.
FDA 21 CFR Part 892 governs diagnostic imaging agent quality in the United States, while EU MDR reclassifies certain radiographic contrast and processing materials under stricter clinical evidence requirements. Japan's METI chemical substance reporting mandates shape supplier transparency obligations for silver-based formulations exported to East Asian electronics manufacturers. Stakeholders must monitor evolving perfluorinated substance restrictions in the EU and corresponding state-level analogs in California and New York, as these chemicals appear in select anti-halation backing layers and coating surfactants.
Market Dynamics
Silver halide emulsion chemistry faces displacement pressure from digital radiography and inkjet pigment systems, yet retains structural demand in holographic recording, archival preservation, and defense applications where dynamic range requirements exceed CMOS sensor capabilities.
Growth Catalysts
- EU MDR Compliance Deadlines:Medical diagnostic centers across Germany, France, and Italy are accelerating procurement of certified X-ray processing chemicals ahead of stricter clinical evidence requirements for radiographic materials.
- Holographic Recording Expansion:Japanese electronics manufacturers are redirecting R&D budgets toward custom-formulated panchromatic emulsions for volume holography in data storage and authentication applications.
- Defense Research Procurement:United States military laboratories sustain bulk purchasing agreements for specialized photographic formulations used in high-speed imaging and reconnaissance systems.
Market Restraints
- Silver Price Volatility:Fluctuations in London Bullion Market Association silver pricing directly compress margins for emulsion manufacturers dependent on halide salt inputs.
- REACH Discharge Restrictions:ECHA mandates on silver compound wastewater limits force European suppliers into costly effluent treatment infrastructure or reformulation cycles.
- Digital Radiography Substitution:Flat-panel detector systems in hospital radiology departments eliminate recurring consumable demand for wet-chemistry film processing.
Strategic Opportunities
- India Diagnostic Infrastructure:Tier-2 and Tier-3 cities are expanding analog X-ray capacity faster than digital retrofitting, creating sustained demand for developer and fixer chemistry.
- Perfluorinated Alternative Development:California and New York state-level restrictions on PFAS in coating surfactants are opening formulation contracts for fluorine-free anti-halation backing layers.
- Hybrid Digital-Analog Workflows:Archival institutions and fine-art photographers are converging silver-gelatin printing with digital negative inkjet output, requiring specialized emulsion coatings.
Industry Challenges
- Emulsion Chemistry Expertise Scarcity:Retirement waves among gelatin-dispersion engineers and precipitation kettle operators threaten knowledge continuity at legacy manufacturing sites.
- ISO 9001 and ISO 13485 Certification Timelines:Medical-grade chemical suppliers face 18-24 month audit cycles to maintain quality management system credentials for diagnostic market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Imaging Chemicals Market |
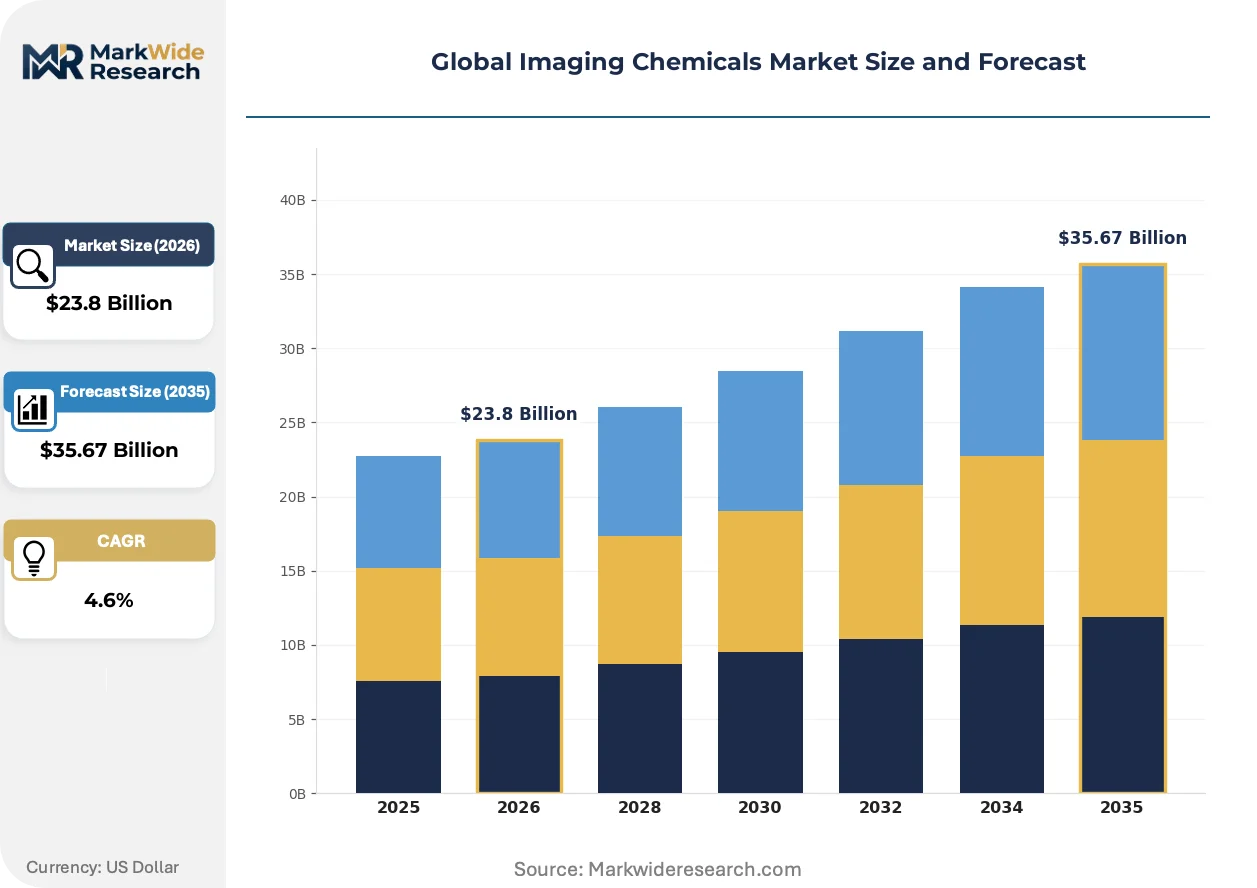
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photographic Emulsions, Color Developers, Fixers, Stop Baths, Bleach Solutions, Hardeners Application: Film Processing, Digital Printing, Photographic Paper, X-ray Imaging, Lithography, Holography End User: Photographic Labs, Print Shops, Medical Diagnostic Centers, Research Institutes, Holography Studios Form: Liquid, Powder, Gel, Emulsion, Concentrate |
| Companies Covered | FUJIFILM Holdings Corporation, Eastman Kodak Company, Agfa-Gevaert N.V., DIC Corporation, Flint Group, Kao Corporation, Vivimed Labs Limited, Sakata INX Corporation, Altana AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Imaging Chemicals Market Shifts & Advancements
Formulation science is pivoting toward hybrid architectures that bridge analog light-sensitivity with digital workflow integration, while regulatory chemistry is forcing systematic replacement of legacy halogenated and metallic components.
Desktop holographic printing systems using self-processing silver halide plates are decentralizing access to volume holography for security labeling and cultural heritage documentation. Museum conservation labs and authentication service providers in Switzerland and the United Kingdom are adopting these systems to bypass centralized industrial coating facilities. The technology is decentralizing what was historically a capital-intensive, supplier-controlled capability into distributed on-demand production.
EU REACH Annex XVII restrictions on perfluorinated substances are compelling reformulation of anti-halation layers and coating surfactants across European photographic chemical suppliers. Industrial consequence includes accelerated R&D spending on fluorine-free wetting agents and revised safety data sheet documentation obligations. Medical imaging film manufacturers serving EU hospital networks are responding by qualifying alternative backing layer chemistries ahead of 2025 enforcement milestones.
Hospital radiology departments are unbundling long-term service contracts from chemistry supply agreements, separating equipment maintenance from consumable procurement. This pattern disrupts bundled vendor relationships that dominated the 2010s and replaces them with competitive tendering for developer, fixer, and replenisher solutions. The shift is most visible in United States hospital networks and German diagnostic center chains seeking procurement flexibility.
Global Imaging Chemicals Market Segmentation
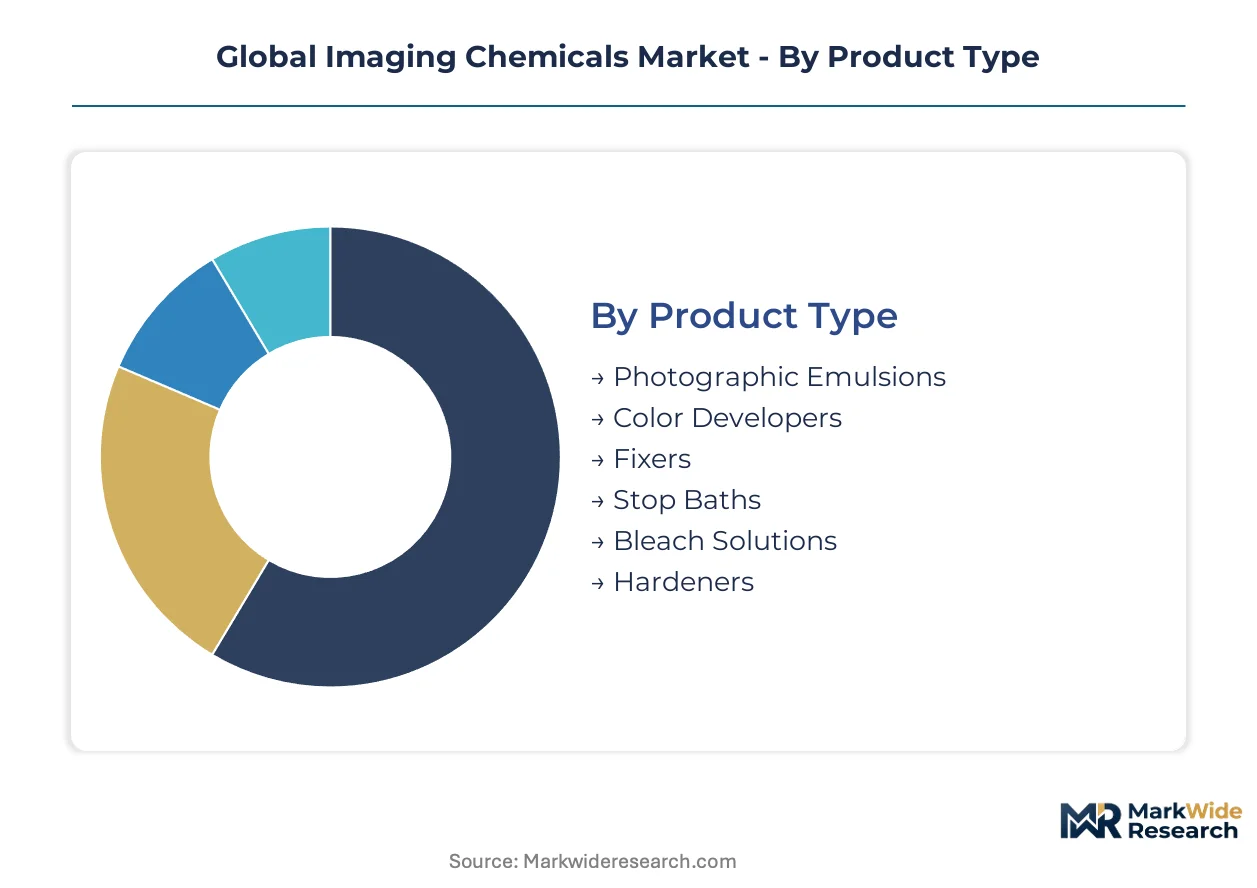
Imaging chemicals demand fragments across incompatible technical specifications, regulatory grades, and workflow architectures. Product chemistry, application environment, and end-user operational scale each impose distinct formulation constraints that prevent universal solutions.
Product Type:
Customization intensity spans from commodity replenisher solutions to precision-engineered emulsion architectures requiring kettle-controlled precipitation.
- Photographic Emulsions:Silver halide crystals suspended in gelatin matrices with grain sizes calibrated to ISO speed ratings and spectral sensitivity curves. Demand concentrates in Japanese holography studios and Swiss authentication labs seeking panchromatic formulations for volume holography where CMOS sensors fail to capture dynamic range.
- Color Developers:Phenylenediamine-based redox solutions engineered for precise oxidation potential control during chromogenic dye formation. Hospital networks in Germany and France are accelerating procurement of EU MDR-certified variants ahead of tightened clinical evidence requirements for radiographic processing materials.
- Fixers:Thiosulfate solutions removing unexposed silver halides through complex ion formation.
- Stop Baths:Acetic acid or citric acid buffers halting development at precise intervals.
- Bleach Solutions:Ferric EDTA or persulfate oxidizers converting metallic silver to silver halide for color reversal.
- Hardeners:Glutaraldehyde or formaldehyde crosslinkers increasing gelatin abrasion resistance.
Most installed capacity flows through Photographic Emulsions. Expansion is steepest in Color Developers.
Application:
Volume concentration versus value capture splits sharply between declining consumable workflows and premium specialty niches.
- Film Processing:Wet-chemistry workflows for silver halide development, fixation, washing, and drying in continuous or batch configurations. Analog X-ray capacity in India's Tier-2 and Tier-3 cities sustains demand faster than digital retrofitting permits, creating recurring consumable contracts for developer and fixer chemistry.
- Digital Printing:Pigment dispersion and dye-based ink formulations for inkjet, electrophotographic, and thermal transfer systems. United States hospital networks and defense research labs sustain bulk purchasing agreements for specialized photographic formulations used in high-speed imaging and reconnaissance documentation.
- Photographic Paper:Resin-coated and fiber-base papers with gelatin emulsion topcoats.
- X-ray Imaging:Medical and industrial radiographic film processing chemistry.
- Lithography:Photoresist and developer chemistry for semiconductor and printed circuit board fabrication.
- Holography:Custom-formulated panchromatic emulsions for volume holography in data storage and authentication.
Digital Printing absorbs the largest production volumes. Holography commands the steepest value-per-kilogram trajectory.
End User:
Procurement sophistication ranges from spot-market chemical purchasing to decade-long bundled service contracts with dedicated replenisher logistics.
- Photographic Labs:Commercial film processing operations serving consumer, professional, and industrial photography markets.
- Print Shops:Graphic arts service providers integrating digital and analog output workflows.
- Medical Diagnostic Centers:Hospital radiology departments and independent imaging clinics processing X-ray, mammography, and dental radiographic films. German diagnostic center chains are unbundling long-term service contracts from chemistry supply agreements, separating equipment maintenance from consumable procurement to enable competitive tendering flexibility.
- Research Institutes:Academic and government laboratories requiring specialized formulations for experimental imaging.
- Holography Studios:Cultural heritage, security labeling, and artistic practitioners requiring custom emulsion specifications.
Medical Diagnostic Centers represent the most concentrated demand pool. Holography Studios exhibit the fastest contract value expansion.
Form:
Logistics economics and shelf stability requirements drive format selection across geographic distribution networks.
- Liquid:Ready-to-use or dilutable solutions for immediate deployment in continuous processors.
- Powder:Dehydrated concentrates reducing shipping weight and extending storage stability.
- Gel:Thickened preparations for specialized coating and brush-applied applications.
- Emulsion:Viscous silver halide suspensions requiring temperature-controlled transport.
- Concentrate:High-strength formulations diluted on-site to reduce packaging and freight costs.
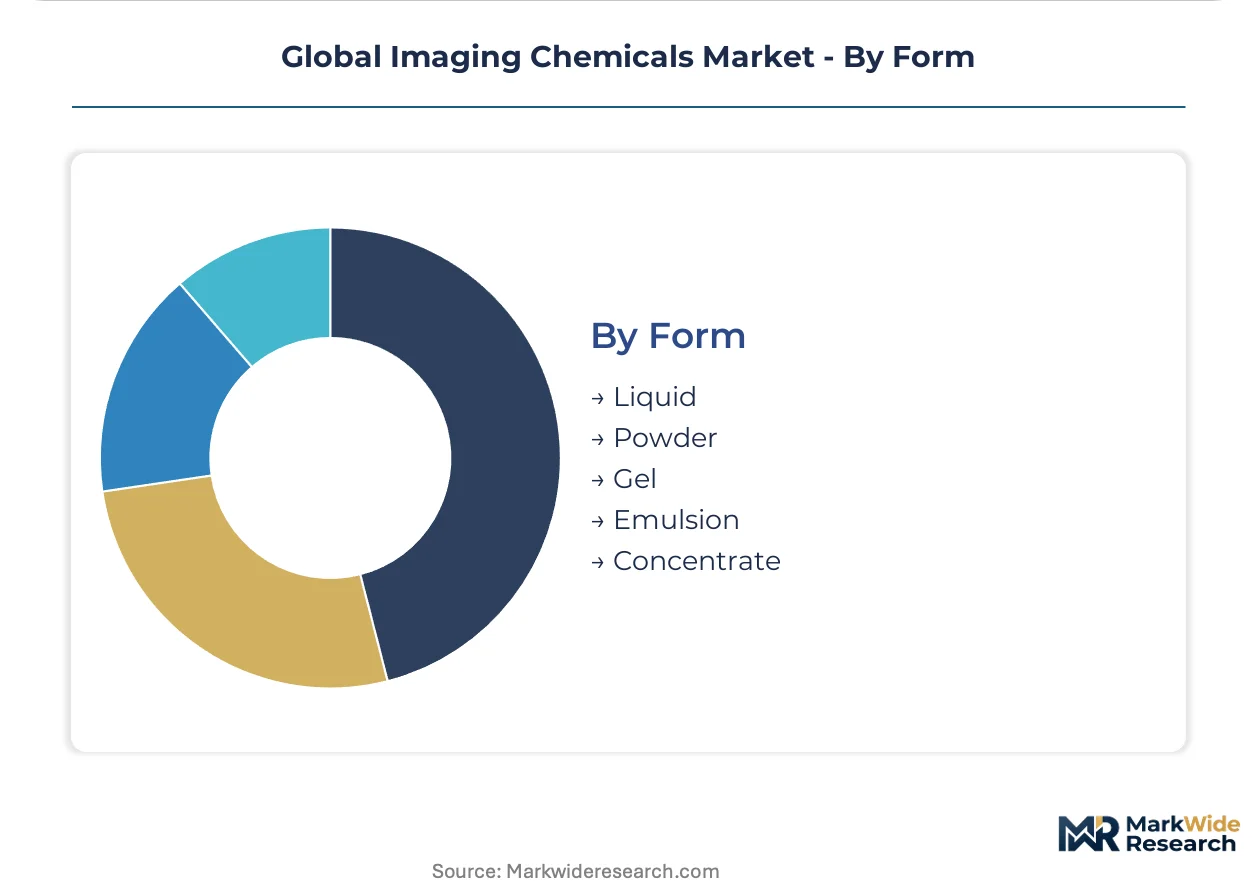
Liquid formulations dominate current installed base throughput. Concentrate formats are gaining share fastest in cost-sensitive procurement environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastman Kodak Company pioneered mass-market photographic chemistry in Rochester, New York, establishing the industrial template that Japanese and European competitors later adapted for medical and holographic applications. This legacy infrastructure continues shaping regional specialization patterns across silver halide formulation clusters.
United States
Defense research laboratories in Maryland and California sustain bulk purchasing agreements for high-speed imaging formulations used in reconnaissance systems. FDA 21 CFR Part 892 governs diagnostic imaging agent quality, requiring extensive documentation for radiographic processing materials. Hospital networks in Texas and Florida are unbundling long-term service contracts from chemistry supply agreements to enable competitive tendering flexibility.
Germany
Medical diagnostic centers in Bavaria and North Rhine-Westphalia are accelerating procurement of certified X-ray processing chemicals ahead of EU MDR compliance deadlines. ECHA REACH restrictions on silver compound discharge are forcing reformulation mandates across photographic chemical suppliers. Industrial chemical clusters around Leverkusen and Ludwigshafen are investing in effluent treatment infrastructure to meet tightened wastewater limits.
Japan
Electronics manufacturers in Tokyo and Osaka are redirecting R&D budgets toward custom-formulated panchromatic emulsions for volume holography in data storage applications. METI chemical substance reporting mandates shape supplier transparency obligations for silver-based formulations exported to regional electronics manufacturers. Holography studios in Yokohama occupy a premium niche requiring precision-engineered spectral sensitivity curves.
India
Tier-2 and Tier-3 cities in Maharashtra and Tamil Nadu are expanding analog X-ray capacity faster than digital retrofitting permits, creating sustained demand for developer and fixer chemistry. CDSCO regulates diagnostic imaging materials under the Medical Devices Rules framework. Hospital procurement in Chennai and Pune favors concentrate formats to reduce packaging and freight costs in cost-sensitive environments.
Switzerland
Museum conservation labs in Zurich and Geneva are adopting desktop holographic printing systems using self-processing silver halide plates for cultural heritage documentation. Swissmedic oversees quality standards for medical imaging applications. Authentication service providers in Basel are decentralizing volume holography production previously concentrated in centralized industrial coating facilities.
Global Imaging Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification intensity in the imaging chemicals sector. The vendor base organizes into three tiers: diversified chemical conglomerates with captive emulsion manufacturing, specialized photographic chemical suppliers serving legacy film markets, and regional formulators competing on replenisher solution pricing. Dominant competitive moves include strategic partnerships with hospital networks for bundled service contracts and geographic expansion into India's diagnostic infrastructure.
Within the diversified conglomerate tier, FUJIFILM Holdings Corporation exemplifies backward integration into raw material quality control, while Eastman Kodak Company occupies a position bridging legacy consumer film production with specialized industrial formulations. Agfa-Gevaert N.V. represents the hospital radiology service contract archetype, anchoring long-term relationships with diagnostic centers through bundled chemistry supply agreements.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Eastman Kodak Company |
| Agfa-Gevaert N.V. |
| DIC Corporation |
| Flint Group |
| Kao Corporation |
| Vivimed Labs Limited |
| Sakata INX Corporation |
| Altana AG |
| Others |
Supply & Pricing Matrix
Silver halide crystal costs cascade from London Bullion Market Association pricing through emulsion manufacturers to tiered buyer contracts, with volatility in precious metal inputs compressing margins most acutely for European suppliers facing ECHA REACH discharge compliance investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified medical-grade formulations from industrial replenisher solutions and commodity spot-market chemistry. Price differentiation hinges on ISO 13485 certification status and volume scale, with hospital network procurement teams commanding steepest discounts through competitive tendering. Cost compression in standard-tier developer and fixer solutions is intensifying because Indian diagnostic centers favor concentrate formats. Medical diagnostic centers exhibit highest price sensitivity; holography studios demonstrate lowest.
Supply Chain Analysis
Retirement waves among gelatin-dispersion engineers in Japan and Germany constrain precipitation kettle operator availability at legacy manufacturing sites. Supply concentrates in Japan, Germany, and the United States, drawing from silver nitrate feedstock, pharmaceutical-grade gelatin, and thiosulfate fixer precursors. Single-source vulnerability sits with Japanese electronics manufacturers dependent on custom panchromatic emulsion supply. Distribution runs through long-term service contracts and competitive tender channels to hospital radiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into procurement urgency, with EU MDR reclassification of radiographic processing materials driving accelerated certification investments across German diagnostic center chains.
For Market Incumbents: Extend captive emulsion manufacturing control into holographic recording material supply chains to defend against Japanese electronics manufacturer backward integration. Deepen ISO 13485 certification coverage across Indian Tier-2 and Tier-3 city distribution networks before digital radiography substitution accelerates.
For New Entrants and Emerging Players: Enter via fluorine-free anti-halation backing layer formulation contracts in California and New York state markets where PFAS restrictions have disqualified incumbent suppliers. Target museum conservation lab desktop holographic printing system chemistry as the most penetrable segment, leveraging direct technical sales to Swiss authentication service providers.
For Investors and Strategic Acquirers: Consolidation pressure builds where emulsion chemistry expertise scarcity intersects with 18-24 month ISO certification audit timelines. Five-to-ten year viability favors acquiring specialized photographic chemical suppliers with existing hospital radiology service contracts rather than commodity replenisher formulators. Watch silver price volatility spikes as the signal indicating margin compression inflection across European supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Halide Precipitation | Captive control over grain size calibration secures holography studio premium contracts. |
| EU MDR Certification Fast-Track Program | Accelerated clinical evidence submission captures German diagnostic center procurement windows. |
| Fluorine-Free Anti-Halation Layer Development | REACH Annex XVII compliance opens reformulation contracts with European film manufacturers. |
| India Concentrate Format Localization | Maharashtra and Tamil Nadu packaging reduction addresses cost-sensitive hospital procurement. |
| Holography Studio Technical Partnership | Custom panchromatic emulsion collaboration secures volume authentication application demand. |
Research Methodology
Direct dialogue with emulsion manufacturing plant managers, hospital radiology procurement leads, holography studio technical directors, and photographic chemical distribution channel partners grounded qualitative assessment, cross-referenced with customs trade data, SEC 10-K filings from diversified chemical conglomerates, ECHA REACH substance registration databases, and hospital GPO contract disclosures. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Segmentation outputs across product chemistry type, application workflow architecture, end-user operational scale, and geographic regulatory cluster fed analytical framework construction over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating silver price volatility indices, digital radiography substitution rates, and EU MDR compliance timeline acceleration. Industry-specific inputs included gelatin dispersion engineering labor availability and effluent treatment capital expenditure cycles.
The model holds under stable precious metal pricing and regulatory enforcement timelines; deviation in silver volatility spikes or accelerated digital radiography substitution would shift volume trajectories. Forecasts reflect documented assumptions regarding hospital procurement unbundling velocity and holographic recording material R&D redirection. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Electronic Chemicals Market
Electronic Chemicals
Silver Paste Market