
 Primary Charge Roller Market | 2026-2036
Primary Charge Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Charge Roller Market Insights
Subscription-based maintenance contracts for electrophotographic equipment is shifting how primary charge rollers are procured and replaced. Mitsubishi Chemical Group leverages captive polymer compounding capabilities to secure raw material consistency across roller production. Sumitomo Riko anchors its position through precision rubber molding expertise developed for automotive applications. CET Group competes on aftermarket coverage breadth, sustaining margin pools in replacement roller channels across emerging Asian markets.
A primary charge roller is a cylindrical component in laser printers and copiers that applies uniform electrostatic charge to the photoconductor drum, typically constructed from conductive rubber or polymer composites with surface resistivity between 10^6 and 10^9 ohm-cm. Its core function is to prime the drum surface for latent image formation before toner transfer and fusing. OEM rollers command premium positioning due to tight tolerances and warranty bundling, while aftermarket rollers capture volume through independent service provider networks. Composite materials are displacing pure rubber formulations as manufacturers seek thinner wall sections and improved charge uniformity across extended duty cycles.
Japan's METI enforces JIS standards for office equipment energy efficiency that indirectly mandate roller durability thresholds. China's NMPA and SAMR coordinate GB standard updates for electrophotographic consumable safety, restricting certain plasticizer chemistries in roller compounds. The EU's RoHS and REACH frameworks limit heavy metal content and substance of very high concern usage in rollers sold across European member states. Stakeholders must monitor how regional material compliance timelines diverge and whether dual-certification strategies become necessary for cross-border component supply.
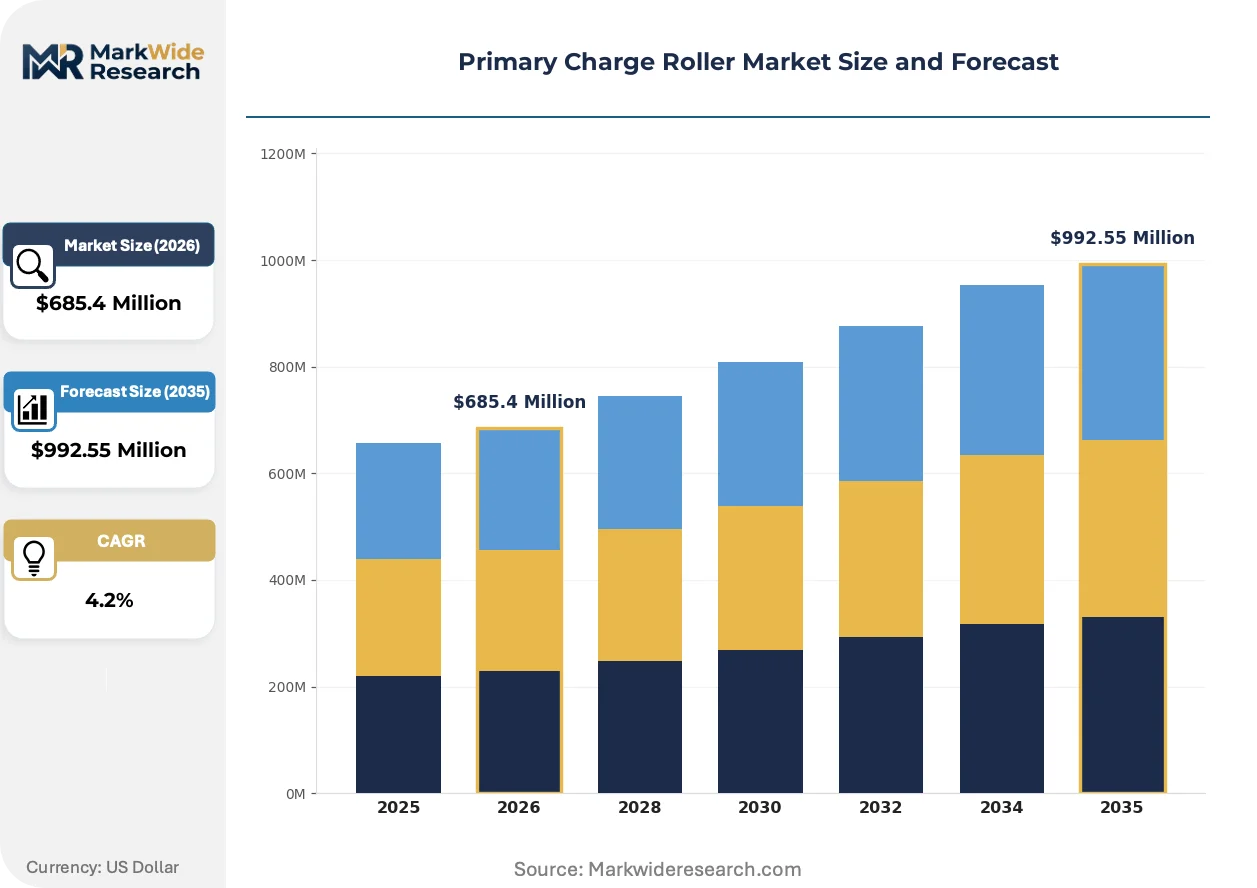
Market Dynamics
Subscription-based maintenance contracts for electrophotographic equipment are restructuring procurement flows, compressing replacement cycles and binding roller supply to multi-year service agreements rather than spot aftermarket purchases.
Growth Catalysts
- Extended equipment lifecycles:Commercial printing fleets are stretching service intervals to preserve roller performance across longer duty cycles, generating predictable replacement demand.
- REACH compliance:The EU's substance restrictions on plasticizer chemistries are accelerating formulation upgrades that improve roller durability thresholds.
- Pearl River Delta concentration:China's manufacturing cluster dominance sustains component ecosystem density that lowers logistics costs for roller assembly.
Market Restraints
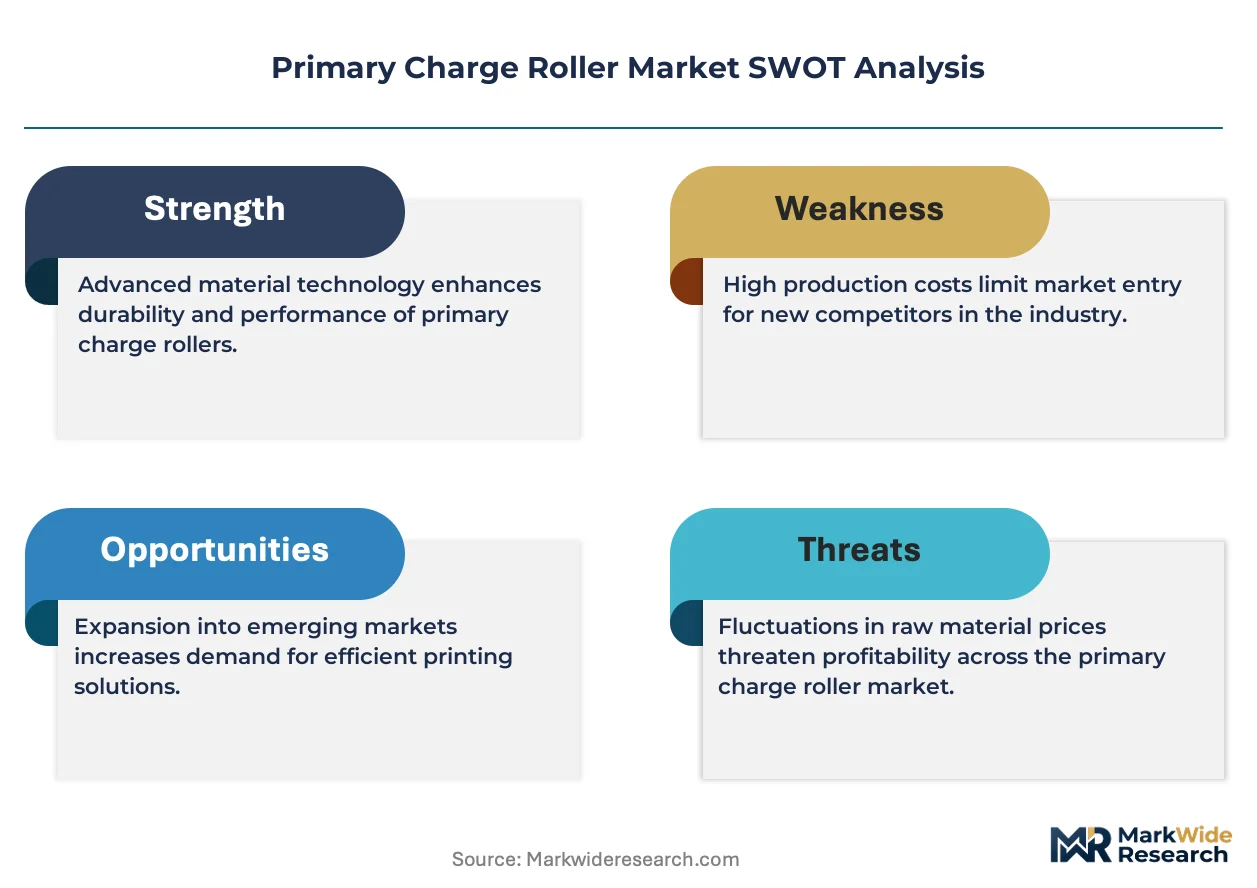
- Conductive polymer feedstock volatility:Specialized rubber compounds depend on petroleum-derived precursors exposed to energy price swings.
- East Asian supplier concentration:Precision molding capabilities concentrate in Japan's Kansai region and select Chinese provinces, creating geographic vulnerability.
- Surface resistivity tolerances:Tight specifications between 10^6 and 10^9 ohm-cm limit viable material substitutes and compound formulation flexibility.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing could attract roller assembly capacity outside incumbent East Asian bases.
- Composite material convergence:Hybrid polymer-ceramic formulations enable thinner wall sections that reduce material intensity per roller unit.
- SAMR standard alignment:China's evolving GB standards for electrophotographic consumables create certification pathways for suppliers meeting dual-market requirements.
Industry Challenges
- Precision rubber molding talent scarcity:Automotive-sector expertise transfer into electrophotographic components requires specialized tooling knowledge that commands premium compensation.
- Dual-certification timelines:Divergent NMPA and REACH compliance schedules force inventory segmentation that complicates cross-border supply planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Charge Roller Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Rollers, Aftermarket Rollers, Replacement Rollers, Compatible Rollers Material: Rubber, Plastic, Metal, Composite End User: Commercial Printing, Office Equipment, Home Use, Industrial Applications Technology: Laser Technology, Inkjet Technology, Digital Printing, Electrophotography |
| Companies Covered | Mitsubishi Chemical Group, Sumitomo Riko, CET Group, Katun, Static Control, Nippon Carbide Industries, Huaguang Photoconductor, Dinglong, Enbi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Charge Roller Market Trends and Innovations
Material science advances and procurement model restructuring are converging to redefine roller performance benchmarks and supply chain relationships across electrophotographic equipment ecosystems.
Conductive polymer-ceramic hybrid composites are electrifying roller construction by enabling sub-millimeter wall thicknesses that maintain charge uniformity across extended duty cycles. High-volume commercial print operators in Japan and Germany are specifying these formulations for fleet refresh programs. The technology is electrifying competitive differentiation around total cost-per-page metrics rather than unit replacement pricing.
China's NMPA and SAMR coordination on GB standard updates for electrophotographic consumable safety is tightening material purity requirements that restrict legacy plasticizer chemistries. Domestic roller manufacturers must reformulate compounds to maintain market access. Aftermarket suppliers serving both Chinese and European markets are consolidating certification efforts to avoid duplicate testing burdens.
Service contract bundling is compressing direct procurement autonomy for independent print service providers. OEM captive supply arrangements now dominate fleet maintenance channels, displacing spot aftermarket purchases. This concentration is most visible in China's Pearl River Delta manufacturing corridor where integrated equipment-leasing-roller packages lock in multi-year supply commitments.
Primary Charge Roller Market Segmentation
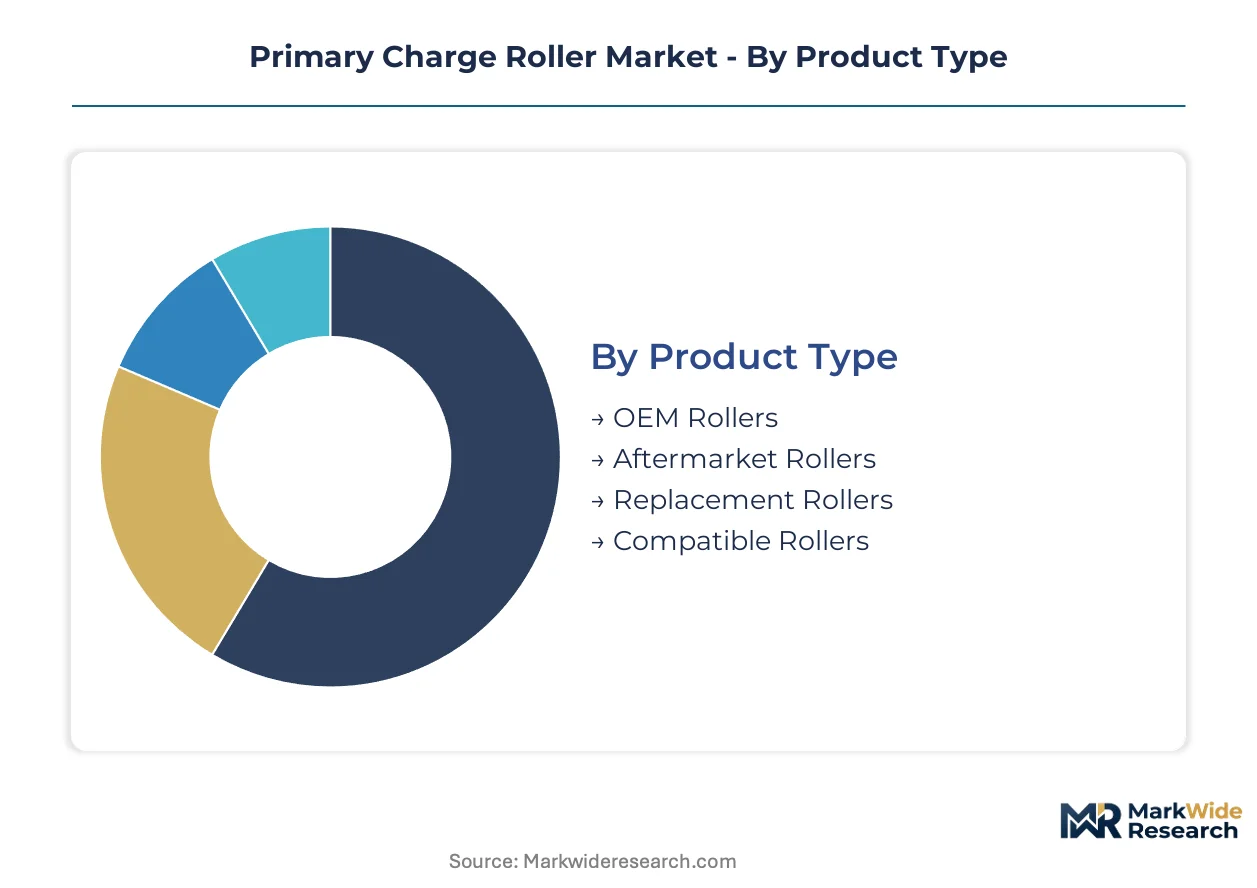
Segmentation in the primary charge roller market reveals how procurement authority, material specifications, and equipment technology intersect to determine supplier positioning. Buyers navigate trade-offs between OEM warranty coverage and aftermarket cost efficiency, while material choices constrain formulation flexibility under tightening regulatory frameworks.
Product Type:
Procurement authority concentrates with fleet operators seeking predictable maintenance economics over unit cost minimization.
- OEM Rollers:Manufactured to equipment-specific tolerances with captive supply arrangements bundling warranty protection and performance guarantees. Fleet operators in Japan's Kansai region specify these for high-duty commercial installations where charge uniformity failures trigger service penalties.
- Aftermarket Rollers:Produced by independent manufacturers for replacement channels, competing on coverage breadth across legacy equipment models. CET Group sustains margin pools in emerging Asian markets through distribution density rather than technical differentiation.
- Replacement Rollers:Direct substitutes for worn components in out-of-warranty equipment, capturing volume from independent service provider networks.
- Compatible Rollers:Third-party alternatives engineered to function across multiple OEM platforms, subject to varying patent enforcement intensity by geography.
OEM rollers lead on scale; compatible rollers lead on momentum as patent cliffs expand addressable equipment populations.
Material:
Formulation decisions hinge on surface resistivity compliance and wall thickness requirements under divergent regional chemical restrictions.
- Rubber:Traditional conductive compounds with established molding expertise but declining share as wall thickness requirements tighten. Sumitomo Riko leverages automotive-sector precision rubber capabilities to maintain positioning in premium segments.
- Composite:Polymer-ceramic hybrids enabling sub-millimeter wall sections that reduce material intensity while preserving charge uniformity across extended duty cycles. Mitsubishi Chemical Group exploits captive polymer compounding to secure formulation consistency.
- Plastic:Thermoplastic alternatives offering dimensional stability but constrained by conductive filler loading limits that affect charge distribution.
- Metal:Core structural substrates providing dimensional rigidity, typically overmolded with conductive layers rather than functioning as primary charge application surfaces.
Composite formulations are climbing the fastest as equipment refresh programs specify thinner-walled durability; rubber maintains installed base replacement volume.
End User:
Application environment determines duty cycle intensity and tolerance for charge uniformity variance.
- Commercial Printing:High-volume operations with extended equipment lifecycles generating predictable replacement demand through service contract structures.
- Office Equipment:Mid-duty installations where total cost-per-page metrics dominate procurement evaluation.
- Home Use:Low-duty consumers prioritizing initial equipment cost over consumable longevity, with minimal roller replacement incidence.
- Industrial Applications:Specialized environments with temperature or contamination exposures requiring modified roller formulations.
Commercial printing leads on scale; industrial applications lead on specification premium capture.
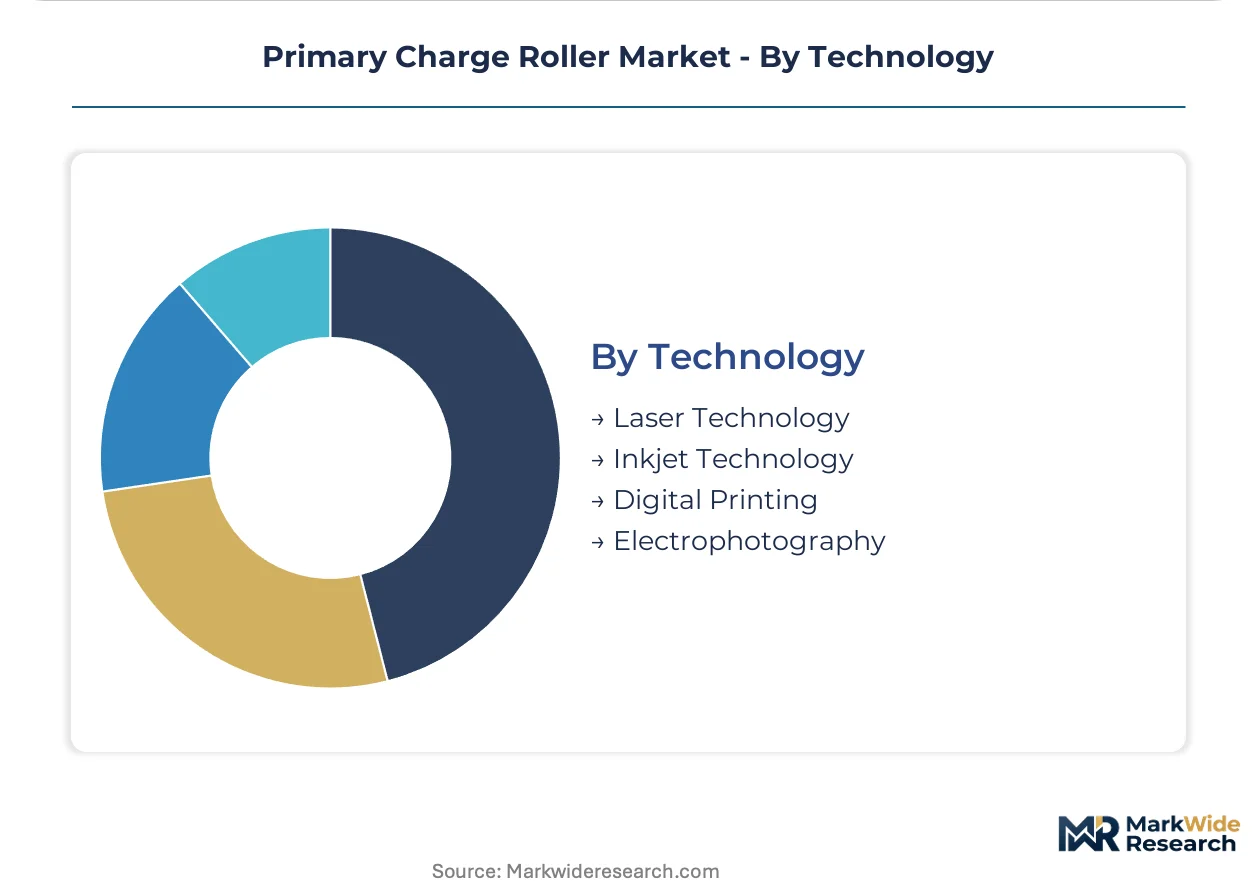
Technology:
Imaging modality dictates roller functional requirements and replacement frequency.
- Electrophotography:Core laser printing and copier technology where primary charge rollers serve as essential drum priming components with defined surface resistivity tolerances between 10^6 and 10^9 ohm-cm.
- Laser Technology:Monochrome and color systems with established roller specifications and mature aftermarket supply chains.
- Digital Printing:Emerging production platforms with evolving consumable interfaces and less standardized roller geometries.
- Inkjet Technology:Non-electrophotographic imaging where primary charge rollers serve no functional role, excluding this segment from addressable demand.
Electrophotography leads on scale; digital printing leads on formulation evolution requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting primary charge roller assembly capacity toward jurisdictions with streamlined chemical compliance timelines, as dual-certification burdens in Europe and China force suppliers to optimize production geography.
China
Pearl River Delta manufacturing clusters dominate component ecosystem density, with Shenzhen and Dongguan hosting integrated roller-molding facilities serving electrophotographic OEMs. SAMR and NMPA coordination on GB standard updates restricts legacy plasticizer chemistries, compelling domestic compound reformulation. Guangdong province's electronics manufacturing base sustains multi-year service contract bundling that locks in captive supply arrangements.
Japan
Kansai region precision molding capabilities anchor high-duty commercial printing supply, with Osaka-based facilities supplying fleet maintenance channels. METI-enforced JIS standards for office equipment energy efficiency indirectly mandate roller durability thresholds exceeding 500,000 impressions. Automotive-sector expertise transfer from nearby Toyota and Honda supplier networks strengthens rubber compounding talent pools.
Germany
REACH substance restrictions on plasticizer chemistries accelerate formulation upgrades among Düsseldorf and Munich-based industrial print operators. ECHA compliance timelines drive R&D investment in hybrid polymer-ceramic composites. Bavaria's precision engineering corridor hosts testing laboratories certifying rollers for cross-border EU distribution.
United States
Commercial printing fleets in Illinois and Ohio extend equipment lifecycles through subscription-based maintenance contracts that compress replacement procurement cycles. EPA oversight of petroleum-derived conductive polymer feedstocks affects compound cost structures. Texas petrochemical corridors supply specialized rubber precursors to domestic roller fabricators.
India
PLI scheme incentives for electronics manufacturing attract roller assembly capacity to Karnataka and Tamil Nadu, challenging East Asian supplier concentration. BIS standards for electrophotographic consumables remain under development, creating temporary certification flexibility. Chennai and Bengaluru industrial zones host emerging distribution networks for replacement roller channels.
Primary Charge Roller Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-captive supply arrangements dominating fleet maintenance channels while independent fabricators capture spot aftermarket purchases. Market structure tilts toward consolidated precision molding capabilities in Japan and China, supplemented by emerging Indian assembly capacity. Three archetypes define competitive positioning: chemical conglomerates with captive polymer compounding, precision rubber specialists with automotive heritage, and aftermarket distributors with geographic coverage density. Capacity expansion and formulation licensing represent the dominant competitive moves as suppliers navigate divergent regulatory timelines.
Among chemical-sector conglomerates, Mitsubishi Chemical Group exemplifies backward integration into raw material consistency, while Sumitomo Riko occupies a position translating automotive-sector precision molding expertise into electrophotographic applications. CET Group anchors the aftermarket coverage archetype, sustaining margin pools through distribution density across emerging Asian markets rather than technical differentiation.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Sumitomo Riko |
| CET Group |
| Katun |
| Static Control |
| Nippon Carbide Industries |
| Huaguang Photoconductor |
| Dinglong |
| Enbi Group |
| Others |
Pricing and Supply Chain Analysis
OEM-aftermarket bifurcation separates captive supply arrangements from independent replacement channels, compressing margins in the latter while locking premium pricing into multi-year service contracts. This divergence maps directly onto supply chain geography, with precision molding capabilities clustering in Japan's Kansai region and China's Pearl River Delta while aftermarket distribution networks fragment across emerging Asian markets.
Pricing Analysis
Distributor markups in replacement channels absorb margin compression as CET Group and independent fabricators compete on coverage breadth rather than technical differentiation. Three-tier pricing structure across premium OEM, certified compatible, and economy aftermarket levels reflects certification grade divergence and warranty bundling intensity. Pricing pressure stems from conductive polymer feedstock volatility tied to petroleum-derived precursor costs. Independent service providers exhibit highest price sensitivity, while fleet operators under subscription contracts prioritize total cost-per-page predictability over unit minimization.
Supply Chain Analysis
Dual-sourcing requirements from commercial printing fleets mandate multi-supplier qualification for critical charge uniformity specifications, preventing single-source dependency despite geographic concentration. Raw material supply concentrates in China, Japan, and South Korea, with conductive rubber compounding anchored in Osaka and Shenzhen processing corridors. Specialized polymer-ceramic hybrid formulations draw from captive petrochemical feedstocks and precision ceramic filler suppliers. Tariff exposure on cross-border component flows between China and Western markets threatens inventory segmentation costs. Distribution runs through OEM captive channels for fleet maintenance and independent distributor networks for spot aftermarket purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where extended equipment lifecycles shift procurement authority toward premium durability specifications and predictable replacement economics.
For Market Incumbents: Anchor positioning through backward integration into conductive polymer compounding to secure formulation consistency against feedstock volatility, while expanding precision molding capacity in India's PLI-subsidized electronics corridors to diversify geographic exposure beyond Kansai and Pearl River Delta concentration. Certification investment in dual NMPA-REACH compliance streamlines cross-border supply planning threatened by diverging regulatory timelines. For New Entrants and Emerging Players: Launch via direct-to-fleet service contract partnerships targeting India's emerging commercial printing infrastructure, where BIS standard development creates temporary certification flexibility and PLI incentives attract assembly capacity outside incumbent East Asian bases. White-space exists in composite roller formulations for digital printing platforms with evolving consumable interfaces and less standardized geometries. For Investors and Strategic Acquirers: Consolidation pressure builds where precision rubber molding talent scarcity intersects with automotive-sector expertise transfer costs into electrophotographic applications. Long-term viability favors suppliers with captive material science capabilities and multi-regional certification infrastructure. Acquisition targets include mid-cap composite formulation specialists and India-based assembly operators with established SAMR compliance pathways. Watch for inflection in China's GB standard enforcement intensity as a signal of domestic supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Mitsubishi Chemical Group's captive raw material control secures formulation consistency against petroleum feedstock volatility. |
| Composite Material R&D Investment | Hybrid polymer-ceramic development enables sub-millimeter wall sections that reduce material intensity per roller unit. |
| India PLI Assembly Expansion | Karnataka and Tamil Nadu production capacity challenges East Asian supplier concentration with government incentive backing. |
| Dual Certification Consolidation | Unified NMPA-REACH testing protocols eliminate duplicate compliance burdens for cross-border component supply. |
| Service Contract Bundling | Multi-year equipment-leasing-roller packages displace spot aftermarket purchases in China's Pearl River Delta corridor. |
Research Methodology
Coverage spans East Asia, Europe, North America, and South Asia, with primary inputs from each region combining executive interviews with electrophotographic OEM procurement directors, commercial fleet maintenance managers, precision rubber molding plant engineers, and aftermarket distribution channel heads. Secondary validation draws from customs trade data for conductive polymer feedstocks, METI energy efficiency filings, NMPA consumable safety registrations, and SEC disclosures from chemical sector conglomerates. Bottom-up unit shipment modeling triangulates against top-down equipment installed base estimates.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, material formulation, end-use duty cycle intensity, and imaging technology modality. CAGRs derive from segment-level replacement frequency assumptions tied to equipment lifecycle extension trends and service contract penetration rates. Industry-specific forecast inputs include surface resistivity specification evolution and regional regulatory compliance timeline divergence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH plasticizer restriction acceleration or NMPA enforcement intensity surprises. Deviation in conductive polymer feedstock cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Braking Resistors Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Data Bus Market
Electronic Components
GPIO Expanders Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Resonators Market
Electronic Components
Loudspeaker Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Fixed Capacitor Market
Electronic Components
PTC Resettable Device Market