
 Global Hypoxia Treatment Market | 2026-2036
Global Hypoxia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hypoxia Treatment Market Foresight
Respiratory therapist shortages across intensive care units is redrawing competitive dynamics in hypoxia care delivery. ResMed leverages its cloud-connected ventilation platforms to sustain remote patient monitoring capabilities. GE Healthcare anchors hospital procurement decisions through integrated critical care ecosystems that span imaging and respiratory support. Masimo competes via non-invasive monitoring technologies that extend its footprint beyond traditional pulse oximetry into continuous hemoglobin assessment.
Hypoxia treatment encompasses therapeutic interventions that restore adequate oxygen delivery to tissues, including mechanical ventilation, supplemental oxygen systems, pharmacological agents such as inhaled nitric oxide, and hyperbaric oxygen therapy administered at pressures typically exceeding 1.4 atmospheres absolute. The primary purpose spans acute resuscitation in emergency settings, chronic management of respiratory insufficiency, and reversal of ischemic tissue damage. Oxygen concentrators dominate home-based and long-term care settings where portability and energy efficiency determine purchasing criteria. Hyperbaric chambers command premium pricing in wound care centers and diving medicine facilities. Nitric oxide therapy occupies a specialized niche in neonatal and pulmonary hypertension applications where precise dosing protocols justify higher reimbursement rates.
FDA 510(k) pathways and EMA's Medical Device Regulation govern device approvals, while WHO oxygen access initiatives shape procurement priorities in low-resource settings. Japan's PMDA enforces stringent clinical evidence requirements that filter market entrants and elevate quality benchmarks. Stakeholders must monitor evolving reimbursement frameworks for home oxygen therapy and anticipate how Medicare's competitive bidding adjustments will reshape distribution economics.
Market Dynamics
Mechanical ventilation manufacturers face a structural squeeze as cloud-connected platforms commoditize hardware margins and shift value toward software subscriptions and remote monitoring services.
Growth Catalysts
- Emergency Medical Services Expansion:Ambulance fleet modernization across the United States, Germany, and Japan is embedding portable oxygen concentrators and advanced airway management systems into pre-hospital protocols.
- WHO Oxygen Access Initiatives:Procurement frameworks for low-resource settings are redirecting development capital toward ruggedized, solar-compatible concentrators and pressure swing adsorption systems.
- Japan PMDA Stringency:Elevated clinical evidence requirements for neonatal nitric oxide delivery systems are filtering out marginal competitors and consolidating quality-tier supply.
Market Restraints
- Helium Supply Concentration:Geographic clustering of helium extraction in the United States, Qatar, and Algeria creates input volatility for hyperbaric chamber operators and MRI-dependent oxygen monitoring.
- Reimbursement Compression:Medicare competitive bidding adjustments for home oxygen therapy are compressing distributor margins and accelerating consolidation among durable medical equipment suppliers.
- Technical Limitation in Portable Systems:Energy density constraints in battery technology cap ambulatory oxygen concentrator runtime, restricting patient mobility and device utility.
Strategic Opportunities
- Underpenetrated Home Care in India:Chronic obstructive pulmonary disease prevalence and expanding health insurance coverage are opening addressable demand for subscription-based oxygen concentrator leasing.
- Technology Convergence:Integration of pulse oximetry with continuous hemoglobin monitoring and AI-driven alarm algorithms is creating premium-tier product categories in intensive care settings.
- EMA MDR Streamlining:Consolidated device approval pathways for inhaled nitric oxide systems are reducing time-to-market for pediatric pulmonary hypertension indications.
Industry Challenges
- Respiratory Therapist Shortages:Intensive care unit staffing gaps in the United States and Germany are limiting optimal utilization of advanced ventilation modes and delaying weaning protocols.
- Capex Intensity in Hyperbaric Infrastructure:Multiplace chamber installations require specialized construction, fire suppression systems, and clinical staffing that strain hospital capital allocation committees.
- Integration Complexity with Legacy HIS:Cloud-connected ventilation platforms face interoperability friction with entrenched hospital information systems, slowing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hypoxia Treatment Market |
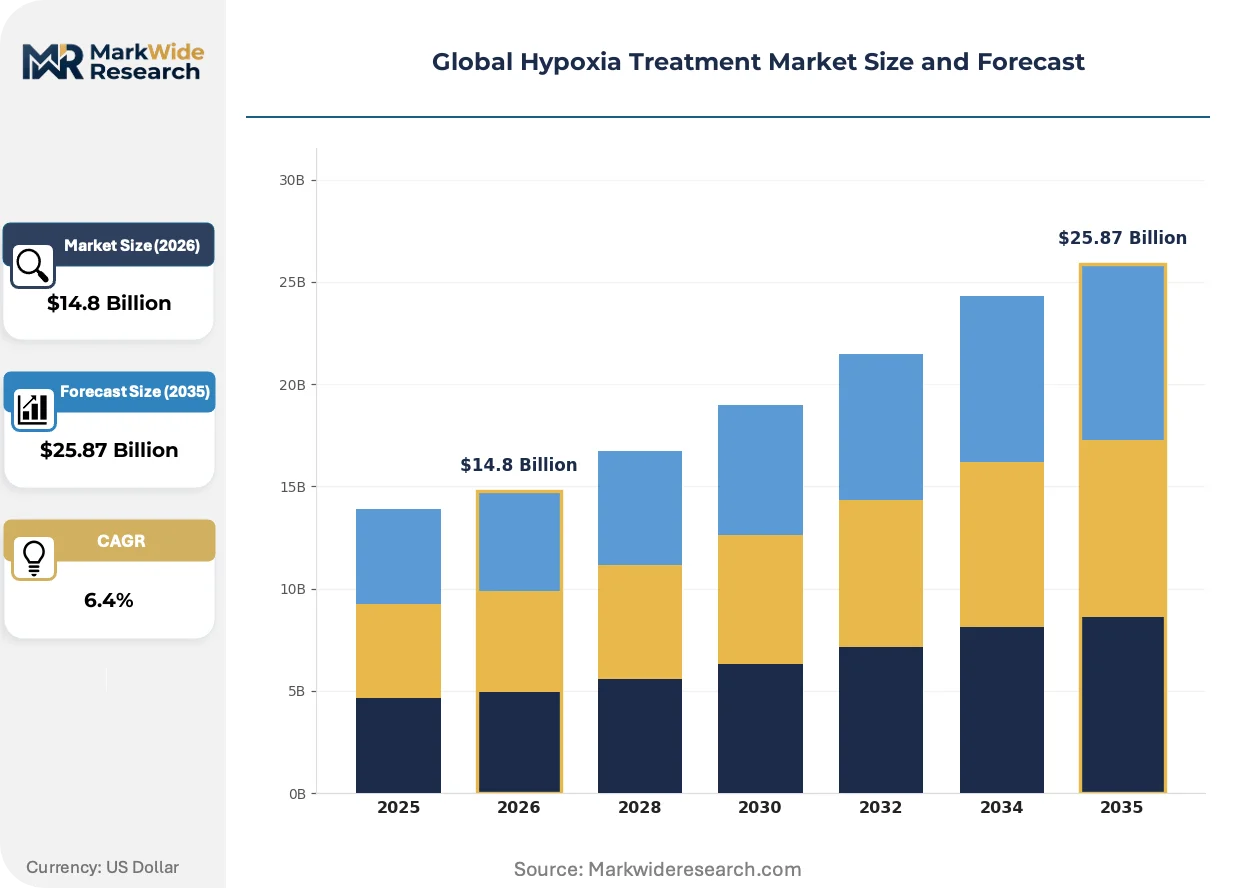
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Concentrators, Hyperbaric Chambers, Nitric Oxide Therapy, Portable Oxygen Cylinders, Continuous Positive Airway Pressure Application: Chronic Obstructive Pulmonary Disease, Pneumonia, High Altitude Sickness, Anemia, Heart Failure End User: Hospitals, Emergency Medical Services, Respiratory Therapy Centers, Rehabilitation Clinics, Long-term Care Facilities Delivery Mode: Inhalation Devices, Intravenous Injection, Injectable Gas, Oral Supplements, Injection Pumps |
| Companies Covered | Resmed, GE Healthcare, Merck KGaA, Masimo, Medtronic, Koninklijke Philips NV, Hamilton Company, Smiths Medical, Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hypoxia Treatment Market Shifts & Advancements
Software-defined respiratory care is redistributing competitive advantage from device manufacturers to platform operators capable of integrating real-time biometric streams with predictive analytics.
Membrane oxygenation technology is decomposing traditional boundaries between extracorporeal life support and conventional mechanical ventilation. Academic medical centers in the United States and Germany are adopting compact extracorporeal membrane oxygenation circuits for bridge-to-recovery protocols in acute respiratory distress syndrome. This convergence is compressing the addressable market for high-frequency oscillatory ventilators and forcing incumbents to reposition around hybrid platform architectures.
EMA's Medical Device Regulation is tightening post-market surveillance requirements for Class III respiratory devices. Manufacturers must now maintain systematic clinical follow-up registries and submit periodic safety update reports. Neonatal nitric oxide delivery systems face the steepest compliance burden, with notified bodies demanding extended pediatric outcome data that extends certification timelines by eighteen to thirty-six months.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Third-party clinical engineering firms in Japan and the United States are capturing preventive maintenance revenue through independent service organization certifications. This disintermediation pressures original equipment manufacturers to defend recurring revenue through exclusive consumable lock-in and software subscription tiers rather than bundled service agreements.
Global Hypoxia Treatment Market Segmentation
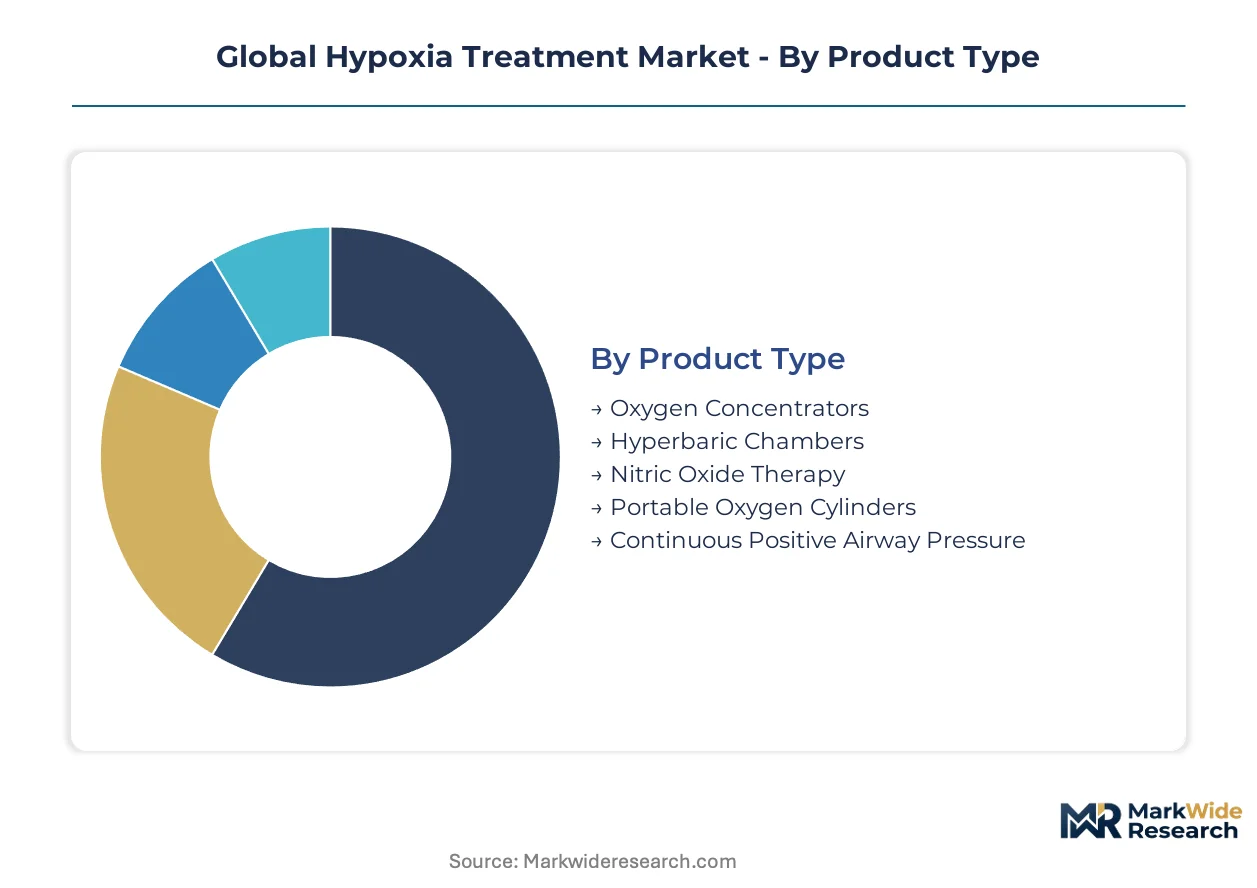
Hypoxia treatment devices fragment across four intersecting dimensions that determine reimbursement codes, procurement cycles, and clinical workflow integration. Product type and application together dictate capital intensity and service attach rates, while end-user concentration shapes geographic sales coverage models.
Product Type:
Oxygen concentrators capture the deepest margin pools due to recurring consumable revenue and home-care subscription economics, whereas hyperbaric chambers concentrate value in specialized construction and clinical staffing services.
- Oxygen Concentrators:Pressure swing adsorption units separate nitrogen from ambient air to deliver concentrated oxygen at flow rates from 1-10 liters per minute. Demand concentrates in United States home-care settings where Medicare competitive bidding has compressed hardware margins but preserved recurring revenue from replacement filters and cannulas.
- Hyperbaric Chambers:Monoplace and multiplace systems pressurize treatment environments to 1.4-3.0 atmospheres absolute for wound healing and diving medicine. Japan's PMDA enforces extended clinical evidence requirements for fire suppression certification, filtering marginal competitors and elevating installed-base service pricing.
- Nitric Oxide Therapy:Precision delivery systems for neonatal pulmonary hypertension carry premium reimbursement in German intensive care units.
- Portable Oxygen Cylinders:Lightweight aluminum and composite vessels dominate ambulance fleet modernization across emergency medical services in the United States and Germany.
- Continuous Positive Airway Pressure:Sleep apnea therapy devices with cloud connectivity command software subscription tiers from Japanese respiratory therapy centers.
The dominant share belongs to oxygen concentrators, while hyperbaric chambers are closing the gap fastest through wound care center expansion.
Application:
Volume concentration tracks chronic disease prevalence and acute respiratory event frequency, with reimbursement intensity varying sharply between episodic hospitalization and longitudinal management.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation drives the largest installed base of home oxygen therapy. German statutory health insurance funds capitate long-term oxygen provision, bundling device leasing with remote monitoring services.
- Pneumonia:Acute infectious lung inflammation generates emergency department oxygen consumption spikes. United States hospital networks pre-position surge capacity agreements with durable medical equipment distributors ahead of respiratory virus seasons.
- High Altitude Sickness:Hypobaric hypoxia management supports expedition medicine and military operations.
- Anemia:Reduced oxygen-carrying capacity triggers supplemental oxygen in perioperative settings.
- Heart Failure:Cardiogenic pulmonary edema creates intermittent hypoxia treated with non-invasive ventilation.
Chronic obstructive pulmonary disease holds the dominant share, though pneumonia applications are expanding most quickly through pre-hospital protocol embedding.
End User:
Procurement sophistication and capital availability diverge sharply between integrated health systems and fragmented independent operators.
- Hospitals:Integrated delivery networks in the United States negotiate enterprise contracts spanning imaging, ventilation, and monitoring platforms. GE Healthcare anchors these procurement decisions through critical care ecosystem bundling.
- Emergency Medical Services:Municipal and private ambulance operators prioritize ruggedized portability and rapid deployment protocols. Fleet modernization in Germany embeds advanced airway management alongside portable oxygen concentrators.
- Respiratory Therapy Centers:Outpatient facilities concentrate weaning protocols and long-term ventilator management.
- Rehabilitation Clinics:Post-acute settings bridge hospital discharge to home oxygen independence.
- Long-term Care Facilities:Nursing homes face staffing constraints that limit adoption of advanced ventilation modes.
Hospitals retain the dominant share, while emergency medical services are gaining share fastest through ambulance fleet modernization mandates.
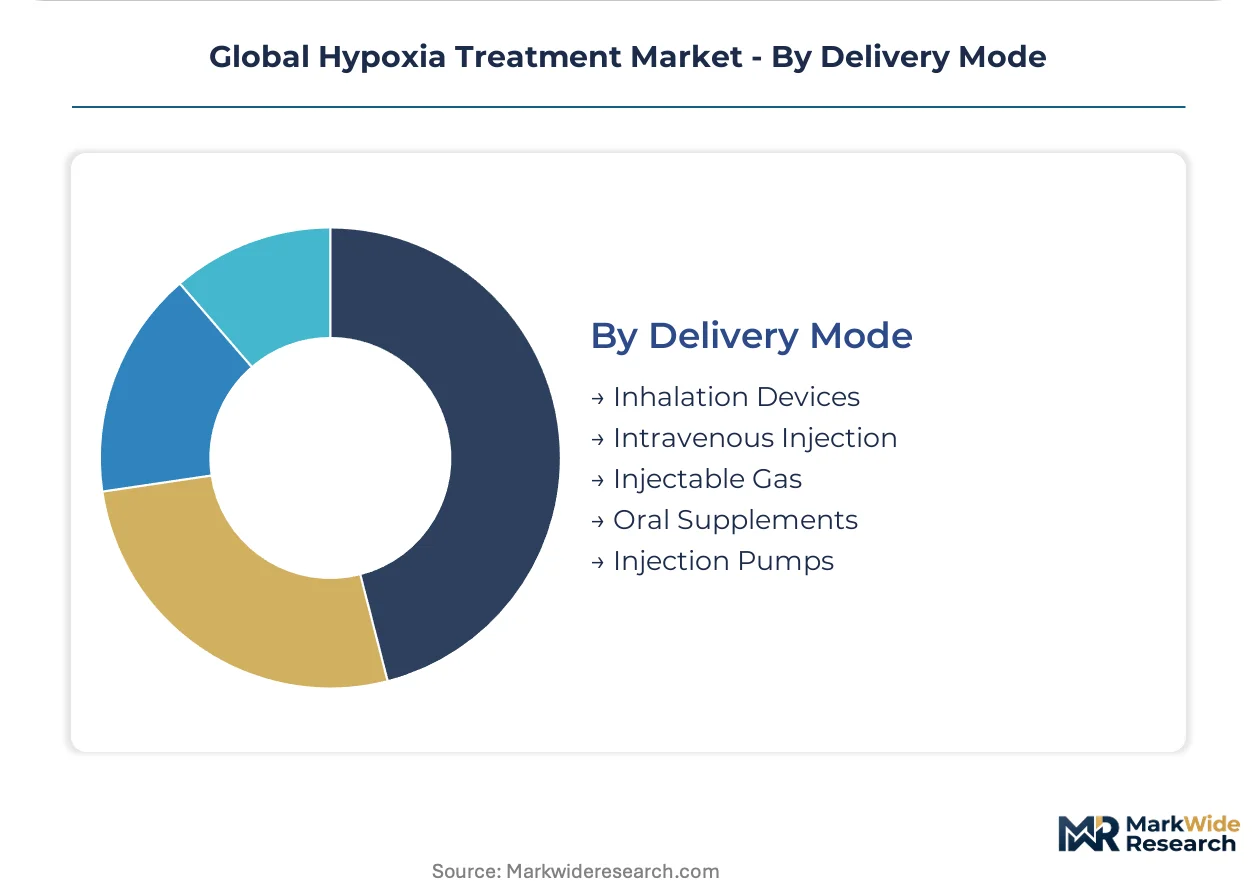
Delivery Mode:
Regulatory classification and clinical evidence requirements fragment margin structures across invasive and non-invasive administration pathways.
- Inhalation Devices:Nasal cannulas, masks, and high-flow systems constitute the standard non-invasive route. FDA 510(k) pathways govern device approvals for these Class II systems in United States markets.
- Intravenous Injection:Perfluorocarbon emulsions and hemoglobin-based oxygen carriers remain developmental with limited commercial penetration.
- Injectable Gas:Carbon dioxide-oxygen mixtures support diagnostic contrast in angiography suites.
- Oral Supplements:Oxygenated water and chlorite solutions occupy wellness market niches outside regulated medical channels.
- Injection Pumps:Targeted drug delivery systems integrate hypoxia-modulating agents in oncology protocols.
Inhalation devices command the dominant share, with intravenous injection positioned for steepest expansion trajectory if clinical trials demonstrate efficacy in trauma resuscitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pathways anchor the United States as the dominant geography, while EMA frameworks and Japan's PMDA elevate clinical evidence standards across developed markets. WHO oxygen access initiatives redirect capital toward low-resource procurement frameworks.
United States
Ambulance fleet modernization and Medicare competitive bidding reshape pre-hospital oxygen delivery and home-care economics. FDA 510(k) pathways streamline approvals for Class II inhalation devices while tightening post-market surveillance. The Southeast corridor concentrates durable medical equipment distribution hubs serving respiratory therapy networks.
Germany
Statutory health insurance capitation models bundle long-term oxygen provision with remote monitoring services. EMA's Medical Device Regulation imposes systematic clinical follow-up registries for Class III respiratory devices. The Rhine-Ruhr metropolitan cluster anchors critical care ecosystem procurement for integrated delivery networks.
Japan
PMDA stringency filters marginal competitors through extended pediatric outcome data requirements for neonatal nitric oxide systems. METI industrial policy directs development capital toward compact membrane oxygenation platforms. The Kanto region surrounding Tokyo concentrates academic medical center adoption of bridge-to-recovery protocols.
India
Expanding health insurance coverage and chronic obstructive pulmonary disease prevalence open subscription-based oxygen concentrator leasing models. CDSCO device registration pathways align with WHO procurement frameworks for ruggedized, solar-compatible systems. Maharashtra and Gujarat host manufacturing clusters for pressure swing adsorption units targeting low-resource settings.
United Kingdom
NHS England's integrated care systems negotiate enterprise contracts spanning hospital and community respiratory services. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards while streamlining pediatric device pathways. The Greater Manchester and West Midlands clusters concentrate weaning protocol centers bridging acute and post-acute care.
Global Hypoxia Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-connected platform operators capturing software subscription value while hardware margins commoditize. The structure favors ecosystem bundlers over standalone device manufacturers. Strategic archetypes include critical care ecosystem integrators, non-invasive monitoring specialists, and precision delivery system developers. Dominant competitive moves encompass exclusive consumable lock-in and independent service organization certifications that disintermediate original equipment maintenance revenue.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips NV occupy positions as ecosystem anchors, while Resmed exemplifies the platform-operator archetype through cloud-connected ventilation services. Specialists in continuous hemoglobin monitoring and pulse oximetry convergence include Masimo, which sits within the premium-tier non-invasive monitoring segment. Precision delivery for neonatal pulmonary hypertension applications is represented by Merck KGaA's positioning in inhaled nitric oxide therapy systems.
| Leading Market Players |
|---|
| Resmed |
| GE Healthcare |
| Merck KGaA |
| Masimo |
| Medtronic |
| Koninklijke Philips NV |
| Hamilton Company |
| Smiths Medical |
| Fisher & Paykel Healthcare Limited |
| Others |
Supply & Pricing Matrix
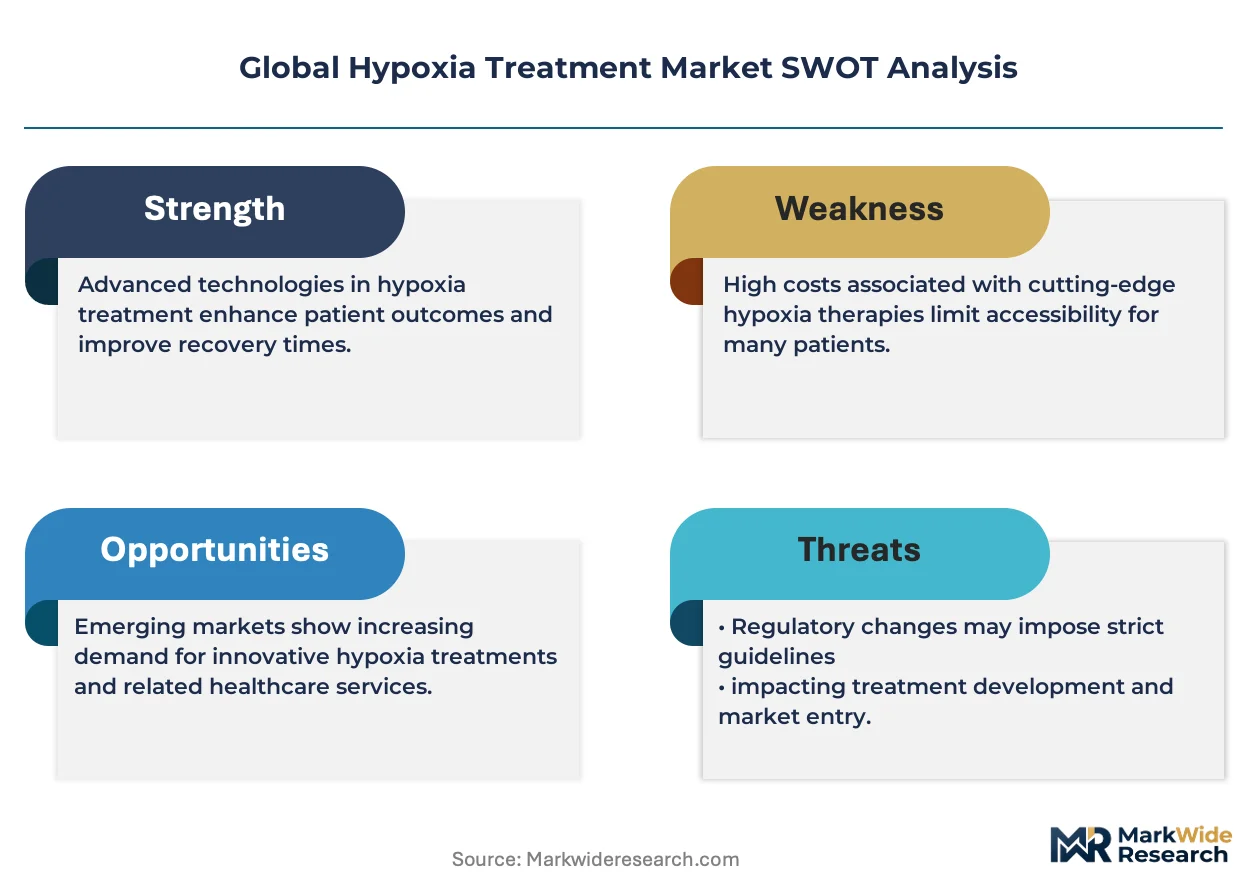
FDA 510(k) and EMA MDR certification tiers gate both supplier qualification and price differentiation simultaneously, with Class III respiratory devices commanding premium positioning against Class II alternatives while filtering marginal competitors from reimbursement-eligible supply pools.
Pricing Analysis
United States home oxygen therapy prices diverge sharply from German statutory insurance capitation rates and Japanese PMDA-certified premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected platforms with software subscriptions from basic pressure swing adsorption units and refurbished legacy hardware. Cost compression in durable medical equipment distribution is intensifying because Medicare competitive bidding compresses hardware margins while preserving recurring filter and cannula revenue. Emergency medical services buyers exhibit highest price sensitivity due to municipal procurement constraints, whereas academic medical centers in Japan and Germany demonstrate lowest sensitivity for neonatal nitric oxide systems with extended pediatric outcome data requirements.
Supply Chain Analysis
Helium extraction concentration in the United States, Qatar, and Algeria creates a chokepoint that constrains hyperbaric chamber operators and MRI-dependent oxygen monitoring systems. Pressure swing adsorption units draw from zeolite molecular sieve supplies centered in China and domestic United States production, while precision gas delivery components rest on German and Japanese pneumatic valve manufacturing. Single-source vulnerability in specialty gas supply exposes wound care centers and diving medicine facilities to input volatility. Distribution runs through durable medical equipment distributors in the United States, statutory health insurance funds in Germany, and regional medical device trading houses in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement consolidation in the United States and enterprise contract bundling across German hospital alliances, fragmenting standalone device manufacturers' pricing leverage.
For Market Incumbents: Secure exclusive consumable lock-in through proprietary filter and cannula designs that tether home oxygen concentrator users to recurring revenue streams. Anchor hospital procurement decisions by integrating cloud-connected ventilation platforms with entrenched hospital information systems, reducing interoperability friction that slows competitive displacement. Invest in independent service organization certifications to recapture preventive maintenance revenue from third-party clinical engineering firms in Japan and the United States. For New Entrants and Emerging Players: Lead with subscription-based oxygen concentrator leasing models targeting underpenetrated home care in India, where chronic obstructive pulmonary disease prevalence and expanding health insurance coverage create addressable demand without entrenched incumbent relationships. Position ruggedized, solar-compatible pressure swing adsorption units for WHO oxygen access initiative procurement frameworks in low-resource settings. Pursue direct partnerships with state-level health insurance schemes rather than competing for hospital capital equipment committees. For Investors and Strategic Acquirers: EMA MDR streamlining for inhaled nitric oxide systems reshapes the acquisition landscape by reducing certification timelines and expanding addressable pediatric pulmonary hypertension markets. Target platform operators with cloud-connected ventilation services and established software subscription tiers, as hardware margins commoditize and value migrates toward predictive analytics integration. Monitor Japan PMDA enforcement patterns as the inflection signal for quality-tier supply consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Streamlined Class II inhalation device approvals accelerate United States market entry timelines. |
| Hospital System Partnership | Enterprise contracts with integrated delivery networks anchor critical care ecosystem bundling decisions. |
| Software Companion Development | AI-driven alarm algorithms and remote monitoring tiers capture subscription value beyond hardware sales. |
| CE Marking Pathway | EMA MDR compliance for Class III respiratory devices opens German and United Kingdom reimbursement channels. |
| Reimbursement Strategy | Medicare competitive bidding alignment preserves distributor margins through recurring consumable revenue streams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across intensive care clinicians, hospital purchasing committee members, biomedical engineers, durable medical equipment distributors, and GPO contracts managers. Primary interview insights were validated against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare competitive bidding records, and hospital procurement contract registries. Bottom-up installed base modeling and top-down reimbursement flow analysis were triangulated to cross-validate market sizing.
Across the analysis window, forecasts segment by product type, application, end user, and delivery mode, with additional disaggregation by regulatory certification tier and remote monitoring capability. CAGRs were derived from historical reimbursement trajectory analysis and projected adoption curves for cloud-connected platforms. Key inputs include respiratory therapist staffing ratios by United States census region, statutory health insurance capitation rates in Germany, and PMDA approval timelines for neonatal nitric oxide systems.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability, helium supply continuity, or battery energy density improvements would require recalibration. Forecasts reflect documented assumptions regarding cloud platform adoption rates and integrated delivery network consolidation trajectories. Practitioners should keep alternative scenarios live as WHO oxygen access initiative procurement volumes and EMA MDR enforcement stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Oxygen Therapy Equipment Market