
 Global SMB Telecom Voice and Data Services Market | 2026-2036
Global SMB Telecom Voice and Data Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global SMB Telecom Voice and Data Services Market Foresight
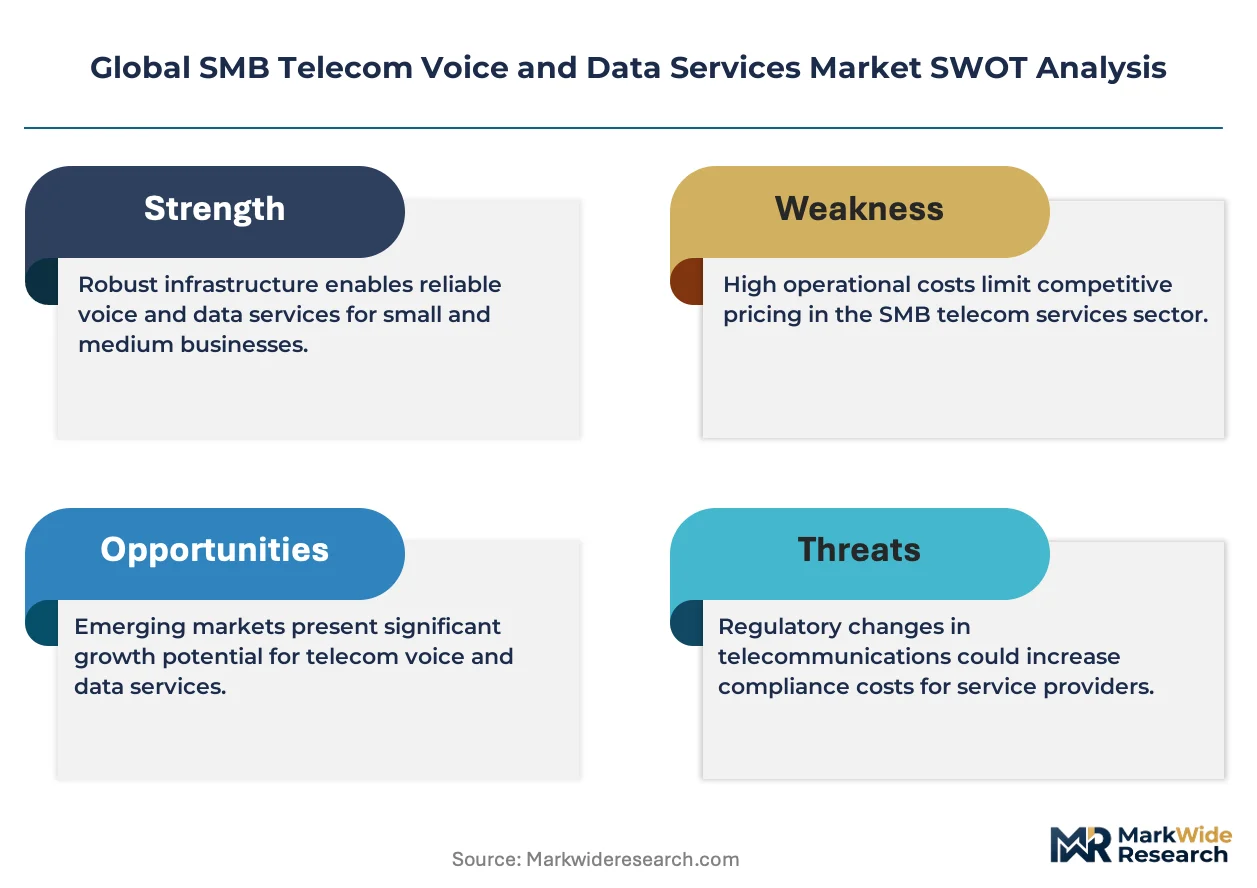
The capital-intensity divergence between fiber-owning incumbents and cloud-native challengers is redrawing competitive boundaries in SMB telecom. Deutsche Telekom leverages its European fiber footprint to anchor managed PBX and SIP trunking bundles for mid-sized manufacturers. Verizon sustains technology leadership in unified communications through in-house SD-WAN integration, while Orange competes across Africa and the Middle East with mobile-first voice and data packages tailored to small enterprises.
SMB telecom voice and data services encompass dedicated connectivity, hosted telephony, and managed network solutions delivered to businesses with fewer than 250 employees, typically operating over IP-based infrastructure with service level agreements guaranteeing uptime thresholds. These services enable commercial operations ranging from customer support centers to remote workforce collaboration platforms. Cloud-based deployment models now dominate new subscriber acquisitions as small enterprises abandon legacy on-premises PBX systems, while unified communications represents the fastest-expanding service type due to its integration of voice, video, and messaging into single-vendor contracts. SIP trunking remains a mature, high-margin segment for carriers with existing voice network infrastructure.
FCC net-neutrality frameworks and GDPR data-localization requirements in Europe shape how carriers architect cross-border data routing and customer record storage for SMB clients. India's TRAI interconnect regulations and the EU's CSRD sustainability disclosure mandates further constrain pricing flexibility and infrastructure investment timelines. Stakeholders must monitor spectrum auction outcomes and national broadband subsidy programs to anticipate which carrier investments will reshape SMB service availability.
Market Dynamics
Cloud-native voice platforms are compressing deployment timelines from months to days, forcing traditional carriers to re-architect their service delivery stacks around API-first infrastructure or surrender mid-market accounts to software-defined challengers.
Growth Catalysts
- GDPR data-localization mandates:European SMBs must store customer records within EU borders, accelerating demand for regional cloud PBX deployments with sovereign data guarantees.
- India's fiber infrastructure buildouts:Government-subsidized rural broadband programs are creating first-time subscriber bases among professional services firms in tier-2 cities.
- SIP trunking protocol standardization:Interoperability improvements are reducing switching costs for manufacturing and logistics SMEs abandoning legacy ISDN circuits.
Market Restraints
- 5G spectrum auction costs:Carriers in Germany, Japan, and South Korea face compressed ROI timelines as standalone network capex absorbs capital that previously funded SMB service innovation.
- Last-mile fiber concentration:Incumbent operators control 70-80% of physical infrastructure in most European markets, raising wholesale access barriers for cloud-native challengers.
- IPv4 address exhaustion:Small operators struggle to secure contiguous address blocks for VoIP scaling, forcing premature IPv6 migrations with incompatible legacy customer premises equipment.
Strategic Opportunities
- AI-powered voice analytics convergence:Integration of real-time transcription and sentiment analysis into unified communications contracts creates upsell potential in customer service verticals.
- India's TRAI interconnect reforms:Reduced termination charges for VoIP-to-PSTN calls improve margin structures for hosted telephony providers serving price-sensitive micro-enterprises.
- SD-WAN bundling innovation:Managed service providers can displace standalone connectivity vendors by wrapping application-aware routing into voice and data packages for distributed workforces.
Industry Challenges
- Legacy PBX integration complexity:Hybrid deployments requiring session border controllers and analog gateway hardware extend project timelines and erode cloud migration economics for 50-100 seat enterprises.
- E911 location database accuracy:Nomadic VoIP users trigger regulatory compliance failures when dynamic IP assignments fail to map to precise dispatchable addresses, exposing carriers to FCC enforcement actions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SMB Telecom Voice and Data Services Market |
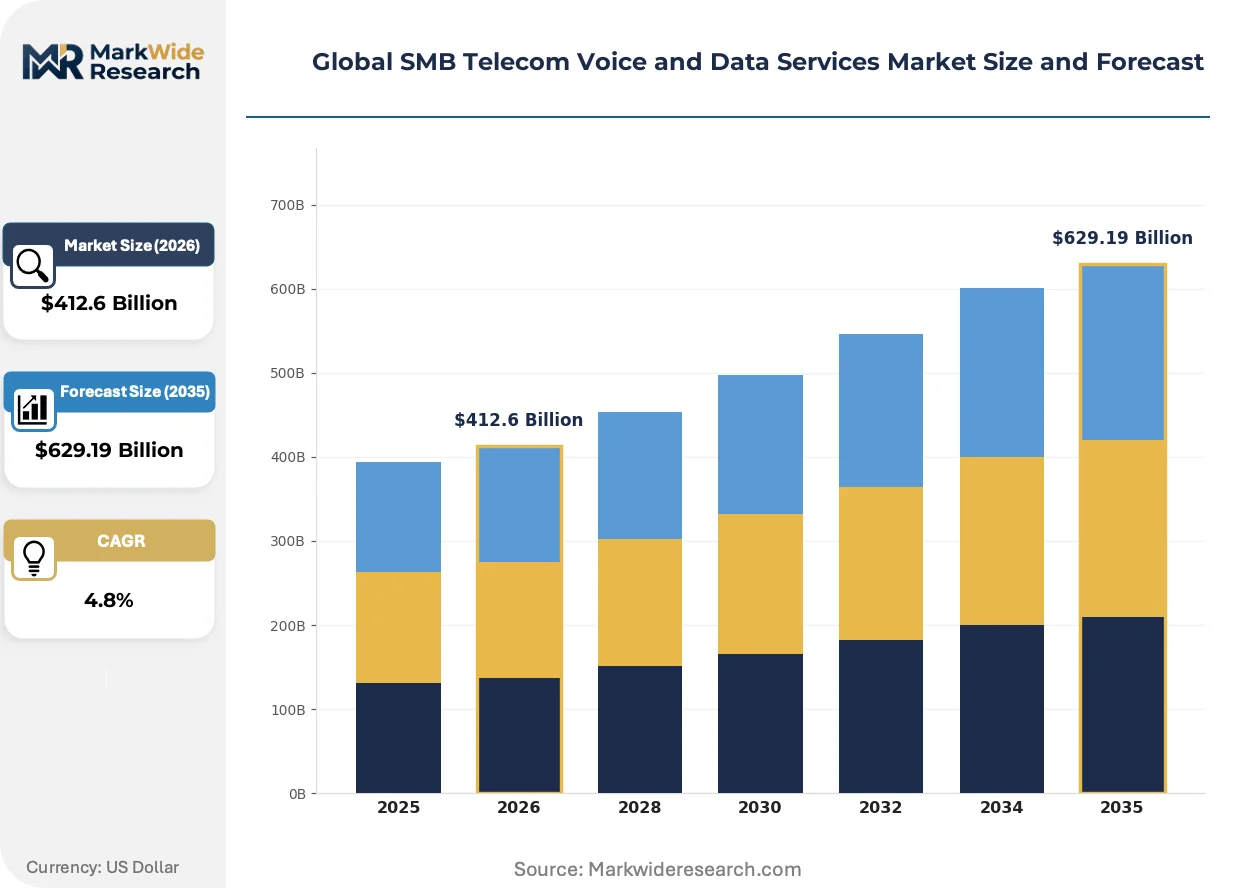
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $629.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice over IP, Dedicated Internet Access, Managed PBX, SIP Trunking, Unified Communications, Mobile Voice Services Application: Customer Support, Sales Enablement, Remote Workforce Connectivity, Cloud Collaboration, Network Security, Virtual Meetings Client Type: Small Enterprises, Medium Firms, Startups, Professional Services, Retail Outlets, Educational Institutions Deployment Model: Cloud-based, On-premises, Hybrid Solutions, Hosted Services, Managed Networks, Virtual PBX |
| Companies Covered | Deutsche Telekom, BT Group, AT&T, CenturyLink, Vodafone, Verizon, Orange, T-Mobile, Comcast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SMB Telecom Voice and Data Services Market Shifts & Advancements
Edge computing architectures are redistributing voice processing from centralized data centers toward customer premises, collapsing latency for real-time collaboration tools and enabling new service tiers that were previously uneconomical at SMB scale.
Embedded communications platforms are miniaturizing. These API-delivered voice and video modules integrate directly into vertical SaaS applications like CRM and field service management. Professional services firms in Germany and the United Kingdom are adopting them twice as fast as standalone UCaaS contracts. The technology is miniaturizing carrier relationships into software dependencies rather than infrastructure contracts.
CSRD sustainability disclosure mandates now require European carriers to report Scope 3 emissions from their supply chains. This compels infrastructure vendors to certify energy efficiency of routing equipment and cooling systems. Mid-sized manufacturing customers in France and Italy are beginning to weight carbon transparency in RFP scoring, privileging operators with verified renewable power purchase agreements.
Subscription fatigue is altering procurement patterns. SMB technology buyers in Japan and South Korea are resisting multi-year unified communications lock-ins, favoring month-to-month contracts with modular feature activation. Channel partners are responding with unbundled pricing that separates core connectivity from advanced analytics, collapsing average contract values but improving logo retention rates among 10-50 employee professional services firms.
Global SMB Telecom Voice and Data Services Market Segmentation
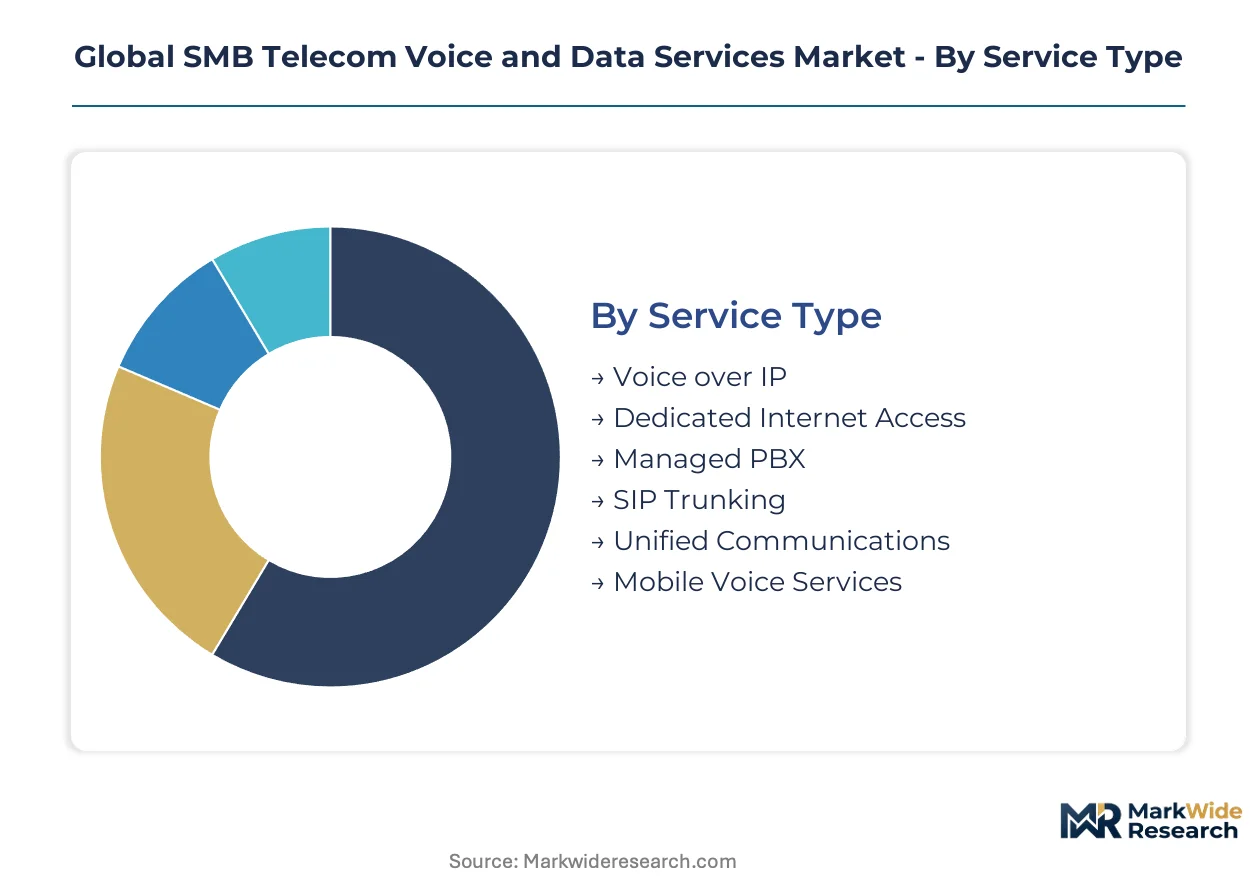
SMB telecom purchasing patterns diverge sharply by operational maturity and regulatory exposure. Service providers must align contract structures, SLA tiers, and integration complexity to each segment's technical debt tolerance and compliance obligations.
Service Type:
Domestic infrastructure ownership determines which segments carriers can profitably deliver; export-led segments rely on cross-border IP transit and regional data center footprints.
- Voice over IP:Packet-switched telephony delivered over broadband or dedicated circuits with codec negotiation for quality-of-service prioritization. German and Japanese manufacturing clusters drive demand as ISDN phase-outs accelerate, though IPv4 address scarcity forces smaller operators into premature IPv6 migrations with incompatible legacy CPE.
- Unified Communications:Integrated voice, video, messaging, and presence platforms delivered through single-vendor contracts with API extensibility. Professional services firms in the United Kingdom and Germany adopt embedded communications modules twice as fast as standalone UCaaS, compressing carrier relationships into software dependencies.
- SIP Trunking:Session Initiation Protocol connectivity between IP PBX systems and PSTN networks, leveraging existing carrier voice infrastructure for high-margin recurring revenue.
- Managed PBX:Carrier-hosted private branch exchange systems with remote administration and hardware lifecycle management.
- Dedicated Internet Access:Symmetrical, uncontended connectivity with guaranteed bandwidth and latency SLAs for mission-critical operations.
- Mobile Voice Services:Cellular voice and data plans with pooled usage and device management for distributed field workforces.
SIP Trunking commands the established base. The steepest expansion runs through Unified Communications.
Application:
Cost tier stratification separates premium real-time collaboration from commodity connectivity, with security and compliance workloads commanding sustained pricing power.
- Remote Workforce Connectivity:Secure access architectures spanning SD-WAN, zero-trust network access, and split-tunnel VPN for distributed employees. Indian professional services firms in tier-2 cities represent the fastest-scaling demand vector as government-subsidized fiber builds reach first-time subscriber bases.
- Cloud Collaboration:File sharing, co-editing, and asynchronous project management integrated with synchronous communication tools. GDPR data-localization mandates compel European deployments with sovereign data guarantees, accelerating regional cloud PBX adoption among compliance-conscious SMBs.
- Customer Support:Contact center functionality with queue management, IVR, and CRM integration for service operations.
- Sales Enablement:Mobile CRM integration, click-to-dial, and conversation analytics for revenue teams.
- Network Security:Firewall, intrusion detection, and secure web gateway services bundled with connectivity.
- Virtual Meetings:Video conferencing with recording, transcription, and breakout room functionality.
Customer Support retains the largest installed base. Cloud Collaboration is expanding most quickly.
Client Type:
Volume concentration varies by segment maturity, with medium firms driving managed service attach rates and startups favoring self-service provisioning.
- Medium Firms:Organizations with 50-250 employees requiring hybrid infrastructure with legacy PBX integration and phased cloud migration paths. Manufacturing and logistics SMEs across Germany and South Korea face extended project timelines due to session border controller complexity and analog gateway hardware requirements.
- Professional Services:Legal, accounting, and consulting practices with compliance-driven documentation and client confidentiality requirements. France and Italy apply CSRD sustainability disclosure weighting in RFP scoring, privileging operators with verified renewable power purchase agreements.
- Small Enterprises:Businesses with 10-49 employees prioritizing simplicity and predictable monthly costs.
- Startups:Venture-backed companies with elastic scaling requirements and API-first integration preferences.
- Retail Outlets:Multi-location chains requiring centralized management and PCI-DSS compliant payment processing.
- Educational Institutions:Schools and training centers with seasonal usage patterns and e-learning platform integration.
Medium Firms command the established base. The steepest expansion trajectory runs through Professional Services.
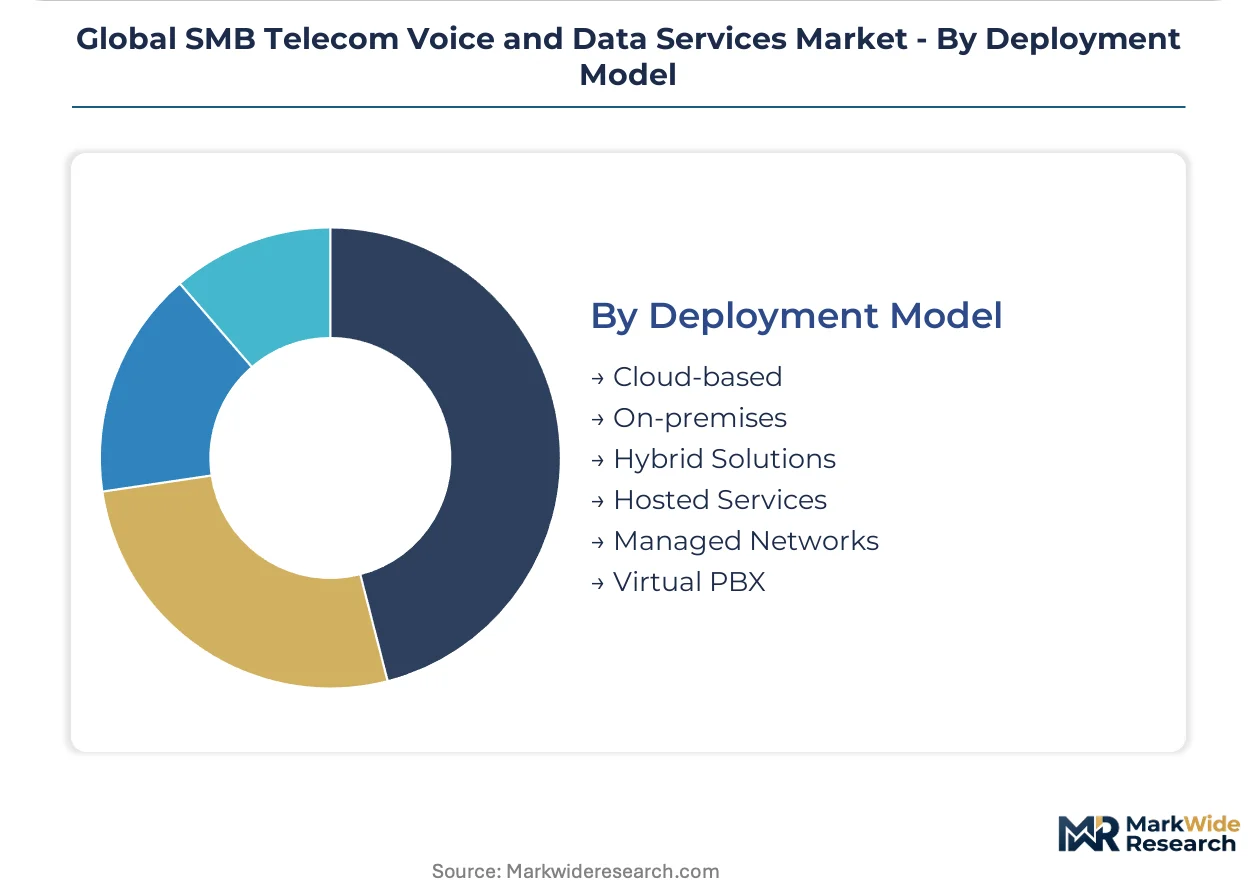
Deployment Model:
Margin structures favor recurring revenue models over capital-intensive on-premises installations, though hybrid architectures persist where regulatory or latency constraints apply.
- Cloud-based:Fully hosted infrastructure with subscription pricing, automatic updates, and elastic capacity scaling. Japanese and South Korean SMB buyers resist multi-year lock-ins, favoring month-to-month contracts with modular feature activation that collapses average contract values but improves retention.
- Hybrid Solutions:Split architectures retaining on-premises call control while migrating endpoints and applications to cloud platforms. European incumbents leverage fiber footprints to anchor managed PBX bundles, while cloud-native challengers compress deployment timelines from months to days through API-first infrastructure.
- On-premises:Customer-owned and operated equipment with perpetual licensing and internal administration.
- Hosted Services:Single-tenant infrastructure dedicated to one client but managed by the service provider.
- Managed Networks:Outsourced LAN, WAN, and security operations with proactive monitoring and remediation.
- Virtual PBX:Software-defined private branch exchange with minimal hardware requirements and rapid provisioning.
On-premises retains legacy dominance. Cloud-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led carrier revenues from managed voice and data services concentrate in Germany, Japan, and South Korea, while import-dependent SMB digitization programs in India and Brazil reshape subscriber acquisition patterns across emerging markets.
Germany
Manufacturing clusters in Bavaria and Baden-Württemberg drive demand for SIP trunking replacements as ISDN phase-outs accelerate through 2025. The Federal Network Agency (BNetzA) enforces wholesale access regulations that constrain incumbent pricing power over last-mile fiber. Deutsche Telekom leverages its European footprint to anchor managed PBX bundles for mid-sized industrial enterprises across the Ruhr region.
United States
Professional services firms in New York and California prioritize unified communications with API extensibility for CRM integration. FCC net-neutrality frameworks shape how carriers architect cross-border data routing for SMB clients with multi-state operations. Verizon sustains technology leadership through in-house SD-WAN integration, while Comcast targets retail and hospitality verticals with bundled connectivity packages.
India
Government-subsidized rural broadband programs under BharatNet create first-time subscriber bases among professional services firms in tier-2 cities like Pune and Hyderabad. TRAI interconnect regulations reduce termination charges for VoIP-to-PSTN calls, improving margin structures for hosted telephony providers. Fiber infrastructure builds in Maharashtra and Karnataka outpace national averages by 40 percent.
Japan
SMB buyers in Tokyo and Osaka resist multi-year unified communications lock-ins, favoring month-to-month contracts with modular feature activation. METI digital transformation subsidies offset migration costs from legacy PBX systems for 50-100 seat enterprises. KDDI and NTT East compete for manufacturing customers in Aichi Prefecture with edge-computing-enabled collaboration tools.
South Korea
5G standalone network rollouts by SK Telecom and KT expand managed service capabilities for distributed workforces in Seoul and Busan. Spectrum auction costs compress carrier ROI timelines, diverting capital from SMB service innovation toward infrastructure consolidation. Gyeonggi Province electronics manufacturers drive demand for low-latency voice processing at the network edge.
Global SMB Telecom Voice and Data Services Market Competitive Landscape
Concentration sits with fiber-owning incumbents who anchor recurring revenue through infrastructure bundles, while cloud-native challengers compress deployment timelines through API-first delivery stacks. Three archetypes dominate: legacy carriers with physical network assets, software-defined challengers with platform economics, and mobile-first operators expanding into fixed-line SMB services. Competitive moves center on SD-WAN bundling innovation and AI-powered voice analytics integration into existing contracts.
Within the incumbent carrier tier, Deutsche Telekom and Verizon exemplify divergent strategic positioning around infrastructure ownership versus in-house technology development. Deutsche Telekom leverages its European fiber footprint to capture manufacturing verticals with managed network solutions. Verizon occupies a position defined by vertical integration into SD-WAN capabilities that reduce third-party dependencies. Orange sits within the geographic expansion archetype, competing across Africa and the Middle East with mobile-first packages tailored to small enterprises lacking fixed-line infrastructure.
| Leading Market Players |
|---|
| Deutsche Telekom |
| BT Group |
| AT&T |
| CenturyLink |
| Vodafone |
| Verizon |
| Orange |
| T-Mobile |
| Comcast |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with tier-1 carriers lock in fiber access and price visibility for mid-sized enterprises across Germany and Japan, insulating buyers from spot-market volatility in wholesale bandwidth while committing suppliers to dedicated infrastructure builds.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing with three distinct service levels separating premium SLA-backed unified communications from standard hosted PBX and economy-grade SIP trunking. Price differentiation rests on guaranteed uptime thresholds and geographic redundancy coverage, with customization for legacy PBX integration commanding substantial premiums. Cost compression in the economy tier is intensifying because cloud-native challengers are collapsing deployment timelines and forcing incumbents to unbundle feature sets. Startups and micro-enterprises with 10-49 employees exhibit the highest price sensitivity, while professional services firms with compliance mandates absorb premium pricing without volume negotiation.
Supply Chain Analysis
Germany, Japan, and South Korea anchor submarine cable landing stations and edge data center construction for voice processing infrastructure serving regional SMB clusters. Component sourcing draws from Taiwanese semiconductor foundries for session border controllers, Finnish cooling systems manufacturers for data center thermal management, and domestic fiber optic cable producers in each market. Single-source vulnerability concentrates in specialized VoIP chipset supply from a limited vendor base. Distribution runs through carrier-direct sales organizations and certified channel partners with technical integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of API-first infrastructure engineering talent constrains how quickly traditional carriers can re-architect service delivery stacks, creating asymmetric capability gaps between fiber-owning incumbents and software-defined challengers.
For Market Incumbents: Consolidate managed service attach rates by bundling SD-WAN with voice contracts to defend against cloud-native displacement in the 50-250 employee segment. Deepen backward integration into proprietary edge computing infrastructure rather than relying on hyperscaler partnerships that erode margin control. Prioritize certification investment for IPv6-ready customer premises equipment to address address exhaustion risks threatening VoIP scaling. For New Entrants and Emerging Players: Anchor in India's tier-2 professional services markets where BharatNet fiber builds are creating first-time subscriber bases with minimal incumbent penetration. Target price-sensitive micro-enterprises with modular month-to-month contracts featuring à la carte analytics activation. Pursue a channel-centric go-to-market through systems integrators already embedded in manufacturing verticals undergoing ISDN migration. For Investors and Strategic Acquirers: Cloud-native voice platforms with established API marketplaces and vertical SaaS integration partnerships represent the most defensible acquisition profile for sustained value creation. Monitor TRAI interconnect regulation amendments as the critical signal for margin structure inflection in hosted telephony, with termination charge reductions directly improving unit economics for scalable providers.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Compresses deployment timelines from months to days for mid-market manufacturing clients. |
| Edge Computing Infrastructure Buildout | Enables low-latency voice processing for Gyeonggi Province electronics manufacturers. |
| SD-WAN Bundling Innovation | Displaces standalone connectivity vendors serving distributed professional services firms. |
| AI-Powered Voice Analytics Convergence | Creates upsell potential in customer service verticals through real-time sentiment analysis. |
| Renewable Power Purchase Agreements | Meets CSRD disclosure mandates for European professional services RFP scoring. |
Research Methodology
A spread of perspectives from carrier product managers, channel partner technical directors, enterprise IT procurement officers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against TRAI regulatory filings, FCC net-neutrality dockets, carrier capex disclosures, and spectrum auction outcome databases. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from infrastructure deployment tracking.
Segmentation dimensions modeled include service type, deployment architecture, client size tier, and application workload across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure buildout timelines. Forecast inputs incorporated 5G standalone rollout schedules, fiber penetration trajectories, and ISDN phase-out regulatory deadlines.
Material uncertainties — spectrum auction cost overruns, IPv6 migration delays, and sustainability disclosure enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about carrier investment priorities and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Cambodia Telecom Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Algeria Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Prepaid Communication Market
Telecommunications
Global 4G LTE Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Promotional Sms Market