
 India Optical Transport Network (OTN) Market | 2026-2036
India Optical Transport Network (OTN) Market Size, Share, and Industry Trends Forecast 2026-2036
India Optical Transport Network (OTN) Market Insights
Data center operators is broadening their share of OTN procurement as hyperscale facilities multiply across Indian cities. Tejas Networks Limited anchors its position through in-house ASIC design and domestic manufacturing scale. Huawei Technologies Co Ltd competes on system-level integration spanning transport and access layers. Ciena Corporation differentiates via programmable coherent optics and software-defined control planes.
Optical Transport Network denotes a standardized digital wrapper protocol that encapsulates client signals into optical channel transport units, enabling multiplexing of 10G to 400G wavelengths over single-mode fiber with forward error correction and tandem connection monitoring. Its primary purpose is to guarantee service-level agreements across long-haul and metro networks through sub-50ms protection switching. Wavelength Division Multiplexing dominates capital deployment as carriers maximize fiber utilization, while OTN Switches command premium margins at network aggregation nodes. Synchronous Optical Networking retains relevance in legacy government and utility backbones where circuit emulation remains mandatory.
TRAI's quality-of-service benchmarks and the Department of Telecommunications' mandatory testing through designated labs shape equipment certification timelines and technical compliance costs. BIS standards for optical fiber cables and the CEA's grid connectivity codes for telecom infrastructure create layered conformance requirements for vendors. Stakeholders must weigh the pace of 400G coherent rollout against the revenue dilution from open optical disaggregation models gaining traction in carrier procurement.
Market Dynamics
Carrier investment in 400G coherent optics is compressing upgrade cycles across Indian metro and long-haul routes, forcing equipment vendors to recalibrate roadmaps around domestic manufacturing incentives and TRAI-mandated quality benchmarks.
Growth Catalysts
- 5G backhaul densification:Telecom service providers are extending OTN rings to cell towers, creating sustained demand for 100G to 400G wavelength services across urban corridors.
- BharatNet Phase III:The Department of Telecommunications' rural broadband initiative is channeling public capital into optical fiber deployment across gram panchayats, expanding addressable infrastructure.
- Hyperscale data center clustering:Cloud operators in Mumbai, Hyderabad, and Chennai are procuring OTN switches for inter-facility connectivity, shifting procurement volume toward aggregation-layer equipment.
Market Restraints
- Import dependency for coherent DSPs:Domestic vendors lack captive supply of digital signal processors, exposing margins to dollar-denominated component costs and customs processing delays.
- Right-of-way fragmentation:Municipal corporations and state electricity boards impose inconsistent fees and timelines for fiber trenching, extending project gestation in dense urban cores.
- Legacy SONET/SDH lock-in:Government utilities and defense networks maintain circuit-switched backbones, delaying packet-optical convergence and constraining addressable base for pure OTN vendors.
Strategic Opportunities
- Semi-urban fiberization:Tier-2 cities including Jaipur, Lucknow, and Kochi present underpenetrated demand for metro rings as enterprise cloud adoption diffuses beyond top eight metros.
- Open optical disaggregation:Separating transponder hardware from line system control software enables white-box procurement models, allowing system integrators to capture value previously held by vertically integrated suppliers.
- PLI scheme for telecom equipment:The Production Linked Incentive framework offers cost offsets for domestic manufacturing, rewarding vendors with in-house ASIC design and fab-less production scale.
Industry Challenges
- Optical design engineering scarcity:The talent pool for coherent modulation algorithms and forward error correction implementation remains concentrated in Bengaluru and Hyderabad, constraining vendor expansion.
- Multi-vendor interoperability certification:Operators deploying open line systems face extended lab validation cycles at TEC-designated facilities, compressing deployment windows for competitive bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Optical Transport Network (OTN) Market |
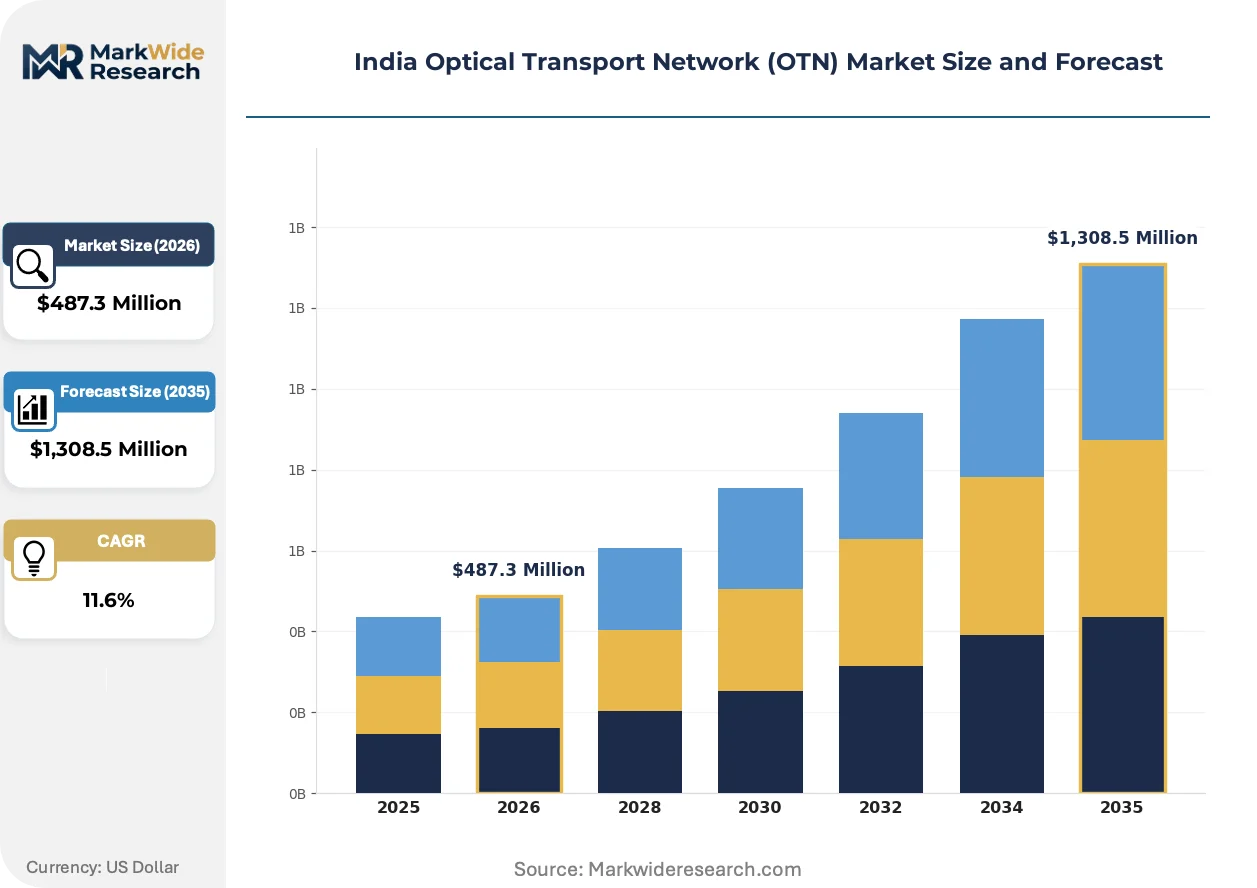
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wavelength Division Multiplexing, Synchronous Optical Networking, Fiber Channel, OTN Switches End User: Telecommunications Service Providers, Data Center Operators, Enterprises, Government Agencies Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services Technology: Ethernet, SONET, SDH, MPLS |
| Companies Covered | Huawei Technologies Co Ltd, Fujitsu Limited, Nokia Corporation, Tejas Networks Limited, Infinera Corporation, Ciena Corporation, ZTE Corporation, NEC Corporation, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Optical Transport Network (OTN) Market Trends and Innovations
Software-defined control planes are reconfiguring how Indian carriers provision wavelength services, collapsing manual provisioning intervals from weeks to hours while introducing new vendor competitive dynamics around API openness.
Programmable coherent optics is automating capacity allocation across variable-reach links. BSNL and Bharti Airtel are deploying these transponders in 400G-ready configurations, enabling modulation-format selection per span without truck rolls. The technology is automating margin optimization that previously required manual engineering judgment, compressing opex for long-haul routes.
TRAI's revised quality-of-service regulations now mandate latency and availability reporting at the wavelength level. Carriers must install performance monitoring probes and submit quarterly compliance filings, elevating documentation overhead. Metro Ethernet and enterprise VPN segments face the steepest compliance burden as they lack legacy performance management infrastructure.
Enterprise buyers are consolidating transport procurement under managed service contracts rather than capital purchase agreements. System integrators including Tech Mahindra and Tata Communications are absorbing equipment risk and offering bandwidth-as-a-service to financial institutions and healthcare networks. This rotation is most pronounced in Maharashtra and Karnataka where data center proximity enables rapid service activation.
India Optical Transport Network (OTN) Market Segmentation
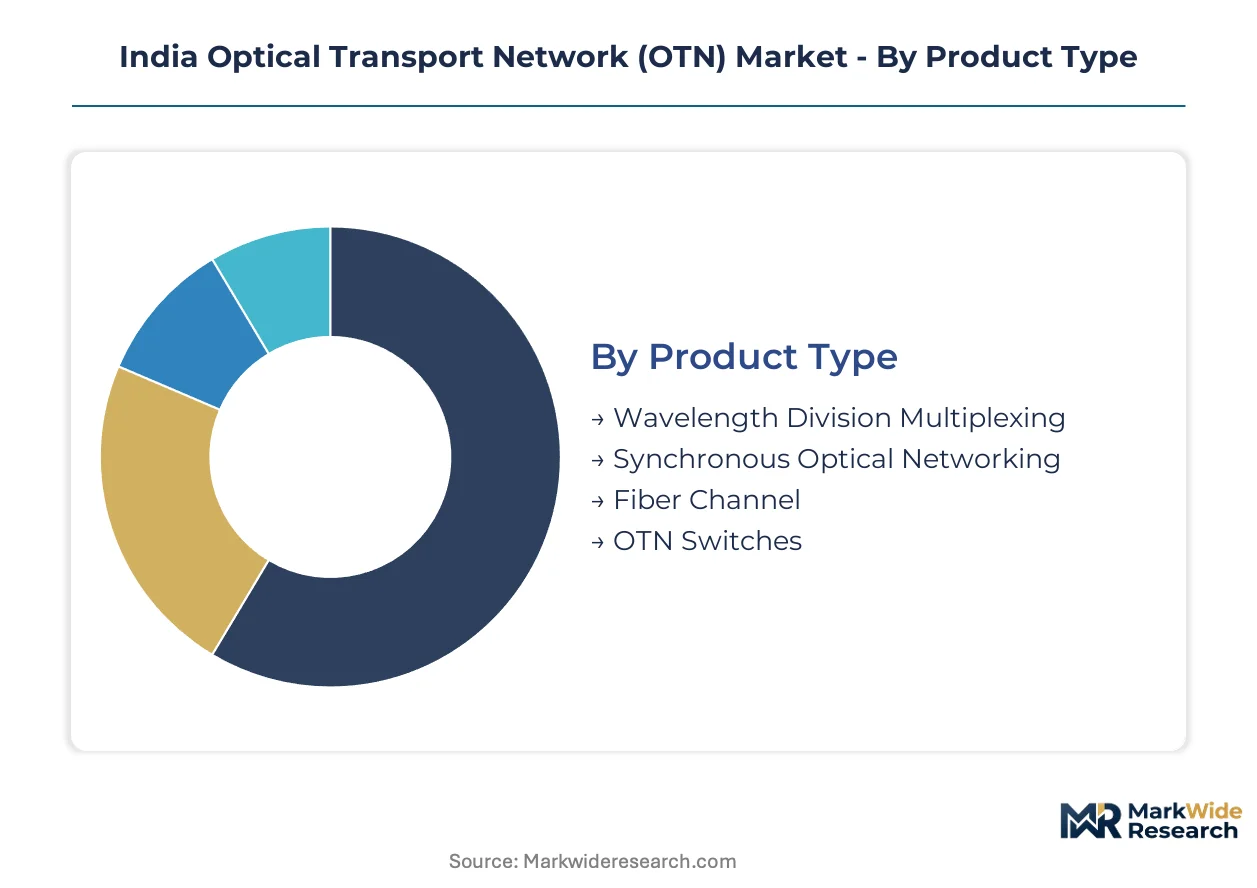
India's OTN procurement patterns fragment sharply across product architectures, buyer sophistication, and deployment economics. Each segmentation dimension reveals distinct margin profiles and vendor competitive dynamics that shape strategic positioning.
Product Type:
Buyers differentiate primarily by fiber utilization efficiency versus switching intelligence requirements.
- Wavelength Division Multiplexing:Multi-carrier optical transmission technology multiplexes 10G to 400G signals across single-mode fiber pairs. TRAI's quality benchmarks and BharatNet rural fiberization concentrate procurement in Maharashtra and Telangana corridors where backbone densification is most acute.
- OTN Switches:Aggregation-layer equipment with sub-50ms protection switching and tandem connection monitoring capabilities. Hyperscale data center operators in Mumbai and Hyderabad drive premium pricing as they interconnect facilities for cloud workload portability.
- Synchronous Optical Networking:Legacy TDM transport retaining relevance in defense and utility networks where circuit emulation remains mandatory for SCADA and mission-critical telemetry systems.
- Fiber Channel:Storage-area network protocol extending OTN encapsulation for enterprise disaster recovery and financial transaction replication workloads.
Volume sits with Wavelength Division Multiplexing; growth tilts toward OTN Switches.
End User:
Procurement sophistication varies by buyer technical staffing depth and capex-versus-opex preference.
- Telecommunications Service Providers:Backbone operators scaling 400G coherent rings for 5G backhaul and metro densification. Bharti Airtel and BSNL deployments concentrate in Karnataka and Tamil Nadu urban corridors with highest mobile data density.
- Data Center Operators:Hyperscale and colocation facilities procuring programmable coherent optics for inter-facility connectivity. Their procurement is shifting toward managed bandwidth contracts rather than capital equipment ownership.
- Enterprises:Financial institutions and healthcare networks in Maharashtra purchasing managed wavelength services through system integrators, absorbing equipment risk under SLA-governed agreements.
- Government Agencies:Defense and utility networks maintaining SONET/SDH backbones with circuit-switched reliability requirements, constraining addressable base for packet-optical vendors.
Revenue concentrates with Telecommunications Service Providers; expansion is steepest among Data Center Operators.
Deployment Model:
Control retention versus operational burden trade-offs segment buyer preferences.
- On-premises:Carrier-owned infrastructure with direct hardware maintenance responsibility, prevailing among BSNL and defense networks with sovereign data requirements.
- Managed Services:System integrators including Tech Mahindra and Tata Communications absorbing equipment lifecycle risk, offering bandwidth-as-a-service with guaranteed latency and availability SLAs.
- Cloud-based:Software-defined control planes with API-driven provisioning, gaining traction among enterprises seeking rapid service activation without truck-roll dependency.
- Hybrid:Mixed ownership models partitioning critical backbone infrastructure from elastic capacity augmentation through service contracts.
Installed base favors On-premises deployment; contract value is climbing fastest in Managed Services.
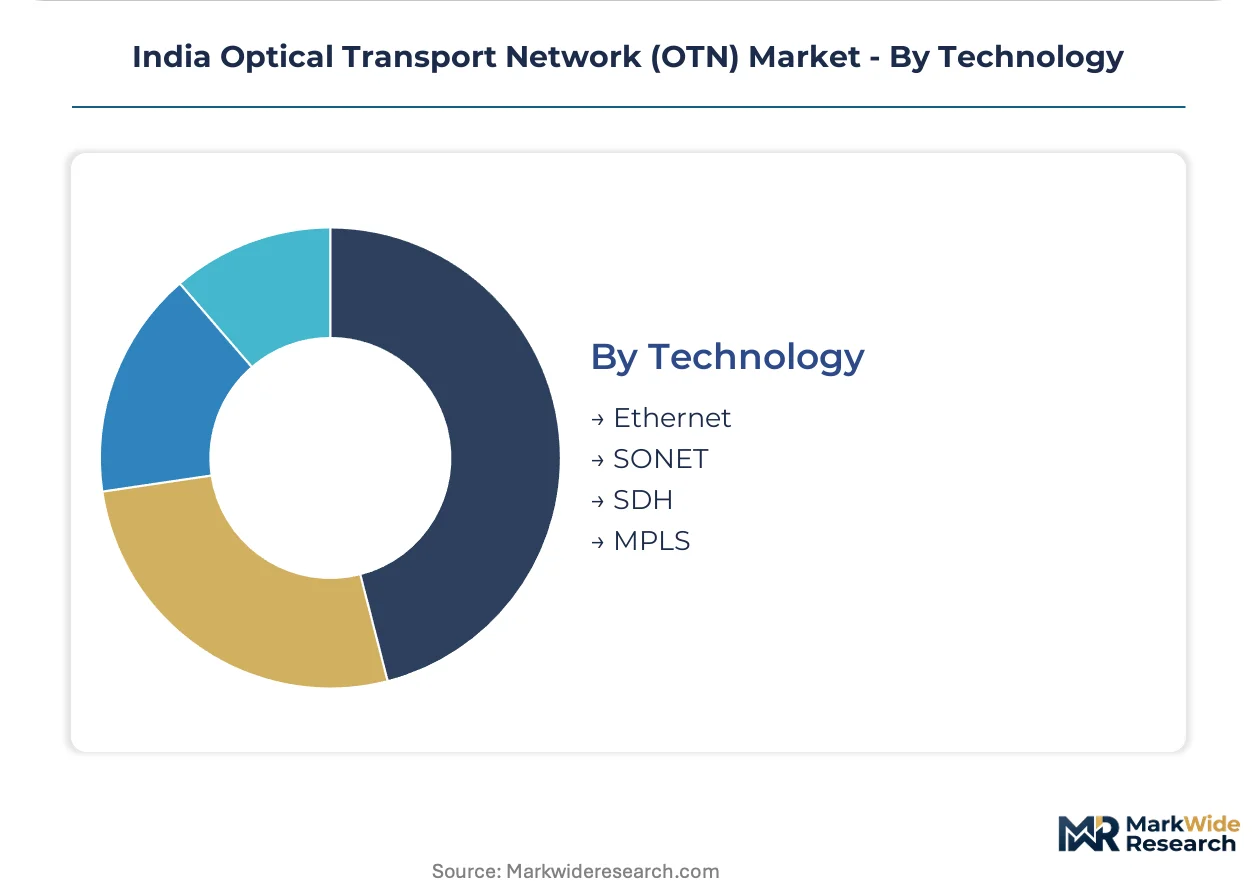
Technology:
Layer-2 encapsulation choices determine interoperability complexity and legacy migration paths.
- Ethernet:Dominant client interface for data center interconnect and enterprise VPN aggregation, aligning with IP/MPLS convergence trends in carrier backbones.
- MPLS:Traffic-engineered packet transport with differentiated service classes, deployed by Bharti Airtel for enterprise SLA enforcement across variable-reach optical spans.
- SONET:Legacy synchronous transport with rigid hierarchy, retained in government utility networks where TDM circuit emulation remains non-negotiable.
- SDH:International variant of SONET with identical technical characteristics, referenced in BIS standards for optical fiber cable conformance testing.
Deployment volume rests with Ethernet; MPLS is gaining share fastest among carriers modernizing enterprise service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software Technology Parks of India (STPI) zones and Special Economic Zones (SEZs) channel optical infrastructure investment into designated corridors. Tax holidays and duty exemptions under these frameworks concentrate vendor operations and carrier procurement in specific geographic clusters. State-level electronics policies further amplify regional divergence in deployment velocity.
Maharashtra
Mumbai's hyperscale data center concentration drives inter-facility OTN switch procurement for cloud workload portability. The state's Information Technology and IT Enabled Services Policy offers capital subsidies for data center infrastructure, accelerating metro ring densification. Pune and Mumbai together host the densest fiber corridors, with carriers deploying 400G coherent optics along the Mumbai-Pune Expressway route.
Karnataka
Bengaluru's telecom equipment design ecosystem supplies coherent DSP engineering talent to domestic vendors. The Karnataka Electronics System Design and Manufacturing Policy incentivizes optical component assembly within the state. Whitefield and Electronic City data center clusters generate sustained demand for programmable transponders with software-defined control planes.
Telangana
Hyderabad's tier-2 data center market is expanding faster than national averages, pulling OTN aggregation equipment into the city periphery. The Telangana State Industrial Project Approval and Self-Certification System (TS-iPASS) fast-tracks telecom infrastructure clearances. The Hyderabad Metro Rail corridor serves as a fiber duct pathway, reducing right-of-way negotiation cycles for carrier deployments.
Tamil Nadu
Chennai's submarine cable landing stations anchor international bandwidth aggregation, requiring high-capacity backhaul to inland data centers. The Tamil Nadu Electronics Manufacturing Policy targets optical fiber cable production through dedicated electronics manufacturing clusters. Sriperumbudur and Oragadam industrial zones are emerging as assembly points for passive optical components serving South Indian carriers.
Gujarat
GIFT City's financial district procurement of managed wavelength services is shifting enterprise transport spending toward opex models. The Gujarat Electronics Policy allocates land parcels for telecom equipment manufacturing near Sanand and Vadodara. Ahmedabad's enterprise cloud adoption lags metro peers, creating latent demand for metro ring expansion as SaaS penetration deepens.
India Optical Transport Network (OTN) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated system vendors holding backbone positions while white-box assemblers gain traction in open line system deployments. The vendor base arranges into three tiers: integrated transport-access platforms, pure-play optical component suppliers, and domestic system integrators with in-house ASIC design. Consolidation pressure is mounting as carriers consolidate procurement under fewer vendor relationships. Capacity localization and software licensing flexibility represent the dominant competitive vectors.
Among integrated platform vendors, Huawei Technologies Co Ltd and Nokia Corporation occupy positions spanning transport layer hardware through management software stacks. Tejas Networks Limited exemplifies the domestic specialist archetype with captive semiconductor design capabilities. Ciena Corporation represents the programmable optics tier with software-defined control plane differentiation. These three anchors illustrate the strategic divergence between global scale, local manufacturing incentives, and disaggregated software value capture.
| Leading Market Players |
|---|
| Huawei Technologies Co Ltd |
| Fujitsu Limited |
| Nokia Corporation |
| Tejas Networks Limited |
| Infinera Corporation |
| Ciena Corporation |
| ZTE Corporation |
| NEC Corporation |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
400G coherent optics deployment compresses upgrade cycles while concentrating procurement power among carriers with BharatNet-scale fiberization mandates. This technology transition simultaneously elevates domestic manufacturing incentives under the PLI scheme and exposes margins to dollar-denominated DSP component costs.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment: carriers pay premiums for 400G transponders deliverable within compressed windows, while spot inventory of 100G legacy hardware trades at discounts. Three-tier pricing structure across premium programmable optics, standard fixed-configuration systems, and economy refurbished equipment dominates procurement. Price differentiation hinges on TEC certification tier and volume scale commitments. Cost compression in the standard tier intensifies because open optical disaggregation enables white-box substitution. Government utilities demonstrate highest price sensitivity due to fixed budget appropriations; hyperscale data center operators show lowest sensitivity given latency SLA penalties.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme and BIS optical fiber cable standards are reshoring final assembly while captive DSP supply remains concentrated in Taiwan, South Korea, and the United States. Raw material dependencies center on indium phosphide wafers, lithium niobate modulators, and single-mode fiber preforms. Single-source vulnerability in coherent DSP supply exposes vendors to customs processing delays and dollar-denominated cost volatility. Distribution runs through carrier-direct procurement for backbone infrastructure and system integrator channels for managed wavelength services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TRAI's quality-of-service benchmarks and TEC mandatory testing protocols erect compliance moats that favor incumbents with established lab relationships and certification track records.
For Market Incumbents: Acquire coherent DSP engineering talent pools concentrated in Bengaluru and Hyderabad to secure algorithmic differentiation against open optical commoditization. Consolidate procurement relationships by absorbing equipment lifecycle risk under managed service contracts, mirroring Tech Mahindra and Tata Communications positioning. Expand domestic manufacturing footprint to capture PLI scheme offsets and reduce exposure to import duty volatility. For New Entrants and Emerging Players: Capture semi-urban fiberization demand in Jaipur, Lucknow, and Kochi where tier-2 enterprise cloud adoption outpaces incumbent carrier deployment velocity. White-box transponder assembly for open line system integrators represents the most penetrable entry vector, bypassing vertically integrated vendor relationships. Lead with API-first software-defined control planes to differentiate against legacy provisioning intervals. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic system integrators with in-house ASIC design capabilities and established TEC certification pipelines. Long-term viability favors vendors capturing value migration from hardware to software layers as programmable optics automates manual engineering judgment. Watch open optical disaggregation penetration rates as the inflection signal distinguishing commodity assemblers from platform consolidators.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic ASIC Design Capability | Captures PLI scheme incentives while reducing coherent DSP import dependency. |
| TEC Certification Fast-Track Investment | Compresses equipment approval timelines for BharatNet Phase III deployment windows. |
| Managed Service Contract Expansion | Absorbs carrier capex constraints by offering bandwidth-as-a-service with guaranteed SLAs. |
| Open Line System Partnership | Enables white-box procurement models that displace vertically integrated transport vendors. |
| Semi-Urban Metro Ring Deployment | Addresses latent enterprise demand in tier-2 cities beyond saturated Mumbai-Bengaluru corridors. |
Research Methodology
Document review covered TRAI regulatory filings, TEC equipment certification records, and BharatNet deployment disclosures, complemented by interviews with carrier network planning executives, optical equipment procurement managers, and data center interconnection specialists. Secondary validation drew from BIS standards documentation, CEA grid connectivity codes, and PLI scheme administrative records. Bottom-up demand modeling across carrier capex disclosures and top-down market sizing from infrastructure deployment pipelines were triangulated for convergence.
Segment-level projections across product architecture, end-user category, deployment model, and encapsulation technology were generated over the projection horizon. CAGRs were derived from infrastructure investment trajectories, equipment replacement cycle compression, and technology transition elasticity estimates. Forecast inputs incorporated 5G backhaul densification timelines, hyperscale data center clustering patterns, and rural broadband subsidy allocation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to open optical disaggregation adoption rates, PLI scheme incentive continuity, and right-of-way clearance velocity in dense urban corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Costa Rica Telecom Market
Telecommunications
C-RAN Market
Telecommunications
France Telecom Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Indonesia Telecom Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Fixed LTE Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Fixed Voice Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Denmark ICT Market
Telecommunications
Global LTE Market
Telecommunications
5G System Integration Market