
 Smart Food Scale Market | 2026-2036
Smart Food Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Food Scale Market Insights
Market Context
The capital-intensity divergence between sensor-integrated hardware specialists and commodity electronics assemblers is unwinding competitive dynamics across the smart food scale landscape. RENPHO leverages its wellness ecosystem to bundle scales with body composition monitors, sustaining cross-device data loyalty. Etekcity competes on manufacturing scale, anchoring cost leadership through Shenzhen-based production networks. Greater Goods differentiates through certified B-Corp positioning, occupying the ethically sourced materials niche.
Technical Definition and Segment Structure
A smart food scale is a digitally connected weighing instrument incorporating load-cell sensors, microcontrollers, and wireless transmitters to measure food mass and communicate data to companion software for nutritional logging and recipe management. Precision typically reaches one-gram resolution, with Bluetooth Low Energy enabling real-time synchronization to smartphone applications that parse USDA or regional food databases. Smart scales with mobile app integration command the dominant revenue share, while nutritional analysis functionality represents the fastest-expanding feature segment as dietitian-prescribed meal planning proliferates. Bluetooth connectivity leads unit shipments, though Wi-Fi scales capture premium positioning through cloud-independent operation.
Regulatory Environment
The FDA oversees nutritional labeling claims on companion applications, while the FCC governs wireless transmission compliance for Bluetooth and Wi-Fi modules sold in the United States. The EU Green Deal's ecodesign requirements and REACH substance restrictions shape material selection for load-cell housings and circuit assemblies entering European markets. Stakeholders must monitor evolving cybersecurity standards for IoT kitchen devices as health data privacy frameworks tighten across major jurisdictions.
Market Dynamics
The smart food scale landscape is reconfiguring around load-cell sensor commoditization, which erodes hardware margins while forcing differentiation through software ecosystems and nutritional database depth.
Growth Catalysts
- Bluetooth Low Energy adoption:Real-time synchronization to USDA and regional food databases eliminates manual logging friction for macronutrient tracking. Home kitchens and clinical dietetics programs deploy these scales at accelerating rates.
- EU Green Deal ecodesign mandates:REACH substance restrictions and circular economy requirements for electronics are pressuring manufacturers toward recyclable load-cell housings and modular circuit designs, creating upgrade-cycle compression.
- Wellness technology spending concentration:Health-conscious consumer segments in the United States, Germany, and Japan sustain premium pricing for connected kitchen devices through insurance-integrated preventive health programs.
Market Restraints
- Lithium battery supply concentration:Cobalt and lithium processing gravity in the Democratic Republic of Congo and Chile exposes manufacturers to geopolitical disruption and ESG compliance costs for portable scale production.
- FDA nutritional labeling enforcement:Companion application claims require substantiation against USDA database accuracy, creating compliance friction for startups lacking regulatory affairs infrastructure.
- Smartphone dependency:Bluetooth-enabled scales without onboard displays become inoperable during device failure or app discontinuation, limiting adoption among technology-averse demographic segments.
Strategic Opportunities
- Clinical nutrition integration:Hospital discharge planning and renal/diabetes management programs in the United States are prescribing connected scales for home monitoring, opening institutional procurement channels.
- Wi-Fi cloud-independent operation:Direct router connectivity bypasses smartphone intermediaries, capturing premium positioning among multi-user households and professional kitchen environments.
- Japan's METI IoT security certification:Cybersecurity standards for connected kitchen devices create compliance-based segmentation, rewarding early certification with institutional procurement preference.
Industry Challenges
- Embedded firmware engineering scarcity:Load-cell calibration algorithms and BLE stack optimization require specialized talent concentrated in Shenzhen and Taipei, constraining R&D velocity for Western hardware startups.
- FCC modular approval timelines:Bluetooth and Wi-Fi transmitter certification for United States market entry extends development cycles by four to eight months, compressing competitive response windows.
- Multi-database synchronization complexity:Regional food composition variations between USDA, BLS (Germany), and MHLW (Japan) databases force costly localization of companion applications for market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Food Scale Market |
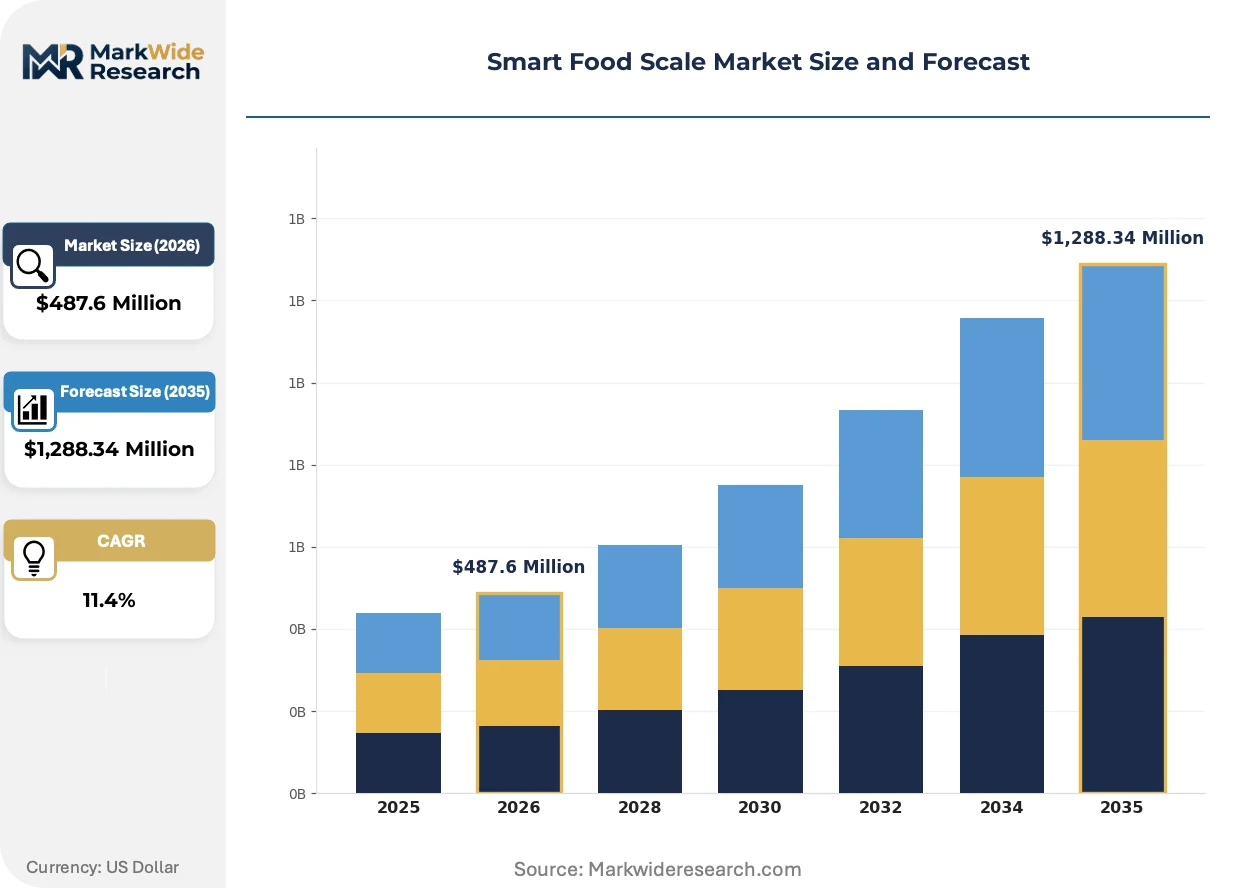
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scale, Mechanical Scale, Portion Control Scale, Smart Scale Connectivity: Bluetooth, Wi-Fi, USB, Wired End User: Home Users, Chefs, Nutritionists, Restaurants Feature: Mobile App Integration, Nutritional Analysis, Weight Tracking, Recipe Suggestions |
| Companies Covered | RENPHO, Escali, Etekcity, NutraTrack, Terraillon, Greater Goods, ZWILLING, Smart Chef, HOTO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Food Scale Market Trends and Innovations
Load-cell microfabrication and companion application intelligence are converging to collapse the boundary between raw measurement and actionable nutritional guidance, compressing the value chain toward software-centric monetization.
MEMS-based strain gauge technology is miniaturizing load-cell form factors while maintaining one-gram precision thresholds. Wearable and portable nutrition device manufacturers are integrating these sensors into pocket-scale formats for travel and restaurant use cases. Component miniaturization is compressing bill-of-material costs and enabling subscription-tier hardware bundling.
EU AI Act risk classification for health-adjacent algorithms is mandating transparency documentation for machine-learning food recognition features in companion applications. Manufacturers must now maintain explainability logs for automated nutritional suggestions, increasing compliance overhead. Premium-tier scales with on-device inference are capturing market preference by reducing cloud dependency and GDPR exposure.
Direct-to-consumer subscription bundling is displacing single-transaction retail for connected kitchen ecosystems. Scale purchasers commit to monthly nutritional coaching or meal-planning services, shifting revenue recognition patterns. This model concentrates in United States urban markets where wellness service penetration exceeds hardware attachment rates.
Smart Food Scale Market Segmentation
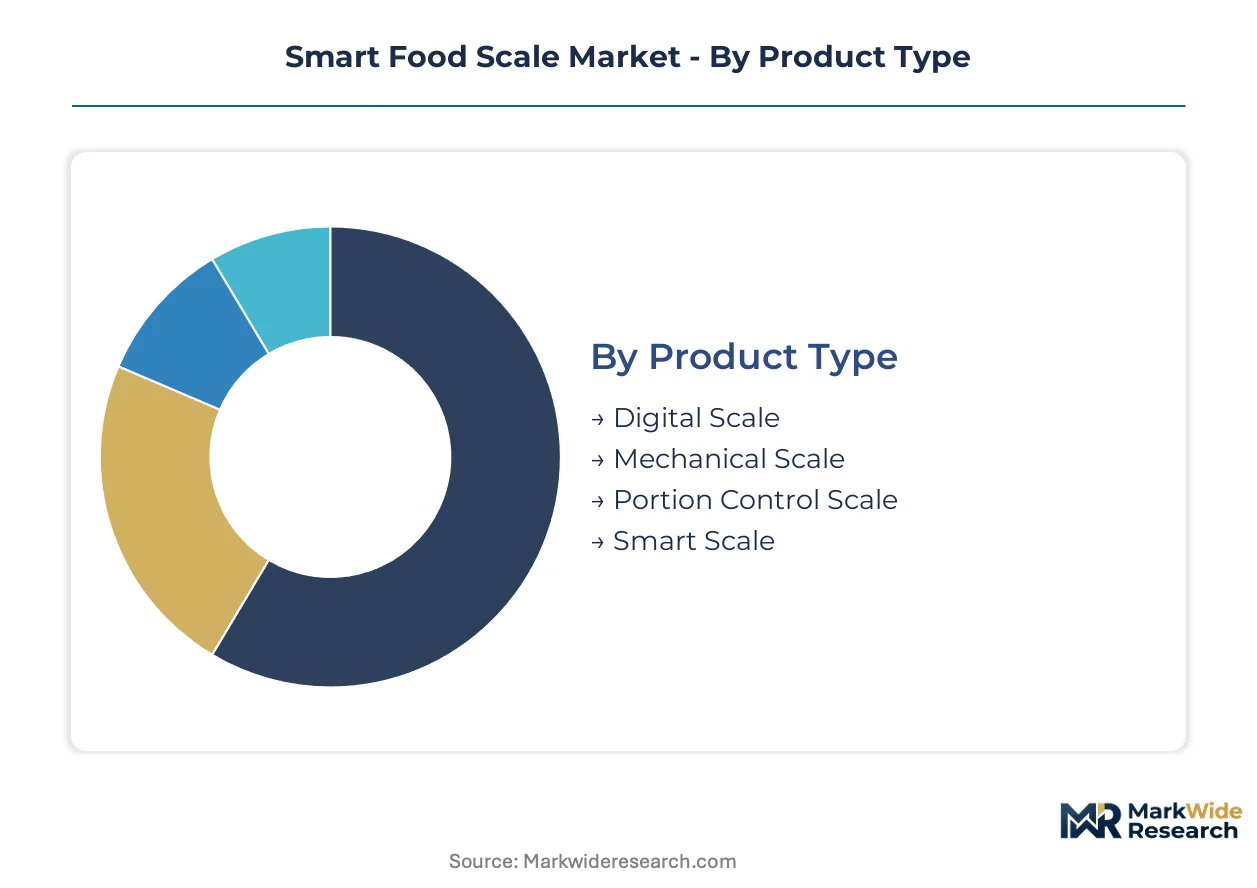
Segmentation in the smart food scale market exposes divergent margin profiles across hardware commoditization and software monetization pathways. Understanding where connectivity premiums concentrate versus where sensor costs dominate enables targeted portfolio construction for manufacturers navigating the shift from device sales to subscription ecosystems.
Product Type:
Domestic manufacturing of mechanical and digital scales persists in Germany and Japan for precision-engineered units, while smart scale assembly concentrates in Shenzhen export corridors serving North American and European wellness markets.
- Digital Scale:LCD-display units with tare functions and gram-ounce toggle dominate mass-market retail channels. Demand clusters in United States suburban households seeking basic portion control without connectivity overhead.
- Mechanical Scale:Spring-based analog mechanisms persist in price-sensitive segments and offline retail environments across India and Southeast Asia where battery replacement logistics constrain digital adoption.
- Portion Control Scale:Compact platforms with preset serving-size alerts target weight-management clinics and bariatric surgery discharge programs in the United States and United Kingdom.
- Smart Scale:BLE-enabled load-cell instruments with companion app synchronization capture premium positioning. Export-led production from Guangdong Province supplies health-conscious consumers in Germany, Japan, and United States metro markets tracking macronutrient intake through USDA-integrated databases.
Smart Scale holds the largest share; momentum sits with Portion Control Scale as clinical prescription channels expand.
Connectivity:
Cost tier stratification runs from wired economy units through Bluetooth mid-market dominance to Wi-Fi premium positioning, with module selection directly determining retail price anchoring and replacement cycle velocity.
- Bluetooth:Low Energy 5.0 modules enable real-time smartphone synchronization with minimal power draw. United States and German consumers in preventive health programs drive unit volume through insurance-subsidized wellness bundles.
- Wi-Fi:Direct router connectivity eliminates smartphone intermediaries for multi-user households and professional kitchens. Cloud-independent operation commands premium shelf positioning in Japan and United States commercial foodservice procurement.
- USB:Tethered data transfer persists in clinical research settings and regulatory compliance environments where air-gapped systems prevent wireless interception of patient health data.
- Wired:AC-powered analog-to-digital converters serve industrial food processing and institutional cafeteria operations where electromagnetic interference from commercial kitchen equipment disrupts wireless transmission reliability.
Bluetooth dominates unit shipments; Wi-Fi gains share fastest among professional end-users.
End User:
Application intensity varies sharply across customer types, with home users driving volume through retail channels while restaurants and nutritionists generate recurring software revenue through white-label platform licensing.
- Home Users:Individual consumers purchasing through Amazon, direct-to-consumer brands, and big-box retail. Macro-tracking functionality and recipe database depth determine repurchase rates in United States and German markets.
- Chefs:Professional kitchen operators requiring NSF-certified platforms with fluid-resistant housings and rapid tare response. Demand concentrates in Michelin-rated restaurants across France, Japan, and California seeking precise ingredient ratios for menu consistency.
- Nutritionists:Registered dietitians prescribing connected scales for diabetes and renal disease management. United States hospital discharge planning programs and German statutory health insurance preventive care benefits expand institutional procurement.
- Restaurants:Chain operators implementing portion standardization to control food cost variance. Quick-service franchises in United States and United Kingdom deploy networked scales with enterprise dashboard visibility across kitchen locations.
Home Users account for the greatest volume; Nutritionists show the steepest expansion trajectory as clinical integration deepens.
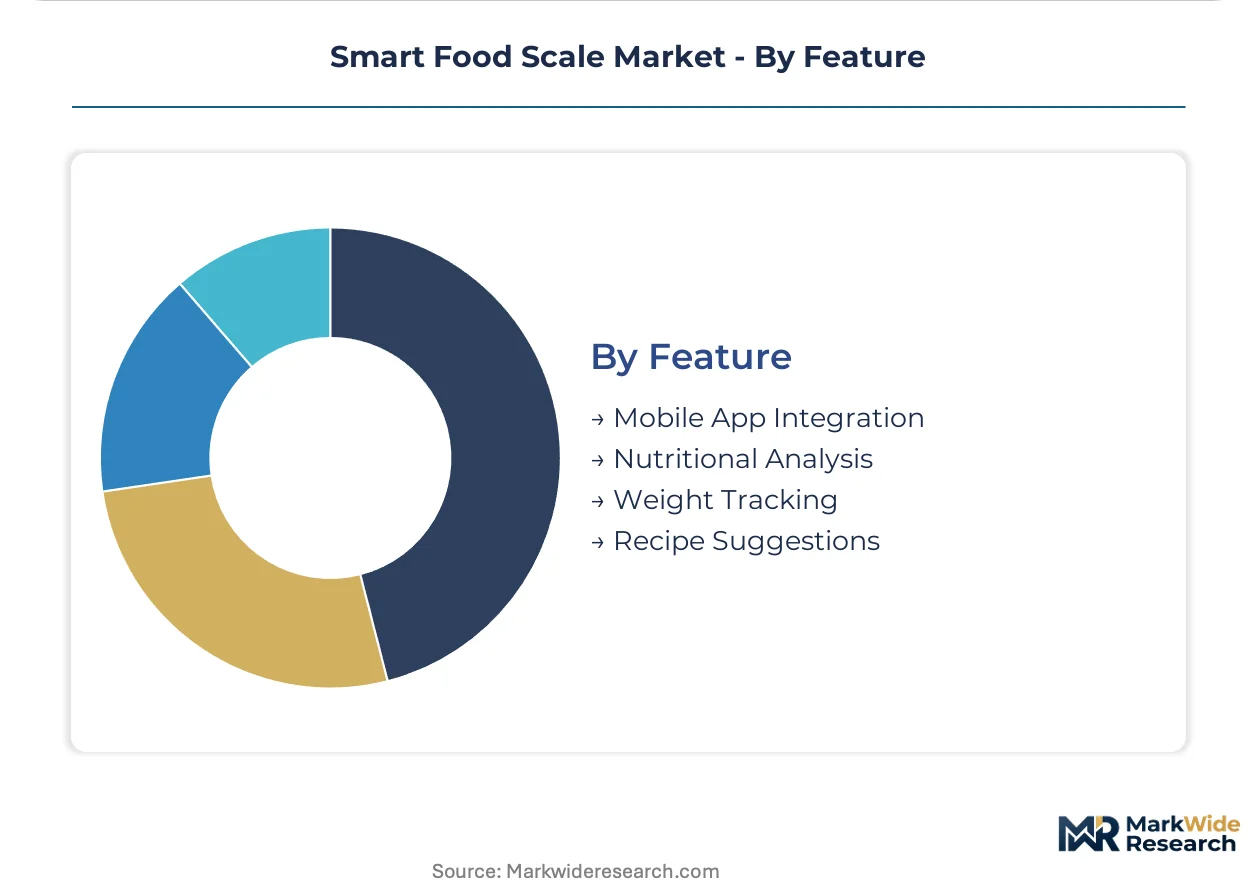
Feature:
Customer type dictates feature prioritization, with mobile app integration table stakes for home users while nutritional analysis commands premium pricing in clinical and professional segments.
- Mobile App Integration:Companion software enabling food logging, goal setting, and progress visualization. Bluetooth synchronization to iOS and Android platforms represents baseline functionality for United States and German consumer purchases.
- Nutritional Analysis:Automated macronutrient calculation against USDA, BLS, or MHLW databases. Japanese METI IoT security certification and EU AI Act transparency requirements increase compliance overhead for machine-learning food recognition features.
- Weight Tracking:Historical measurement storage and trend visualization for longitudinal monitoring. Appeals to bariatric surgery patients and weight-management clinic clients in United States and United Kingdom seeking accountability tools.
- Recipe Suggestions:Algorithmic meal recommendations based on available ingredients and dietary restrictions. Subscription-tier monetization concentrates in United States urban markets where wellness service penetration exceeds hardware attachment rates.
Mobile App Integration holds the largest share; Nutritional Analysis climbs fastest as dietitian-prescribed meal planning proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese and German metro markets where wellness technology insurance integration sustains hardware margins above Shenzhen export corridors serving North American retail channels.
United States
Preventive health program subsidies through Medicare Advantage and employer wellness benefits drive Bluetooth scale adoption in suburban households. FDA oversight of companion application nutritional claims creates compliance barriers for direct-to-consumer entrants. Silicon Valley hardware startups and Boston-area digital health clusters compete for hospital discharge planning procurement contracts.
Germany
Statutory health insurance preventive care reimbursements expand nutritionist-prescribed scale deployment in Bavaria and North Rhine-Westphalia. EU Green Deal ecodesign mandates and REACH substance restrictions shape load-cell housing material selection for manufacturers. Stuttgart precision engineering clusters supply high-resolution sensor modules to domestic wellness device assemblers.
Japan
METI IoT security certification requirements create compliance-based segmentation favoring early-certified manufacturers in Kanto and Kansai regions. Aging population diabetes management programs prescribe connected scales through municipal health services. Tokyo digital health startups integrate food recognition algorithms with MHLW database synchronization for clinical nutrition applications.
China
Shenzhen export corridors dominate smart scale assembly for North American and European wellness markets through BLE module integration and load-cell calibration. Domestic demand concentrates in tier-one cities where middle-class health consciousness tracks macronutrient intake through USDA-integrated companion applications. MIIT wireless transmission standards govern Bluetooth and Wi-Fi module certification for local market entry.
United Kingdom
NHS diabetes prevention program referrals drive portion control scale prescriptions in Greater London and Manchester clinical commissioning groups. Bariatric surgery discharge protocols in Birmingham and Glasgow hospital networks specify connected weighing instruments for home monitoring. Post-Brexit regulatory divergence from EU ecodesign requirements creates material compliance uncertainty for import-dependent retailers.
Smart Food Scale Market Competitive Landscape
Concentration sits with wellness ecosystem bundlers and Shenzhen-based manufacturing scale operators, while ethical positioning specialists occupy defensible niche segments. The vendor base spans three tiers: cross-device platform owners leveraging body composition monitor bundling, export-oriented electronics assemblers anchoring cost leadership through component integration, and certified B-Corp positioned brands commanding sustainability premiums. Strategic moves center on subscription ecosystem migration and clinical procurement channel penetration.
Among wellness ecosystem bundlers, RENPHO anchors cross-device data loyalty through body composition monitor integration. Etekcity occupies the manufacturing scale archetype with Shenzhen-based production network leverage. Greater Goods exemplifies ethical positioning through certified B-Corp status and transparent supply chain sourcing. These three patterns represent the dominant competitive configurations reshaping revenue recognition from hardware transactions toward recurring service monetization.
| Leading Market Players |
|---|
| RENPHO |
| Escali |
| Etekcity |
| NutraTrack |
| Terraillon |
| Greater Goods |
| ZWILLING |
| Smart Chef |
| HOTO |
| Others |
Pricing and Supply Chain Analysis
FDA nutritional labeling enforcement gates both supply qualification and price differentiation simultaneously, as companion application accuracy requirements separate certified database integrators from commodity hardware assemblers while METI IoT security certification in Japan creates parallel compliance premiums for cloud-independent Wi-Fi models.
Pricing Analysis
Configured-to-order pricing for clinical nutrition programs commands substantial premiums over standard retail Bluetooth units. Three-tier pricing structure across premium Wi-Fi, standard Bluetooth, and economy digital-only levels reflects certification grade and database depth. Cost compression in the Bluetooth mid-market is intensifying because load-cell sensor commoditization erodes hardware margins. Home users in suburban United States markets exhibit highest price sensitivity, while hospital discharge planning programs show lowest sensitivity due to insurance reimbursement structures.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium-ion battery supply security for portable scale manufacturers. Component sourcing concentrates in China for BLE module integration, Taiwan for microcontroller fabrication, and Japan for high-resolution strain gauge sensors. Raw material dependencies span cobalt from the Democratic Republic of Congo, lithium from Chile, and rare earth elements from China. Single-source vulnerability in semiconductor foundry capacity constrains production scaling. Distribution runs through Shenzhen export corridors serving North American and European wellness markets via Amazon and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clinical prescription channels proliferate while wellness ecosystem bundlers and manufacturing scale operators occupy divergent competitive positions, creating white-space for specialized nutrition service platforms.
For Market Incumbents: Consolidate cross-device data loyalty through deeper body composition monitor integration and preemptive METI certification investment in Japan. Threat from direct-to-consumer subscription bundlers compressing hardware transaction margins demands defensive software ecosystem deepening. Priority lever rests on backward integration into load-cell calibration algorithm development to reduce Shenzhen R&D dependency. For New Entrants and Emerging Players: White-label nutritional coaching service layers represent the most penetrable gap where incumbents under-serve registered dietitian practices. Target bariatric surgery discharge programs in United Kingdom NHS networks and German statutory insurance preventive care channels. Go-to-market angle emphasizes HIPAA-compliant cloud architecture and USDA database accuracy guarantees to differentiate from consumer-grade alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across MEMS-based strain gauge sub-segments as microfabrication matures. Long-term viability favors acquisition targets with established hospital procurement relationships and companion application AI transparency documentation for EU AI Act compliance. Signal to watch involves Japan METI IoT security certification completion rates as institutional procurement preference inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Nutrition Integration | Hospital discharge planning contracts in United States Medicare Advantage networks open institutional procurement channels beyond retail. |
| Wi-Fi Cloud-Independent Operation | Direct router connectivity captures premium positioning in Japanese commercial foodservice and multi-user household segments. |
| EU AI Act Compliance Investment | Explainability logs for machine-learning food recognition features reduce GDPR exposure and accelerate German market entry. |
| Subscription Ecosystem Migration | Monthly nutritional coaching bundling shifts revenue recognition patterns in United States urban wellness service markets. |
| MEMS Strain Gauge Miniaturization | Pocket-scale formats for travel and restaurant use cases expand addressable market beyond home kitchen deployment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, FCC equipment authorization databases, USDA food composition tables, and EU ecodesign directive implementation reports. Primary interviews incorporated connected device hardware engineers, registered dietitians prescribing clinical nutrition tools, hospital procurement committee administrators, wellness technology retail category buyers, and companion application product managers. Bottom-up unit shipment modeling triangulated against top-down consumer electronics spending allocation estimates.
Segmentation dimensions modeled span connectivity protocol, end-user application intensity, feature functionality tier, and regional regulatory cluster across the analysis window. CAGRs derived from weighted average of historical shipment velocity and projected insurance-integrated preventive health program expansion. Industry-specific forecast inputs incorporated Bluetooth Low Energy module cost curves and lithium battery supply concentration risk adjustments.
Forecasts assume regulatory continuity in FDA nutritional labeling enforcement and EU AI Act algorithm transparency requirements; material policy shifts would require re-modeling. Specific risk factors include FCC modular approval timeline extensions and REACH substance restriction amendments affecting load-cell housing materials. Practitioners should keep alternative scenarios live as METI IoT security certification standards and NHS diabetes prevention program funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Kegerator Equipment Market