
 US and Canada Hot Food Vending Machine Market | 2026-2036
US and Canada Hot Food Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Hot Food Vending Machine Market Analytics
Hospital and transportation hub procurement is broadening as institutional buyers seek round-the-clock meal access without kitchen labor. Farmer's Fridge leverages refrigerated-to-hot conversion technology to anchor its position in healthcare corridors. Crane Merchandising Systems sustains channel control through legacy vending relationships with major transit authorities. Azkoyen Group competes on European-imported engineering precision for high-traffic installations.
US and Canada hot food vending machines are self-service automated retail units engineered to store, heat, and dispense prepared meals at temperatures exceeding 140°F, employing forced-air convection or induction elements with integrated HACCP-compliant temperature logging. These systems serve commercial and institutional environments where traditional foodservice infrastructure proves cost-prohibitive or operationally impractical. Pizza vending and Asian cuisine vending categories command premium placement economics due to higher per-transaction values and extended consumption windows. Microwave cooking technology dominates installed bases for speed and energy efficiency, though induction heating segments attract replacement demand from operators seeking precise temperature control and reduced maintenance cycles.
The FDA Food Code and Health Canada's Safe Food for Canadians Regulations jointly govern hot-holding protocols, while NSF/ANSI standards certify equipment sanitation design, collectively raising capital requirements for new market entrants. USDA nutritional labeling mandates and evolving state-level sodium disclosure rules in California and New York further constrain product formulation and interface design. Stakeholders must monitor municipal zoning liberalization for sidewalk kiosks and weigh upfront smart location installation costs against labor savings from unattended operation.
Market Dynamics
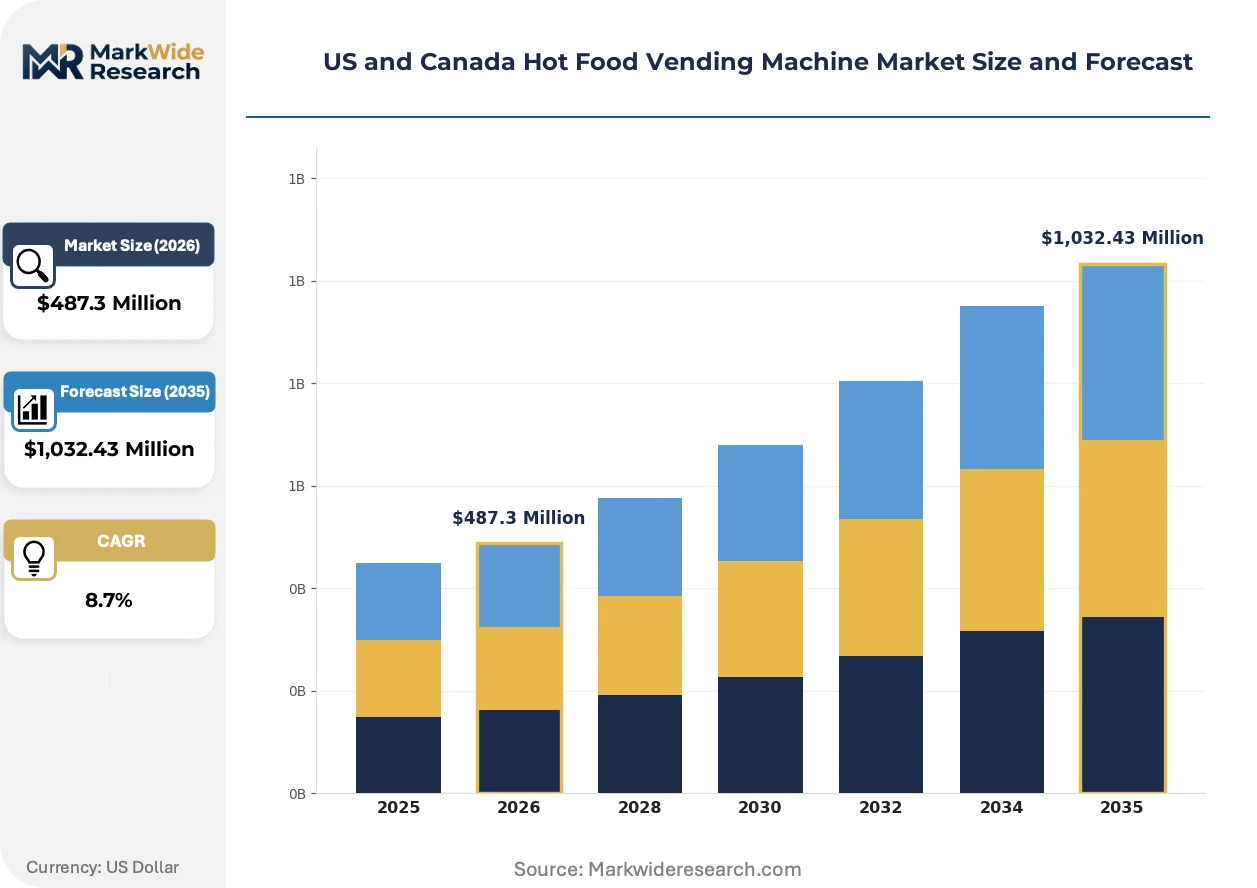
Corporate dining program expansion and FDA-Health Canada food code harmonization are compressing equipment replacement cycles while elevating capital barriers for new entrants in the US and Canada hot food vending machine market.
Growth Catalysts
- Workplace Dining Programs:Corporate campuses across the Northeast corridor from Boston to Washington DC are expanding machine deployments to reduce cafeteria labor costs and extend meal service hours.
- NSF/ANSI Sanitation Standards:Equipment certification requirements are accelerating replacement demand as operators upgrade legacy units to maintain institutional procurement eligibility.
- Induction Heating Technology:Precision temperature control systems are attracting replacement demand from operators seeking reduced maintenance cycles and HACCP compliance automation.
Market Restraints
- Stainless Steel Input Volatility:Equipment chassis and heating element fabrication faces raw material cost swings that compress manufacturer margins and deter price-sensitive buyers.
- Control System Supplier Concentration:PLC and IoT module sourcing concentrates among a handful of industrial automation vendors, creating vulnerability to semiconductor allocation disruptions.
- Substitution by Ghost Kitchens:Third-party delivery aggregation platforms and centralized dark kitchens compete for the same 24-hour meal access use cases in urban corridors.
Strategic Opportunities
- Canadian Healthcare Corridors:Provincial hospital procurement in Ontario and Quebec remains underpenetrated relative to US institutional density, offering whitespace for equipment vendors with Health Canada clearance.
- California Sodium Disclosure Rules:State-level nutritional labeling mandates are creating demand for vending interface upgrades that display real-time ingredient data and drive premium placement economics.
- Refrigerated-to-Hot Conversion:Dual-temperature systems that store chilled inventory and heat on demand are converging with RFID payment integration to unlock transportation hub deployments.
Industry Challenges
- HACCP Logging Technician Shortage:Equipment operators face scarce availability of certified food safety professionals capable of maintaining automated temperature monitoring systems and audit documentation.
- Municipal Zoning Liberalization Lag:Sidewalk kiosk permitting timelines vary unpredictably across city governments, delaying smart location installations and compressing ROI realization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Hot Food Vending Machine Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pizza Vending, Sandwich Vending, Pasta Vending, Asian Cuisine Vending Technology: Heated Display, Microwave Cooking, Induction Heating, Evaporative Cooling Installation: Indoor Placement, Outdoor Kiosks, Mobile Units, Smart Locations End User: Offices, Educational Institutions, Hospitals, Transportation Hubs |
| Companies Covered | Azkoyen Group, 365 Retail Markets, Farmer’s Fridge, ALe Bread Xpress, Inc., Ausbox Group, PizzaForno, Seaga Manufacturing Inc., FastCorp Vending, LLC, Crane Merchandising Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Hot Food Vending Machine Market Evolving Landscape
Equipment intelligence and regulatory disclosure mandates are reshaping how hot food vending machines interface with institutional buyers and end consumers across North American commercial corridors.
Induction heating elements with closed-loop temperature feedback are overtaking forced-air convection systems in high-traffic installations. Hospital and university procurement teams specify these systems for precise holding temperatures that reduce food waste liability. The technology is overtaking legacy microwave architectures by enabling operators to command premium placement fees through guaranteed thermal compliance documentation.
FDA Food Code harmonization with Health Canada's Safe Food for Canadians Regulations is tightening hot-holding protocol enforcement across cross-border supply chains. Equipment manufacturers must now engineer dual-certification temperature logging systems to serve integrated US-Canada operator networks. Pizza vending and Asian cuisine categories face the steepest compliance retrofit costs due to extended holding window requirements.
Institutional buyers are consolidating vendor relationships around full-service equipment leasing models that bundle maintenance, ingredient restocking, and compliance reporting. Single-source contracting is displacing fragmented procurement across hospital and transit authority accounts. This concentration is most visible in the Northeast US corridor, where procurement officers prioritize vendor scale over unit economics to reduce administrative overhead.
US and Canada Hot Food Vending Machine Market Segmentation
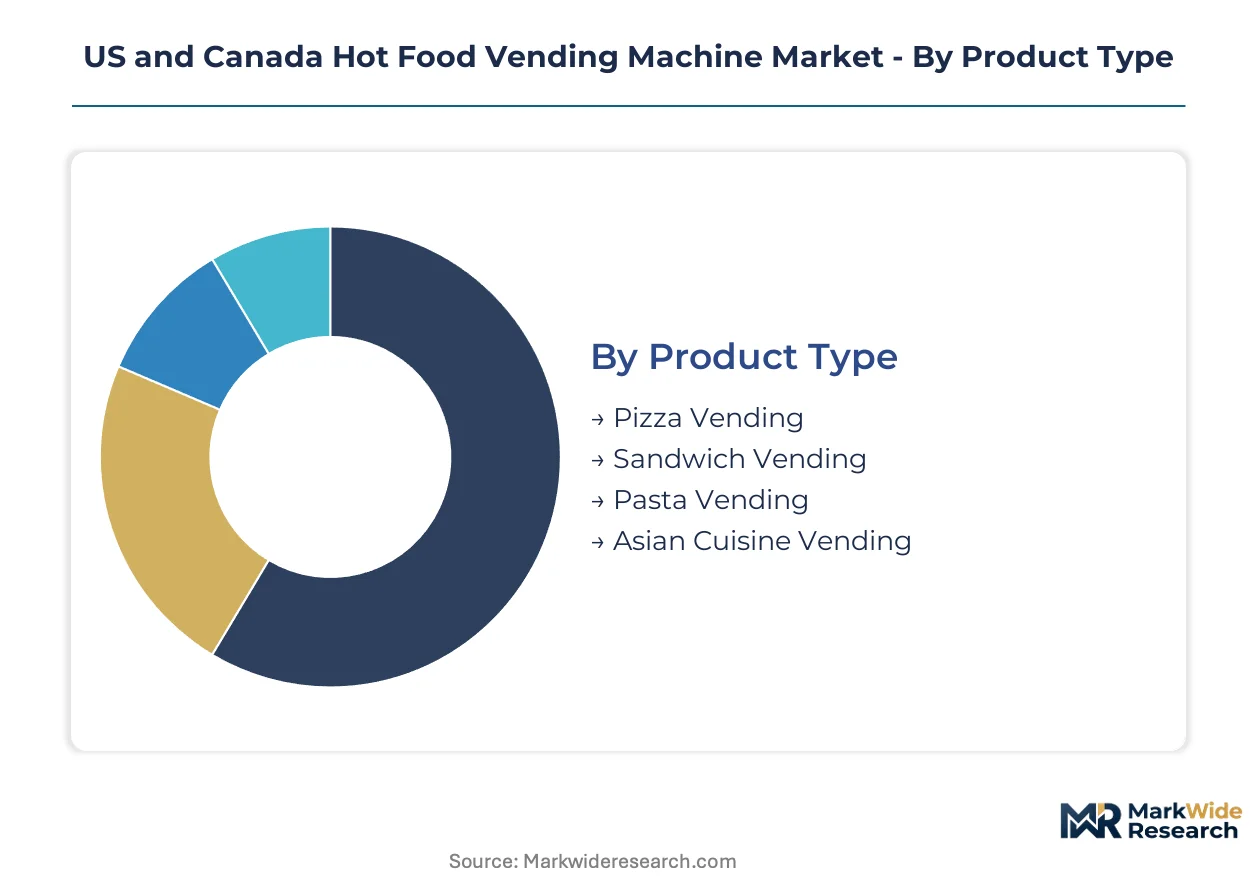
Equipment specification and placement context determine procurement priorities across the US and Canada hot food vending machine market. Buyers segment demand by meal format, heating technology, physical installation constraints, and institutional use case.
Product Type:
Premium per-transaction economics drive buyer selection within prepared meal categories.
- Pizza Vending:Specialized ovens maintain cheese integrity and crust texture through forced-air convection cycles calibrated for extended holding windows. Hospital procurement teams in Ontario and Quebec specify these systems for overnight staff meal access where cafeteria operations prove cost-prohibitive.
- Asian Cuisine Vending:Rice and noodle-based meal formats require humidity-controlled compartments to prevent starch retrogradation during storage. Transit authorities along the Northeast corridor from Boston to Washington DC deploy these units in commuter rail terminals to capture extended evening ridership with higher-margin menu options.
- Sandwich Vending:Pressed and grilled formats dominate office building lobbies seeking breakfast-to-lunch transition coverage.
- Pasta Vending:Sauce separation engineering addresses viscosity maintenance challenges in healthcare and university accounts.
Pizza vending leads on scale; Asian cuisine vending leads on momentum.
Technology:
Energy efficiency and temperature precision reshape operator upgrade cycles.
- Induction Heating:Closed-loop feedback systems deliver holding temperature variance within two degrees Fahrenheit, satisfying FDA Food Code documentation requirements with minimal technician intervention. Corporate dining programs across Massachusetts and New York specify induction architectures to reduce food waste liability and extend equipment depreciation schedules.
- Microwave Cooking:Magnetron-based systems retain installed base dominance due to lower capital cost and standardized maintenance protocols. Budget-constrained municipal transit authorities continue specifying microwave units despite higher energy draw and less precise thermal control.
- Heated Display:Forced-air convection remains prevalent in legacy hospital and university installations awaiting replacement funding.
- Evaporative Cooling:Hybrid temperature management supports dual-zone machines storing chilled beverages alongside hot entrees in transportation hub deployments.
Microwave cooking leads on scale; induction heating leads on momentum.
Installation:
Permitting complexity and infrastructure availability constrain physical deployment options.
- Smart Locations:IoT-integrated kiosks with predictive maintenance dashboards and real-time inventory tracking command premium lease rates in high-foot-traffic urban corridors. California sodium disclosure compliance requirements favor these installations for their capacity to display dynamic nutritional data through touchscreen interfaces.
- Outdoor Kiosks:Weatherized enclosures with HVAC integration serve sidewalk and plaza placements where municipal zoning liberalization is expanding. Chicago and Toronto pilot programs demonstrate viability, though permitting timelines vary unpredictably across city governments.
- Indoor Placement:Climate-controlled environments dominate existing corporate campus and hospital infrastructure.
- Mobile Units:Trailer-mounted systems serve temporary construction sites and event venues with seasonal demand patterns.
Indoor placement leads on scale; smart locations lead on momentum.
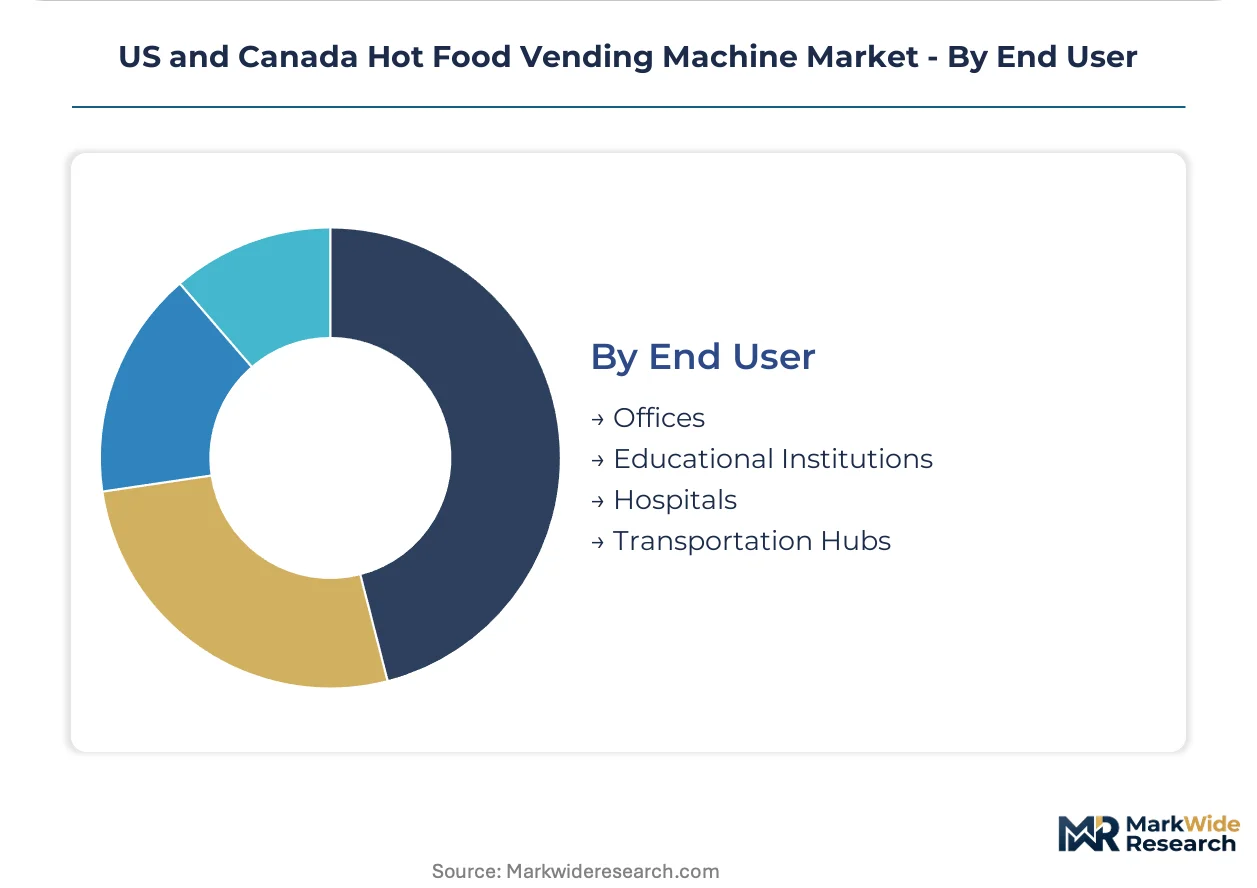
End User:
Operational hour requirements and labor cost structures determine institutional adoption patterns.
- Hospitals:Round-the-clock meal access for clinical staff and visitor populations justifies capital expenditure despite stringent Health Canada and FDA sanitation documentation requirements. Ontario provincial procurement frameworks favor vendors offering bundled maintenance and compliance reporting.
- Transportation Hubs:Extended service windows align with commuter rail and airport operational schedules where traditional foodservice labor proves uneconomical. Amtrak and major metropolitan transit authorities consolidate vendor relationships around full-service leasing models.
- Offices:Corporate campus dining programs seek cafeteria labor reduction across the Northeast corridor.
- Educational Institutions:University residence hall and library placements capture late-night study period demand.
Offices lead on scale; hospitals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment sourcing patterns as manufacturers seek cost-of-compliance advantages across provincial and state jurisdictions with divergent inspection protocols and certification timelines.
Northeast Corridor
Corporate campus dining programs from Boston to Washington DC are accelerating machine deployments to reduce cafeteria labor expenditures. FDA Food Code enforcement in Massachusetts and New York elevates capital requirements for temperature logging systems. The I-95 metropolitan chain anchors procurement concentration as transit authorities consolidate vendor relationships around full-service leasing models.
Ontario
Provincial hospital procurement frameworks favor bundled maintenance and compliance reporting vendors with Health Canada clearance. The Safe Food for Canadians Regulations tighten hot-holding documentation requirements for cross-border operator networks. Toronto and Ottawa healthcare corridors demonstrate underpenetrated whitespace relative to US institutional density.
Quebec
French-language interface mandates and provincial nutrition labeling standards create specialized equipment specification demand. Montreal transit hubs pilot refrigerated-to-hot conversion systems with RFID payment integration. Provincial procurement officers prioritize vendor scale over unit economics to reduce administrative overhead.
California
State-level sodium disclosure rules in advance of federal mandates drive vending interface upgrade cycles for real-time ingredient data display. Los Angeles and San Francisco municipal zoning liberalization for sidewalk kiosks proceeds unevenly across city governments. Smart location installations command premium lease rates for predictive maintenance dashboard capabilities.
Texas
Energy sector workplace dining programs in Houston and Dallas-Fort Worth extend meal service hours through automated retail deployment. Lower municipal permitting friction relative to coastal jurisdictions accelerates ROI realization schedules. Dallas transit authority procurement mirrors Northeast corridor consolidation patterns with full-service leasing preference.
US and Canada Hot Food Vending Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring integrated service providers while transportation hubs tolerate fragmented equipment-only supply. The vendor base organizes around three archetypes: European-imported engineering specialists, North American full-service leasing platforms, and refrigerated-to-hot conversion technology developers. Consolidation pressure concentrates in the Northeast corridor where procurement officers reduce vendor counts to streamline compliance administration. Competitive moves center on strategic partnerships with transit authorities and backward integration into temperature control module fabrication.
Within the European-imported engineering tier, Azkoyen Group occupies a position exemplifying precision fabrication for high-traffic installations. Among North American full-service platforms, Crane Merchandising Systems anchors legacy vending relationships with major transit authorities. Farmer's Fridge represents the refrigerated-to-hot conversion archetype, leveraging dual-temperature technology to secure placement in healthcare corridors. These three entities collectively illustrate the strategic positioning vectors—engineering heritage, institutional relationship depth, and product format innovation—that define competitive differentiation in this market.
| Leading Market Players |
|---|
| Azkoyen Group |
| 365 Retail Markets |
| Farmer's Fridge |
| ALe Bread Xpress, Inc. |
| Ausbox Group |
| PizzaForno |
| Seaga Manufacturing Inc. |
| FastCorp Vending, LLC |
| Crane Merchandising Systems |
| Others |
Value Network & Pricing Analysis
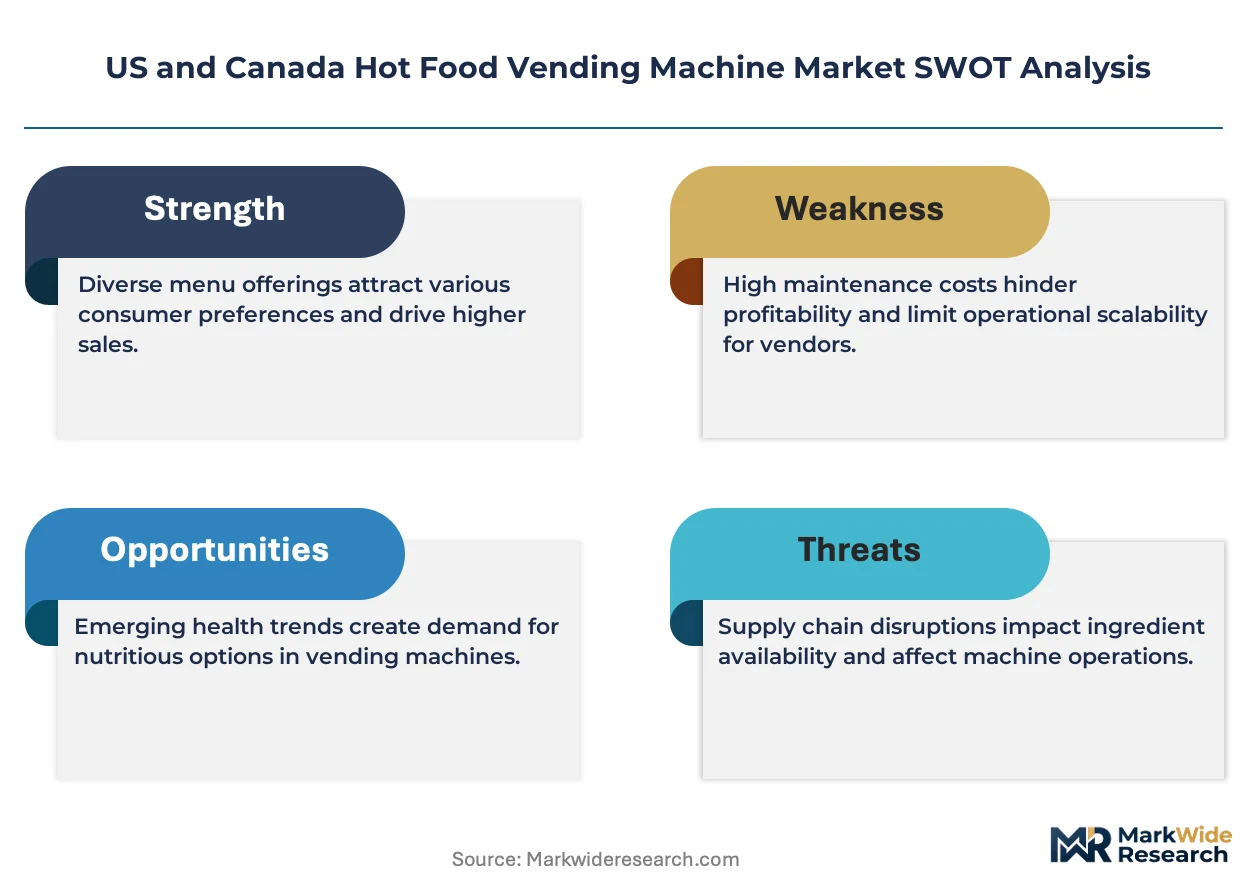
FDA-Health Canada food code harmonization gates qualified supply and premium-tier pricing access by mandating dual-certification temperature logging systems that only established vendors can engineer profitably.
Pricing Analysis
Distributor margins compress as transit authorities consolidate vendor relationships around full-service leasing models that bundle maintenance and compliance reporting. Pricing stratifies across premium induction-heating units, standard microwave architectures, and economy-tier heated display systems. Cost compression in the economy tier intensifies because stainless steel input volatility squeezes manufacturer margins. Municipal transit authorities exhibit highest price sensitivity; hospital procurement teams in Ontario and Quebec demonstrate lowest sensitivity due to bundled service requirements.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification for PLC and IoT control modules, forcing equipment manufacturers to qualify secondary vendors from Mexico and Taiwan alongside primary German and Japanese suppliers. Chassis fabrication draws from Canadian and US steel mills, while induction heating elements source from South Korean and Chinese component specialists. Single-source vulnerability concentrates in semiconductor allocation disruptions affecting IoT module availability. Distribution runs through direct OEM relationships with transit authorities and GPO-aggregated hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on labor substitution economics as corporate dining programs replace cafeteria infrastructure with unattended automated retail.
For Market Incumbents: Acquire temperature control module fabrication capabilities to reduce supplier concentration risk and capture value from induction heating upgrade cycles. Consolidate vendor relationships with major transit authorities before ghost kitchen delivery platforms capture 24-hour meal access share. Defend position by securing Health Canada clearance for Ontario and Quebec hospital corridors where procurement frameworks favor bundled service providers. For New Entrants and Emerging Players: California sodium disclosure rules in advance of federal mandates open a window for smart location interface developers with real-time nutritional data display capabilities. Target underpenetrated Canadian healthcare corridors where provincial procurement favors vendors offering compliance reporting bundles. Pursue refrigerated-to-hot conversion technology partnerships with Farmer's Fridge to anchor transportation hub deployments in Montreal and Toronto pilot programs. For Investors and Strategic Acquirers: Roll-up economics work for regional full-service leasing platforms because institutional procurement officers prioritize vendor scale over unit economics to reduce administrative overhead. Long-term viability hinges on consolidation of fragmented maintenance and restocking operations across the Northeast corridor. Monitor municipal zoning liberalization velocity in Chicago, Toronto, Los Angeles, and San Francisco as inflection indicator for smart location ROI realization schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature Control Modules | Reduces PLC supplier concentration vulnerability and captures margin from induction heating replacement demand. |
| Health Canada Dual-Certification Investment | Unlocks Ontario and Quebec hospital procurement frameworks that favor bundled compliance reporting vendors. |
| Smart Location Interface Upgrade | Captures California sodium disclosure compliance demand for real-time nutritional data display capabilities. |
| Transit Authority Full-Service Leasing Consolidation | Mirrors Northeast corridor procurement patterns where Amtrak and municipal authorities reduce vendor counts. |
| Refrigerated-to-Hot Conversion Partnership | Enables RFID-integrated transportation hub deployments in Montreal and Toronto pilot programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement officers, transit authority facilities managers, corporate dining program directors, and vending equipment maintenance technicians with secondary validation against FDA Food Code filings, Health Canada Safe Food for Canadians Regulations guidance documents, NSF/ANSI certification databases, and municipal zoning ordinance records. Bottom-up equipment deployment counts triangulated against top-down market sizing from institutional foodservice expenditure data.
Segment-weighting across the analysis window applied product type, heating technology, installation format, and end-use institutional category dimensions to derive volume and value outputs. CAGRs were computed from fitted growth curves incorporating equipment replacement cycle acceleration from regulatory harmonization, labor cost substitution economics in corporate campuses, and penetration rate assumptions for induction heating technology adoption.
Revisions become necessary when FDA-Health Canada regulatory divergence materializes, stainless steel input volatility exceeds historical bands, or ghost kitchen delivery platform density in urban corridors accelerates beyond substitution thresholds. Deviation in municipal zoning liberalization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Smart Cooker Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Scroll Chiller Market