
 Mobile Bottling Line Market | 2026-2036
Mobile Bottling Line Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Bottling Line Market Foresight
Capital-intensity divergence between integrated machinery builders and modular service providers is reorganizing competitive dynamics across the mobile bottling landscape. Krones AG leverages its deep engineering heritage in high-throughput systems to anchor premium positioning among contract packers seeking reliability. IC Filling Systems specializes in compact, trailer-mounted configurations that dominate small-batch beverage operations across Southern Europe. Zhangjiagang King Machine Co. Ltd competes aggressively on configurable manual-to-automatic gradations, sustaining cost advantages that resonate with emerging-market distributors.
A mobile bottling line constitutes a transportable, self-contained packaging system—typically mounted on trailer or skid platforms—engineered to execute rinsing, filling, capping, and labeling sequences at throughputs ranging from 1,000 to 12,000 bottles per hour depending on configuration and liquid viscosity. Its primary commercial purpose lies in delivering on-demand packaging capacity to producers lacking permanent bottling infrastructure or facing seasonal volume spikes. Fully automatic systems capture the dominant margin pool due to labor substitution and throughput consistency, while vacuum filling technology leads adoption in oxygen-sensitive categories such as wine and craft spirits where preservation of organoleptic properties commands priority. Semi-automatic configurations retain structural relevance among contract packers serving fragmented regional beverage brands with variable batch sizes.
The EU F-Gas Regulation and CE marking requirements shape equipment design standards across European mobile bottling deployments, compelling refrigerant system upgrades and pressure-vessel certifications that filter smaller fabricators from commercial viability. In the United States, FDA cGMP standards and OSHA workplace safety protocols govern on-site mobile operations, particularly in pharmaceutical and cosmetics applications where cross-contamination controls prove decisive. Stakeholders must monitor evolving PFAS restrictions in packaging materials and accelerating state-level deposit-return schemes, as these regulatory trajectories will determine which filling technologies and bottle-handling configurations retain compliance headroom.
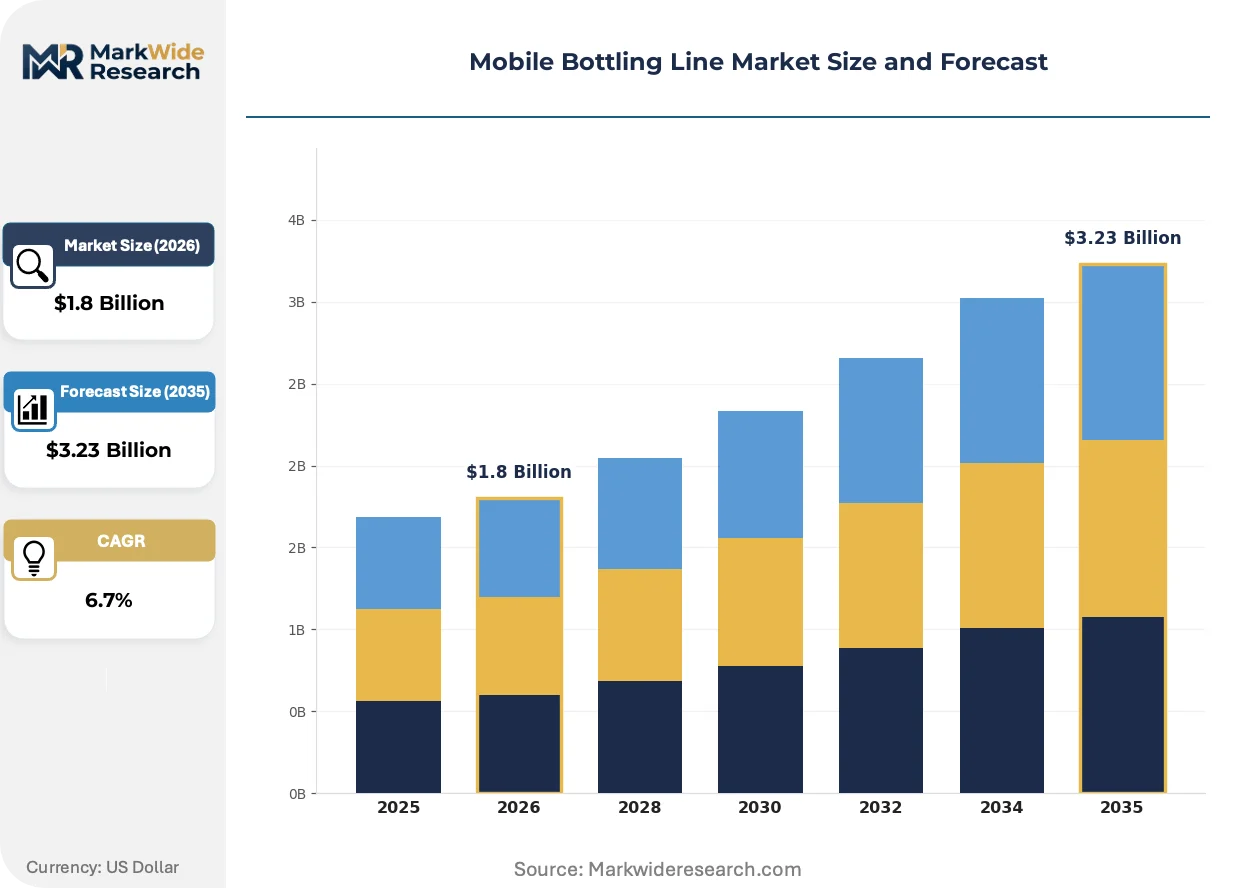
Market Dynamics
Capital-intensity divergence between integrated machinery builders and modular service providers is reorganizing competitive dynamics across the mobile bottling landscape. Craft beverage producers are driving adoption of mobile bottling services as they seek flexible production without fixed-line capital expenditure. The EU F-Gas Regulation is pushing equipment manufacturers toward lower-GWP refrigerant systems in filling operations.
Growth Catalysts
- Craft Beverage Outsourcing:Mid-size wineries and regional breweries in Germany increasingly outsource bottling to mobile operators, eliminating fixed infrastructure costs while maintaining seasonal flexibility.
- EU F-Gas Regulation:Mandatory phase-down of high-GWP refrigerants under the EU F-Gas Regulation is accelerating equipment refresh cycles among contract packers seeking compliant filling systems.
- Vacuum Filling Technology:Oxygen-sensitive categories such as wine and craft spirits prioritize vacuum filling technology to preserve organoleptic properties, creating premium service tiers among mobile operators.
Market Restraints
- Stainless Steel Input Volatility:Trailer-mounted systems rely heavily on food-grade stainless steel for pressure vessels and piping, exposing fabricators to commodity price swings that compress margin predictability.
- CE Marking Certification Burden:Pressure-vessel certifications and CE marking requirements filter smaller fabricators from commercial viability in European deployments, consolidating supply among engineered-systems specialists.
- Fixed-Line Substitution Threat:Large beverage conglomerates with captive bottling infrastructure represent a persistent substitute, limiting mobile service addressability above 12,000 bottles per hour throughput thresholds.
Strategic Opportunities
- Emerging Market Distributors:Configurable manual-to-automatic gradations resonate with distributors in developing economies lacking technical service networks for complex fixed-line maintenance.
- Pharmaceutical Cosmetics Applications:FDA cGMP standards and cross-contamination controls create a defensible premium segment for mobile operators serving pharmaceutical and cosmetics producers with validated cleaning protocols.
- State-Level Deposit-Return Schemes:Accelerating deposit-return legislation across multiple US states is driving demand for bottle-handling configurations compatible with returnable glass formats.
Industry Challenges
- Mechatronics Skill Scarcity:Mobile bottling operations require technicians proficient in both pneumatic filling mechanics and trailer-mounted electrical systems, a hybrid skill set concentrated among legacy dairy and brewing equipment specialists.
- Legacy System Integration Friction:Contract packers serving fragmented regional beverage brands face technical complexity when interfacing mobile lines with existing ERP and batch-tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Bottling Line Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Custom Application: Beverages, Chemicals, Pharmaceuticals, Cosmetics End User: Manufacturers, Contract Packers, Distributors, Retailers Technology: Vacuum Filling, Gravity Filling, Pressure Filling, Cold Filling |
| Companies Covered | Krones AG, IC Filling Systems, Tetra Laval Group, ProMach, Barry-Wehmiller Group, Coesia S.p.A., Optima Packaging Group GmbH, Zhangjiagang King Machine Co. Ltd, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Bottling Line Market Shifts & Advancements
Automation architecture is decomposing traditional throughput hierarchies in mobile bottling. Trailer-mounted systems now integrate distributed control modules that enable remote diagnostics and predictive maintenance, compressing the capability gap between semi-automatic and fully automatic configurations.
Modular filling platforms are decomposing the capital barrier between entry-level and premium service tiers. Compact, trailer-mounted configurations from Southern European specialists now incorporate servo-driven capping and in-line labeling previously reserved for fixed-line installations. Small-batch beverage operations adopt these systems at accelerated pace, enabling contract packers to serve variable batch sizes without throughput penalty.
REACH chemical restrictions and evolving PFAS limitations in packaging materials are reshaping equipment specification requirements across European mobile bottling deployments. The ECHA regulatory trajectory is compelling manufacturers to validate seal materials and lubricant chemistries for compliance headroom. Wine and craft spirits segments, where organoleptic preservation commands priority, are most affected and are responding with accelerated qualification of fluorine-free alternatives.
Service unbundling is fragmenting traditional procurement relationships between mobile bottling operators and beverage producers. Large regional brands now separate equipment mobilization, operational labor, and post-run sanitization into discrete purchase decisions. This pattern is most visible in Germany, where mid-size wineries negotiate line-time contracts independently from cleaning validation services, compressing operator margins while expanding addressable customer base.
Mobile Bottling Line Market Segmentation
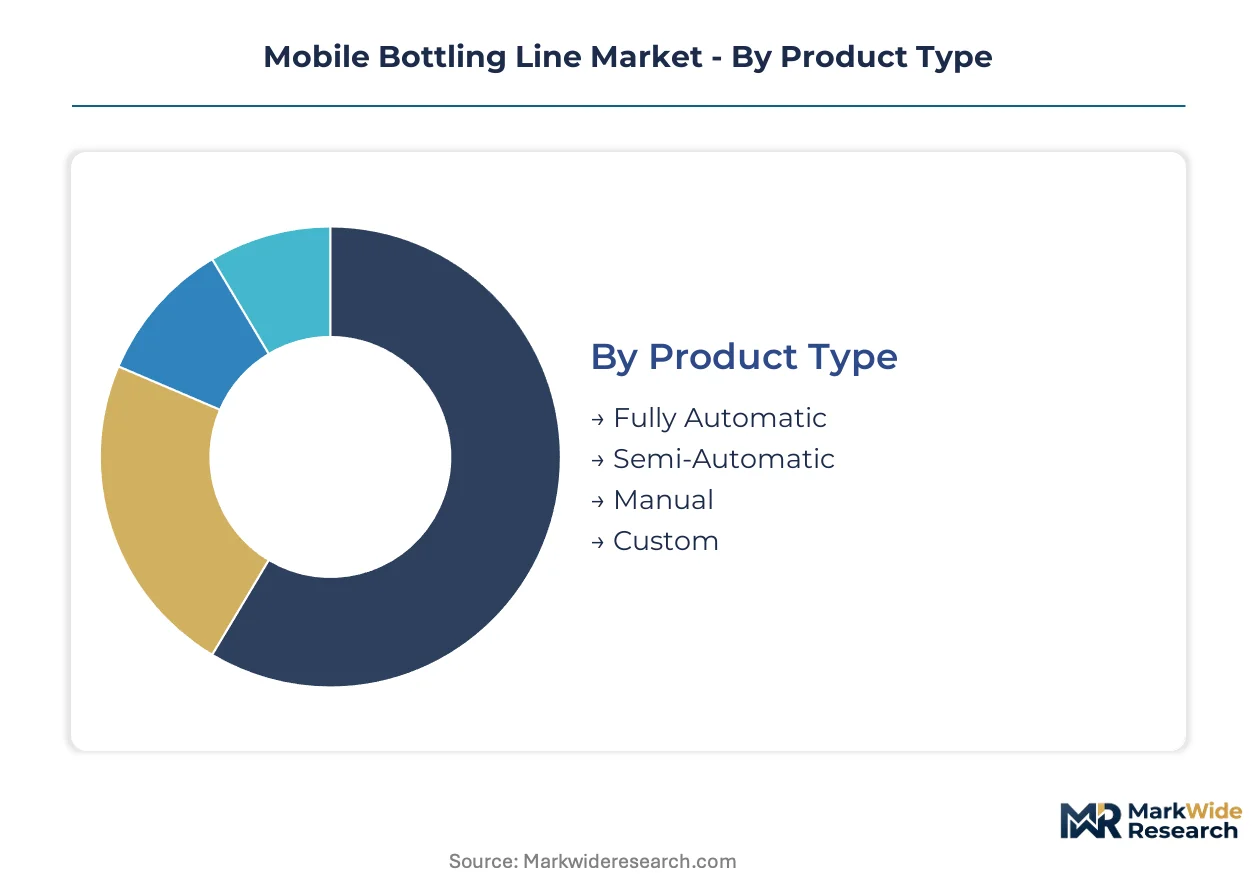
Mobile bottling line configurations fragment across four distinct dimensions, each shaping procurement decisions and operator economics differently. Product type and technology choices determine capital intensity and throughput ceilings, while application and end-user segmentation governs service packaging and compliance requirements.
Product Type:
Premium margin pools concentrate in configurations that minimize labor dependency and maximize throughput consistency for high-volume contract packers.
- Fully Automatic:Systems integrate servo-driven capping, in-line labeling, and distributed control modules enabling remote diagnostics. Demand clusters among German mid-size wineries and regional breweries outsourcing seasonal bottling runs to mobile operators seeking labor substitution.
- Semi-Automatic:Configurations retain manual loading stations while automating filling and capping sequences. Contract packers serving fragmented Southern European beverage brands with variable batch sizes sustain this segment's relevance despite throughput penalties.
- Manual:Entry-level skid-mounted units target emerging-market distributors lacking technical service networks for complex system maintenance.
- Custom:Purpose-built trailer configurations accommodate atypical bottle geometries or specialty liquid viscosities for craft spirits producers.
The dominant share belongs to Fully Automatic, while Semi-Automatic is closing the gap fastest as modular platforms compress capability differentials.
Application:
Volume concentration tracks liquid sensitivity to oxygen exposure and regulatory stringency rather than absolute bottle throughput.
- Beverages:Wine and craft spirits producers prioritize vacuum filling technology to preserve organoleptic properties, creating defensible premium service tiers. German wineries and regional breweries drive outsourcing adoption to eliminate fixed infrastructure costs.
- Pharmaceuticals:FDA cGMP standards and cross-contamination controls govern on-site mobile operations. Validated cleaning protocols create barrier-to-entry advantages for operators serving this segment.
- Chemicals:Pressure-vessel certifications and material compatibility requirements filter smaller fabricators from commercial viability in European deployments.
- Cosmetics:Batch-size flexibility and rapid changeover capabilities attract contract packers serving premium skincare brands with frequent SKU rotations.
Beverages command the largest addressable base, though Pharmaceuticals delivers the steepest margin expansion trajectory due to compliance premiums.
End User:
Procurement authority and technical sophistication determine service unbundling patterns and contract structure complexity.
- Contract Packers:German operators increasingly separate equipment mobilization, operational labor, and post-run sanitization into discrete purchase decisions, compressing margins while expanding customer base.
- Manufacturers:Mid-size wineries lacking permanent bottling infrastructure represent core demand for seasonal flexibility without capital commitment.
- Distributors:Configurable manual-to-automatic gradations resonate in developing economies where fixed-line maintenance networks remain underdeveloped.
- Retailers:Private-label beverage programs drive spot demand for mobile capacity during promotional volume spikes.
Contract Packers account for the dominant procurement volume, while Manufacturers are gaining share fastest as craft beverage outsourcing accelerates.
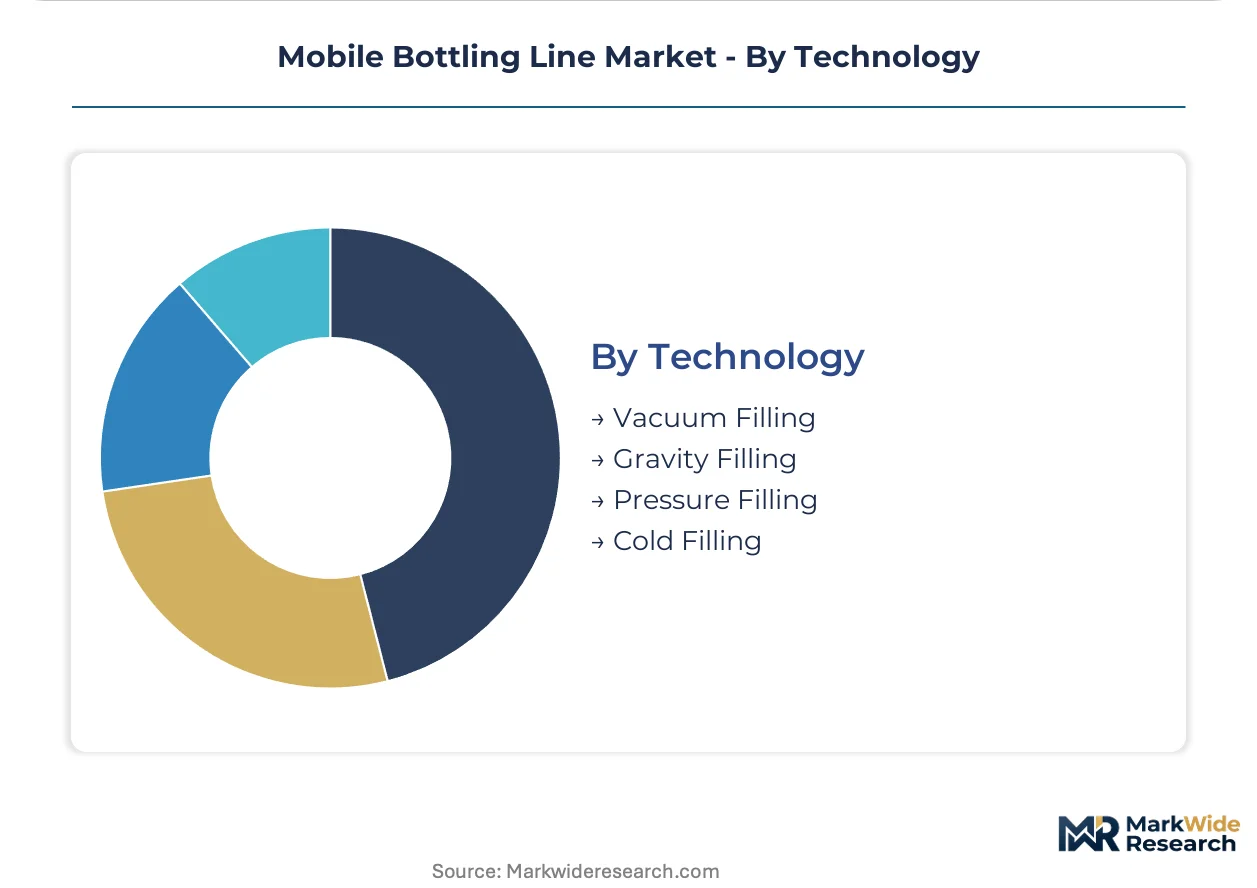
Technology:
Adoption patterns reflect liquid-specific preservation requirements and energy efficiency trade-offs in trailer-mounted configurations.
- Vacuum Filling:Oxygen exclusion mechanics protect wine and craft spirits from oxidation during bottling. EU F-Gas Regulation compliance for associated refrigeration systems adds certification burden.
- Gravity Filling:Low-shear mechanics suit viscous liquids and foam-sensitive formulations in cosmetics applications.
- Pressure Filling:Carbonated beverage compatibility drives adoption among contract packers serving regional brewery clients.
- Cold Filling:Aseptic pathways for sensitive pharmaceuticals require validated temperature control and cleanroom-equivalent trailer configurations.
Vacuum Filling holds the leading position, while Cold Filling is climbing the fastest as pharmaceutical applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity, absorbing premium mobile bottling rates for vacuum filling precision, while emerging-market distributors in Southeast Asia exhibit acute sensitivity to capital outlay, driving demand for manual-to-automatic gradations.
Germany
Mid-size wineries in the Rhineland-Palatinate and Baden-Württemberg regions outsource seasonal bottling to mobile operators, eliminating fixed infrastructure costs while maintaining organoleptic quality standards. The EU F-Gas Regulation mandates lower-GWP refrigerant systems, accelerating equipment refresh cycles among contract packers. Stuttgart anchors engineering excellence, where trailer-mounted system fabricators cluster around precision mechatronics supply chains.
United States
Craft spirits producers in California and Oregon deploy mobile vacuum filling for small-batch releases, prioritizing oxygen exclusion over throughput speed. FDA cGMP standards govern pharmaceutical and cosmetics applications, where cross-contamination controls create compliance premiums. The Pacific Northwest hosts the densest concentration of specialty mobile operators serving wine and distilled spirits segments.
Italy
Prosecco and regional wine producers in Veneto and Friuli-Venezia Giulia leverage mobile bottling for harvest-season surge capacity, avoiding capital lock-in for cyclical demand. CE marking requirements and pressure-vessel certifications filter smaller fabricators from commercial viability. Conegliano-Valdobbiadene represents the epicenter of mobile service demand, where Prosecco DOCG bottling runs concentrate during autumn harvest windows.
China
Regional beverage distributors in Jiangsu and Zhejiang provinces adopt configurable manual-to-automatic systems, compensating for underdeveloped fixed-line maintenance networks. National food safety standards under SAMR govern filling equipment sanitation protocols. Zhangjiagang anchors fabrication capacity, where domestic machinery builders compete on cost-adjustable configurations for emerging-market price points.
France
Champagne houses and Loire Valley wineries utilize mobile bottling for limited-edition cuvées and experimental formats unsuited to permanent line investment. REACH chemical restrictions and evolving PFAS limitations reshape seal material specifications for European deployments. Reims and Tours host specialized mobile operators serving AOC-protected wine categories with validated cleaning protocols.
Mobile Bottling Line Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure in mobile bottling systems. The upper tier comprises diversified packaging machinery conglomerates with cross-category engineering platforms, while the specialist tier focuses on trailer-mounted configurations for craft beverage segments. Three archetypes dominate: integrated systems builders with heritage in high-throughput fixed lines, compact mobile specialists optimizing for small-batch flexibility, and configurable fabricators serving price-sensitive emerging markets. Competitive moves concentrate on modular platform development and regional service network expansion.
Among European-integrated specialists, Krones AG exemplifies the premium engineering archetype, leveraging deep heritage in high-throughput systems to anchor reliability positioning among contract packers. IC Filling Systems occupies the compact mobile specialist tier, with trailer-mounted configurations dominating small-batch operations across Southern Europe. Zhangjiagang King Machine Co. Ltd represents the configurable emerging-market archetype, competing on manual-to-automatic gradations that resonate with distributors lacking technical service infrastructure.
| Leading Market Players |
|---|
| Krones AG |
| IC Filling Systems |
| Tetra Laval Group |
| ProMach |
| Barry-Wehmiller Group |
| Coesia S.p.A. |
| Optima Packaging Group GmbH |
| Zhangjiagang King Machine Co. Ltd |
| Syntegon Technology GmbH |
| Others |
Supply & Pricing Matrix
Ninety-day stainless steel inventory cycles at trailer-mounted system fabricators compress pricing power during commodity spikes, concentrating margin pressure on operators dependent on food-grade pressure vessel inputs while amplifying the cost advantage of vertically integrated machinery builders with captive metallurgical supply.
Pricing Analysis
After-sales service contracts and spare parts revenue dominate lifetime value capture among mobile bottling operators, with three-tier pricing structure across premium, standard, and economy levels separating CE-marked vacuum filling systems from manual skid configurations. Price differentiation rests on certification grade and geographic delivery cost, with German contract packers absorbing premium rates for organoleptic preservation capabilities while Southeast Asian distributors drive cost compression in entry-level segments. Pricing pressure stems from stainless steel input volatility, eroding margin predictability for fabricators without backward integration into metallurgical supply.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for servo-driven control modules and precision filling heads, stretching lead times for trailer-mounted system assembly. Manufacturing gravity centers on Germany, Italy, and China, with Zhangjiagang anchoring fabrication capacity for configurable manual-to-automatic gradations. Raw material dependencies span food-grade stainless steel, pneumatic valve assemblies, and refrigerant systems compliant with EU F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in precision mechatronics components sourced from Stuttgart engineering clusters. Distribution runs through regional contract packers serving fragmented beverage brands with seasonal mobilization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile bottling services constitute a defensive-moat business where regulatory entrenchment around CE marking and FDA cGMP validation creates switching costs that cement incumbent positions against price-based disruption.
For Market Incumbents: Fortify market position by deepening backward integration into stainless steel pressure vessel production, insulating margin structures from commodity volatility while accelerating equipment refresh cycles ahead of EU F-Gas Regulation deadlines. Expand regional service networks in Rhineland-Palatinate and Baden-Württemberg to capture outsourcing demand from mid-size wineries eliminating fixed infrastructure costs. For New Entrants and Emerging Players: CE marking fast-track programs for compact trailer-mounted configurations offer the most penetrable entry vector, targeting Southern European contract packers serving variable-batch Prosecco and regional wine producers with modular servo-driven platforms. Prioritize vacuum filling technology specialization to command premium positioning in oxygen-sensitive craft spirits segments where organoleptic preservation justifies rate absorption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across semi-automatic configurations as distributed control modules compress capability differentials with fully automatic systems, extending viable investment horizons for modular platform specialists. Target acquisition candidates with validated pharmaceutical cleaning protocols and established FDA cGMP compliance track records. Monitor stainless steel price trajectories as the decisive inflection signal for margin expansion versus compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Upgrade | EU F-Gas Regulation compliance secures market access across German and Italian contract packer networks. |
| Service Network Expansion | Regional mobilization capabilities in harvest-concentrated zones capture seasonal outsourcing demand from wineries. |
| Pharmaceutical Validation Investment | FDA cGMP protocols create defensible premium tiers with cross-contamination control barriers. |
| Modular Platform Development | Configurable manual-to-automatic gradations address emerging-market distributor price sensitivity. |
| Backward Integration | In-house stainless steel vessel production insulates margins from commodity input volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mobile bottling line fabricators, contract packer operations directors, winery production managers, and beverage distributor procurement leads. Secondary validation drew from EU F-Gas Regulation implementation filings, CE marking certification databases, FDA cGMP guidance documents, and stainless steel commodity trade data. Bottom-up equipment shipment tallies and top-down addressable market sizing were triangulated to anchor volume estimates.
Across the analysis window, forecasts model product type segmentation across fully automatic, semi-automatic, manual, and custom configurations; application splits between beverages, pharmaceuticals, chemicals, and cosmetics; and technology differentiation spanning vacuum, gravity, pressure, and cold filling modalities. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance-driven refresh demand, with craft beverage outsourcing intensity and deposit-return scheme adoption serving as demand-side calibration inputs.
Underlying assumptions cover stable EU regulatory enforcement continuity and stainless steel price band persistence, with deviation risk concentrated in accelerated PFAS packaging restrictions and state-level deposit-return scheme proliferation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Food Ultrasound Market