
 Global Electrodialysis Equipment Market | 2026-2036
Global Electrodialysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrodialysis Equipment Market Analysis
OEM-direct procurement channels for large-scale membrane stacks is rewriting how electrodialysis systems reach municipal and industrial buyers. Evoqua Water Technologies LLC leverages its integrated service network to sustain recurring revenue from membrane replacement cycles. PCCell GmbH anchors European demand through specialized batch system engineering for pharmaceutical-grade water. MEGA Group competes on electrode manufacturing scale across Central European industrial clusters.
Electrodialysis equipment employs ion-selective membranes and electrical potential gradients to separate dissolved ions from aqueous solutions, typically operating at cell voltages of 1-2 volts per membrane pair with current densities reaching 20-40 mA per square centimeter for brackish water desalination. The primary commercial purpose centers on producing potable water from saline sources and recovering valuable salts from industrial process streams. Continuous systems dominate installed capacity for large municipal desalination while modular systems capture fastest-growing demand from distributed industrial water recycling sites. Ion exchange membranes concentrate margin pools due to replacement cycle economics and material specialization barriers.
The EPA's Safe Drinking Water Act enforcement and China's MEE discharge standards for industrial wastewater are tightening membrane performance certification requirements across both markets. The EU F-Gas Regulation and REACH chemical restrictions are reshaping membrane polymer formulations and electrode material selection for European equipment suppliers. Stakeholders must monitor evolving zero-liquid-discharge mandates and membrane durability standards to align product development with tightening compliance thresholds.
Market Dynamics
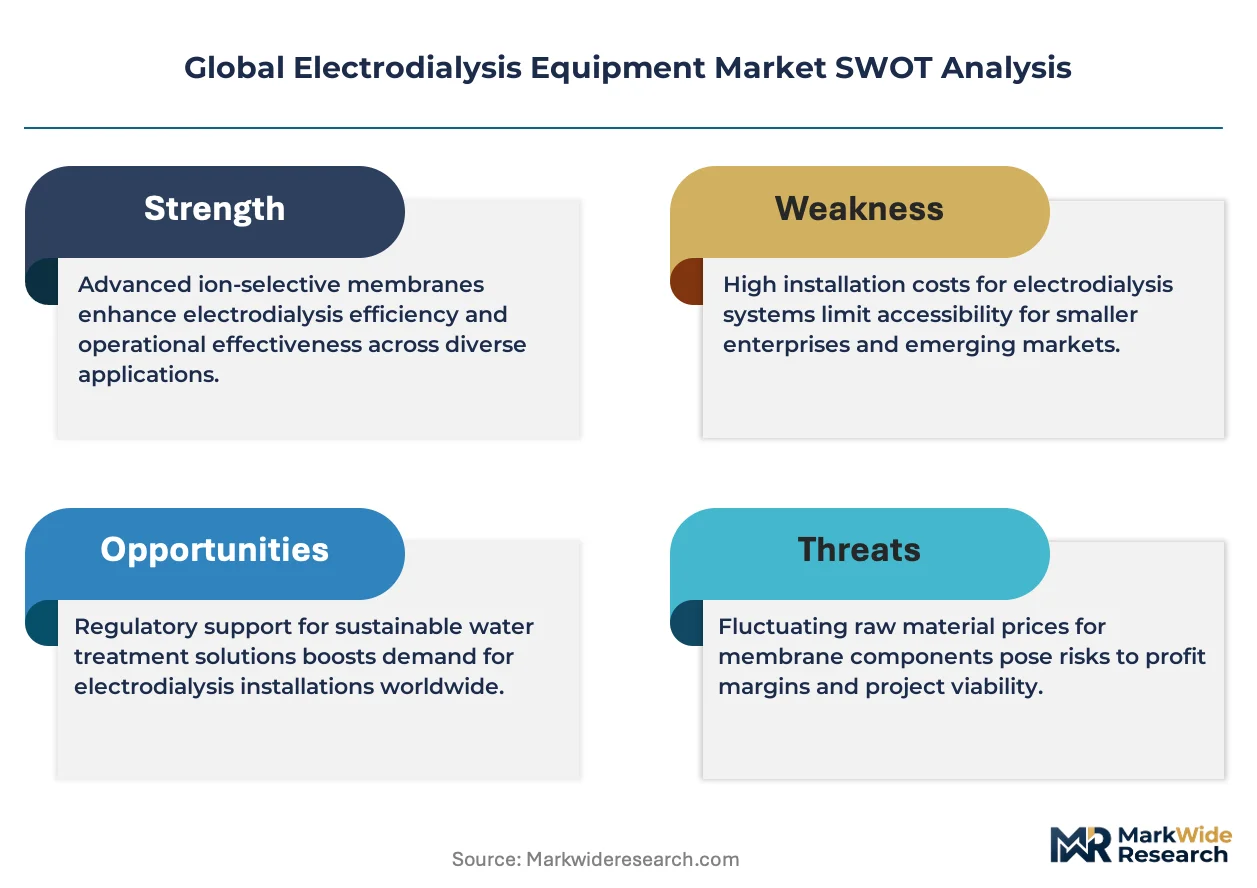
Zero-liquid-discharge mandates in coastal industrial zones are compressing membrane replacement cycles and forcing equipment suppliers to engineer higher-concentration tolerance into stack designs.
Growth Catalysts
- China's MEE discharge standards:Industrial clusters in Shandong and Jiangsu provinces face tightening effluent limits, accelerating electrodialysis adoption for salt recovery and water reuse in chemical processing.
- Brackish water desalination:Municipal utilities in Germany and Japan are expanding electrodialysis capacity as energy costs make thermal desalination uneconomical for inland saline aquifers.
- Perfluorinated membrane alternatives:Research programs in the Netherlands and South Korea are commercializing hydrocarbon-based ion-exchange membranes that bypass EU F-Gas Regulation restrictions on fluoropolymer production.
Market Restraints
- Ion-exchange membrane supply concentration:Japanese and German specialty chemical producers control over 70% of high-performance cation and anion membrane supply, creating procurement bottlenecks for stack assemblers outside these geographies.
- Electrode material cost volatility:Ruthenium oxide and iridium oxide coatings for dimensionally stable anodes fluctuate with precious metal markets, compressing margins on replacement electrode orders.
- Reverse osmosis substitution in high-salinity applications:Seawater desalination projects above 10,000 ppm TDS increasingly specify reverse osmosis over electrodialysis reversal due to lower energy consumption at extreme concentrations.
Strategic Opportunities
- Lithium extraction from brine:Electrodialysis is hybridizing with solvent extraction in Argentine and Chilean salar operations to selectively concentrate lithium ions before precipitation, reducing evaporation pond footprints.
- India's PLI scheme for advanced chemistry cell manufacturing:Battery-grade lithium hydroxide demand is creating new membrane system opportunities in Gujarat and Tamil Nadu industrial corridors.
- Direct-to-utility procurement platforms:OEMs are bypassing traditional EPC channels to sell membrane stacks directly to Saudi Arabia's Saline Water Conversion Corporation and UAE's Federal Electricity and Water Authority.
Industry Challenges
- Membrane fouling prediction and control:Organic fouling in food and beverage applications requires real-time conductivity monitoring and automated polarity reversal protocols that many installed systems lack.
- REACH compliance documentation:European membrane suppliers face extended certification timelines for new polymer formulations as ECHA expands substance of very high concern screening to perfluorinated materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrodialysis Equipment Market |
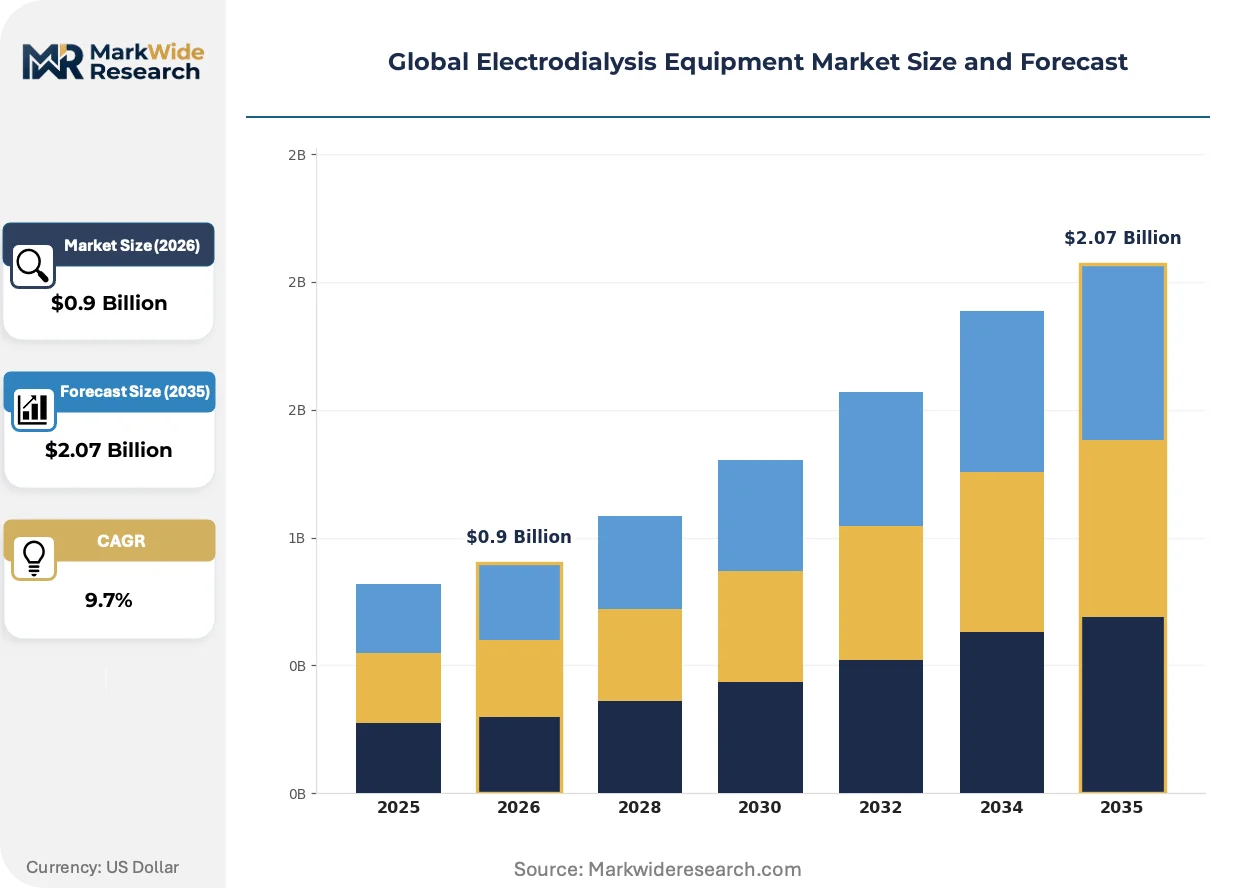
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $2.07 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Hybrid Systems, Modular Systems Technology: Ion Exchange Membranes, Electrodeionization, Membrane Distillation, Capacitive Deionization Application: Water Treatment, Wastewater Treatment, Desalination, Food Processing End User: Municipal, Industrial, Agricultural, Research Institutions |
| Companies Covered | PCCell GmbH, Evoqua Water Technologies LLC, General Electric Company, AGC Engineering Co., Ltd., Eurodia, ASTOM Corporation, MEGA Group, Saltworks Technologies Inc., C-Tech Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrodialysis Equipment Market Emerging Trajectories
Equipment manufacturers are reconfiguring stack architectures and membrane chemistries to serve concentration-driven applications beyond traditional desalination, blurring boundaries between water treatment and chemical processing.
Monovalent-selective ion-exchange membranes are hybridizing with conventional electrodialysis stacks to enable selective chloride removal from sulfate-rich industrial wastewater. Food processors in the Netherlands and dairy cooperatives in New Zealand are adopting these hybrid configurations to meet discharge limits without neutralizing valuable byproduct salts. The technology is compressing demand for downstream crystallization equipment by achieving higher concentration factors in fewer stages.
EU F-Gas Regulation phase-down schedules are forcing membrane producers to reformulate perfluorinated sulfonic acid polymers or transition to partially fluorinated alternatives. Equipment suppliers serving the European market must now validate stack performance with non-fluorinated membrane prototypes, extending product development cycles by 18-24 months. German pharmaceutical water system integrators are absorbing these compliance costs through premium pricing on validated batch electrodialysis units.
Service unbundling is fragmenting the traditional equipment-plus-membranes procurement model. Industrial buyers in China's coastal chemical parks are purchasing membrane stacks separately from maintenance contracts, then sourcing replacement membranes from third-party Asian suppliers. This pattern is most visible in Shandong province, where zero-liquid-discharge mandates have created a secondary market for reverse-engineered ion-exchange membranes at 40-60% below OEM pricing.
Global Electrodialysis Equipment Market Segmentation
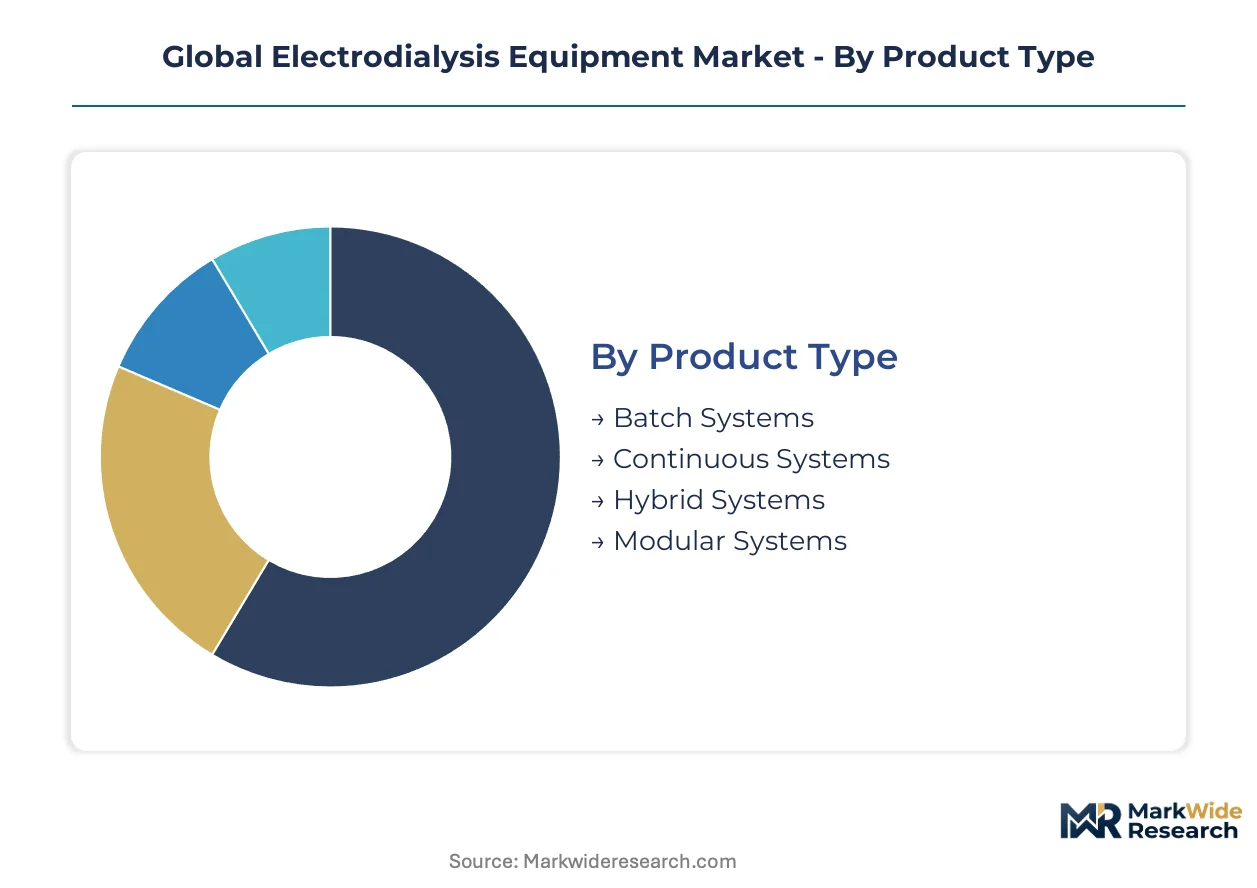
Segmentation in electrodialysis equipment reveals divergent equipment lifecycles and margin structures across operating modes and membrane technologies. Procurement patterns vary sharply between municipal utilities seeking decades-long service intervals and industrial operators prioritizing modular flexibility.
Product Type:
Continuous systems command the longest replacement cycles at 10-15 years for municipal installations, while modular configurations turn over fastest as distributed industrial sites scale capacity incrementally.
- Batch Systems:Engineered for pharmaceutical-grade water production with automated polarity reversal and precise conductivity control. German pharmaceutical water system integrators specify these units for validated production environments where FDA and EMA compliance documentation is mandatory.
- Continuous Systems:Designed for high-throughput municipal desalination with stacked membrane pairs operating at sustained current densities. Utilities in Japan and Germany deploy these for inland brackish aquifer treatment where energy costs disadvantage thermal alternatives.
- Hybrid Systems:Combine electrodialysis with solvent extraction for lithium concentration in Argentine and Chilean salar operations.
- Modular Systems:Capture fastest-growing demand from China's coastal chemical parks seeking incremental zero-liquid-discharge capacity.
Continuous systems anchor the volume base while modular systems gain share at the steepest rate.
Technology:
Cost tiers separate membrane-based approaches from electrode-intensive alternatives, with ion-exchange membranes commanding premium pricing due to polymer specialization and regulatory certification burdens.
- Ion Exchange Membranes:Perfluorinated sulfonic acid polymers and hydrocarbon-based alternatives form the selective barrier layer, with EU F-Gas Regulation phase-downs forcing reformulation cycles. Japanese and German specialty chemical producers control supply concentration, creating procurement bottlenecks for stack assemblers.
- Electrodeionization:Integrates ion-exchange resins with electrochemical regeneration for ultrapure water production in semiconductor fabrication. South Korean and Taiwanese electronics manufacturers specify these systems for chip rinsing operations.
- Membrane Distillation:Serves niche high-temperature industrial wastewater applications where thermal energy is available as waste heat.
- Capacitive Deionization:Emerging for low-salinity brackish treatment with lower energy footprints than conventional electrodialysis.
Ion exchange membranes dominate revenue concentration while capacitive deionization expands most quickly from a small installed base.
Application:
Application maturity varies by regulatory enforcement intensity, with zero-liquid-discharge mandates in industrial zones accelerating wastewater treatment deployment fastest.
- Water Treatment:Municipal utilities in Germany and Japan deploy electrodialysis for inland brackish aquifer desalination where thermal alternatives prove uneconomical.
- Wastewater Treatment:Industrial clusters in Shandong and Jiangsu provinces face China's MEE discharge standards, accelerating salt recovery and water reuse adoption.
- Desalination:Coastal installations concentrate in the Middle East where Saline Water Conversion Corporation procurement specifications influence stack design.
- Food Processing:Dutch food processors and New Zealand dairy cooperatives adopt monovalent-selective configurations to meet discharge limits without neutralizing valuable byproduct salts.
Water treatment retains the largest installed base while wastewater treatment climbs the fastest under tightening effluent regulations.
End User:
Customer type determines procurement channel structure, with municipal direct-to-utility platforms fragmenting traditional EPC relationships.
- Municipal:Saudi Arabia's Saline Water Conversion Corporation and UAE's Federal Electricity and Water Authority now procure membrane stacks directly from OEMs, bypassing engineering-procurement-construction intermediaries.
- Industrial:Chemical processors in Gujarat and Tamil Nadu industrial corridors demand battery-grade lithium hydroxide systems under India's PLI scheme for advanced chemistry cell manufacturing.
- Agricultural:Irrigation water treatment in water-stressed regions employs smaller-scale modular configurations.
- Research Institutions:Universities and national laboratories pilot next-generation membrane chemistries and hybrid process configurations.
Industrial end users generate the steepest order growth trajectory while municipal contracts sustain the revenue foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE discharge standards in China anchor the dominant geography, with coastal industrial zones driving membrane stack demand under tightening effluent mandates. Municipal utilities in Germany and Japan expand brackish water capacity as energy economics disfavor thermal alternatives. Procurement patterns fragment across direct-to-utility platforms in the Middle East and modular system adoption in India's battery chemical corridors.
China
Shandong and Jiangsu province chemical clusters deploy electrodialysis for zero-liquid-discharge compliance under MEE wastewater standards. GB membrane material specifications tighten ion-exchange polymer certification timelines for stack assemblers. Qingdao and Nantong industrial parks source modular systems incrementally, bypassing traditional EPC channels for faster capacity scaling.
Germany
Municipal utilities in Bavaria and North Rhine-Westphalia expand electrodialysis capacity for inland brackish aquifer treatment. REACH compliance documentation extends certification cycles for new membrane formulations as ECHA screens perfluorinated materials. Frankfurt-Rhine-Main pharmaceutical water system integrators absorb compliance premiums through validated batch unit pricing.
Japan
Tokyo and Osaka metropolitan utilities specify continuous electrodialysis systems for energy-efficient desalination of saline groundwater. METI efficiency standards shape membrane performance benchmarks for municipal procurement. Kansai region industrial operators pilot monovalent-selective configurations for sulfate-rich wastewater concentration.
Saudi Arabia
Saline Water Conversion Corporation procurement specifications influence stack design for coastal desalination capacity expansion. SFDA water quality standards intersect with membrane performance certification for potable output. Jubail and Yanbu industrial city operators evaluate hybrid electrodialysis-solvent extraction configurations for process water recycling.
India
Gujarat and Tamil Nadu battery chemical corridors demand membrane systems under PLI scheme incentives for advanced chemistry cell manufacturing. BIS membrane material standards tighten import substitution requirements for stack components. Hazira and Ennore industrial zones source electrode manufacturing capacity for captive lithium hydroxide production.
Global Electrodialysis Equipment Market Vendor Landscape
Integrated service networks and specialized batch engineering firms split the market between recurring revenue capture and premium validated system positioning. Japanese and German specialty chemical producers concentrate high-performance membrane supply, creating procurement bottlenecks for stack assemblers outside these geographies. Two archetypes dominate: vertically integrated water technology conglomerates with captive membrane production, and focused membrane stack engineering specialists serving pharmaceutical and food-grade applications. Competitive moves center on direct-to-utility procurement platform development and hydrocarbon-based membrane formulation partnerships to bypass fluoropolymer regulatory restrictions.
Among German engineering specialists, PCCell GmbH anchors European demand through validated batch system positioning for pharmaceutical-grade water production. Evoqua Water Technologies LLC exemplifies the integrated service archetype, sustaining recurring revenue through membrane replacement cycle capture across municipal and industrial installed bases. MEGA Group occupies a position within Central European electrode manufacturing, supplying dimensionally stable anode components to stack assemblers serving industrial cluster demand.
| Leading Market Players |
|---|
| PCCell GmbH |
| Evoqua Water Technologies LLC |
| General Electric Company |
| AGC Engineering Co., Ltd. |
| Eurodia |
| ASTOM Corporation |
| MEGA Group |
| Saltworks Technologies Inc. |
| C-Tech Innovation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese membrane stack assembly is compressing margins for modular system suppliers while tightening procurement leverage for industrial buyers in Shandong and Jiangsu chemical parks. This utilization imbalance feeds directly into pricing aggression on replacement membrane cycles and accelerates third-party sourcing from reverse-engineered Asian suppliers.
Pricing Analysis
Price spreads between validated European batch systems and Chinese modular configurations reach three-to-one multiples based on REACH compliance documentation and FDA certification tiers. Three-tier pricing structure across premium, standard, and economy levels reflects membrane polymer grade, electrode coating quality, and after-sales service bundling. Cost compression in economy-tier modular stacks intensifies as Shandong chemical processors unbundle maintenance contracts and source membranes from third-party suppliers. Municipal utilities in Germany and Japan show lowest price sensitivity due to decades-long service interval requirements and regulatory validation needs.
Supply Chain Analysis
Tariff exposure between Japan and China on fluoropolymer precursor chemicals dominates supply chain risk planning for membrane producers. Japanese and German specialty chemical producers anchor high-performance ion-exchange membrane supply, while Chinese stack assemblers draw from domestic electrode manufacturing capacity. Ruthenium oxide and iridium oxide coatings for dimensionally stable anodes introduce precious metal price volatility. Distribution runs through OEM-direct platforms for Saudi and UAE municipal utilities, while traditional EPC channels persist for European pharmaceutical water integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer formulation expertise and regulatory certification capabilities represent the scarcest assets in this market, concentrating margin capture among Japanese and German membrane suppliers while leaving stack assemblers exposed to input cost volatility.
For Market Incumbents: Harden membrane replacement cycle capture through integrated service contracts that lock in recurring revenue from municipal utilities in Germany and Japan. Secure backward integration into hydrocarbon-based polymer formulations to bypass EU F-Gas Regulation restrictions on fluoropolymer production. Defend against third-party membrane encroachment in Chinese chemical parks by embedding predictive fouling monitoring into stack designs. For New Entrants and Emerging Players: Mid-market modular systems for India's Gujarat and Tamil Nadu battery chemical corridors represent the most penetrable entry point under PLI scheme incentives. Argentine and Chilean lithium extraction hybrid configurations offer white-space demand with less entrenched incumbent presence. Lead with electrode manufacturing partnerships rather than membrane supply to circumvent Japanese and German supply concentration. For Investors and Strategic Acquirers: Capital is best deployed toward validated batch system engineering specialists with captive pharmaceutical water relationships and REACH-compliant membrane formulation pipelines. Long-term viability hinges on regulatory certification moats and replacement cycle economics rather than project-based equipment sales. Watch for MEE discharge standard tightening in additional Chinese provinces as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Membrane Formulation Partnership | Bypasses EU F-Gas Regulation phase-downs and extends addressable market in Europe. |
| Direct-to-Utility Procurement Platform | Captures Saudi Saline Water Conversion Corporation and UAE FEWA membrane stack demand. |
| Predictive Fouling Monitoring Integration | Defends against third-party membrane substitution in Chinese zero-liquid-discharge installations. |
| Electrode Manufacturing Scale-Up | Reduces precious metal coating cost volatility for dimensionally stable anode supply. |
| Lithium Extraction Hybrid System Development | Positions for Argentine and Chilean salar operator demand with solvent extraction integration. |
Methodological Framework
Operator-level perspectives from municipal utility planning officers, pharmaceutical water system integrators, chemical park procurement managers, and membrane stack engineering directors anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC filings of listed water technology conglomerates, ECHA substance registration databases, and Chinese MEE discharge standard documentation. Customs data on ion-exchange membrane trade flows and bottom-up stack shipment estimates triangulated against top-down market sizing across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and membrane material substitution timelines shaped the analytical framework. Segmentation dimensions modeled include product type, membrane technology, application vertical, and end-user procurement channel. CAGRs derived from installed base turnover rates and replacement cycle economics rather than simple extrapolation. Forecast inputs incorporated MEE discharge standard rollout schedules and EU F-Gas Regulation phase-down milestones.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing or precious metal markets would shift the trajectory for energy-intensive desalination and electrode coating cost structures. Forecasts reflect documented assumptions on regulatory enforcement consistency and membrane durability benchmarks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Coconut Crushers Market