
 Ice Cleat Market | 2026-2036
Ice Cleat Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cleat Market Insights
Chinese rubber compounders is repositioning supply chains for cold-weather elastomers used in traction footwear, redirecting bulk polymer flows toward North American converters. Hillsound leverages alpine-grade material sourcing to sustain premium positioning across mountain rescue channels. Winter Walking anchors its presence in industrial safety procurement through direct corporate and institutional contracts. Kahtoola differentiates via specialized hiking traction systems that occupy technical backcountry segments.
Ice cleats are mechanical traction devices constructed from elastomeric bands or frames fitted with metal studs, carbide spikes, or molded polymer grips, engineered to prevent slip incidents on frozen surfaces by increasing coefficients of friction between footwear and ice. Metal cleats dominate commercial and industrial procurement due to durability under load, while rubber cleats lead consumer recreational channels through lighter weight and lower unit cost; composite cleats represent the fastest-growing category as hybrid material formulations improve cold-flex performance without corrosion susceptibility. Distribution runs through specialty stores for fitted industrial applications, whereas online retail captures seasonal consumer spikes in temperate climate zones.
OSHA fall-protection enforcement shapes employer liability calculations and drives bulk purchasing of certified traction devices for outdoor workforces. The European Union's REACH chemical regulations and CE marking requirements for personal protective equipment govern material composition and testing protocols for cleats sold into EU member states. ISO standards for slip resistance provide cross-border benchmarking that influences procurement specifications among multinational logistics and energy operators. Stakeholders must monitor evolving PPE harmonization between OSHA and EU frameworks to anticipate compliance cost shifts and certification timeline adjustments.
Market Dynamics
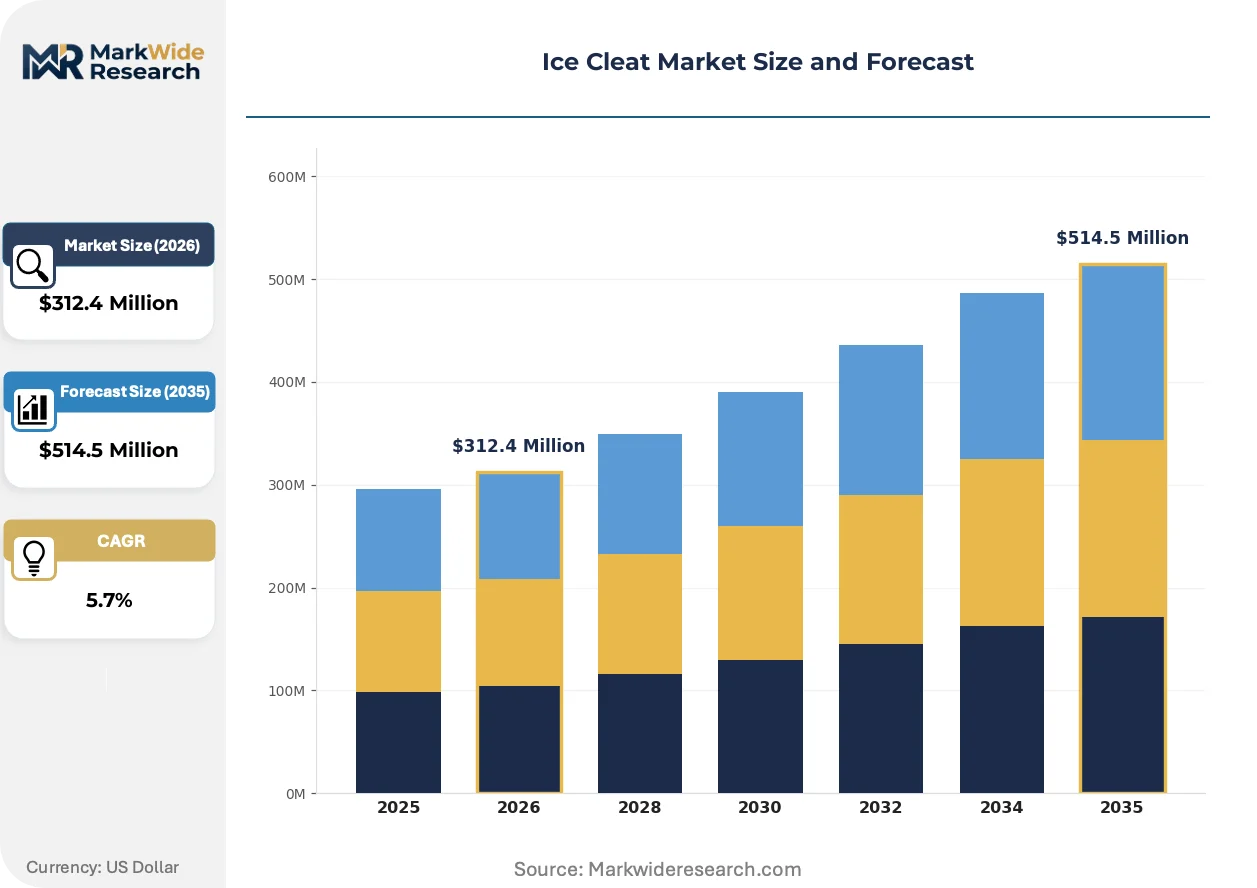
OSHA fall-protection enforcement is compressing employer liability windows and mandating certified traction devices for outdoor workforces across jurisdictions with freeze-thaw exposure. This regulatory pressure is restructuring procurement specifications and supplier qualification requirements.
Growth Catalysts
- Municipal fleet expansion:Sanitation and utility crews across Minnesota, Wisconsin, and New York states are receiving mandated slip-prevention allocations. Seasonal freeze-thaw cycles sustain recurring procurement volumes.
- REACH chemical compliance:EU material composition standards are elevating certification barriers for cleat exporters, favoring compounders with validated cold-weather elastomer formulations.
- Carbide spike durability:Industrial buyers are specifying tungsten-carbide traction elements for load-bearing applications where steel corrosion degrades performance.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly to compounder input costs, compressing converter margins during peak seasonal demand.
- Single-source carbide dependency:Tungsten processing concentrates in Chinese smelters, creating supply vulnerability for premium cleat manufacturers.
- CE marking timeline friction:EU PPE certification delays extend product launch cycles by 8-14 months for North American exporters.
Strategic Opportunities
- Underpenetrated Nordic markets:Finland and Norway municipal procurement remains fragmented, creating entry points for certified industrial suppliers.
- Composite material convergence:Hybrid polymer-carbide formulations are opening technical backcountry segments previously served by metal-only systems.
- Direct institutional contracting:Corporate safety departments are bypassing distributors for volume agreements with certified manufacturers.
Industry Challenges
- Cold-flex testing capacity scarcity:Validated laboratories for sub-zero elastomer performance are concentrated in Germany and the US, creating certification bottlenecks.
- Legacy inventory obsolescence:Retail channels face write-downs when OSHA specification updates render non-certified stock unsellable to institutional buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cleat Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Cleats, Metal Cleats, Composite Cleats, Spiked Cleats End User: Outdoor Enthusiasts, Industrial Workers, Emergency Responders, Casual Users Use Case: Hiking, Construction, Search & Rescue, Recreational Activities Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Retailers, Wholesale |
| Companies Covered | Hillsound, Winter Walking, Kahtoola, Cimkiz, Stabilicers, Yaktrax, Korkers, Unigear, Black Diamond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cleat Market Trends and Innovations
Material science advances and procurement digitization are compressing product development cycles while elevating performance certification requirements. Buyers now demand validated cold-weather performance data prior to contract award.
Hybrid elastomer-carbide composites are integrating into mid-tier product lines, delivering alpine-grade traction at industrial price points. Municipal procurement departments are specifying these formulations for crew safety programs. The technology is integrating previously separate consumer and industrial supply chains, forcing compounders to dual-certify formulations.
OSHA's updated fall-protection directive is tightening documentation requirements for employer-provided traction devices. Construction and logistics operators must now maintain usage logs and inspection records. Upper Midwest states are experiencing the steepest compliance cost increases as inspectors prioritize outdoor workforce citations.
Direct-to-institution contracting is displacing seasonal retail purchasing for enterprise safety programs. Corporate procurement teams are consolidating vendor lists around certified manufacturers with validated cold-flex data. This concentration is most visible in Minnesota and Wisconsin, where municipal and private fleet operators coordinate specification harmonization.
Ice Cleat Market Segmentation
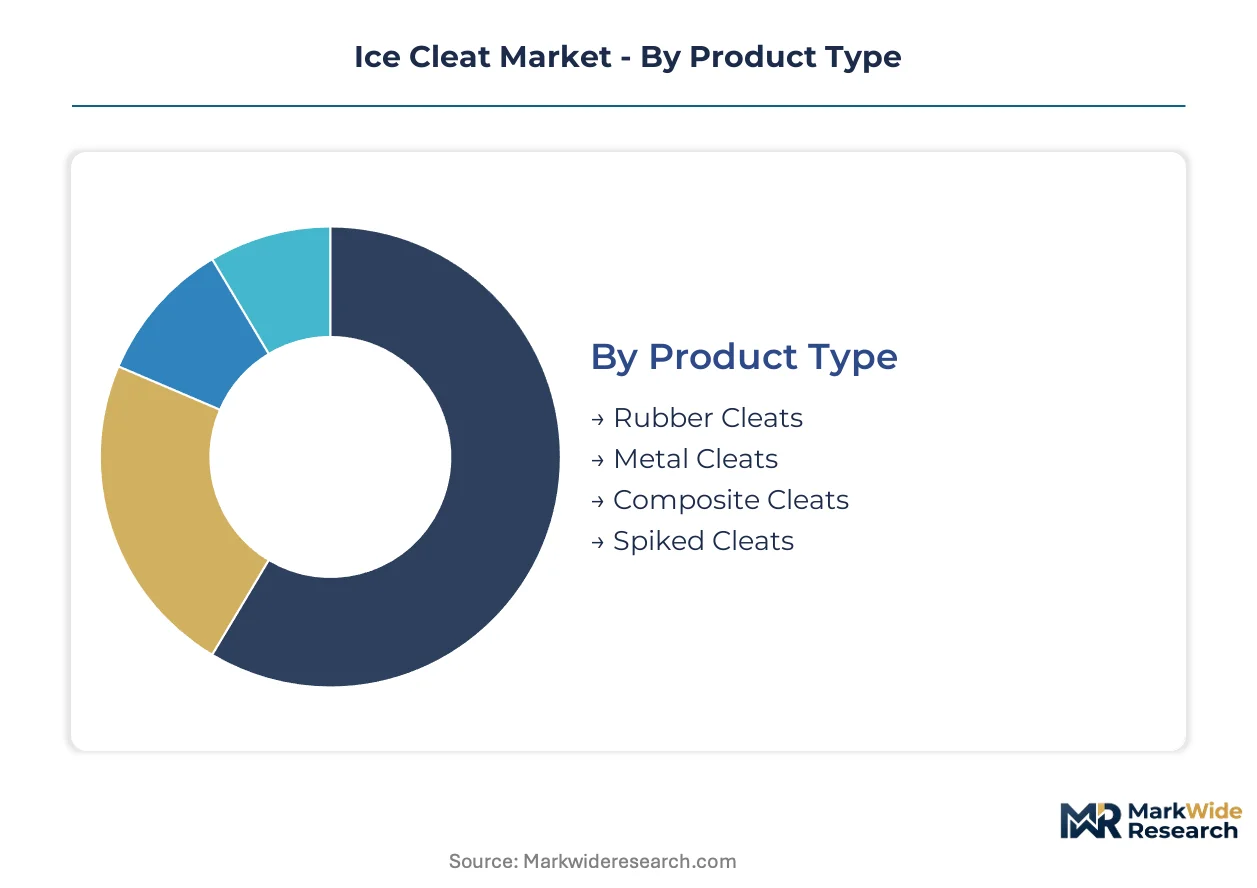
Ice cleat procurement splits sharply between institutional buyers demanding certified load-bearing performance and recreational consumers prioritizing weight and convenience. Specification divergence across these segments is widening as OSHA compliance mandates reshape employer purchasing criteria.
Product Type:
Industrial buyers prioritize spike material and frame durability over unit cost when specifying traction devices for crew safety programs.
- Metal Cleats:Steel or aluminum frames fitted with hardened spikes deliver maximum traction under heavy load. Municipal sanitation departments in Minnesota and Wisconsin specify these for year-round crew safety compliance.
- Composite Cleats:Hybrid polymer-carbide formulations merge cold-flex elasticity with spike durability. These systems are climbing the fastest as compounders validate sub-zero performance for dual consumer-industrial certification.
- Rubber Cleats:Molded elastomer bands with integrated polymer grips serve lightweight consumer applications.
- Spiked Cleats:Aggressive tungsten-carbide protrusions anchor technical mountaineering and rescue operations.
Volume sits with Metal Cleats; growth tilts toward Composite Cleats.
End User:
Procurement scale and specification rigor separate enterprise safety programs from individual purchasing decisions.
- Industrial Workers:Construction, logistics, and utility employers mandate certified traction devices under OSHA fall-protection directives. Fleet operators in New York State coordinate bulk purchasing through harmonized safety specifications.
- Emergency Responders:Mountain rescue and urban search teams require alpine-grade reliability for mission-critical deployment. These users validate cold-flex performance data before contract award.
- Outdoor Enthusiasts:Hikers and backcountry skiers drive seasonal demand spikes through specialty retail channels.
- Casual Users:Urban pedestrians in freeze-thaw climates purchase entry-level protection for intermittent winter use.
Contract value concentrates with Industrial Workers; technical specification leadership rests with Emergency Responders.
Use Case:
Activity-specific traction requirements dictate frame geometry, spike density, and attachment mechanism design.
- Construction:Flat-soled boots on icy scaffolding and steel surfaces demand aggressive carbide penetration. OSHA inspectors prioritize citation enforcement at Upper Midwest job sites.
- Search & Rescue:Technical terrain traversal requires modular systems adaptable to mixed ice, rock, and snow conditions.
- Hiking:Trail-oriented designs balance weight against grip on packed snow and frozen ground.
- Recreational Activities:Ice fishing, winter photography, and dog walking generate intermittent demand for basic traction enhancement.
Procurement standardization advances fastest in Construction; product complexity peaks in Search & Rescue.
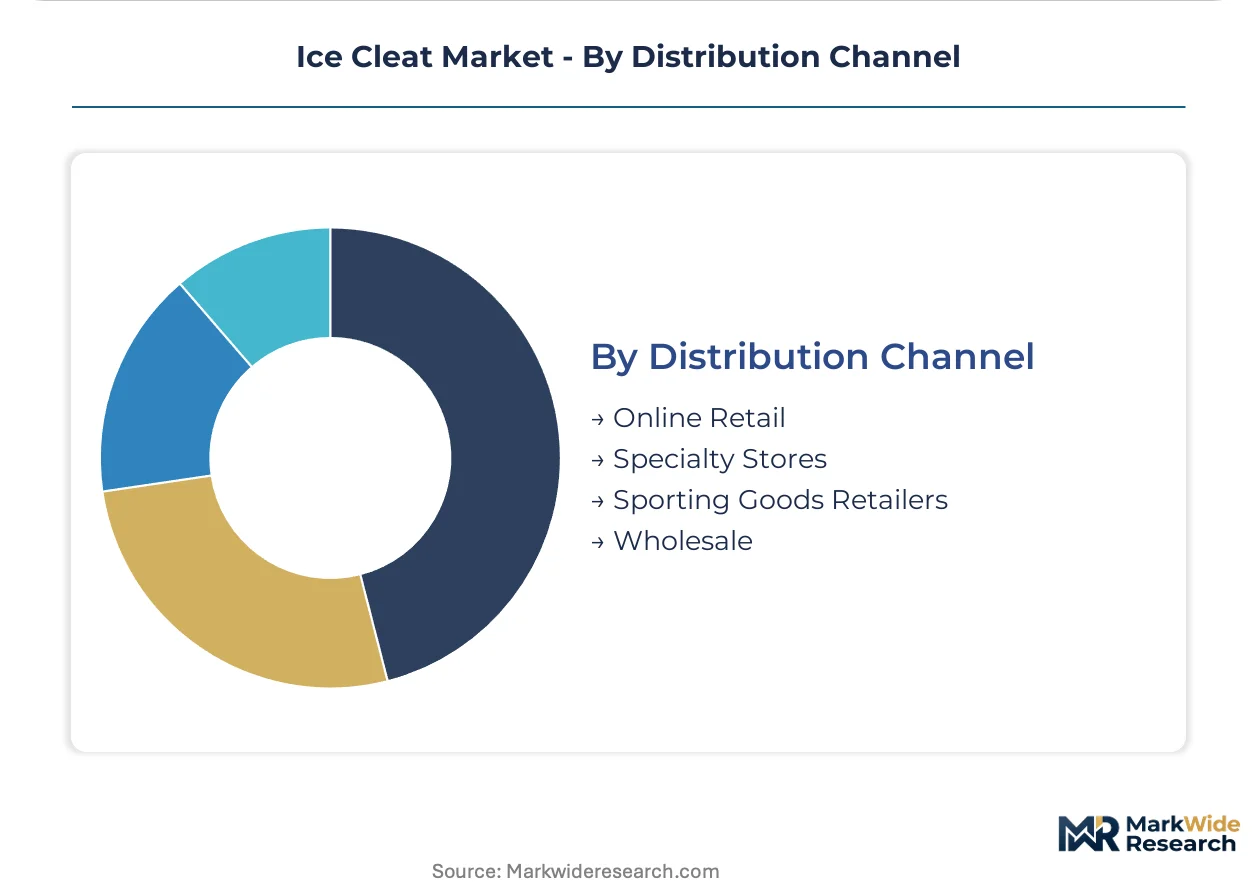
Distribution Channel:
Channel selection tracks buyer type, with institutional procurement bypassing traditional retail infrastructure.
- Specialty Stores:Fitted industrial applications require trained staff for sizing and compliance verification. These outlets capture municipal fleet contracts through direct relationship management.
- Online Retail:E-commerce platforms capture seasonal consumer spikes in temperate climate zones where demand concentrates in narrow winter windows.
- Sporting Goods Retailers:Recreational users purchase through regional chains with winter sports inventory.
- Wholesale:Distributors serve smaller employers lacking direct manufacturer relationships.
Revenue stability favors Specialty Stores; transaction velocity peaks in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten carbide processing concentrates in Chinese smelters, anchoring raw material flows for premium cleat manufacturers serving freeze-thaw corridors worldwide.
United States
Municipal fleet operators in Minnesota, Wisconsin, and New York State drive institutional procurement volumes through coordinated safety specifications. OSHA fall-protection enforcement tightens employer liability calculations and mandates certified traction devices for outdoor construction and utility crews. The Upper Midwest corridor experiences the steepest compliance cost increases as inspectors prioritize workforce citation enforcement.
Canada
Provincial safety regulators in Ontario, Quebec, and Alberta align procurement standards with federal workplace hazard protocols for winter maintenance personnel. The country's national occupational health regulator mandates slip-prevention equipment for federal infrastructure contractors operating in sub-zero conditions. Toronto and Calgary anchor municipal fleet standardization efforts that harmonize specifications across prairie and Great Lakes jurisdictions.
Germany
REACH chemical compliance elevates certification barriers for elastomer compounders supplying cold-weather traction devices into EU member states. The European Chemicals Agency validates material composition standards that govern personal protective equipment market access. Bavaria and North Rhine-Westphalia concentrate industrial safety distributors serving logistics and energy operators with harmonized procurement specifications.
China
Rubber compounders reposition supply chains for cold-weather elastomers, redirecting bulk polymer flows toward North American converters facing seasonal demand spikes. The country's national standards administration oversees material testing protocols that influence export certification timelines. Yangtze River Delta manufacturing clusters supply frame components and molded grips for mid-tier consumer segments.
Finland
Municipal procurement remains fragmented across Nordic jurisdictions, creating entry points for certified industrial suppliers with validated cold-flex performance data. The country's national occupational safety regulator enforces winter workplace protocols that exceed baseline EU requirements. Helsinki anchors technical specification development for rescue and emergency responder equipment deployed across Baltic conditions.
Ice Cleat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material convergence and direct institutional contracting channels. The vendor base stratifies across three tiers: alpine-grade specialists serving technical rescue segments, industrial safety suppliers anchoring municipal fleet contracts, and consumer-oriented brands capturing seasonal retail velocity. Two dominant competitive moves define current positioning: hybrid formulation development to bridge consumer-industrial certification requirements, and backward integration into cold-weather elastomer compounding to secure supply continuity.
Within the alpine-grade specialist tier, Hillsound and Kahtoola occupy positions defined by technical backcountry credibility and mountain rescue channel relationships. Winter Walking exemplifies the industrial safety archetype through direct corporate and institutional contracting presence. These three anchors demonstrate how material sourcing strategies and certification depth separate premium positioning from commodity competition in freeze-thaw markets.
| Leading Market Players |
|---|
| Hillsound |
| Winter Walking |
| Kahtoola |
| Cimkiz |
| Stabilicers |
| Yaktrax |
| Korkers |
| Unigear |
| Black Diamond |
| Others |
Pricing and Supply Chain Analysis
OSHA-mandated cold-flex certification for industrial cleats is forcing compounders to validate elastomer formulations through scarce German and US testing laboratories, compressing margins for uncertified manufacturers while concentrating pricing power with dual-certified suppliers. Municipal fleet buyers in Minnesota and Wisconsin now require documented sub-zero performance data, shifting procurement toward premium-tier products with bundled compliance verification.
Pricing Analysis
Warranty and inspection-log bundling separates industrial-grade contracts from unverified consumer purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and spike material—tungsten-carbide systems command substantial premiums over steel alternatives. Pricing pressure stems from Thai and Indonesian natural rubber supply disruptions transmitting directly to compounder input costs. Municipal safety departments exhibit lowest price sensitivity due to liability exposure, while casual urban pedestrians drive volume at entry price points.
Supply Chain Analysis
Regional distribution centers in Chicago and Toronto anchor North American fulfillment for seasonal demand spikes, with hub-and-spoke patterns radiating toward Upper Midwest municipal fleets. Manufacturing concentrates in China for frame components and molded grips, Germany for cold-flex validation services, and the US for final assembly of certified industrial units. Raw material flows draw from Chinese tungsten smelters for carbide spikes, Southeast Asian latex plantations for elastomer feedstock, and domestic converters for hybrid polymer formulations. Single-source carbide dependency creates acute supply vulnerability. Distribution runs through specialty industrial distributors for fleet contracts and direct e-commerce for recreational consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cold-weather elastomer compounding has become the defining competitive race, with first movers securing captive supply chains against Thai latex volatility and Chinese carbide concentration.
For Market Incumbents: Anchor municipal fleet relationships through multi-year direct contracting with embedded cold-flex certification renewals. Defend against composite-formulation entrants by accelerating in-house polymer-carbide R&D and securing exclusive testing-laboratory capacity in Germany. Volume consolidation among Minnesota and Wisconsin safety coordinators threatens distributor-dependent competitors. For New Entrants and Emerging Players: Begin with fragmented Nordic municipal procurement in Finland and Norway, where harmonized EU certification requirements meet localized specification gaps. Target emergency responder channels with alpine-grade reliability claims validated through Helsinki technical institutes. Direct institutional sales bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors compounders with validated cold-flex data and existing CE marking pathways. Long-term viability hinges on backward integration depth and testing-laboratory relationships rather than brand equity. Monitor OSHA specification update timing as inflection signal for legacy inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive supply secures margins against Thai latex price volatility and Indonesian export disruptions. |
| Cold-Flex Laboratory Capacity Expansion | German and US testing scarcity creates certification bottlenecks for REACH and OSHA dual compliance. |
| Direct Municipal Fleet Contracting | Minnesota and Wisconsin safety coordinators consolidate vendor lists around certified manufacturers. |
| Hybrid Polymer-Carbide Formulation Development | Dual consumer-industrial certification bridges previously separate supply chains and pricing tiers. |
| Nordic Market Entry with CE-Marked Industrial Lines | Finland and Norway procurement fragmentation creates first-mover advantages for validated suppliers. |
Research Methodology
Trade customs records, OSHA enforcement databases, and EU REACH certification filings formed the secondary backbone, cross-referenced with primary interviews across municipal fleet safety coordinators, industrial elastomer compounders, cold-flex laboratory directors, and specialty distributor procurement leads. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level demand estimates.
Bottom-up modeling anchored volume projections across product type, end-user archetype, and distribution channel dimensions, with additional granularity for freeze-thaw corridor intensity. CAGRs derived from historical procurement pattern analysis and regulatory enforcement trajectory assessment. Key inputs included municipal budget allocation cycles, tungsten carbide spot price volatility, and laboratory certification queue lengths.
Underlying measurement precision varies by segment; industrial worker and emergency responder categories carry tighter precision than casual consumer estimates due to documented contract visibility. Forecasts reflect documented assumptions around OSHA enforcement intensity and REACH harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Padel Balls Market
Sports Equipment
Balance Bike Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Running Gear Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Golf Bags Market
Sports Equipment
Tennis Equipment Market