
 Windsurfing Equipment Market | 2026-2036
Windsurfing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Windsurfing Equipment Market Outlook
Recreational tourism infrastructure is pivoting toward dedicated windsurfing resorts and school networks, expanding the addressable base beyond traditional owner-operators. Starboard leverages its manufacturing scale to supply rental fleets across Southeast Asian beach destinations. Fanatic differentiates through carbon fiber R&D intensity, targeting performance athletes with lighter mast and boom combinations. Naish anchors its position in wave-riding board shapes, a sub-category where brand heritage commands premium positioning.
Windsurfing equipment comprises boards, sails, masts, and booms engineered for wind-powered water propulsion, with modern boards typically incorporating PVC foam cores wrapped in fiberglass or carbon fiber epoxy laminates to achieve strength-to-weight ratios below seven kilograms for slalom designs. The primary commercial purpose spans recreational leisure, competitive racing, and instructional school operations where durability and handling stability determine procurement decisions. Boards and sails represent the mature volume center where margin pools have compressed, while carbon fiber masts capture the fastest-growing premium tier as professional athletes and advanced recreational users upgrade from aluminum and fiberglass alternatives. Distribution through specialty stores retains structural importance for fitting and demo services, though online retail is gaining share in replacement parts and accessory sales.
REACH in Europe and EPA guidelines in the United States govern resin systems and volatile organic compound emissions in composite manufacturing, raising compliance costs for smaller board builders while favoring scaled producers with in-house chemical management. ISO 12217 small craft stability standards and CE marking requirements shape product liability exposure and market access for equipment sold into EU waters. Stakeholders must monitor how evolving sustainability mandates around end-of-life board recycling reshape material selection decisions and supplier qualification criteria.
Market Dynamics
REACH compliance in Europe is tightening chemical safety standards for composite materials used in board manufacturing, forcing producers to reformulate epoxy resin systems and reshaping supplier qualification criteria across the value chain.
Growth Catalysts
- Coastal tourism infrastructure:Dedicated windsurfing resorts and school networks are expanding equipment procurement beyond traditional owner-operators. Rental fleet operators in Brazil's northeastern coastline drive recurring volume.
- Carbon fiber mast upgrades:Advanced recreational users and professional athletes are displacing aluminum and fiberglass alternatives, creating premium tier expansion.
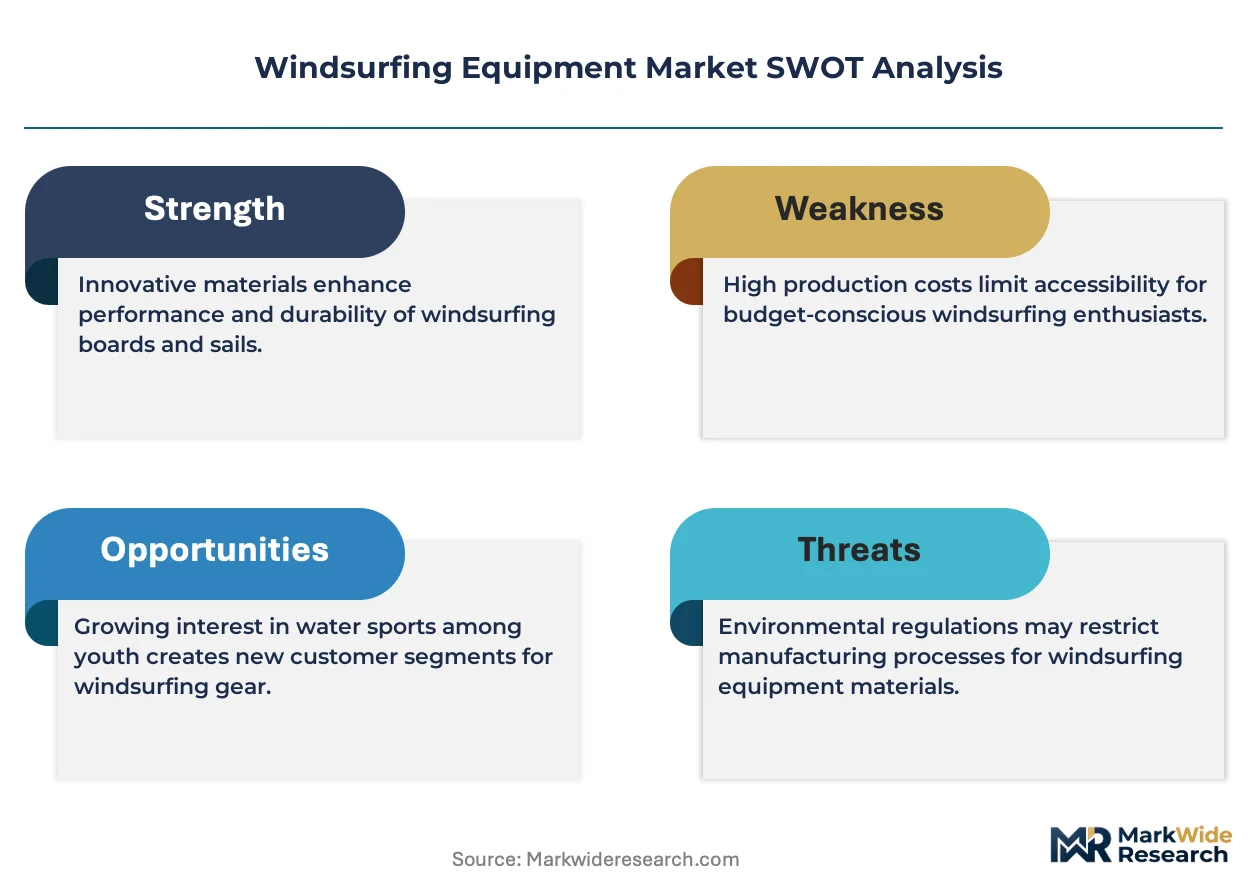
- REACH chemical safety standards:European regulatory pressure is accelerating material innovation in epoxy laminates and PVC foam cores, favoring scaled producers with in-house chemical management capabilities.
Market Restraints
- Epoxy resin input volatility:Petrochemical feedstock price swings compress margin pools for board manufacturers dependent on imported resin systems.
- Specialty retail concentration:Distribution through demo-capable stores limits geographic reach compared to online channels, constraining replacement parts velocity.
- End-of-life board recycling:Limited industrial-scale recovery infrastructure for fiberglass-carbon fiber composites creates landfill liability exposure and reputational risk.
Strategic Opportunities
- Southeast Asian beach destinations:Underpenetrated rental fleet markets in Thailand, Vietnam, and Indonesia offer procurement expansion for volume manufacturers.
- Online replacement parts channel:Direct-to-consumer sales of masts, booms, and accessories bypass specialty store constraints and capture higher margin retention.
- EU Green Deal sustainability mandates:Early compliance with circular economy requirements for composite recycling creates supplier differentiation and preferential procurement positioning.
Industry Challenges
- Composite technician skill scarcity:Hand-lamination expertise for custom board shapes concentrates in legacy manufacturing regions, constraining quality-consistency at scale.
- ISO 12217 stability certification timelines:Small craft testing protocols for CE marking create extended product launch cycles and capital lockup.
- Legacy aluminum mast inventory:Distribution channel overhang from prior generation products depresses carbon fiber upgrade pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windsurfing Equipment Market |
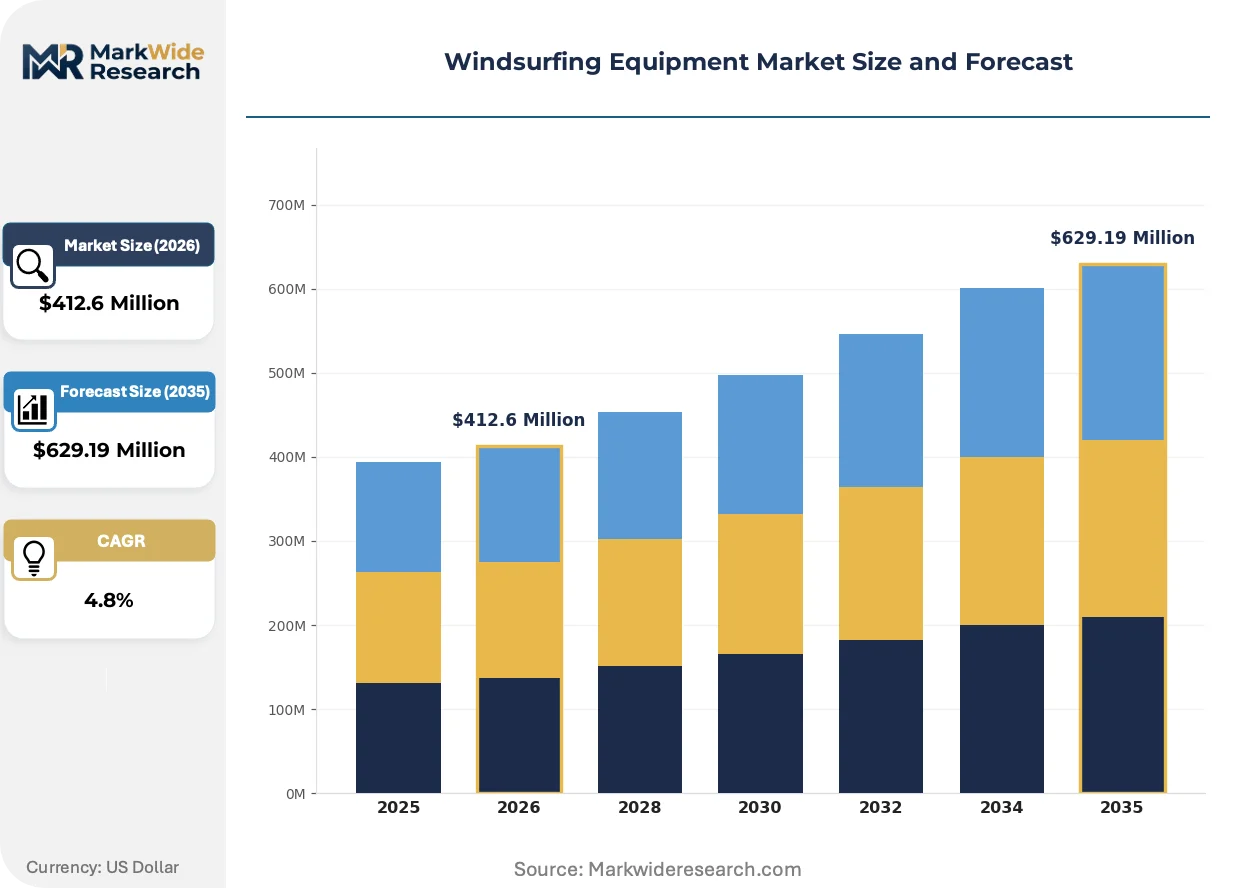
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boards, Sails, Masts, Booms End User: Recreational Users, Professional Athletes, Schools, Rental Services Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors Material: Fiberglass, Carbon Fiber, Plastic, Wood |
| Companies Covered | Naish, Kona Windsurfing, Tabou Surfboards, Mistral International, Starboard, Fanatic, Societe BIC, Ricci International, JP Australia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windsurfing Equipment Market Strategic Shifts
Material science advances and regulatory pressure on chemical safety are converging to reshape manufacturing processes and procurement patterns across the windsurfing equipment value chain.
Modular mast-boom connector systems are decentralizing equipment interoperability standards. Performance athletes and advanced recreational users are adopting quick-release carbon fiber interfaces that permit rapid rig reconfiguration between slalom and wave disciplines. This technology is decentralizing brand-specific ecosystem lock-in and enabling cross-manufacturer component mixing that compresses replacement cycle predictability for incumbent suppliers.
REACH substance restrictions in Europe are tightening permissible volatile organic compound thresholds in epoxy resin curing processes. Board manufacturers face reformulation costs and supply chain requalification burdens that disproportionately impact smaller builders lacking dedicated chemical management infrastructure. Scaled producers with captive laboratory capabilities are accelerating compliance certification and capturing procurement preference from rental fleet operators serving EU waters.
School-based instructional procurement is consolidating volume concentration among regional operator networks. Multi-location coastal academies in Brazil and Southeast Asia are displacing fragmented independent instructor purchases with centralized fleet standardization. This consolidation is most visible in Jericoacoara and Cumbuco, where trade wind reliability supports year-round operations and equipment utilization rates justify premium durability specifications.
Windsurfing Equipment Market Segmentation
Equipment procurement patterns diverge sharply between owner-operators seeking performance optimization and rental fleets prioritizing durability and interchangeability. Understanding these buyer-type distinctions determines go-to-market configuration and margin capture potential across the value chain.
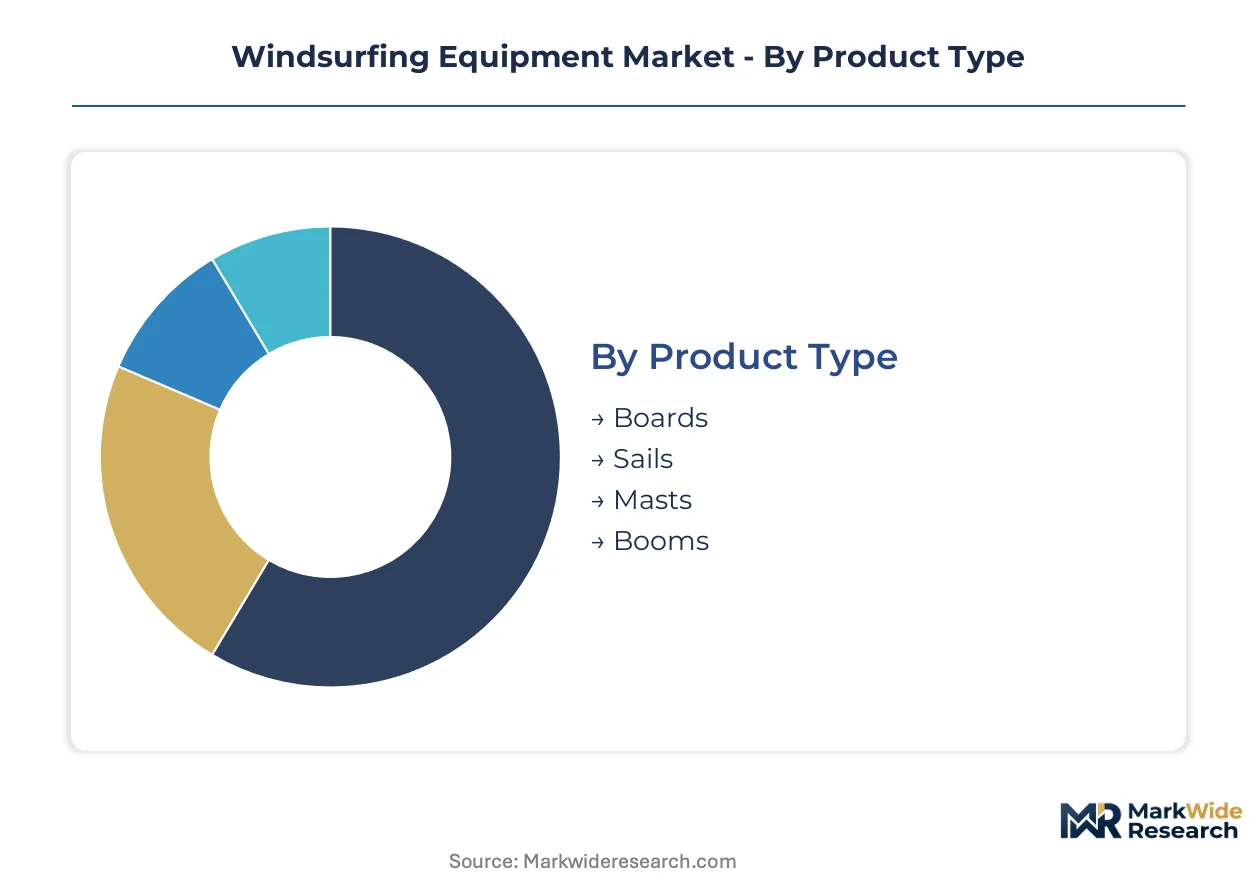
Product Type:
Performance demands and replacement frequency separate casual participants from committed athletes across the four equipment categories.
- Boards:PVC foam cores wrapped in fiberglass or carbon fiber epoxy laminates deliver strength-to-weight ratios below seven kilograms for slalom designs. Volume concentrates in recreational all-around shapes for rental fleets along Brazil's northeastern coastline, where trade wind reliability supports year-round school operations.
- Sails:Monofilm and dacron laminates with carbon or fiberglass battens determine power delivery and handling response. Advanced recreational users and professional athletes in wave-riding disciplines drive premium specification demand, with brand heritage commanding positioning power in this sub-category.
- Masts:Carbon fiber tubes with tapered wall thickness optimize bend characteristics for sail compatibility.
- Booms:Aluminum or carbon fiber tubes with adjustable clamp mechanisms permit rig reconfiguration across wind conditions.
Volume sits with boards and sails; growth tilts toward carbon fiber masts as athletes upgrade from aluminum alternatives.
End User:
Utilization intensity and procurement decision logic fragment the customer base across four distinct operational models.
- Recreational Users:Individual owners purchasing for leisure sailing prioritize handling stability and transport convenience over extreme performance metrics. Replacement cycles extend across multiple seasons, constraining aftermarket velocity relative to fleet operators.
- Professional Athletes:Sponsored competitors and independent racers demand carbon fiber mast and boom combinations optimized for specific discipline requirements. REACH compliance in Europe is tightening chemical safety standards for their preferred composite materials, accelerating supplier requalification.
- Schools:Instructional academies in Jericoacoara and Cumbuco consolidate volume through centralized procurement of durable, standardized equipment.
- Rental Services:Coastal tourism hubs across Southeast Asia expand equipment procurement beyond traditional owner-operators.
Procurement concentrates with rental services; margin expansion favors professional athletes seeking premium tier specifications.
Distribution Channel:
Service intensity requirements and product complexity determine channel viability across the purchase journey.
- Online Retail:Direct-to-consumer platforms capture replacement parts and accessory sales with higher margin retention, bypassing specialty store geographic constraints.
- Specialty Stores:Demo-capable retailers retain structural importance for fitting services and equipment trials, though their concentration limits replacement parts velocity.
- Direct Sales:Manufacturer-controlled channels serve professional athletes and high-volume fleet operators with customized specification negotiations.
- Distributors:Regional intermediaries aggregate fragmented demand in emerging markets lacking dedicated windsurfing retail infrastructure.
Transaction volume flows through specialty stores; channel shift momentum favors online retail for aftermarket components.
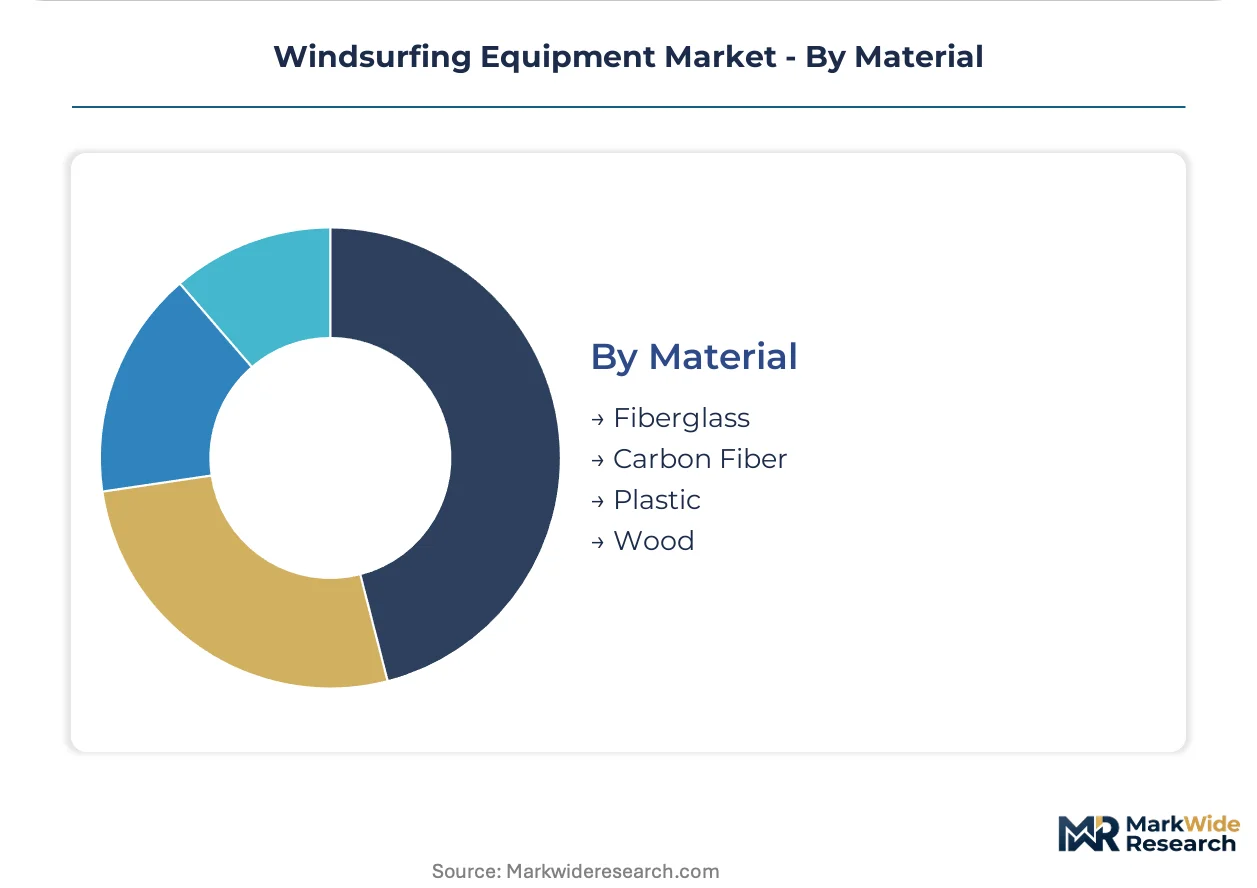
Material:
Cost-performance tradeoffs and regulatory compliance burdens reshape material selection across manufacturing tiers.
- Fiberglass:E-glass and S-glass reinforcements in epoxy matrices deliver cost-effective durability for rental fleet boards and entry-level equipment. REACH substance restrictions in Europe are tightening permissible volatile organic compound thresholds in curing processes, raising reformulation costs.
- Carbon Fiber:T700 and T800 grade prepregs enable sub-seven-kilogram slalom board constructions and stiff mast designs. Professional athletes and advanced recreational users in wave-riding and racing disciplines drive specification intensity.
- Plastic:Thermoplastic constructions serve beginner school equipment and rental fleet durability requirements.
- Wood:Veneer and sandwich core applications persist in custom and heritage board constructions.
Production volume rests with fiberglass; steepest expansion trajectory belongs to carbon fiber as performance tier specifications intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Thailand and Vietnam where composite workshops supply global brands, while consumption clusters in coastal tourism corridors across Brazil, Spain, and Australia. This production-consumption divide shapes logistics networks and regional margin structures.
Brazil
Trade wind reliability along the northeastern coastline from Jericoacoara to Cumbuco sustains year-round school operations and rental fleet procurement. ANVISA oversees product safety compliance for equipment imported into Brazilian waters. Equipment utilization rates in Ceará state justify premium durability specifications from regional operator networks.
Spain
Canary Islands tourism infrastructure drives recurring replacement cycles for rental boards and sails across Tenerife and Fuerteventura. REACH substance restrictions from ECHA govern epoxy resin formulations in boards manufactured for EU distribution. Valencia hosts composite testing laboratories serving CE marking requirements for small craft stability certification.
Thailand
Beach destination expansion in Phuket and Koh Samui attracts procurement from Southeast Asian rental fleet operators. The country's industrial standards regulator monitors chemical safety in composite manufacturing for export markets. Chonburi province concentrates board fabrication facilities supplying branded equipment to regional distributors.
Australia
Coastal recreation demand concentrates in Queensland and Western Australia where school networks standardize equipment procurement. TGA-equivalent product safety frameworks apply to recreational watercraft sold domestically. Perth manufacturers serve domestic wave-riding specialists with custom board shapes.
Germany
Performance athlete demand for carbon fiber masts and racing equipment sustains premium tier procurement despite limited domestic coastline. KBA-adjacent product liability standards influence CE marking preparation for equipment exported throughout Europe. Bavaria hosts engineering consultancies specializing in composite structural analysis for mast design.
Windsurfing Equipment Market Competitive Environment
Top-tier vendors anchor premium carbon fiber and racing equipment, while mid-scale fabricators serve rental fleet volume with fiberglass constructions. The structure tilts toward brand heritage differentiation in wave-riding shapes and mast-boom combinations. Three archetypes dominate: heritage European brands with professional athlete sponsorship, Asian manufacturing specialists supplying private-label rental equipment, and diversified watersports conglomerates with cross-category procurement leverage. Capacity expansion in Southeast Asian composite workshops and strategic partnerships between European designers and Thai manufacturers represent the dominant competitive moves.
Within the heritage brand tier, Naish and Starboard exemplify positioning built on professional athlete validation and wave-riding specialization. Fanatic occupies a position in carbon fiber R&D intensity for performance-tier mast and boom combinations. These European-originated entities represent archetypes of brand-driven premium positioning rather than scale-driven manufacturing.
| Leading Market Players |
|---|
| Naish |
| Kona Windsurfing |
| Tabou Surfboards |
| Mistral International |
| Starboard |
| Fanatic |
| Societe BIC |
| Ricci International |
| JP Australia |
| Others |
Value Chain & Pricing Dynamics
Rental fleet operators in Brazil's northeastern coastline anchor procurement volume and enforce three-tier pricing stratification across premium carbon fiber, standard fiberglass, and economy thermoplastic equipment tiers. Their centralized purchasing power compresses margin pools for board manufacturers while favoring scaled producers capable of volume discounting and durability guarantees.
Pricing Analysis
Cost-down pressure on fiberglass board tiers accelerates because epoxy resin input volatility from petrochemical feedstock swings erodes manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates professional athlete specifications from rental fleet durability requirements and entry-level school equipment. Price differentiation hinges on carbon fiber grade certification and REACH compliance documentation for EU-bound shipments. Schools and rental services exhibit highest price sensitivity; sponsored professional athletes demonstrate lowest sensitivity to premium tier positioning.
Supply Chain Analysis
Composite technician skill scarcity in Thailand and Vietnam constrains quality-consistency at scale for hand-lamination operations serving global brands. Manufacturing concentrates in Chonburi province workshops and Vietnamese coastal fabrication zones that draw from T700 carbon fiber prepregs, PVC foam cores, and reformulated epoxy resin systems. Supply chain risk centers on REACH substance restriction timelines that force supply chain requalification. Distribution runs through specialty demo-capable retailers for initial equipment fitting, with online channels capturing replacement parts velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into carbon fiber prepreg sourcing and captive epoxy resin formulation capabilities defines the competitive race in windsurfing equipment manufacturing.
For Market Incumbents: Lock in rental fleet procurement relationships through multi-year durability guarantees and REACH compliance certification support. Incumbents should deepen in-house production of carbon fiber mast-boom combinations to defend against modular connector systems that decentralize brand ecosystem lock-in. Capacity addition in Thai manufacturing zones preserves cost position against Vietnamese workshop competition. For New Entrants and Emerging Players: Launch via direct-to-consumer online channels targeting aftermarket replacement parts in Southeast Asian beach destinations where specialty retail infrastructure remains underdeveloped. White-space concentration sits with modular mast-boom connector systems that enable cross-manufacturer interoperability. Penetrable entry points include school network procurement in Indonesia's emerging coastal tourism corridors. For Investors and Strategic Acquirers: The window for entry favors scaled composite manufacturers with captive laboratory capabilities for REACH compliance acceleration. Long-term viability hinges on circular economy positioning for end-of-life board recycling infrastructure. Acquisition target archetype: mid-scale Asian fabricators with established European brand partnerships. Signal to watch: EU Green Deal sustainability mandate implementation timelines for composite material recovery requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Sourcing | Captive T700 prepreg supply secures margin retention against commodity volatility for mast production. |
| REACH Compliance Certification Acceleration | In-house chemical management laboratories capture procurement preference from EU rental fleet operators. |
| Modular Connector System Development | Quick-release interfaces for mast-boom combinations respond to athlete demand for rapid rig reconfiguration. |
| School Network Consolidation Partnerships | Centralized fleet standardization in Jericoacoara and Cumbuco locks in recurring replacement cycles. |
| End-of-Life Recycling Infrastructure Investment | Early circular economy compliance creates supplier differentiation under EU Green Deal mandates. |
Study Parameters
Document review covered trade customs data for composite material imports, SEC filings from diversified watersports conglomerates, and ECHA substance restriction databases, complemented by interviews with equipment procurement managers at Brazilian rental fleet operators, composite R&D directors at Thai manufacturing facilities, and regulatory affairs leads navigating REACH compliance pathways. Bottom-up triangulation across school network purchasing patterns and top-down validation against coastal tourism infrastructure investment data anchored market sizing.
Cross-referencing historical equipment replacement cycles against expert panel input on carbon fiber adoption trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user operational model, distribution channel service intensity, and material compliance tier. CAGRs were derived from equipment utilization rate assumptions in trade wind corridors and rental fleet depreciation schedules.
The model assumes a particular technology adoption path for modular mast-boom connector systems; alternative pathways for quick-release interface standardization would alter the outlook for incumbent supplier replacement cycle predictability. Forecasts reflect assumptions around REACH implementation timelines and epoxy resin reformulation costs. Material deviation in EU Green Deal recycling mandate enforcement or petrochemical feedstock price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Crampon Market
Sports Equipment
Rowing Boats Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Wetsuits Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Quad Skate Market
Sports Equipment
Sports Devices Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Knee Pads Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Concussion Helmets Market