
 Running Gear Market | 2026-2036
Running Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Running Gear Market Intelligence
REACH is repositioning the European cost-of-entry calculus for running gear manufacturers, forcing reformulation of synthetic uppers and adhesives to meet restricted substance thresholds. Nike leverages vertical integration across Asian manufacturing clusters to absorb compliance costs without margin erosion. Adidas differentiates through R&D intensity in bio-based midsole foams, while Hoka One One anchors its premium positioning via proprietary cushioning architectures that command specialty retail placement.
Running gear encompasses footwear, apparel, and accessories engineered for locomotive biomechanics, with technical specifications spanning stack heights measured in millimeters, durometer ratings for foam density, and engineered mesh pore counts optimized for thermal regulation. Shoes dominate value capture due to amortized R&D across platform iterations and replacement-cycle frequency, though Smart Gear represents the fastest-growing technology segment as embedded sensors track cadence and ground-contact time for performance optimization. Amateur Runners constitute the largest end-user pool, while Professional Athletes concentrate margin through limited-edition sponsorship pipelines.
FDA oversight of medical-grade recovery wear, EPA scrutiny of perfluorinated water-repellent chemistries, and EU Green Deal circularity mandates collectively reshape material sourcing and end-of-life obligations for running gear producers. ISO standards for biomechanical testing provide baseline interoperability across regional certification regimes. Stakeholders must monitor evolving chemical restriction schedules and decide whether to front-load compliance investment or pursue geographic portfolio rebalancing.
Market Dynamics
Amateur runner participation is electrifying demand for accessible performance footwear, while REACH compliance and state-level chemical mandates in the US force simultaneous reformulation of synthetic uppers and adhesives across manufacturing networks.
Growth Catalysts
- REACH substance restrictions:European chemical thresholds are accelerating R&D investment in bio-based midsole foams and water-borne adhesives, creating first-mover advantages for certified suppliers.
- China marathon participation:Government-backed fitness campaigns and domestic race calendar expansion are amplifying volume demand for technical running footwear in tier-one and tier-two cities.
- Embedded sensor convergence:Smart Gear integration with cadence and ground-contact time analytics is opening premium pricing tiers among data-oriented amateur runners seeking biomechanical optimization.
Market Restraints
- Petrochemical input volatility:EVA and TPU foam feedstock costs fluctuate with crude oil indices, compressing margin predictability for midsole-intensive product lines.
- Asian manufacturing concentration:Over-reliance on clustered production zones in Vietnam and Indonesia creates geopolitical and logistics vulnerability without near-shore alternatives.
- Perfluorinated chemistry substitution:EPA scrutiny of PFAS water-repellent treatments forces rapid phase-out of proven durable water repellent formulations before bio-based replacements achieve parity.
Strategic Opportunities
- India fitness infrastructure:PLI scheme incentives for technical textiles and nascent marathon culture present early-entry positioning for performance apparel localization.
- Circular take-back programs:EU Green Deal extended producer responsibility mandates create competitive differentiation through certified recycling partnerships and material recovery streams.
- Direct-to-consumer biomechanics:AI-driven fit recommendation engines paired with 3D foot scanning are compressing traditional specialty retail intermediation in North American markets.
Industry Challenges
- Cross-functional talent scarcity:Hybrid expertise spanning polymer chemistry, sports biomechanics, and embedded systems engineering commands premium compensation and extended hiring timelines.
- Multi-jurisdiction certification lag:Simultaneous FDA medical-grade recovery wear review, EPA chemical safety substantiation, and EU notified body conformity assessment extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Running Gear Market |
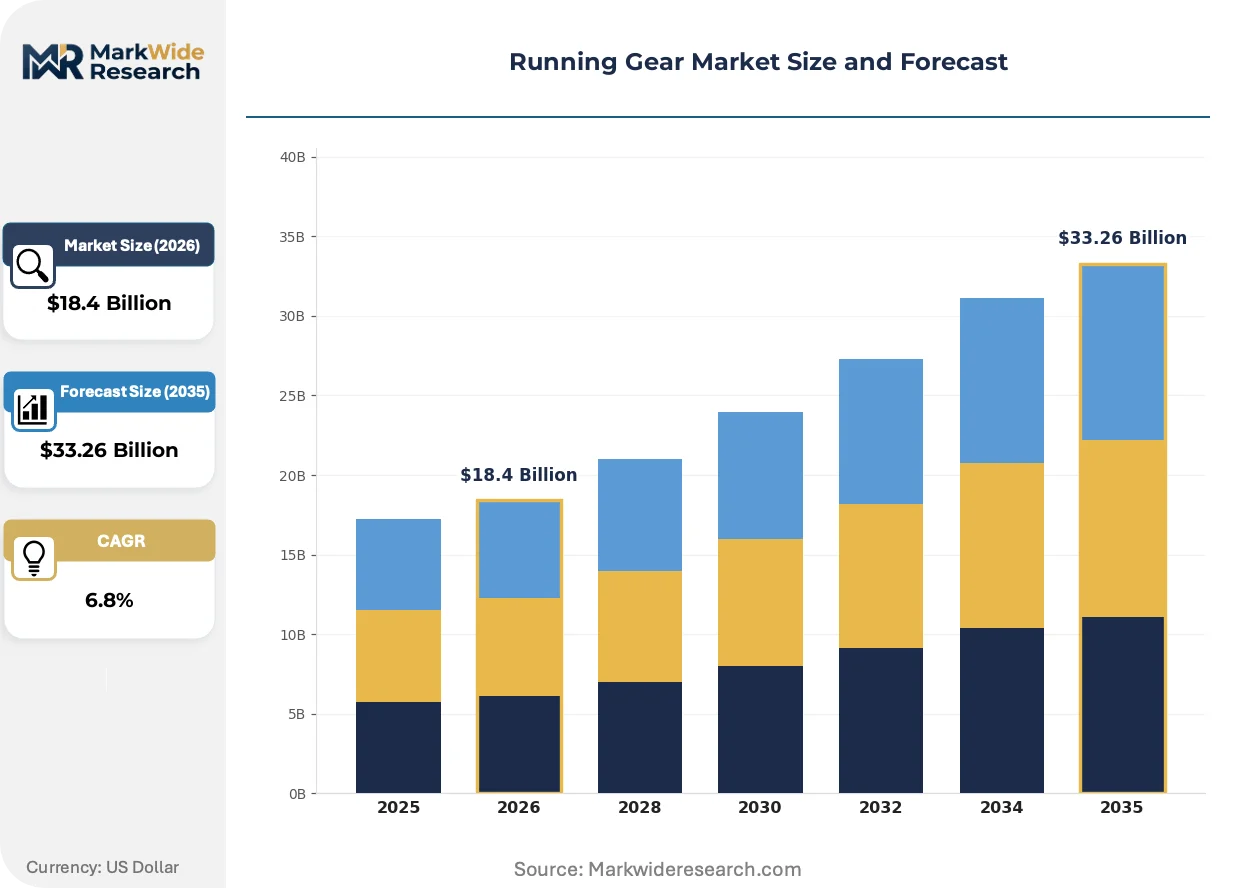
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Apparel, Accessories, Gear End User: Amateur Runners, Professional Athletes, Fitness Enthusiasts, Casual Joggers Material: Mesh, Synthetic, Leather, Cotton Technology: Breathable Fabrics, Cushioning Systems, Moisture-Wicking, Smart Gear |
| Companies Covered | New Balance, Hoka One One, Nike, Salomon, Saucony, Adidas, Brooks, On, Asics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Running Gear Market Strategic Shifts & Innovations
Technical specification convergence across stack height engineering, foam durometer tuning, and thermal-regulation mesh architecture is compressing product development cycles while elevating performance benchmarks for mass-market entrants.
Supercritical nitrogen-infused midsole foams are electrifying cushioning-to-weight ratios across racing and daily training categories. Amateur runners seeking marathon qualification times are adopting these platforms at accelerating replacement frequencies. The technology is electrifying specialty retail placement negotiations as brands compete for limited shelf space with demonstrable energy-return metrics.
EU Green Deal circularity mandates are mandating recycled content minimums and end-of-life take-back infrastructure for running gear placed on European markets. Producers must reconfigure supply chains to incorporate post-industrial and post-consumer polyester streams at scale. Footwear categories face the steepest compliance curves due to multi-material construction complexity and adhesive separation challenges.
Subscription-based refresh models are displacing traditional ownership patterns among high-mileage amateur runners in US metropolitan markets. Specialty run shops and direct-to-consumer platforms are piloting wear-tracking-enabled replacement programs. California and New York clusters show the highest adoption density, driven by convenience preference and sustainability signaling among urban professionals.
Running Gear Market Segmentation
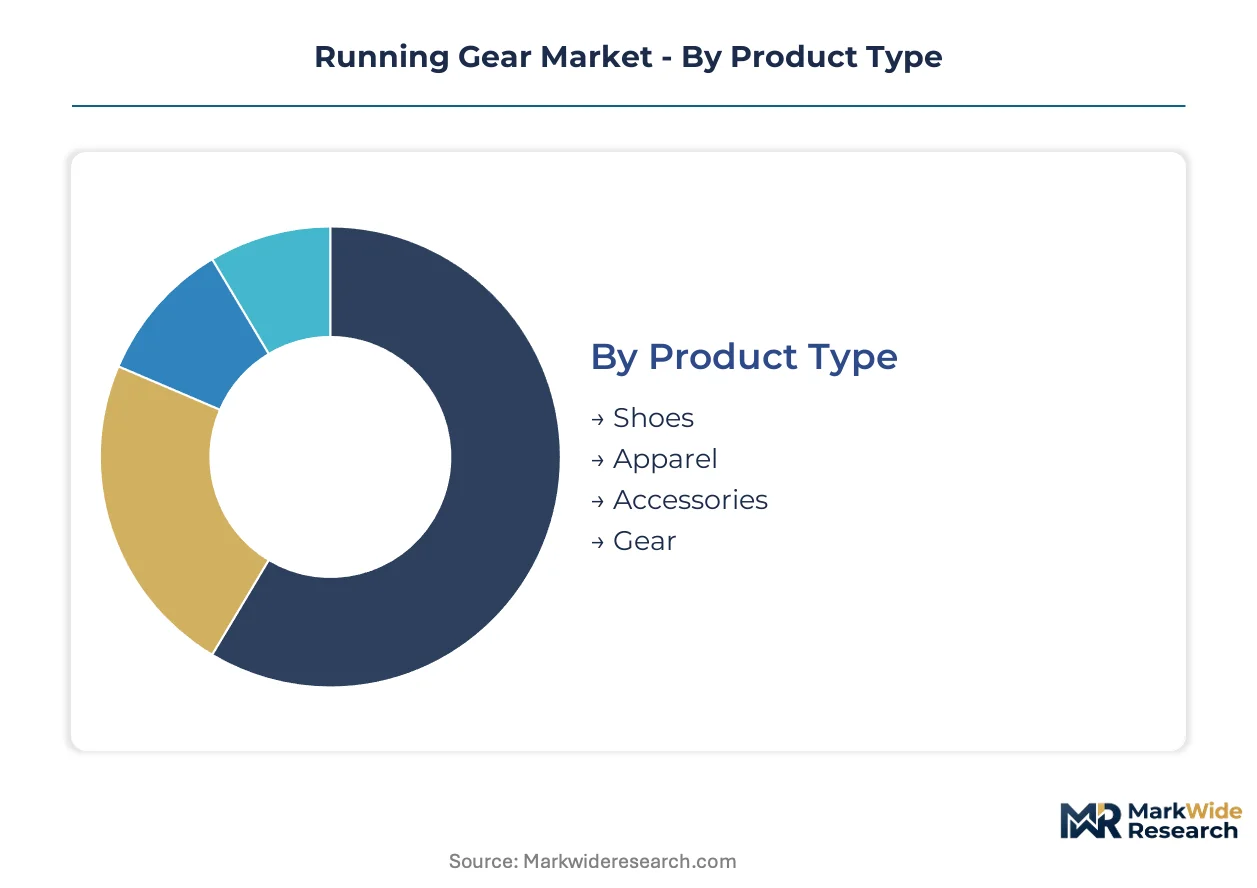
Running gear manufacturers engineer distinct product architectures for biomechanical load profiles, thermal regulation needs, and replacement-cycle frequencies. Segmentation discipline separates marathon-grade cushioning platforms from casual lifestyle hybrids, each commanding different margin structures and retail channel placement.
Product Type:
Replacement cycles vary dramatically by category, with technical footwear amortizing R&D across platform iterations while apparel refreshes on seasonal colorways.
- Shoes:Midsole stack heights, foam durometer ratings, and engineered mesh pore counts define performance tiers. Amateur runners in China drive volume through government-backed fitness campaigns and expanding domestic race calendars.
- Apparel:Compression-grade recovery wear and thermal-regulation layers span training and racing applications. FDA oversight of medical-grade recovery classifications elevates certification costs for US-market compression garments.
- Accessories:Hydration belts, reflective safety gear, and performance socks complete the technical kit. Demand concentrates among high-mileage amateur runners seeking marathon qualification times.
- Gear:GPS watches, heart rate monitors, and training accessories extend the ecosystem. Embedded sensor convergence with cadence analytics opens premium pricing tiers.
Shoes sits at the top of the volume ranking, with Smart Gear climbing the fastest.
End User:
Customer lifetime value spreads across participation intensity, from single-marathon aspirants to daily training devotees.
- Amateur Runners:Recreational participation surged post-pandemic, creating the fastest-expanding demand pool. Tier-one and tier-two Chinese cities amplify volume through domestic marathon participation growth.
- Professional Athletes:Limited-edition sponsorship pipelines and podium-seeding contracts concentrate margin. Bio-based midsole foam R&D validates performance claims for elite placement.
- Fitness Enthusiasts:Cross-training versatility demands hybrid cushioning suitable for treadmill, trail, and road surfaces. Subscription-based refresh models gain traction in California and New York metropolitan clusters.
- Casual Joggers:Lifestyle-adjacent purchases prioritize aesthetic versatility over technical specification. Price sensitivity shapes mass-market retail placement decisions.
Amateur Runners dominates absolute volume, with Fitness Enthusiasts gaining share fastest through hybrid training adoption.
Material:
REACH compliance and EPA scrutiny of perfluorinated chemistries force simultaneous reformulation across synthetic upper and adhesive supply chains.
- Mesh:Engineered pore architectures optimize thermal regulation and moisture evacuation. Post-industrial and post-consumer polyester streams reconfigure supply chains under EU Green Deal circularity mandates.
- Synthetic:TPU and EVA foam feedstocks fluctuate with crude oil indices, compressing margin predictability. Water-borne adhesive substitution accelerates under restricted substance thresholds.
- Leather:Premium racing flats and lifestyle retro releases employ full-grain or synthetic leather uppers. Sourcing concentrates in certified tanneries with traceable hide provenance.
- Cotton:Natural fiber comfort layers and casual lifestyle silhouettes employ combed or organic cotton blends. India PLI scheme incentives for technical textiles present localization opportunities.
Synthetic commands the largest material share, with Mesh expanding most quickly under recycled content minimums.
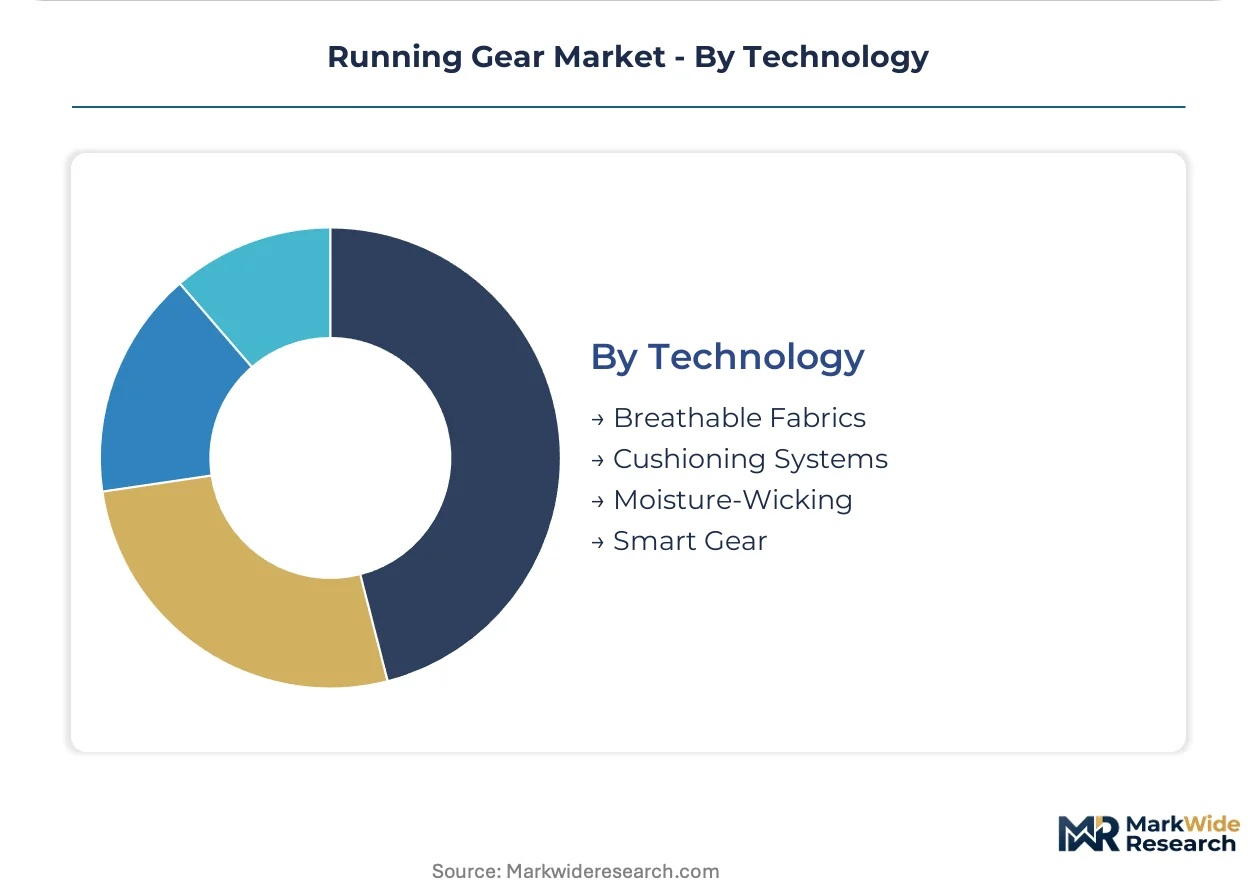
Technology:
Performance differentiation now converges on measurable biomechanical outcomes rather than aesthetic branding alone.
- Breathable Fabrics:Engineered mesh and knit uppers manage heat dissipation during high-output efforts. Thermal regulation specifications separate training-grade from racing-grade platforms.
- Cushioning Systems:Supercritical nitrogen-infused midsole foams electrify cushioning-to-weight ratios. Energy-return metrics drive specialty retail placement negotiations.
- Moisture-Wicking:Capillary-action polyester and merino wool blends maintain thermoregulation across humidity conditions. PFAS water-repellent phase-outs force bio-based replacement development.
- Smart Gear:Embedded sensors track cadence, ground-contact time, and vertical oscillation for biomechanical optimization. AI-driven fit recommendation engines compress traditional specialty retail intermediation.
Cushioning Systems anchors technology value capture, with Smart Gear posting the steepest expansion trajectory among data-oriented amateurs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist biomechanical engineers and polymer chemists concentrate in Germany's technical universities and China's manufacturing clusters, anchoring R&D and production capacity respectively.
United States
Amateur runner participation surged post-pandemic in California and New York metropolitan clusters. EPA scrutiny of PFAS water-repellent chemistries forces rapid reformulation of durable water repellent treatments. Specialty run shops in Austin and Boulder pilot subscription-based refresh models with wear-tracking-enabled replacement programs.
China
Domestic marathon participation amplifies volume demand for technical footwear in tier-one and tier-two cities. Government-backed fitness campaigns under national dual carbon goals promote mass participation events. Manufacturing clusters in Fujian and Guangdong provinces concentrate supercritical nitrogen-infused foam production for export markets.
Germany
REACH compliance elevates material certification costs for synthetic uppers and water-borne adhesives. ECHA substance restrictions accelerate R&D investment in bio-based midsole formulations. Industrial fabricators in Bavaria and Baden-Württemberg specialize in precision-engineered mesh architectures for thermal regulation.
India
Nascent marathon culture in Mumbai and Bengaluru creates early-entry positioning for performance apparel localization. PLI scheme incentives for technical textiles attract domestic manufacturing investment. Maharashtra and Gujarat states concentrate cotton-blend recovery wear production for export to Middle Eastern markets.
Japan
High-mileage amateur runners in Tokyo and Osaka adopt Smart Gear with embedded cadence sensors at accelerating rates. METI standards for wearable device interoperability shape product development specifications. Kansai region manufacturers specialize in precision cushioning systems for racing flat categories.
Running Gear Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered pricing strata. Consolidation concentrates around vertically integrated manufacturers with captive Asian production networks and heritage sportswear houses with deep specialty retail relationships. Three archetypes dominate: scale-driven platform licensors, biomechanical innovation specialists, and regional heritage brands with cult enthusiast followings. Capacity expansion in Vietnam and Indonesia clusters and strategic partnerships with recycled polyester stream suppliers constitute the dominant competitive moves.
Within the heritage-performance tier, New Balance and Brooks exemplify manufacturing-scale anchoring with domestic US production lines. Asics occupies a position bridging technical innovation and mass-market accessibility across Asian and European markets. Hoka One One represents the biomechanical-specialist archetype through proprietary cushioning architectures that command premium specialty retail placement.
| Leading Market Players |
|---|
| New Balance |
| Hoka One One |
| Nike |
| Salomon |
| Saucony |
| Adidas |
| Brooks |
| On |
| Asics |
| Others |
Cost & Logistics Intelligence
Captive Asian manufacturing networks anchor supply positions for major running gear producers while simultaneously underwriting pricing power through controlled input costs and platform amortization. This integration choice insulates margin structures from petrochemical volatility but concentrates geopolitical exposure in clustered production zones.
Pricing Analysis
Bundled subscription refresh models are displacing unbundled transactional purchases among high-mileage amateur runners in US metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels separates supercritical nitrogen-infused platforms from conventional EVA midsoles and entry-level lifestyle silhouettes. Pricing pressure stems from REACH compliance costs elevating material certification thresholds for European market entry. Casual joggers exhibit highest price sensitivity while marathon-qualification amateurs accept premium positioning for demonstrable energy-return metrics.
Supply Chain Analysis
EVA and TPU foam feedstock supply rests on petrochemical complexes in China, South Korea, and Saudi Arabia with pricing indexed to crude oil benchmarks. Engineered mesh architectures draw from polyester fiber producers in Taiwan and Vietnam under EU Green Deal recycled content mandates. Single-source vulnerability concentrates in supercritical nitrogen-injection equipment suppliers clustered in Germany and Japan. Distribution runs through specialty run shops in North America, direct-to-consumer platforms in China, and sporting goods retail chains across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based midsole foam substitution that commands premium placement while deflecting REACH-driven cost compression.
For Market Incumbents: Hedge against Asian manufacturing concentration by piloting near-shore assembly in Mexico or Portugal for European and North American demand clusters. Accelerate water-borne adhesive certification to preempt EPA PFAS phase-out deadlines. Defensive consolidation around recycled polyester stream suppliers locks in EU Green Deal compliance capacity before 2030 mandates tighten. For New Entrants and Emerging Players: Launch via direct-to-consumer biomechanics platforms pairing AI fit engines with 3D foot scanning to compress specialty retail intermediation. Target India's nascent marathon culture in Mumbai and Bengaluru before PLI scheme incentives attract established competitors. White-space exists in medical-grade recovery wear where FDA oversight elevates certification barriers for unqualified entrants. For Investors and Strategic Acquirers: Consolidation pressure builds where bio-based R&D capabilities concentrate among mid-tier specialists lacking scale to absorb REACH compliance costs. Long-term viability favors vertically integrated manufacturers with captive foam production and certified recycling partnerships. Watch cadence-tracking Smart Gear adoption rates among Japanese high-mileage amateurs as inflection indicator for premium technology penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Midsole Certification | REACH compliance creates first-mover advantage for ECHA-validated foam suppliers in European markets. |
| Recycled Polyester Integration | EU Green Deal mandates reconfigure supply chains around post-consumer stream partnerships. |
| Direct-to-Consumer Biomechanics | AI fit engines displace specialty retail intermediation in California and New York clusters. |
| Near-Shore Assembly Pilot | Geographic diversification mitigates Vietnam-Indonesia concentration risk for North American demand. |
| Smart Gear Platform Launch | METI interoperability standards shape embedded sensor development for Japanese amateur runners. |
Research Approach
Direct dialogue with brand R&D directors, specialty retail buyers, polymer chemists at foam suppliers, and marathon event organizers grounded qualitative insights in operational reality. Secondary validation drew from customs trade data, SEC footwear sector filings, ECHA substance restriction schedules, and marathon participation databases. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmented outputs across product type, end-user participation intensity, material composition, and technology integration informed the analytical framework. CAGRs derived from replacement-cycle frequency analysis, government fitness campaign trajectories, and embedded sensor adoption curves. Supercritical nitrogen-infusion capacity expansion and REACH substance restriction timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spikes or accelerated PFAS regulatory phase-outs. Assumptions reflect documented participation trends, compliance cost trajectories, and supply chain concentration patterns. A small set of named triggers—marathon cancellation rates, ECHA substance list expansions, and Smart Gear interoperability standard adoptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Slam Ball Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Global Darts Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Sandbells Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Global Basketball Shoes Market