
 Cricket Equipment Market | 2026-2036
Cricket Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cricket Equipment Market Analysis
The capital-intensity divergence between bat manufacturers and protective-gear specialists is redrawing competitive boundaries across the cricket equipment landscape. Gunn & Moore leverages its English willow supply chain to sustain premium positioning in hand-crafted bats. Kookaburra Sport Pty Ltd anchors Australasian demand through its dominance of leather ball supply to international boards. Sanspareils Greenlands competes on manufacturing scale, controlling volume production of Kashmir willow bats for price-sensitive Asian markets.
Cricket equipment encompasses bats, balls, protective gear, and apparel engineered to withstand impact velocities exceeding 160 km/h while conforming to mass and dimension standards set by the Marylebone Cricket Club. Bats require pressed willow clefts with specific moisture content and grain structure to balance power transfer with durability. Protective gear commands the fastest growth as helmet and pad innovations address concussion protocols and evolving bowling speeds. Composite materials in bat handles and protective equipment concentrate margin pools through premium pricing tied to performance claims. Distribution through specialty shops retains importance for custom fitting, though online retail extends reach into secondary cricket markets.
ISO standards for sports equipment safety, BIS grading mandates for Indian-manufactured bats, and ECB helmet compliance rules shape product design and market access across producer nations. Regulatory divergence between willow certification regimes and synthetic material approvals complicates cross-border sourcing strategies for multinational suppliers. Stakeholders must monitor how concussion-safety mandates reshape protective-gear specifications and whether carbon-fiber adoption triggers new equipment-category definitions from standards bodies.
Market Dynamics
Composite material adoption is fragmenting the traditional willow-dominated bat supply chain, forcing established manufacturers to reconfigure production lines while BIS certification mandates reshape competitive access across Indian manufacturing clusters.
Growth Catalysts
- Franchise league expansion:Professional T20 tournaments in India, England, and Australia accelerate equipment replacement cycles as franchise academies standardize gear procurement for developmental squads.
- Concussion protocol mandates:ECB helmet compliance rules and Cricket Australia safety standards are mandating protective gear upgrades across competitive levels, pulling demand for certified helmets and chest guards.
- Urban academy proliferation:Cricket coaching centers in Mumbai, Lahore, and Melbourne are concentrating junior player development, creating institutional bulk purchasing channels for mid-tier equipment.
Market Restraints
- English willow supply concentration:Bat-grade Salix alba clefts depend on a narrow East Midlands supplier base, exposing manufacturers to harvest volatility and climate-induced yield fluctuations.
- Kashmir willow quality ceiling:Density variations in Himalayan willow limit power transfer efficiency, constraining price-competitive bats from penetrating performance-seeking segments.
- Leather ball cost structure:Alum-tanned hide processing and cork-center manufacturing concentrate input costs with Australian and Pakistani tanneries, compressing margin flexibility for ball suppliers.
Strategic Opportunities
- Secondary market penetration:Cricket's emergence in Nepal, the Netherlands, and the United States creates equipment demand outside traditional Commonwealth supply networks.
- Smart sensor integration:Embedded accelerometers in bat handles and protective gear are converging with mobile analytics platforms, enabling swing analysis and impact monitoring services.
- Direct-to-academy distribution:Bypassing traditional retail through institutional procurement portals reduces margin leakage and captures volume commitments from coaching chains.
Industry Challenges
- Artisan bat-maker succession gaps:Hand-pressing and grain-grading expertise concentrates with aging craftspeople in Nottinghamshire and Kashmir, constraining quality-controlled scale expansion.
- Multi-standard compliance complexity:Manufacturers serving India, England, and Australia simultaneously face divergent BIS, ECB, and Cricket Australia certification timelines and testing protocols.
- Composite R&D capex intensity:Carbon-fiber handle development and polymer pad engineering require dedicated materials labs, favoring capitalized incumbents over traditional wood specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cricket Equipment Market |
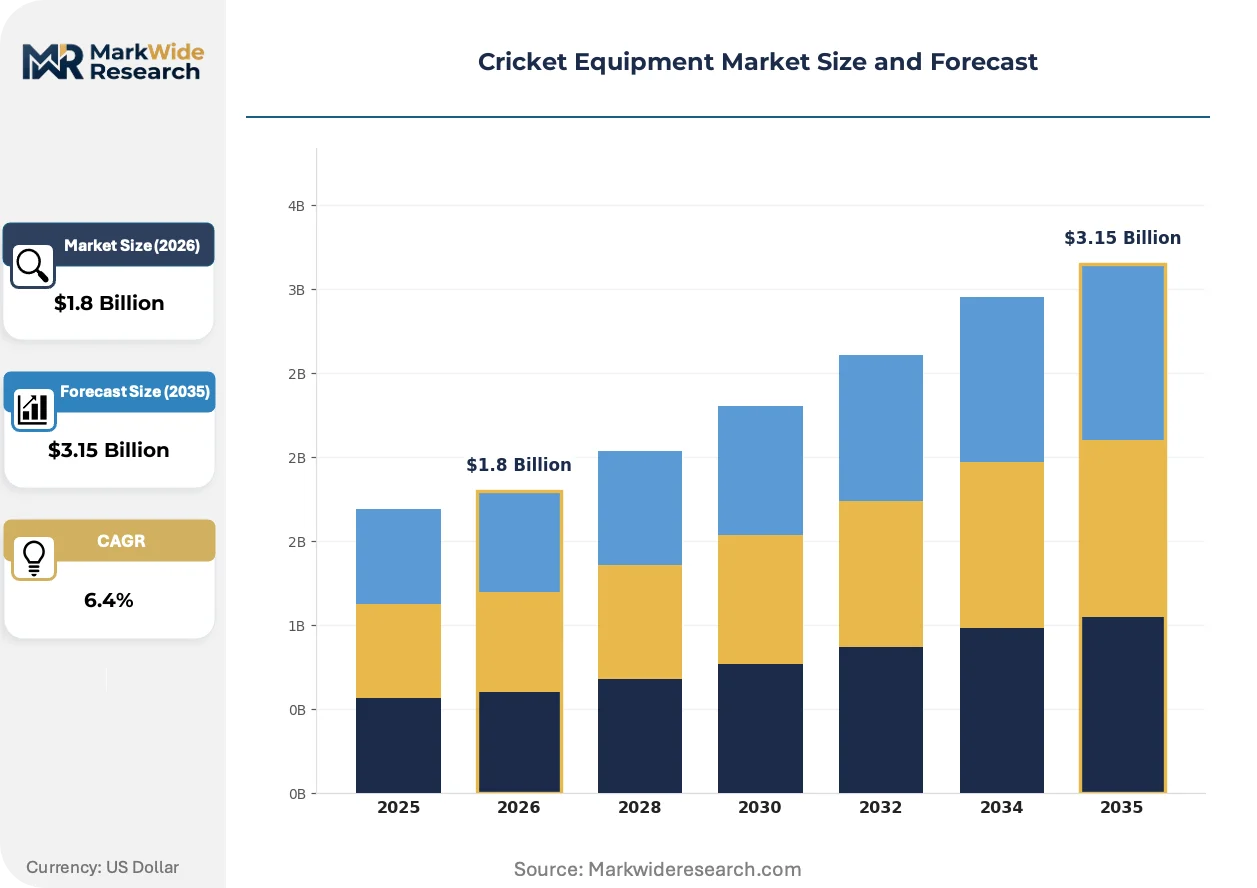
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bats, Balls, Protective Gear, Clothing End User: Amateur Players, Professional Players, Coaches, Clubs Distribution Channel: Online Retail, Sports Stores, Specialty Shops, Direct Sales Material: Wood, Synthetic, Leather, Composite |
| Companies Covered | Adidas AG, Gunn & Moore, Kookaburra Sport Pty Ltd, Sareen Sports Industries, Sanspareils Greenlands, Grays International, PUMA SE, New Balance Athletics Inc., Nike Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cricket Equipment Market Emerging Trajectories
Material science advances and safety mandates are compressing product development cycles while reshaping how equipment reaches end-users. Three forces are reconfiguring competitive positioning across bat manufacturing, protective gear, and distribution architecture.
Carbon-fiber reinforcement is penetrating bat handle construction to dampen vibration transmission without mass penalty. Elite players in Indian Premier League academies are adopting hybrid-handle designs at accelerating rates. This composite intrusion is miniaturizing the performance gap between premium English willow and mid-tier Kashmir alternatives.
India's BIS grading mandates for bat density and moisture content are forcing export-oriented manufacturers toward standardized curing protocols. Compliance investments are filtering smaller Kashmir willow processors from institutional supply chains. Domestic Indian brands with captive pressing facilities are capturing share from ungraded import competitors.
Specialty cricket retailers are losing ground to direct manufacturer portals and academy procurement aggregators. Urban coaching centers in Bangalore and Sydney now negotiate annual equipment contracts bypassing traditional pro shops. This channel compression is most visible in protective gear, where bulk helmet and pad purchases concentrate purchasing power with institutional buyers.
Cricket Equipment Market Segmentation
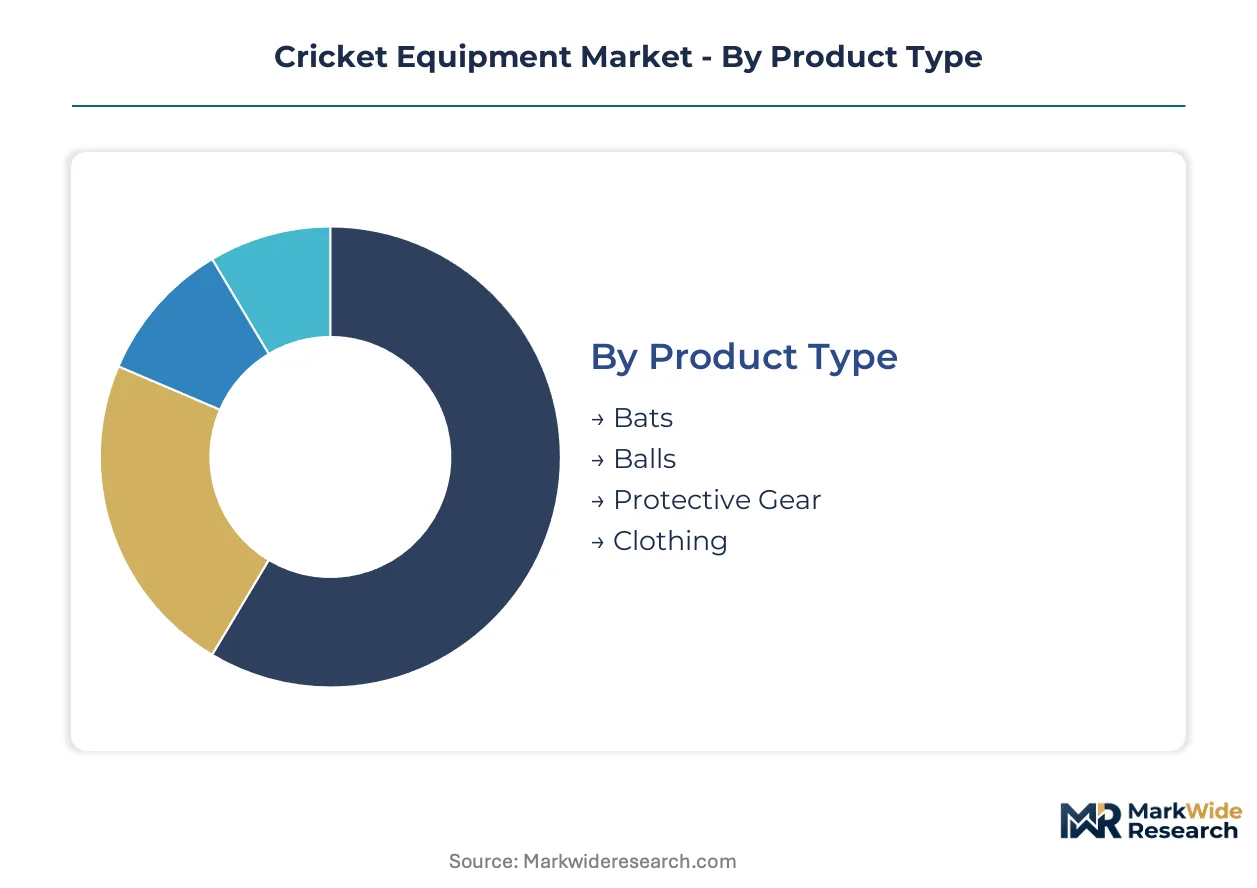
Segmentation in cricket equipment reveals how procurement authority concentrates with institutional buyers versus individual consumers. Channel preferences diverge sharply between premium hand-crafted bats and volume protective gear. Material certification requirements further stratify supply access across amateur and professional tiers.
Product Type:
Specialty shops dominate bat sales due to custom pressing and grain inspection requirements, while protective gear flows through academy procurement portals and online retail for standardized sizing.
- Bats:Pressed willow clefts with calibrated moisture content and straight grain orientation determine power transfer efficiency. Demand clusters in Indian urban academies and English county clubs where BIS and ECB grading mandates drive replacement cycles. Franchise league standardization accelerates volume procurement from certified suppliers.
- Protective Gear:Helmets, pads, and chest guards engineered to absorb impact velocities exceeding 160 km/h. Concussion protocol mandates from Cricket Australia and ECB are forcing upgrades across competitive levels in Sydney and London metropolitan leagues. Composite material adoption is displacing traditional cane and leather construction in high-performance segments.
- Balls:Alum-tanned leather with cork centers meeting international board specifications for seam retention and bounce consistency.
- Clothing:Moisture-wicking polyester blends and traditional whites serving club and professional kit requirements.
By volume, protective gear leads. By growth pace, bats with composite handles are climbing the fastest.
End User:
Cost tier stratification separates premium equipment for professionals from price-accessible lines for development programs.
- Professional Players:Custom-fitted bats with hand-pressed English willow and certified protective gear meeting international board standards. Sponsorship arrangements with manufacturers like Gunn & Moore and Kookaburra concentrate gear allocation through franchise contracts in Indian Premier League and Big Bash League systems.
- Amateur Players:Kashmir willow bats and standardized protective gear dominating volume sales. Urban academy enrollment in Mumbai, Lahore, and Melbourne creates institutional purchasing channels that bypass retail markup.
- Coaches:Training equipment including bowling machines and fielding aids procured through direct manufacturer relationships.
- Clubs:Bulk helmet and pad purchases negotiated through annual equipment contracts with protective-gear specialists.
Amateur players generate the highest unit volume. Professional segments command the steepest expansion trajectory as franchise league expansion deepens.
Distribution Channel:
Volume concentration favors direct sales to academy chains, while margin capture remains strongest in specialty shops for premium bats.
- Online Retail:Standardized protective gear and entry-level bats reaching secondary cricket markets in Nepal, the Netherlands, and the United States. Platform logistics bypass traditional Commonwealth supply network limitations.
- Sports Stores:Mid-tier equipment serving recreational players with limited custom fitting capabilities.
- Specialty Shops:Hand-crafted bat sales requiring grain inspection and weight balancing. Nottinghamshire and Kashmir artisan networks maintain channel relevance through pressing expertise concentration.
- Direct Sales:Academy procurement portals capturing volume commitments from coaching chains in Bangalore and Sydney. Institutional buyers negotiate annual helmet and pad contracts that compress traditional retail margins.
Direct sales channels are gaining share fastest. Specialty shops retain pricing power in premium bat segments.
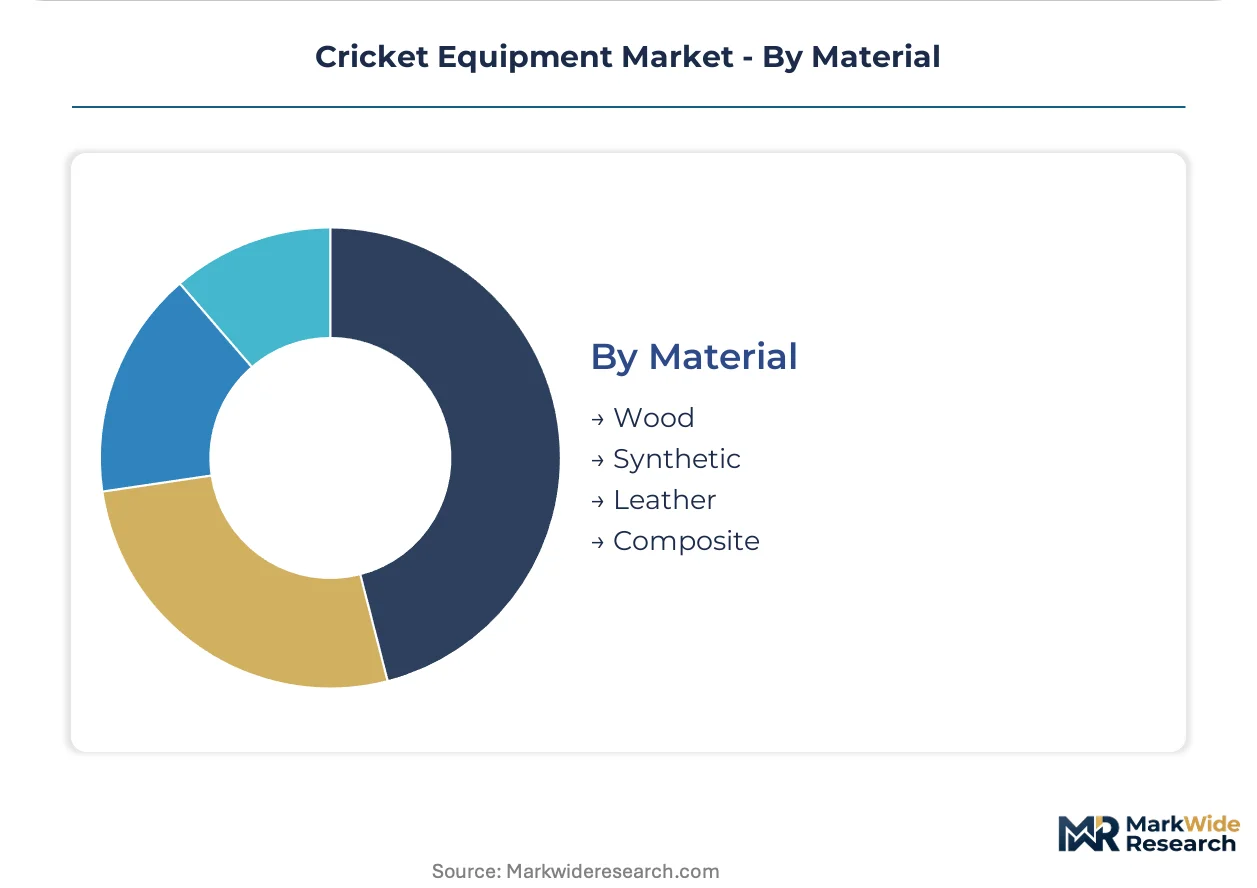
Material:
Supply concentration for bat-grade willow in East Midlands and Himalayan regions dictates sourcing strategies across manufacturer tiers.
- Wood:Salix alba clefts from English and Kashmir willow sources. Density variations between East Midlands and Himalayan harvests create performance tiering that BIS grading mandates now formalize for Indian-manufactured bats.
- Composite:Carbon-fiber reinforced bat handles and polymer-based protective components. R&D capex requirements favor capitalized incumbents over traditional wood specialists.
- Leather:Alum-tanned hide for ball covers sourced from Australian and Pakistani tanneries.
- Synthetic:Polyurethane and polymer alternatives in training equipment and entry-level protective gear.
Wood dominates current volume. Composite materials are expanding most quickly as vibration-dampening technology penetrates elite player segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands pricing power through volume scale while England retains margin capture through artisan scarcity. This asymmetry shapes how manufacturers configure regional supply strategies across Commonwealth and emerging cricket markets.
India
Urban academies in Mumbai and Bangalore drive replacement cycles for protective gear and performance bats. BIS grading mandates for bat density and moisture content force export-oriented manufacturers toward standardized curing protocols. Meerut and Jalandhar manufacturing clusters concentrate Kashmir willow processing for price-sensitive domestic and Asian export markets.
England
County cricket clubs and franchise academies sustain demand for hand-pressed English willow bats. ECB helmet compliance rules mandate protective gear upgrades across competitive levels in London and Birmingham metropolitan leagues. Nottinghamshire retains artisan networks where hand-pressing and grain-grading expertise concentrates with aging craftspeople.
Australia
Big Bash League expansion accelerates equipment replacement cycles through franchise academy standardization. Cricket Australia safety standards pull demand for certified helmets and chest guards across Sydney and Melbourne coaching centers. Ball manufacturing concentrates with Australian tanneries supplying alum-tanned leather to international boards.
Pakistan
Lahore and Sialkot manufacturing clusters produce leather balls and protective gear for Middle East and Asian export markets. Pakistani tanneries supply alum-tanned hide processing that concentrates input costs for cork-center ball manufacturing. Urban academy proliferation in Karachi creates institutional bulk purchasing channels for mid-tier equipment.
United States
Cricket's emergence in Texas and California creates equipment demand outside traditional Commonwealth supply networks. Platform logistics through online retail bypass established distribution limitations for entry-level bats and standardized protective gear. Houston and Los Angeles metropolitan areas concentrate South Asian diaspora communities driving grassroots club formation.
Cricket Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cricket equipment landscape. The market structures around a tiered configuration where premium bat artisans, volume protective-gear specialists, and diversified sporting goods conglomerates occupy distinct competitive spaces. Three strategic archetypes dominate: hand-crafted willow specialists leveraging East Midlands supply chains, composite-material innovators capturing margin through performance claims, and scale manufacturers controlling Kashmir willow production for price-sensitive segments. Dominant competitive moves include direct-to-academy distribution bypassing traditional retail channels and carbon-fiber R&D investments favoring capitalized incumbents.
Within the willow-specialist tier, Gunn & Moore and Sanspareils Greenlands exemplify divergent sourcing strategies. Kookaburra Sport Pty Ltd anchors Australasian positioning through leather ball supply relationships with international boards. These three companies represent how geographic supply concentration—English willow in Nottinghamshire, Kashmir willow in Meerut-Jalandhar, Australian leather in Melbourne—translates into defensible competitive positioning without requiring vertical integration into raw material production.
| Leading Market Players |
|---|
| Adidas AG |
| Gunn & Moore |
| Kookaburra Sport Pty Ltd |
| Sareen Sports Industries |
| Sanspareils Greenlands |
| Grays International |
| PUMA SE |
| New Balance Athletics Inc. |
| Nike Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Meerut-Jalandhar pressing facilities shapes both supply concentration and price floors for Kashmir willow bats. BIS certification investments filter smaller processors from institutional channels, compressing margin flexibility for ungraded competitors while elevating certified manufacturers into premium procurement tiers.
Pricing Analysis
Configured-to-order pricing for hand-pressed English willow bats commands substantial premiums over standardized Kashmir willow alternatives. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and grain density. Cost compression in entry-level Kashmir willow is intensifying because BIS compliance investments concentrate production with capitalized incumbents. Amateur academy players in Mumbai and Lahore exhibit highest price sensitivity, while IPL franchise procurement officers prioritize performance certification over unit cost.
Supply Chain Analysis
England and India anchor bat-grade willow supply, with East Midlands clefts feeding premium hand-crafters and Himalayan harvests supplying volume manufacturers. Raw material dependencies center on Salix alba density grading, alum-tanned leather for ball covers, and carbon-fiber prepreg for composite handle development. Single-source vulnerability concentrates in Nottinghamshire artisan networks where hand-pressing expertise rests with aging craftspeople. Distribution runs through direct-to-academy portals for protective gear and specialty pro shops for custom bat fitting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. BIS grading mandates and ECB helmet compliance rules create certification barriers that favor incumbents with established testing relationships and captive curing facilities.
For Market Incumbents: Shield English willow supply relationships through long-term cleft offtake agreements with East Midlands growers, insulating against harvest volatility. Accelerate carbon-fiber R&D investments to capture composite handle margins before mid-tier manufacturers achieve materials lab scale. Certification entrenchment represents the priority defensive lever against ungraded import competitors.
For New Entrants and Emerging Players: Differentiate on smart sensor integration for swing analytics and impact monitoring, bypassing saturated willow supply chains. Target the United States secondary market where online retail logistics bypass established Commonwealth distribution networks. Direct-to-academy distribution partnerships with Texas and California coaching chains offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite-material innovators with dedicated R&D facilities over traditional wood specialists facing artisan succession gaps. Long-term viability hinges on carbon-fiber adoption rates penetrating elite player segments and concussion-safety mandates expanding protective gear replacement cycles. Watch for Cricket Australia or ECB protocol revisions mandating embedded sensor compliance as the inflection indicator for smart equipment valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Academy Distribution Portal Launch | Bypasses retail margin leakage while capturing volume commitments from Bangalore and Sydney coaching chains. |
| Carbon-Fiber Handle R&D Investment | Captures vibration-dampening premiums as IPL academies accelerate hybrid bat adoption. |
| BIS Certification Compliance Program | Filters ungraded competitors from Indian institutional supply chains, consolidating market share. |
| Smart Sensor Platform Integration | Enables swing analytics services converging with mobile performance monitoring applications. |
| Secondary Market Online Retail Expansion | Reaches Nepal, Netherlands, and United States demand outside traditional Commonwealth networks. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with equipment manufacturers, academy procurement officers, and BIS certification auditors, combined with secondary validation against customs trade records, BIS grading registries, and ECB compliance filings. Stakeholder conversations spanned bat press operators in Nottinghamshire, protective gear R&D directors at composite materials labs, and franchise equipment managers across IPL and Big Bash League systems. Bottom-up equipment shipment data triangulated against top-down market sizing from retail channel audits.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user tier, distribution channel, and material composition. CAGRs derived from historical replacement cycle analysis, franchise league expansion trajectories, and concussion protocol adoption curves. Forecast inputs incorporated BIS certification timeline assumptions and composite materials penetration rates among elite academy players.
Decision-makers should treat outputs as directional under sustained franchise league investment and stable willow harvest yields; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in regulatory protocol mandates and secondary market cricket participation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Golf Club Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Football Market
Sports Equipment
Trail Shoes Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Europe Artificial Grass Market