
 Bicycle Crankset Market | 2026-2036
Bicycle Crankset Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Crankset Market Insights
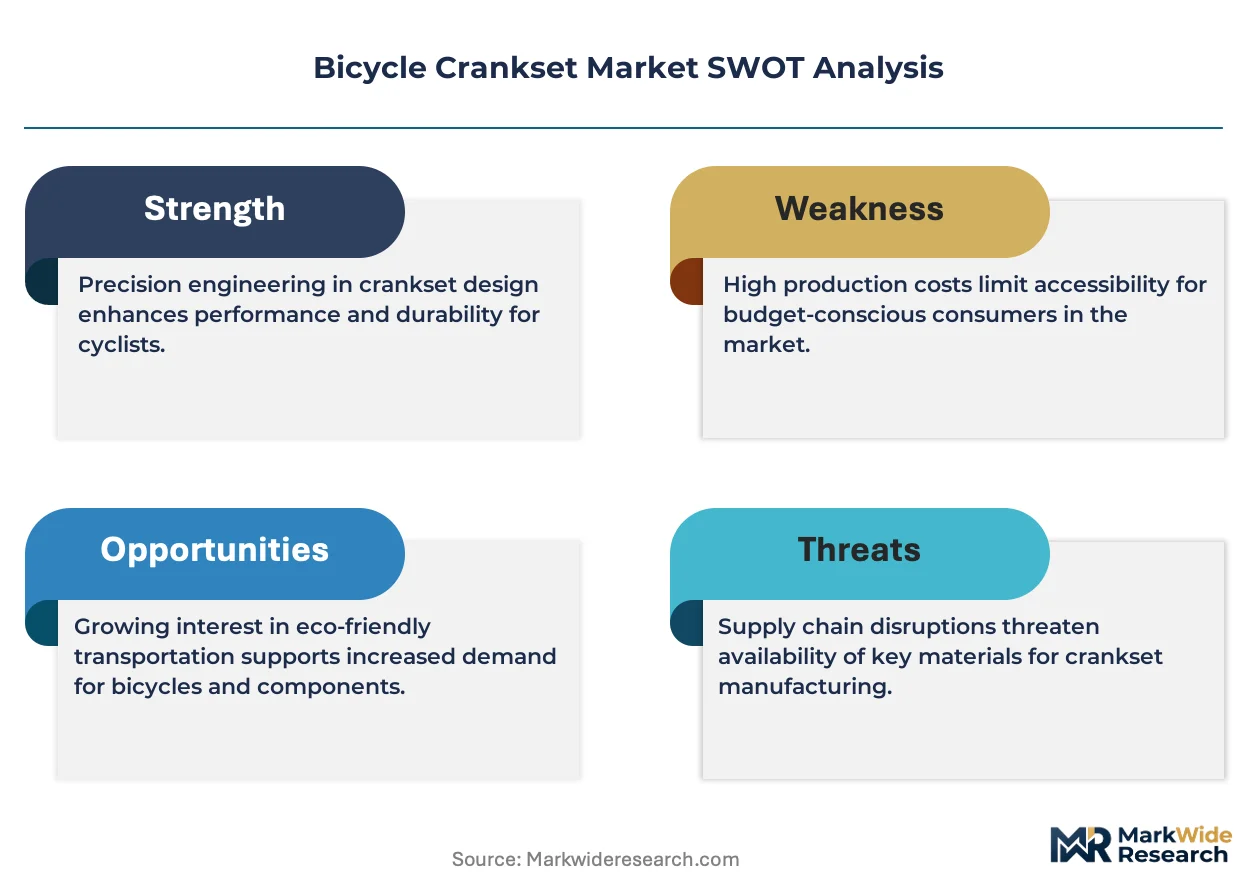
Buyer concentration among e-bike OEMs is restructuring traditional aftermarket dynamics toward frame-integrated specifications. Shimano Inc. leverages its Hollowtech forging expertise to dominate OEM supply agreements with European assemblers. SRAM LLC anchors its position through electronic gear system integration that commands premium placement on performance e-bikes. Campagnolo differentiates via Italian-made titanium and carbon fiber crank arms that sustain loyalty among professional road cycling teams.
A bicycle crankset converts reciprocating leg motion into rotational drive through chainring-mounted spindle assemblies, typically engineered to 24mm or 30mm axle diameters with 170mm to 175mm arm lengths for biomechanical efficiency. Aluminum forged crank arms with CNC-machined spider interfaces remain the industrial standard for mid-tier production, while carbon fiber layup construction penetrates professional racing applications where gram reduction justifies cost multiples. Multi Speed configurations lead volume shipments across commuter and mountain bike platforms, whereas Electronic gear systems capture expanding margin pools as battery-assisted shifting migrates from road racing to gravel and urban segments. Hollowtech spindle designs concentrate R&D investment among tier-one suppliers seeking stiffness-to-weight optimization.
ISO 4210 frame and component safety standards govern fatigue testing protocols, while EU REACH restrictions on hexavalent chromium plating force suppliers toward PVD and anodized surface finishes. Japan's JIS standards and METI circular economy guidelines shape export compliance requirements for Asian-manufactured cranksets entering European markets. Stakeholders must monitor regulatory divergence between EU chemical compliance and North American CPSC mechanical safety criteria when configuring multi-region product platforms.
Market Dynamics
E-bike OEM procurement consolidation is forcing crankset suppliers to abandon aftermarket distribution in favor of frame-integrated development partnerships with assemblers in Germany and the Netherlands.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in manufacturing processes are accelerating investment in low-emission forging technologies across European production facilities.
- Hollowtech spindle innovation:Advanced hollow axle designs reduce weight while maintaining stiffness, attracting premium road and gravel bike manufacturers seeking biomechanical efficiency gains.
- German cycling infrastructure:Federal and municipal investments in urban bike lanes and parking facilities are expanding daily commuter ridership and component replacement cycles.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy market shifts, compressing margins on forged crank arm production.
- Taiwanese forging concentration:Overreliance on Taichung-area suppliers for CNC-machined spider interfaces creates geographic vulnerability to shipping disruptions.
- REACH surface treatment compliance:Hexavalent chromium plating bans force costly retooling toward PVD and anodized finishes with limited supplier base.
Strategic Opportunities
- Gravel bike segment expansion:Unmet demand for wide-range 1x cranksets with 40-42T chainrings offers white space between road and mountain bike specifications.
- Indian e-bike assembly:PLI scheme incentives for domestic manufacturing create entry points for crankset suppliers establishing localized forging partnerships.
- Electronic shifting convergence:Integration of wireless derailleur protocols with power meter cranksets enables premium bundling opportunities.
Industry Challenges
- CNC programming talent scarcity:Spider interface machining requires specialized five-axis programming expertise concentrated among aging European toolmakers.
- ISO 4210 fatigue certification timelines:Extended testing protocols for carbon fiber crank arms delay product launches by six to nine months versus aluminum equivalents.
- Legacy frame compatibility:Proliferation of bottom bracket standards (BB86, T47, PF30) fragments inventory requirements across OEM service programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Crankset Market |
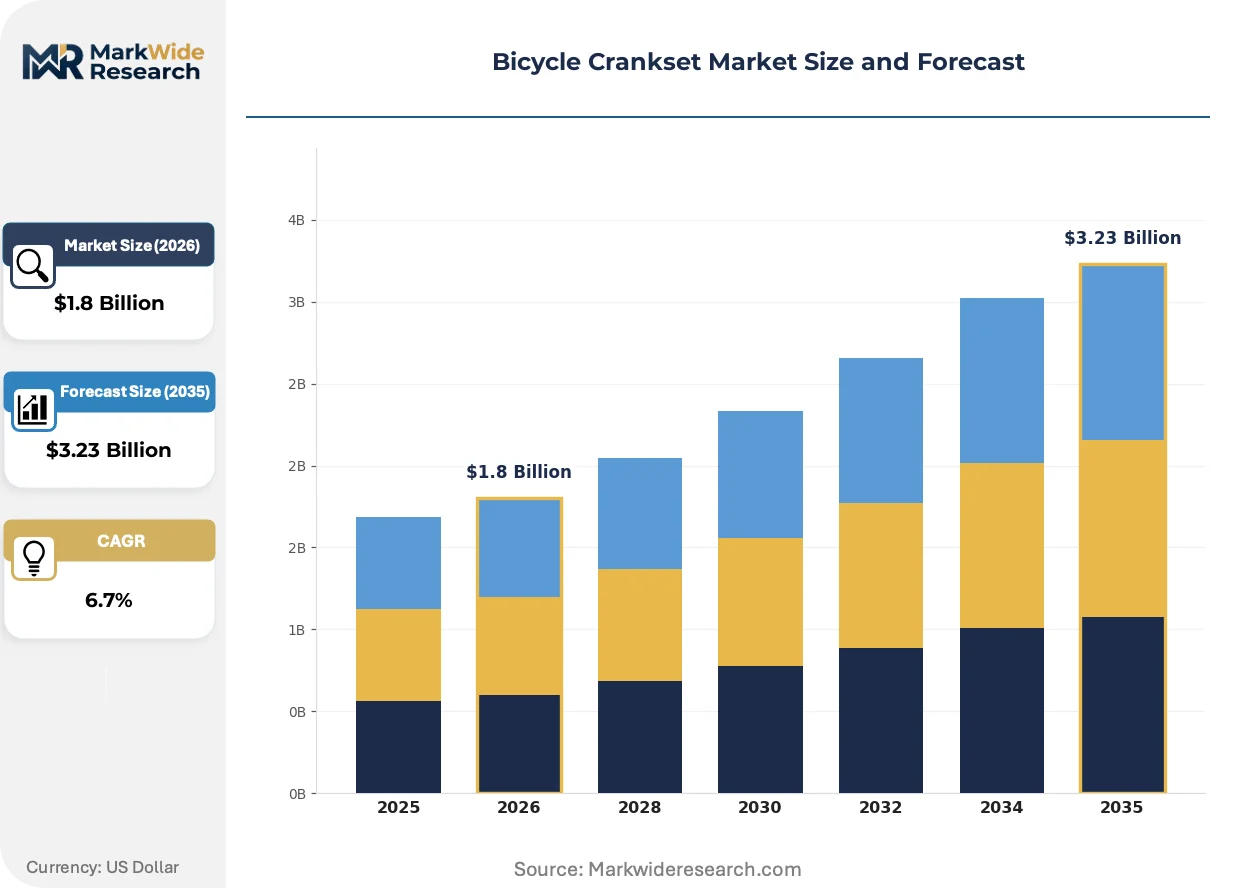
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Speed, Multi Speed, Hollowtech, Duralumin Material: Aluminum, Carbon Fiber, Steel, Titanium End User: Professional Cyclists, Casual Riders, Mountain Bikers, Commuters Gear System: Mechanical, Electronic, Hybrid, Single Gear |
| Companies Covered | Shimano Inc., SRAM LLC, Campagnolo, FSA (Full Speed Ahead), Cane Creek, Hope Technology, Race Face, Praxis Works, Miche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Crankset Market Trends and Innovations
Carbon fiber layup automation and power meter miniaturization are compressing development cycles while regulatory chemical bans reshape surface treatment supply chains.
Modular crank arm systems with interchangeable spiders and direct-mount chainrings are decentralizing component replacement patterns. Recreational cyclists in North American and Australian markets now source spider and ring upgrades separately rather than purchasing complete cranksets. This modularity is decentralizing aftermarket revenue streams toward smaller machine shops and direct-to-consumer brands.
EU REACH restrictions on hexavalent chromium are eliminating traditional plating lines across Italian and Portuguese finishing facilities. Suppliers are retrofitting vacuum chambers for physical vapor deposition or expanding anodizing capacity with sealed-pore hardcoat processes. Road racing cranksets with cosmetic surface requirements face the steepest cost adjustments as aesthetic durability standards tighten.
Direct-to-assembler specification development is displacing traditional distributor-mediated procurement. E-bike manufacturers in Stuttgart, Eindhoven, and Copenhagen now embed crankset engineers within frame design teams eighteen to twenty-four months ahead of production. This co-development model compresses specification finalization timelines while locking out aftermarket competitors from early design influence.
Bicycle Crankset Market Segmentation
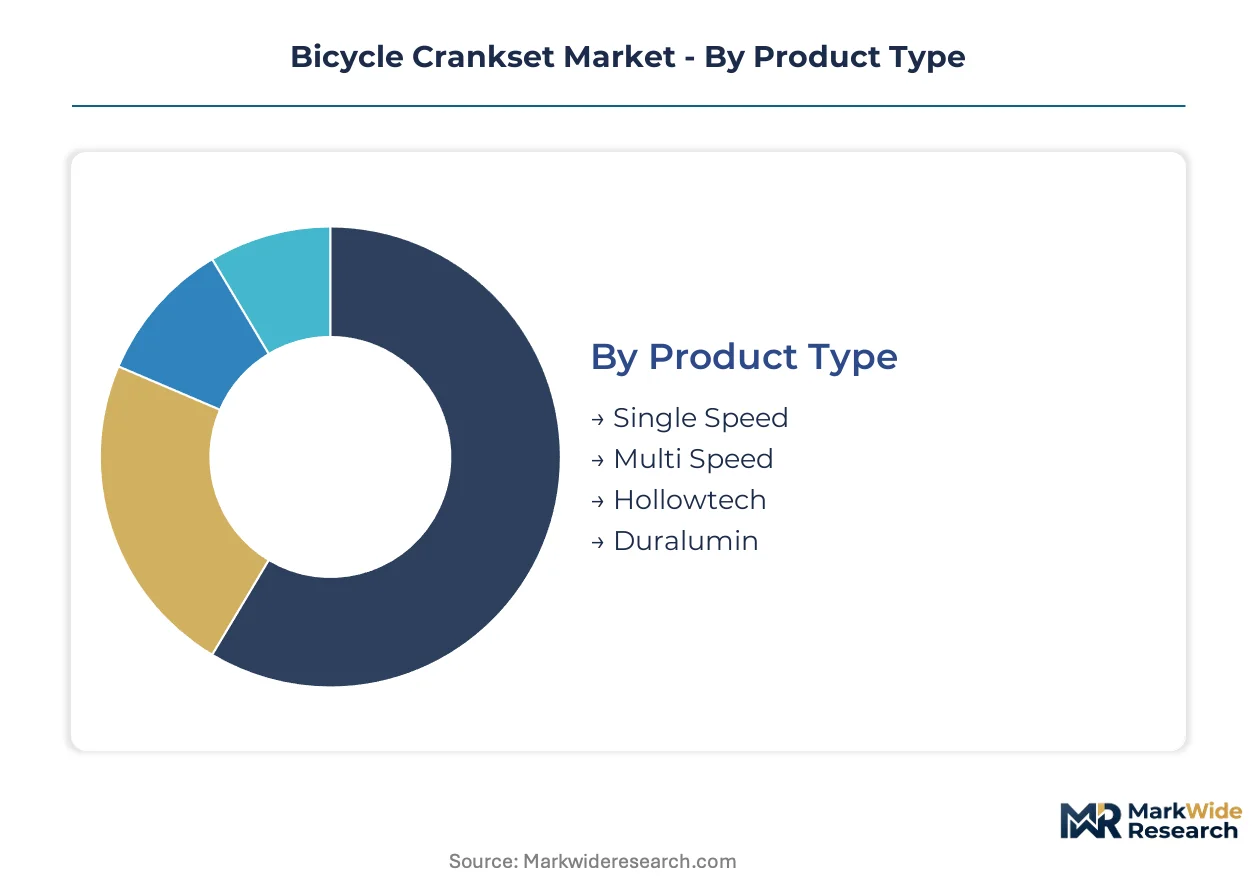
Crankset purchasing patterns diverge sharply between replacement-driven aftermarket demand and frame-integrated OEM procurement. Upgrade cycles vary from three-year intervals for recreational aluminum components to annual refresh rates among professional carbon fiber users. Understanding these segment boundaries clarifies where suppliers must choose between volume scale and margin capture.
Product Type:
Replacement frequency and upgrade spending intensity separate the four product categories, with premium spindle designs commanding disproportionate margin despite lower shipment volumes.
- Multi Speed:Spider-mounted chainring assemblies supporting 2x or 3x drivetrain configurations dominate commuter and mountain bike OEM fitment. German e-bike assemblers in Stuttgart and Munich specify these for urban mobility platforms where gear range flexibility outweighs weight penalties.
- Hollowtech:Advanced hollow spindle architectures reduce rotating mass while preserving torsional rigidity through forged aluminum or carbon fiber construction. Performance road and gravel bike manufacturers in Italy and Portugal specify these for stiffness-to-weight optimization in competitive segments.
- Single Speed:Simplified spiderless designs with fixed gear ratios serve fixed-gear urban cyclists and track racing specialists.
- Duralumin:Age-hardened aluminum alloy crank arms with enhanced fatigue resistance target mid-tier replacement markets.
Multi Speed sits at the top of the volume ranking, with Hollowtech climbing the fastest.
Material:
Raw material cost tiers and processing complexity determine supplier margin structures across the four construction categories.
- Aluminum:Forged 6061-T6 or 7075-T6 alloy crank arms with CNC-machined spider interfaces constitute the industrial baseline for mass production. Taiwanese forging clusters in Taichung supply the majority of OEM demand, though REACH-compliant surface finishing now requires European PVD or anodizing partnerships.
- Carbon Fiber:Prepreg layup or filament-wound crank arm construction achieves 40-50% weight reduction versus aluminum equivalents. Professional road teams and premium e-bike assemblers in the Netherlands specify these despite six-to-nine-month ISO 4210 fatigue certification timelines.
- Steel:Chromoly or stainless steel construction persists in BMX and cargo bike applications where impact durability supersedes weight targets.
- Titanium:Grade 5 Ti-6Al-4V alloy crank arms serve ultra-premium custom builders and weight-obsessed enthusiasts.
Aluminum generates the highest absolute revenue, while Carbon Fiber expands most quickly.
End User:
Usage intensity and component stress exposure create distinct replacement cadences across rider categories.
- Professional Cyclists:UCI-registered teams and continental squads replace cranksets seasonally to maintain power meter calibration and chainring freshness. Italian and Spanish WorldTour programs drive specification influence that cascades into consumer purchasing.
- Mountain Bikers:Aggressive trail and enduro riders subject crank arms to repeated rock strikes and high-torque pedal inputs. Replacement cycles compress to 18-24 months for aluminum components in North American and Australian gravity markets.
- Commuters:Daily urban riders accumulate high mileage with minimal maintenance, extending replacement intervals to five-plus years.
- Casual Riders:Weekend recreational cyclists drive seasonal replacement demand concentrated in spring months.
Commuters constitute the largest installed base, with Mountain Bikers posting the steepest upgrade spending trajectory.
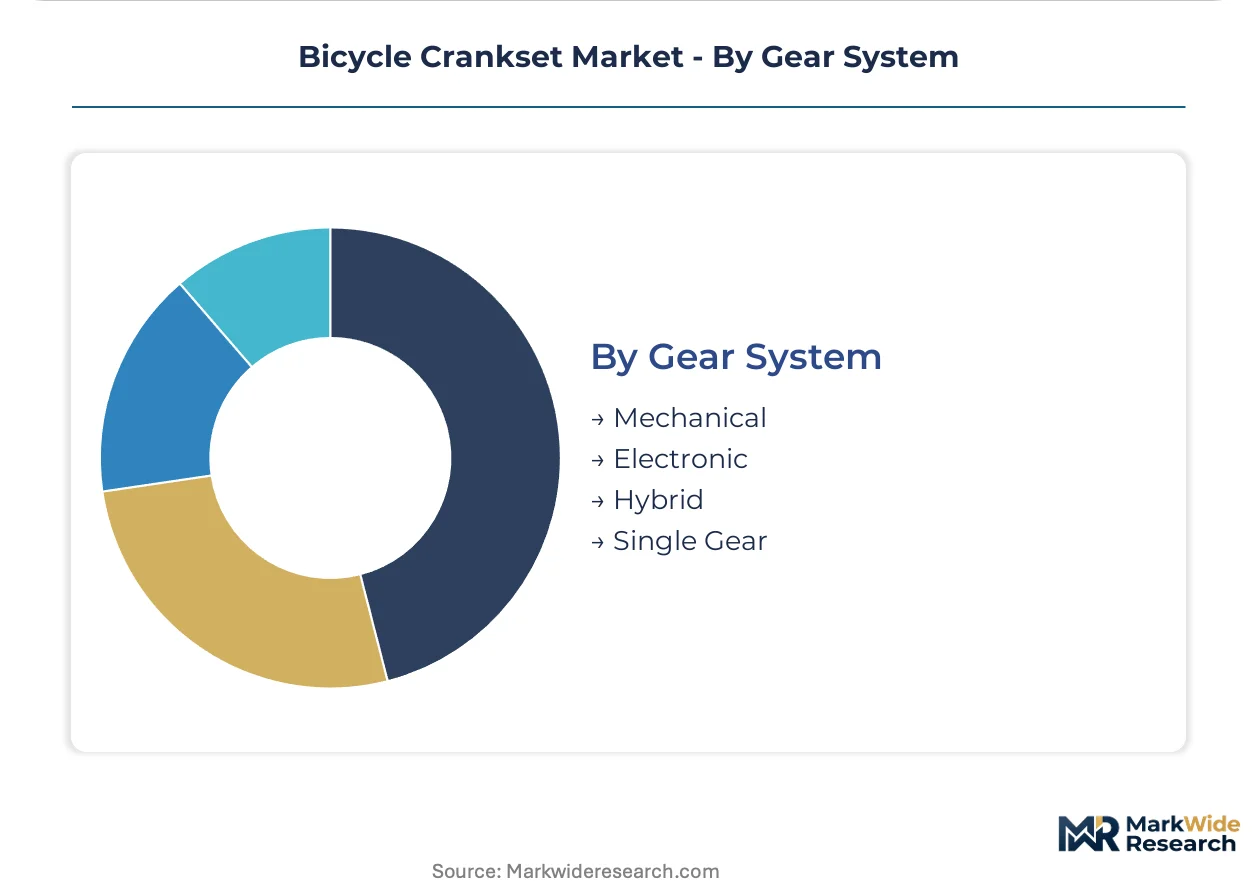
Gear System:
Integration complexity and electronic content value separate the four drivetrain interface categories.
- Mechanical:Cable-actuated front and rear derailleur systems retain dominance across mid-tier road and mountain bike platforms. Shimano and SRAM mechanical groupsets specify proprietary bolt circle diameters that lock in crankset replacement purchases.
- Electronic:Wireless or wired battery-powered shifting systems require crankset-integrated power meters and specific chainline tolerances. European e-bike OEMs in Copenhagen and Eindhoven bundle these with premium motor systems.
- Hybrid:Mixed mechanical-electronic configurations serve transitional upgrade paths and budget-conscious enthusiasts.
- Single Gear:Fixed or freewheel direct-drive systems eliminate derailleur compatibility concerns entirely.
Mechanical retains volume leadership, with Electronic gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cycling infrastructure investments outpace Italy's racing-focused demand, while Taiwan's forging clusters and the Netherlands' e-bike assembly plants create distinct procurement geographies across the crankset supply chain.
Germany
Federal bike lane expansions in Stuttgart and Munich accelerate commuter ridership and component replacement cycles. The EU F-Gas Regulation drives low-emission forging retrofits at Baden-Württemberg production facilities. Premium crankset assemblers cluster along the Neckar Valley, integrating Hollowtech specifications with frame manufacturers eighteen months ahead of production.
Italy
Professional road cycling teams in Lombardy and Emilia-Romagna sustain annual refresh demand for carbon fiber crank arms. REACH restrictions on hexavalent chromium plating eliminate traditional finishing lines across Veneto and Marche facilities. Bologna-area suppliers pivot toward PVD and anodized surface treatments to maintain aesthetic durability standards for racing components.
Taiwan
Taichung-area forging operations supply CNC-machined spider interfaces for mid-tier aluminum crank arms globally. METI circular economy guidelines from Japan shape export compliance requirements for Taiwanese-manufactured components entering European markets. The Central Taiwan Science Park concentrates five-axis programming expertise for complex crank arm geometries.
Netherlands
E-bike OEMs in Eindhoven and Copenhagen embed crankset engineers within frame design teams for battery-assisted shifting integration. EU REACH compliance elevates material standards for surface treatments on urban mobility platforms. The Brainport Eindhoven region hosts specification development partnerships that compress procurement timelines toward frame-integrated supply agreements.
United States
Gravel bike enthusiasts in Colorado and California drive demand for wide-range 1x cranksets with 40-42T chainrings. CPSC mechanical safety criteria diverge from EU chemical compliance, complicating multi-region product configurations. Pacific Northwest machine shops capitalize on modular crank arm systems, sourcing spider and ring upgrades separately from complete crankset purchases.
Bicycle Crankset Market Competitive Landscape
Japanese producers anchor one tier; Italian specialists hold the premium racing segment; Taiwanese fabricators dominate mid-volume forging. The market structures around three strategic archetypes: integrated drivetrain system suppliers, component specialists with regional manufacturing heritage, and modular aftermarket providers. Capacity expansion into low-emission forging technologies and strategic partnerships for electronic shifting integration represent the dominant competitive moves reshaping procurement relationships.
Within the integrated system tier, Shimano Inc. and SRAM LLC occupy positions that exemplify frame-integrated development partnerships with European e-bike assemblers. Campagnolo represents the heritage specialist archetype, maintaining loyalty among professional road cycling teams through Italian-made construction. These three anchors illustrate how competitive positioning diverges between volume-scale OEM supply agreements and margin-focused premium racing segments.
| Leading Market Players |
|---|
| Shimano Inc. |
| SRAM LLC |
| Campagnolo |
| FSA (Full Speed Ahead) |
| Cane Creek |
| Hope Technology |
| Race Face |
| Praxis Works |
| Miche |
| Others |
Pricing and Supply Chain Analysis
Five-axis CNC programming expertise concentrated among aging European toolmakers in Italy and Germany widens labor-cost spreads between premium Hollowtech spindle assemblies and standard forged aluminum crank arms. REACH-compliant PVD and anodized surface finishing requirements in Portugal and Italy add fixed-cost layers that price-discriminate road racing components from commuter-tier equivalents.
Pricing Analysis
Capacity additions in low-emission forging facilities across Baden-Württemberg are reshaping price floors for EU-compliant crankset production. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy steel construction separates professional team specifications from mass-market commuter fitments. Cost compression in mid-tier aluminum forged arms intensifies because primary ingot price volatility feeds directly into spider interface machining margins. E-bike OEMs in the Netherlands exhibit lowest price sensitivity due to motor system bundling economics, while independent bike shops in North American aftermarket channels face highest sensitivity to complete crankset replacement costs.
Supply Chain Analysis
Five-axis programming talent scarcity in Central Taiwan and Northern Italy constrains spider interface machining throughput for complex crank arm geometries. Geographic supply concentrates in Taiwan for CNC-machined aluminum forgings, Germany for Hollowtech spindle assembly, and Italy for carbon fiber layup finishing. Raw material dependencies draw from 6061-T6 and 7075-T6 aluminum billet, Toray prepreg carbon fiber, and Grade 5 titanium bar stock. Single-source vulnerability to Taichung-area forging clusters creates geographic concentration risk for mid-tier OEM supply. Distribution runs through frame-integrated direct procurement with e-bike assemblers, displacing traditional distributor-mediated aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where professional road cycling teams and premium e-bike OEMs prioritize stiffness-to-weight optimization over unit cost minimization. Demand is shifting toward Hollowtech spindle specifications and electronic shifting integration that command placement premiums.
For Market Incumbents:Acquire five-axis CNC programming talent pools in Central Taiwan and Emilia-Romagna to secure spider interface machining capacity before demographic retirement erodes technical workforce depth. Secure backward integration into REACH-compliant PVD finishing chambers across Veneto and Marche to eliminate third-party surface treatment bottlenecks. This counters margin compression from aluminum price volatility and hexavalent chromium plating bans.
For New Entrants and Emerging Players:Capture gravel bike 1x crankset white space between road and mountain specifications where 40-42T chainring demand outstrips incumbent product portfolio coverage. Target Indian e-bike assembly partnerships under PLI scheme incentives where domestic forging capacity remains underdeveloped. Lead with modular spider-and-ring upgrade systems for North American direct-to-consumer channels rather than complete crankset competition.
For Investors and Strategic Acquirers:E-bike drivetrain system integrators are the most active acquirer in this space, seeking crankset engineering teams to embed within eighteen-to-twenty-four-month frame development cycles. Long-term viability hinges on electronic shifting protocol integration and power meter miniaturization capabilities. Watch for ISO 4210 fatigue certification timeline compression as signal of carbon fiber crank arm manufacturing maturity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Forging Retrofit | EU F-Gas Regulation compliance in Baden-Württemberg facilities secures OEM supply eligibility. |
| Electronic Shifting Integration | Wireless derailleur protocol bundling with power meter cranksets captures premium e-bike placement. |
| PVD Surface Treatment Capacity | REACH-compliant vacuum chamber investment replaces hexavalent chromium plating lines in Italian finishing. |
| Five-Axis CNC Talent Acquisition | Spider interface programming expertise concentration in aging European toolmakers requires succession planning. |
| Gravel Bike 1x Specification Development | Wide-range 40-42T chainring designs address unmet demand between road racing and mountain bike segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with crankset procurement managers at e-bike OEMs, forging plant engineers in Taichung, road cycling team equipment directors, and aftermarket distributor category buyers with secondary validation. Bottom-up shipment data from Taiwanese customs records, German federal cycling infrastructure investment disclosures, and Italian component manufacturer SEC filings were triangulated against top-down market sizing from EU bicycle industry association reports and METI circular economy guideline documentation.
Segment-weighting approaches distributed volume and value across product type, material construction, end user intensity, and gear system integration dimensions throughout the forecast period. CAGRs were derived from regression analysis against cycling infrastructure investment trajectories and e-bike motor system penetration curves. Industry-specific inputs included ISO 4210 fatigue certification timeline assumptions and REACH surface treatment compliance cost curves for PVD versus anodized finishing.
Aluminum price volatility, Taiwanese forging cluster disruption, and electronic shifting protocol standardization delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on labor cost trajectories and regulatory enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Europe Running Gear Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Sandbells Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Bike Saddles Market