
 Balance Bike Market | 2026-2036
Balance Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Balance Bike Market Analysis
China's manufacturing belt is narrowing the cost gap between metal and wooden frame production for export-oriented balance bike assembly. Strider Sports International Inc dominates North American direct-to-parent channels through its specialized dealer network. Frog Bikes leverages British design heritage to sustain premium positioning across European specialty retailers. Yvolve Sports Ltd anchors Australasian distribution through controlled wholesale partnerships with regional toy distributors.
A balance bike is a pedal-less two-wheeled training vehicle for children aged 18 months to 5 years, constructed from wood, metal, or composite materials with seat heights typically ranging from 28 to 48 centimeters and weighing between 2 and 5 kilograms; its commercial purpose is to develop proprioception and balance before transition to pedal bicycles. Metal frames occupy the largest margin pool due to aluminum alloy sourcing scale and durability premiums, while wooden variants retain artisan positioning in boutique European channels. The preschool age group generates the fastest volume expansion as daycare procurement standardizes gross motor skill curricula. Adjustable seat mechanisms command price premiums across all product tiers by extending usable product life spans.
The Consumer Product Safety Commission governs tip-over and small-parts standards for US balance bike imports, while the EU Toy Safety Directive mandates EN 71 mechanical testing and CE marking for all models sold in member states. China's GB standards for children's products govern domestic manufacturing quality benchmarks for export and local consumption. Stakeholders must monitor evolving chemical restriction lists under REACH and state-level lead-content thresholds that reshape material sourcing decisions.
Market Dynamics
Preschool enrollment expansion across North American early learning centers is institutionalizing balance bike procurement as standard gross motor skill curriculum equipment, shifting volume from parent-driven retail toward contracted institutional supply chains.
Growth Catalysts
- EU Toy Safety Directive:EN 71 mechanical testing mandates are filtering out substandard imports, creating market share openings for certified manufacturers with compliant aluminum frame sourcing.
- Daycare procurement standardization:Early learning centers in the United States are consolidating vendor relationships for gross motor equipment, generating recurring institutional purchase orders.
- Lightweight aluminum alloys:Advances in hydroforming and heat treatment are reducing frame weight below 2.5 kilograms without sacrificing structural integrity for collision scenarios.
Market Restraints
- REACH chemical restrictions:Evolving substance limitation lists under European chemicals regulation are forcing reformulation of powder coatings and anodization processes, elevating compliance costs for frame finishing.
- Wooden frame supply concentration:Baltic birch plywood sourcing clusters in Eastern European forests, exposing manufacturers to regional harvest quotas and freight rate volatility.
- Seat height adjustability patents:Locked quick-release mechanism designs held by incumbent players create licensing friction for new entrants developing competing adjustable systems.
Strategic Opportunities
- Indian preschool infrastructure:National early childhood education expansion programs are creating first-time institutional demand for training bicycles in tier-2 and tier-3 cities.
- Composite material convergence:Glass-reinforced nylon injection molding paired with carbon fiber seat posts enables sub-2-kilogram production at mid-market price positioning.
- Direct-to-parent subscription models:Size-exchange programs addressing rapid child growth are displacing single-purchase retail through recurring revenue frameworks.
Industry Challenges
- Third-party testing backlog:CPSC laboratory certification queues for tip-over and small-parts compliance are extending product launch timelines by four to six months for US-bound shipments.
- Multi-standard inventory complexity:Simultaneous GB, EN 71, and ASTM compliance requirements force SKU proliferation or specification compromise across export destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balance Bike Market |
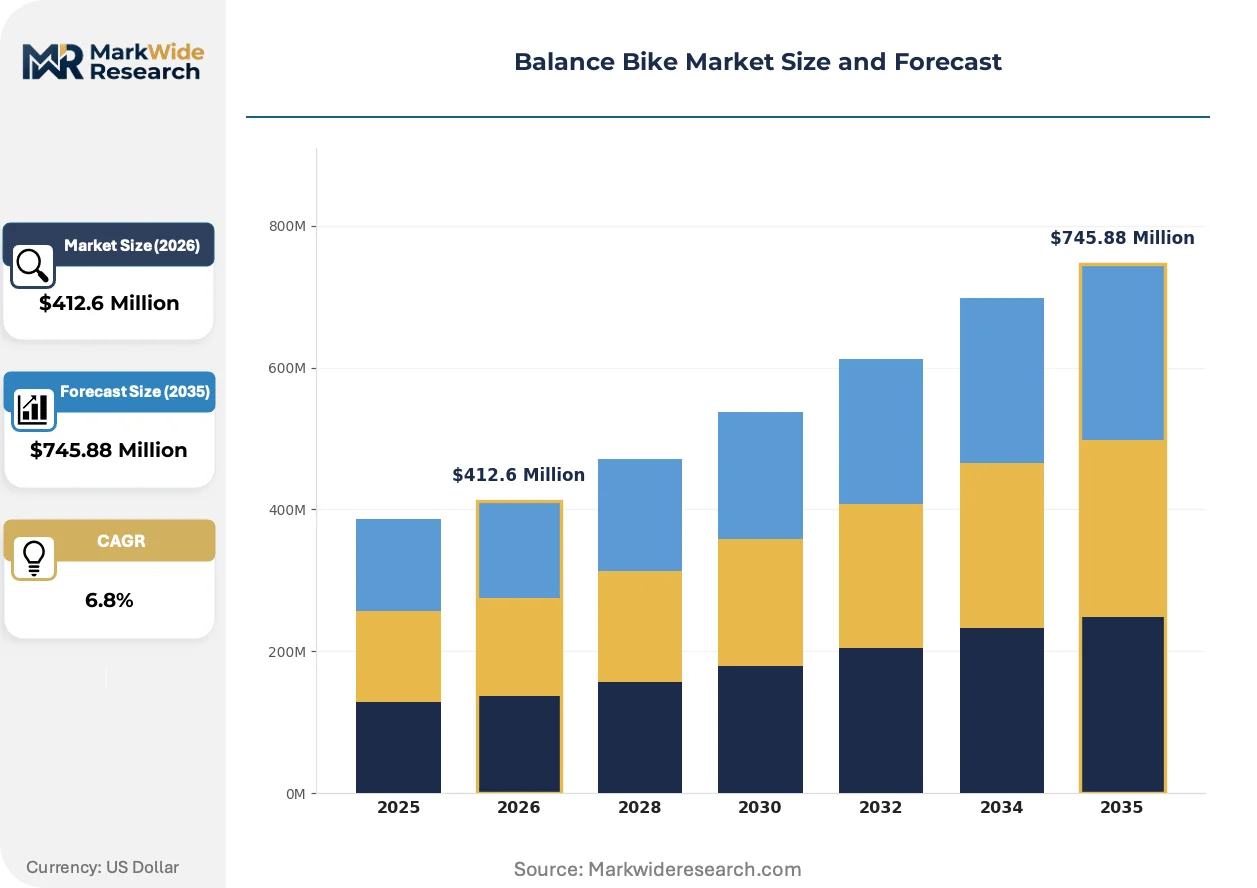
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden, Metal, Plastic, Adjustable Age Group: Toddlers, Preschool, Primary School, Teens Feature: Adjustable Seat, Lightweight Frame, Disc Brakes, Handlebars Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | BayBee Prime Toys India Pvt Ltd, Yvolve Sports Ltd, Strider Sports International Inc, Frog Bikes, Kidvelo, Glide Bikes Inc, Radio Flyer Inc, Guardian Bikes, The First Bike Co Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balance Bike Market Emerging Trajectories
Material science advances and regulatory stringency are compressing the traditional metal-versus-wood product hierarchy, while procurement centralization in institutional channels rewires distribution economics.
Airless polymer tire technology is collapsing the maintenance burden for institutional fleet operators. Closed-cell microcellular polyurethane formulations eliminate puncture risk and pressure monitoring requirements. North American daycare chains are specifying airless configurations for shared-equipment pools, reducing total cost of ownership across three-year replacement cycles.
REACH substance restriction updates are reshaping surface treatment supply chains. Chromium VI limitations in anodization sealants are forcing conversion to trivalent alternatives or ceramic conversion coatings. German specialty retailers are demanding full material disclosure documentation, privileging suppliers with certified green chemistry frameworks.
Parent purchasing behavior is fragmentating across channel types. Research-intensive buyers gravitate toward direct brand websites with geometry sizing tools, while convenience-oriented segments default to marketplace platforms with aggregated reviews. Urban density corridors in Canada exhibit highest direct-channel penetration, correlating with cycling culture familiarity and reduced big-box retail access.
Balance Bike Market Segmentation
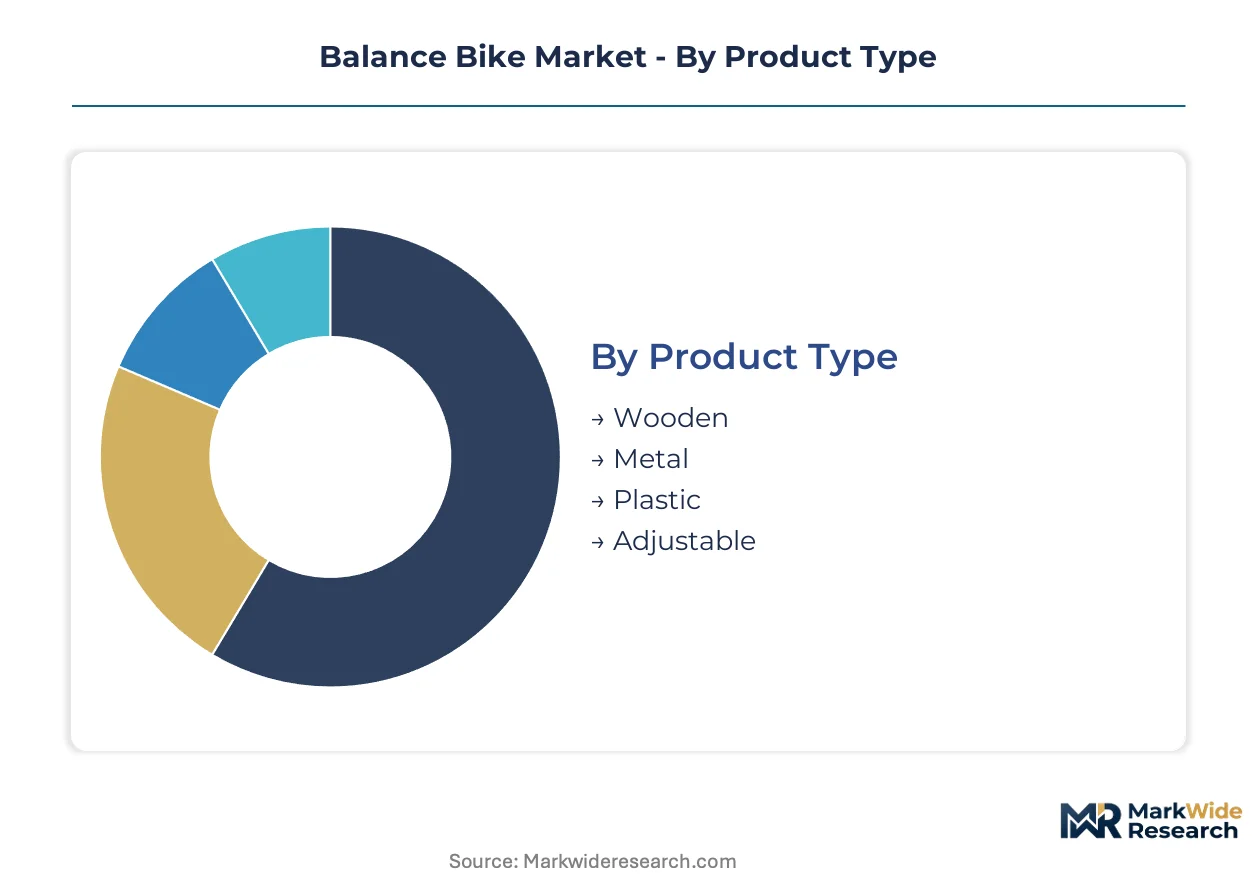
Segmentation in the balance bike market determines procurement pathways and margin structures. Product material dictates institutional durability requirements while age targeting shapes channel selection and safety certification tiers.
Product Type:
After-sales-service intensity varies sharply across material categories, with metal frames requiring collision damage assessment and wooden variants demanding moisture-related warranty handling.
- Wooden:Baltic birch plywood construction delivers tactile warmth and aesthetic appeal for boutique retail positioning. German urban parent segments prioritize these models for indoor storage compatibility and sustainability signaling, though harvest quota volatility in Eastern European forests constrains supply scaling.
- Metal:Aluminum alloy and steel frames dominate institutional procurement through durability premiums and collision resilience. North American early learning centers specify metal construction for shared-equipment pools, with hydroforming advances reducing unit weight below 2.5 kilograms.
- Plastic:Injection-molded polypropylene variants serve price-sensitive entry segments with minimal maintenance overhead.
- Adjustable:Modular frame systems with telescoping seat posts and handlebar stems extend usable lifespan across growth spurts.
Metal holds the largest share; momentum sits with adjustable configurations as replacement cycle extension becomes a parent priority.
Age Group:
Cost tier stratification aligns closely with developmental capability thresholds and corresponding safety regulation stringency.
- Toddlers:Models targeting 18-36 month users emphasize ultra-low standover heights below 28 centimeters and rounded component geometries. Daycare procurement in tier-2 Indian cities is generating first-time institutional demand for this bracket as early childhood infrastructure expands.
- Preschool:3-5 year specifications balance seat height adjustability with weight reduction for unassisted maneuvering. Gross motor skill curriculum standardization across United States early learning centers is concentrating volume in this tier through recurring institutional purchase orders.
- Primary School:Larger wheel diameters and reinforced frames accommodate heavier users transitioning toward pedal bicycles.
- Teens:Extended size ranges with adult-comparable geometry serve delayed skill acquisition or adaptive physical therapy applications.
Preschool commands current volume concentration; toddlers are expanding most quickly as enrollment age thresholds lower across Asian markets.
Feature:
Application context determines which performance attributes justify price premiums versus baseline compliance.
- Adjustable Seat:Quick-release mechanisms with graduated height markings dominate parent preference rankings for multi-year usability. Patent-protected clamp designs held by incumbent manufacturers create licensing barriers for new entrants developing competing systems.
- Lightweight Frame:Sub-2.5 kilogram construction using 6061-T6 aluminum or composite reinforcement enables toddler self-propulsion and caregiver transport convenience.
- Disc Brakes:Mechanical or hydraulic braking systems appear in premium tiers targeting varied terrain usage beyond flat pavement.
- Handlebars:Ergonomic grip compounds and limited-rotation steering limiters reduce wrist strain and jackknife incidents for novice riders.
Adjustable seat mechanisms hold the largest share; lightweight frame demand is climbing the fastest as aluminum sourcing scale improves.
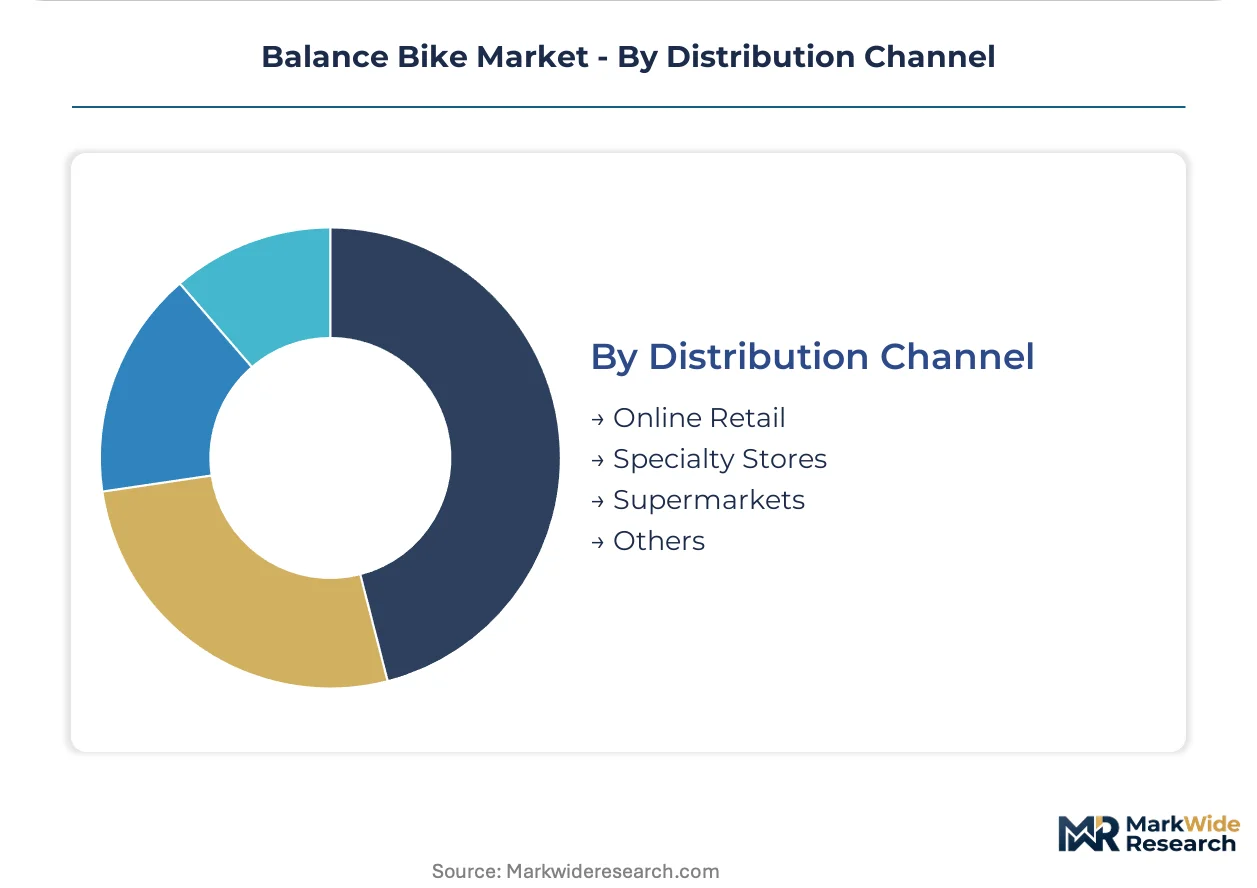
Distribution Channel:
Customer type fragmentation across research-intensive versus convenience-oriented segments reshapes channel economics.
- Online Retail:Direct-to-parent brand websites with geometry sizing tools capture cycling-culture households in Canadian urban corridors with reduced big-box access. Aggregated marketplace platforms serve review-dependent convenience buyers.
- Specialty Stores:British design heritage positioning through European specialty retailers sustains premium pricing for certified aluminum construction with full material disclosure documentation.
- Supermarkets:Mass-market penetration targets price-sensitive first-time purchasers with limited product comparison behavior.
- Others:Institutional contracting and subscription size-exchange programs address rapid child growth through recurring revenue frameworks rather than single-transaction retail.
Specialty stores retain margin leadership; online retail is gaining share fastest as sizing tool accuracy improves return rate reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Consumer Product Safety Commission governs tip-over and small-parts standards for US balance bike imports, while divergent regulatory regimes across Germany, China, India, and Australia create distinct market entry requirements. Institutional procurement patterns and material sourcing clusters vary sharply by geography.
United States
Daycare procurement standardization across early learning centers is consolidating vendor relationships for gross motor equipment into recurring institutional purchase orders. The CPSC laboratory certification queues for tip-over compliance are extending product launch timelines by four to six months for domestic-bound shipments. California and Pacific Northwest urban corridors exhibit highest direct-channel penetration, correlating with cycling culture familiarity.
Germany
Urban parent segments prioritize lightweight aluminum construction with full material disclosure documentation demanded by specialty retailers. REACH chemical restrictions are forcing conversion from chromium VI to trivalent anodization alternatives, elevating compliance costs for frame finishing. Bavaria's manufacturing belt concentrates precision aluminum hydroforming operations serving premium tier production.
China
GB standards for children's products govern domestic manufacturing quality benchmarks for export and local consumption. Yangtze River Delta and Pearl River Delta clusters are narrowing the cost gap between metal and wooden frame production for export-oriented assembly. NMPA-aligned testing protocols are filtering substandard producers from institutional supply chains.
India
National early childhood education expansion programs are creating first-time institutional demand for training bicycles in tier-2 and tier-3 cities. BIS certification requirements for children's products are reshaping import compliance pathways for foreign manufacturers. Maharashtra and Gujarat manufacturing zones are developing aluminum component sourcing for domestic assembly operations.
Australia
Controlled wholesale partnerships with regional toy distributors anchor market access for international brands. TGA-aligned product safety frameworks govern mechanical testing requirements for children's training equipment. Sydney and Melbourne metropolitan areas concentrate parent purchasing through specialty retail channels with strong cycling culture penetration.
Balance Bike Market Vendor Landscape
Capability concentration sits with design-specialist tier players commanding premium positioning; scale advantage sits with mass-market fabricators optimizing aluminum sourcing volumes. The vendor base organizes around three strategic archetypes: heritage-design specialists leveraging British or European aesthetic positioning, North American direct-to-parent operators with specialized dealer networks, and Asia-Pacific wholesale-anchored distributors controlling regional logistics. Competitive moves center on subscription size-exchange program development and institutional contracting consolidation.
Within the heritage-design tier, Frog Bikes exemplifies British design heritage positioning across European specialty retailers. Strider Sports International Inc occupies the North American direct-channel vector through its established dealer network architecture. Yvolve Sports Ltd anchors the Asia-Pacific wholesale partnership model through controlled distribution arrangements with regional toy distributors. These three represent distinct geographic-architype combinations rather than direct product competitors.
| Leading Market Players |
|---|
| BayBee Prime Toys India Pvt Ltd |
| Yvolve Sports Ltd |
| Strider Sports International Inc |
| Frog Bikes |
| Kidvelo |
| Glide Bikes Inc |
| Radio Flyer Inc |
| Guardian Bikes |
| The First Bike Co Inc |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta aluminum hydroforming clusters concentrate upstream frame production, anchoring margin pools with institutional buyers who contract multi-year fleet replacements. Baltic birch plywood harvest quotas in Eastern European forests create parallel artisan pricing tiers for boutique retail channels. The interaction between these dual sourcing geographies and divergent buyer archetypes structures a bifurcated cost architecture across the market.
Pricing Analysis
Price spreads between German specialty retail and North American mass-market channels exceed two-to-one for comparable aluminum specifications. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Price differentiation hinges on EN 71 testing documentation and REACH-compliant surface treatment disclosure. Cost compression in economy tiers is intensifying because Chinese export-oriented assemblers are narrowing metal-wood production cost gaps. Daycare procurement managers demonstrate lowest price sensitivity due to three-year replacement cycle budgeting; entry-level parent buyers exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta frame fabricators to Pearl River Delta assembly plants average 90-120 days, compressing working capital for tier-two suppliers. Geographic supply concentration centers on China for aluminum hydroforming, Estonia and Latvia for Baltic birch plywood, and India for emerging domestic component sourcing. Raw material dependencies rest on 6061-T6 aluminum billet, closed-cell polyurethane tire formulations, and quick-release clamp hardware. Single-source vulnerability in Eastern European plywood harvest quotas exposes wooden-frame specialists to freight rate volatility. Distribution runs through controlled wholesale partnerships in Asia-Pacific, specialized dealer networks in North America, and heritage-positioned specialty retailers across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional procurement fragmentation across daycare chains, early learning centers, and municipal recreation programs creates niche entry points for specialists. Parent purchasing behavior splits between research-intensive direct-channel buyers and convenience-oriented marketplace shoppers.
For Market Incumbents: Entrench institutional relationships through multi-year fleet maintenance contracts with North American early learning center chains. Deepen backward integration into aluminum hydroforming capacity within Bavaria's manufacturing belt to secure REACH-compliant surface treatment control. Certification investment in simultaneous GB, EN 71, and ASTM compliance protects against SKU proliferation threats from multi-standard inventory complexity. For New Entrants and Emerging Players: Pursue tier-2 and tier-3 Indian city preschool infrastructure as first-time institutional demand emerges from national early childhood education expansion. Target subscription size-exchange programs for urban Canadian cycling-culture households seeking multi-year usability without repeat purchase friction. Direct-to-parent brand websites with geometry sizing tools offer the most penetrable go-to-market angle against established wholesale-anchored competitors. For Investors and Strategic Acquirers: Capital is best deployed toward design-specialist tier players with British or European heritage positioning and certified green chemistry frameworks. Long-term viability favors acquisition targets controlling proprietary adjustable seat mechanism patents and institutional contracting relationships. Watch for inflection signals in CPSC laboratory certification queue lengths, which currently extend product launch timelines and create temporary supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Size-Exchange Program Launch | Recurring revenue frameworks displace single-purchase retail for rapid-growth household segments. |
| REACH-Compliant Surface Treatment Investment | Trivalent chromium and ceramic conversion coatings satisfy German specialty retailer disclosure demands. |
| Institutional Fleet Maintenance Contracting | Multi-year service agreements with North American daycare chains secure replacement cycle visibility. |
| Composite Material R&D Partnership | Glass-reinforced nylon injection molding enables sub-2-kilogram production at mid-market positioning. |
| Direct-to-Parent Channel Expansion | Geometry sizing tools on brand websites reduce return rates in Canadian urban corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Daycare procurement managers, early learning center curriculum directors, specialty retail buyers, aluminum frame fabricators, and Baltic birch plywood suppliers provided operational perspectives. Secondary validation drew from CPSC enforcement databases, EU Toy Safety Directive guidance documents, customs trade records for aluminum billet shipments, and REACH substance restriction update notices. Bottom-up shipment data from frame fabricators was triangulated against top-down institutional procurement budget surveys.
Calibration against historical price realizations and documented procurement contract values anchored the analytical framework. Segmentation modeling across material type, age group specification, feature configuration, and distribution channel structure shaped volume and value outputs across the analysis window. CAGRs were derived from regression analysis of enrollment-driven institutional demand curves and parent replacement cycle patterns. Aluminum sourcing scale improvements and airless polymer tire adoption curves served as industry-specific forecast inputs.
Sensitivities concentrate around REACH chemical restriction evolution, CPSC laboratory certification queue lengths, and Eastern European forest harvest quota volatility. Forecasts reflect documented assumptions regarding preschool enrollment expansion rates and institutional procurement standardization trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Dirt Bike Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Quad Skate Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Sports Devices Market
Sports Equipment
Riding Gear Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Wetsuits Market