
 Mixed Martial Arts Equipment Market | 2026-2036
Mixed Martial Arts Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Martial Arts Equipment Market Outlook
Specialty retail and direct-to-consumer channels is fragmenting as fight-sport brands diversify beyond traditional brick-and-mortar fight shops. Venum leverages its premium positioning and UFC partnership to control high-visibility athlete sponsorships. Century Martial Art Supply LLC anchors its presence through broad catalog distribution and institutional contracts with martial arts schools. Hayabusa Fightwear Inc. differentiates via biomechanically engineered glove designs that emphasize wrist stabilization and knuckle protection.
Mixed martial arts equipment encompasses protective and training gear engineered for full-contact combat sports, typically constructed from layered foam padding encased in leather or synthetic shells with reinforced stitching rated for repeated high-impact strikes. Gloves dominate product type revenue due to mandatory use across all competitive and training formats, while mouthguards represent the fastest-growing segment as dental injury awareness spreads among amateur participants. Leather commands material preference among professionals for durability and fit molding, though synthetic fabrics gain share in recreational use cases where cost sensitivity and vegan material preferences shape purchasing decisions.
FDA oversight of mouthguard biocompatibility and ASTM standards for protective athletic equipment establish baseline safety thresholds that manufacturers must satisfy for US market access, while ISO certification frameworks govern export eligibility into European and Asian distribution networks. State athletic commissions in Nevada, California, and New York impose additional equipment specifications for sanctioned bouts that ripple backward into training gear procurement standards. Stakeholders must monitor evolving commission rules on glove padding density and material transparency as regulatory scrutiny intensifies around fighter safety and long-term health outcomes.
Market Dynamics
Olympic recognition of MMA as a medal sport is restructuring equipment procurement standards as national federations standardize gear specifications ahead of potential Los Angeles 2028 inclusion, forcing manufacturers to recalibrate product lines for institutional certification requirements.
Growth Catalysts
- FDA biocompatibility mandates:Mouthguard manufacturers must demonstrate medical-grade material safety for US market access, accelerating dental protection adoption among amateur training facilities.
- Foam density innovations:Layered polymer cores are reducing glove weight while maintaining impact absorption thresholds demanded by state athletic commissions.
- Brazil:Expanding fight academy infrastructure in São Paulo and Rio de Janeiro is driving bulk procurement of protective gear for both competitive and recreational segments.
Market Restraints
- Leather price volatility:Premium hide costs fluctuate with agricultural commodity cycles, squeezing margin structures for professional-grade equipment lines.
- Thai manufacturing concentration:Muay Thai equipment production clusters around Bangkok industrial zones, creating geographic vulnerability to regional logistics disruptions.
- ASTM certification timelines:Extended laboratory testing periods for protective gear approval delay product launches and tie up working capital.
Strategic Opportunities
- India:Nascent MMA training infrastructure presents first-mover positioning for equipment brands establishing distribution through emerging metro gym chains.
- Direct-to-consumer channels:Fight-sport brands bypass traditional retail markup by building proprietary e-commerce platforms with athlete content integration.
- ISO 9001 alignment:Quality management certification opens institutional procurement pathways across European and Asian national Olympic committees.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized glove designers combining combat sport knowledge with orthopedic science command premium compensation and limited availability.
- Multi-jurisdiction compliance:Nevada, California, and New York state athletic commissions maintain divergent equipment specifications, fragmenting production runs.
- Legacy inventory obsolescence:Rapid padding density standard updates strand non-compliant stock in wholesale distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Martial Arts Equipment Market |
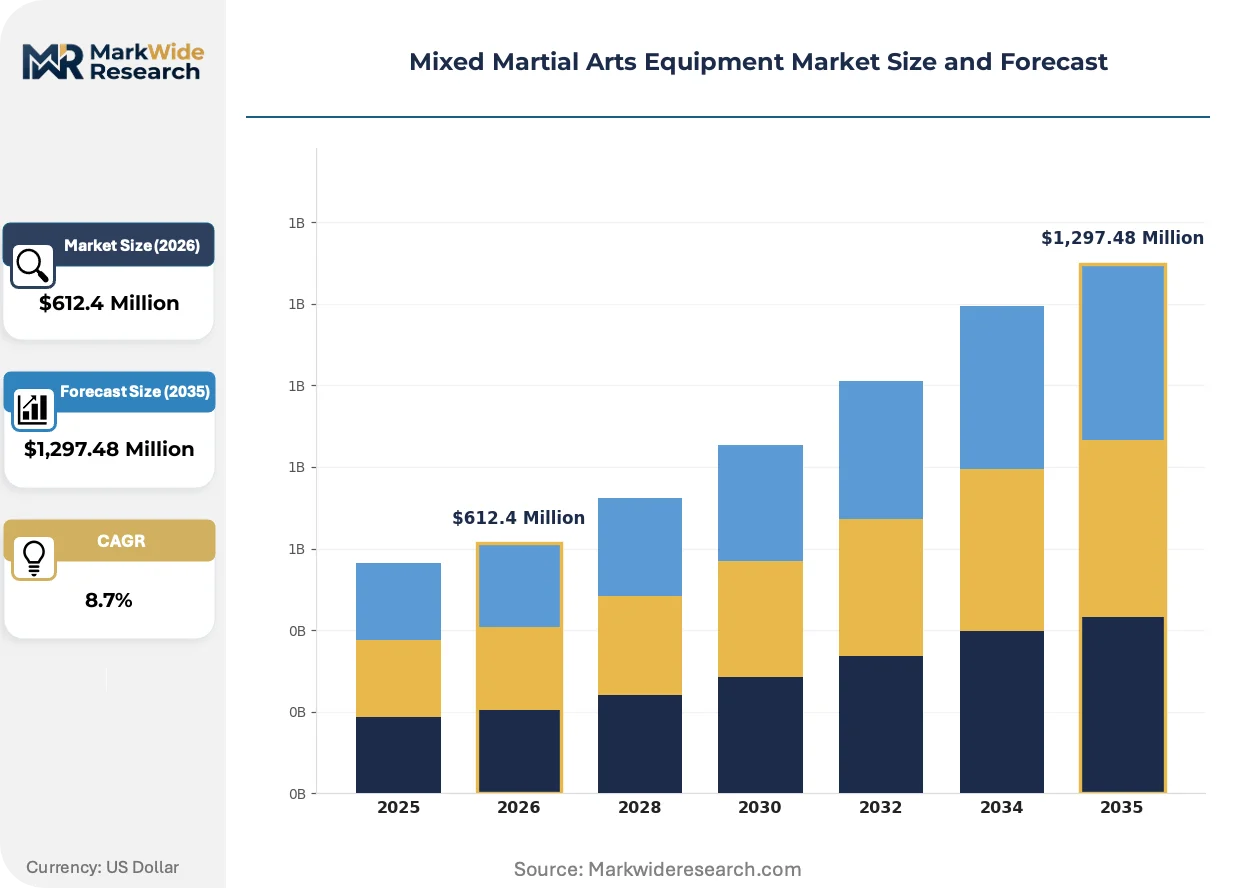
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Mouthguards, Shin Guards, Training Mats Material: Leather, Synthetic Fabrics, Foam, Rubber Use Case: Training, Professional Fighting, Conditioning, Recreational End User: Amateurs, Professionals, Trainers, Gyms |
| Companies Covered | Venum, Century Martial Art Supply LLC, Adidas AG, Twins Special Co. Ltd., Ringside, Inc., Everlast Worldwide Inc., TITLE Boxing LLC, Fairtex, Hayabusa Fightwear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Martial Arts Equipment Market Strategic Shifts
Synthetic material engineering and digital fitting technologies are compressing traditional leather-dominant supply chains while reshaping how fighters select and replace protective equipment across training intensities.
Multi-layered EVA foam cores with gradient density profiles are replacing uniform padding constructions in competition gloves. Amateur training facilities and recreational users are adopting these designs fastest due to durability advantages. The technology is migrating from premium professional lines into mid-tier consumer segments as manufacturing scales reduce unit costs.
REACH substance restrictions in the European Union are compelling reformulation of synthetic leather coatings and adhesive compounds used in equipment shells. Manufacturers serving EU distribution networks must maintain dual material inventories or universal compliant formulations. Glove and shin guard producers with European institutional contracts face the steepest compliance cost absorption.
Subscription-based equipment replacement programs are displacing one-time retail purchases among high-frequency training consumers. Specialty fight-sport retailers and direct brands are piloting monthly fee structures covering glove refresh cycles and mouthguard replacements. California and Texas metro markets show highest enrollment density where gym membership concentration supports logistics efficiency.
Mixed Martial Arts Equipment Market Segmentation
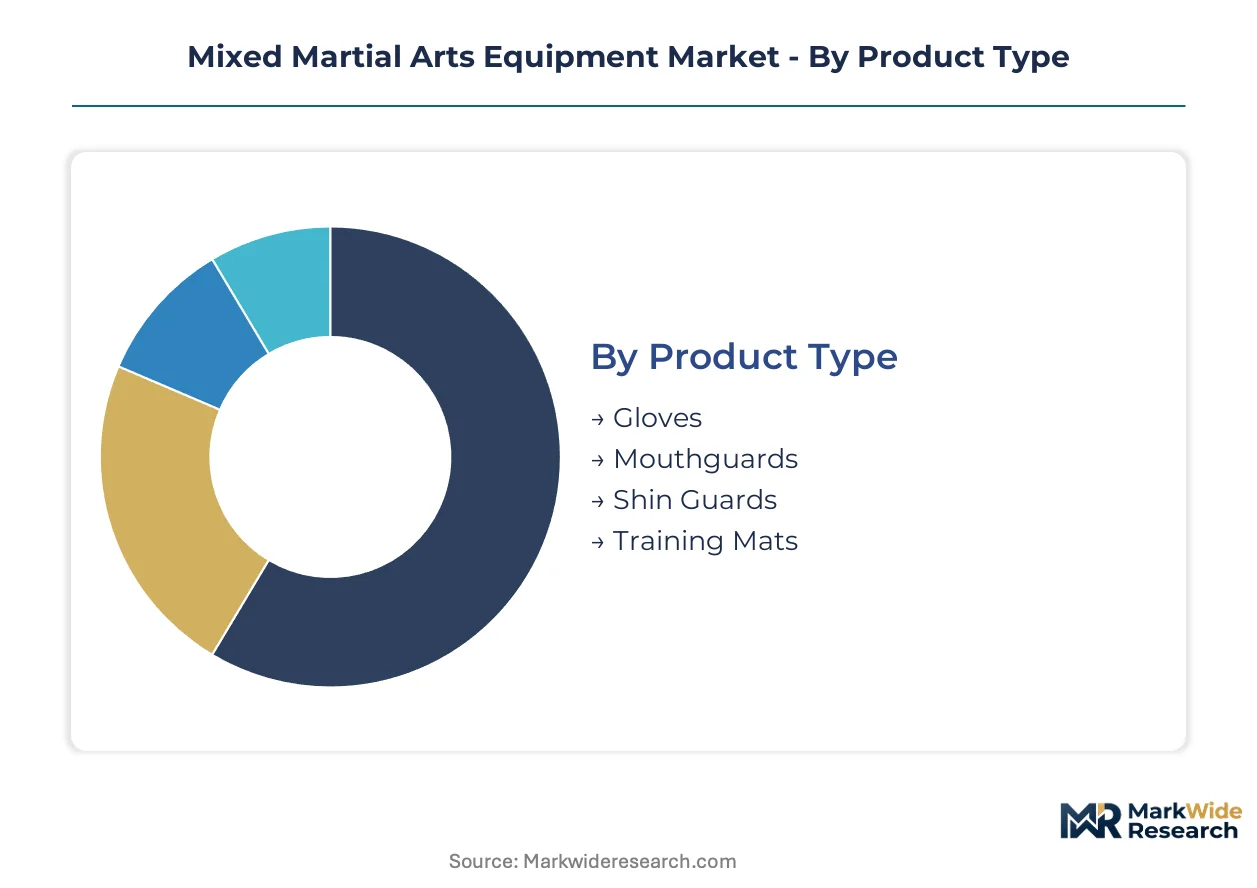
Segmentation in MMA equipment reflects divergent performance demands across competitive tiers and training intensities. Product specifications, material durability thresholds, and end-user sophistication levels create distinct procurement patterns that manufacturers must address through specialized design architectures.
Product Type:
Mature competition formats anchor demand for standardized protective gear while emerging training modalities expand equipment variety beyond traditional fight-sport configurations.
- Gloves:Layered foam padding encased in leather or synthetic shells with reinforced stitching rated for repeated high-impact strikes. Mandatory use across all competitive and training formats in the United States, Brazil, and Thailand concentrates procurement volume through institutional channels and fight academy bulk orders.
- Mouthguards:Medical-grade polymer constructions engineered for dental injury prevention with biocompatibility certification for regulatory compliance. Dental injury awareness spreads fastest among amateur participants in California and Texas metro markets where gym membership density supports education initiatives.
- Shin Guards:Foam-backed protective shells designed for Muay Thai and kickboxing integration within MMA training protocols.
- Training Mats:Impact-absorbing surface systems for grappling and takedown practice in commercial gym installations.
Gloves retain volume leadership; mouthguards hold the steepest expansion curve.
Material:
Cost tier differentiation separates professional-grade durability requirements from recreational price sensitivity and emerging ethical material preferences.
- Leather:Premium hide constructions offering superior durability and fit molding through repeated use cycles. Professional fighters in Nevada and New York state-sanctioned bouts specify leather for its performance consistency under athletic commission scrutiny.
- Synthetic Fabrics:Engineered polymer alternatives reducing weight while maintaining abrasion resistance for high-frequency training. REACH substance restrictions in the European Union accelerate reformulation of coatings and adhesive compounds used in equipment shells.
- Foam:Multi-layered EVA and polymer cores with gradient density profiles replacing uniform padding constructions.
- Rubber:High-grip surface compounds for mat traction and equipment base stabilization in humid training environments.
Leather dominates professional procurement; synthetic fabrics are expanding most quickly in recreational segments.
Use Case:
Application intensity determines equipment replacement frequency and specification rigor across the training-to-competition spectrum.
- Training:Durability-optimized designs with reinforced stitching for daily high-volume use in commercial gym environments. Subscription-based replacement programs in California and Texas metro markets displace one-time retail purchases among high-frequency consumers.
- Professional Fighting:Commission-certified specifications with documented padding density and material transparency for sanctioned bouts. Nevada, California, and New York state athletic commissions impose divergent equipment specifications that fragment production runs.
- Conditioning:Specialized load-bearing equipment for strength and cardio integration within fight-sport training protocols.
- Recreational:Entry-level protective gear for casual participants prioritizing cost accessibility over performance optimization.
Training applications generate the highest unit volume; professional fighting commands the premium pricing tier.
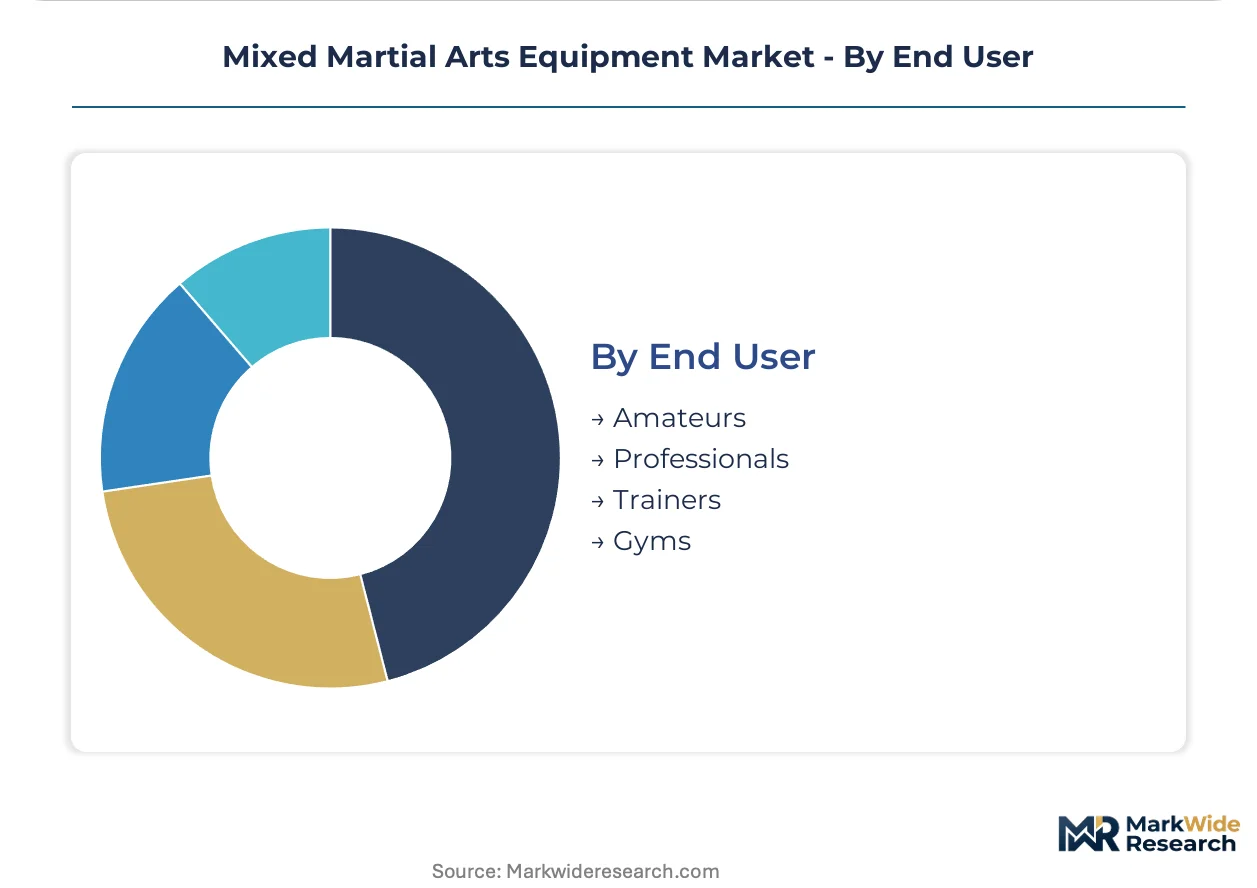
End User:
Customer sophistication and procurement authority shape equipment selection from individual retail purchases to institutional bulk contracting.
- Amateurs:Individual consumers purchasing through direct-to-consumer channels and specialty retail with guidance from gym affiliations. FDA biocompatibility mandates for mouthguards accelerate dental protection adoption among amateur training facilities seeking liability protection.
- Professionals:Athletes with sponsor-provided equipment and personalized fitting requirements through brand ambassador relationships.
- Trainers:Individual coaches procuring demonstration gear and protective equipment for client instruction sessions.
- Gyms:Institutional buyers negotiating bulk contracts for standardized equipment across member populations and class schedules.
Gyms drive institutional procurement volume; amateurs represent the broadest addressable population base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Brazil while Thailand operates on thinner margins tied to manufacturing density. Commission certification requirements and fight academy procurement standards create regional asymmetries in equipment value capture.
United States
State athletic commissions in Nevada, California, and New York mandate divergent glove padding densities and material transparency standards. FDA biocompatibility rules for mouthguards accelerate dental protection adoption across amateur training facilities. Los Angeles and Las Vegas anchor the fight promotion ecosystem with concentrated gym infrastructure driving bulk equipment orders.
Brazil
São Paulo and Rio de Janeiro fight academies are expanding protective gear procurement for both competitive and recreational segments. ANVISA, the national health regulator, enforces medical-grade material standards for mouthguard imports. Manufacturing partnerships with Thai producers concentrate equipment supply through southeastern metro distribution hubs.
Thailand
Bangkok industrial zones cluster Muay Thai equipment production, creating geographic vulnerability to regional logistics disruptions. The country's national industrial standards authority maintains export certification frameworks for protective athletic gear. Chonburi and Phuket host training tourism facilities sourcing equipment directly from metropolitan manufacturers.
United Kingdom
London and Manchester gym chains are standardizing equipment specifications across membership tiers. REACH substance restrictions compel reformulation of synthetic leather coatings in equipment shells. Birmingham retail distribution centers serve as the primary entry point for EU-compliant gear into the British market.
Japan
Tokyo and Osaka martial arts schools integrate MMA training protocols with traditional discipline foundations. METI oversees industrial standards alignment for protective equipment imports under JIS certification frameworks. Yokohama logistics hubs facilitate distribution across the Kanto region's concentrated gym network.
Mixed Martial Arts Equipment Market Competitive Environment
Premium-positioned fight-sport specialists and broad-catalog institutional suppliers split the market into asymmetric competitive tiers. The vendor base concentrates around UFC-aligned premium brands and martial arts school contract holders. Two strategic archetypes dominate: visibility-driven athlete sponsors and institutional procurement anchors. Competitive moves center on direct-to-consumer platform construction and ISO certification acquisition for Olympic committee access.
Within the premium-positioned tier, Venum and Hayabusa Fightwear Inc. exemplify fight-sport specialists leveraging athlete visibility and biomechanical engineering differentiation. Century Martial Art Supply LLC occupies a position as the institutional procurement anchor through broad catalog distribution and martial arts school contracts. These three entities represent the strategic spectrum from high-visibility sponsorship to volume-driven institutional supply.
| Leading Market Players |
|---|
| Venum |
| Century Martial Art Supply LLC |
| Adidas AG |
| Twins Special Co. Ltd. |
| Ringside, Inc. |
| Everlast Worldwide Inc. |
| TITLE Boxing LLC |
| Fairtex |
| Hayabusa Fightwear Inc. |
| Others |
Value Chain & Pricing Dynamics
Bangkok industrial zones concentrate Muay Thai equipment manufacturing, and their capacity utilization rates directly shape pricing power for downstream distributors across North America and Europe. Leather hide costs from Brazilian tanneries and synthetic polymer feedstocks from Chinese petrochemical clusters constitute the dominant input cost structure, while state athletic commission certification requirements in Nevada and California impose quality thresholds that prevent pure price competition at the professional tier.
Pricing Analysis
Configured-to-order pricing for commission-certified gloves commands a substantial premium over standard training-grade equipment. Three-tier pricing structure across premium, standard, and economy levels separates professional fight gear from amateur training lines and entry-level recreational products. Price differentiation hinges on ASTM certification status and leather grade sourcing. Cost compression in synthetic fabric tiers is intensifying because REACH-compliant reformulation expenses are squeezing mid-market manufacturers. Recreational gym chains exhibit highest price sensitivity; professional fighters and sanctioned bout promoters demonstrate lowest elasticity due to regulatory compliance mandates.
Supply Chain Analysis
Extended payment terms from Bangkok manufacturers to Brazilian and US distributors have become standard practice, with supply-chain finance facilities bridging working capital gaps during ASTM certification delays. Geographic supply concentration centers on Thailand, China, and Brazil for finished goods and raw materials respectively. Raw material dependencies draw from Argentine cattle hides, Saudi petrochemical derivatives, and Taiwanese synthetic textile innovations. Single-source vulnerability around Bangkok industrial clustering creates exposure to regional logistics disruptions from monsoon flooding or port congestion. Distribution runs through specialty fight-sport retailers, direct-to-consumer platforms, and institutional gym contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
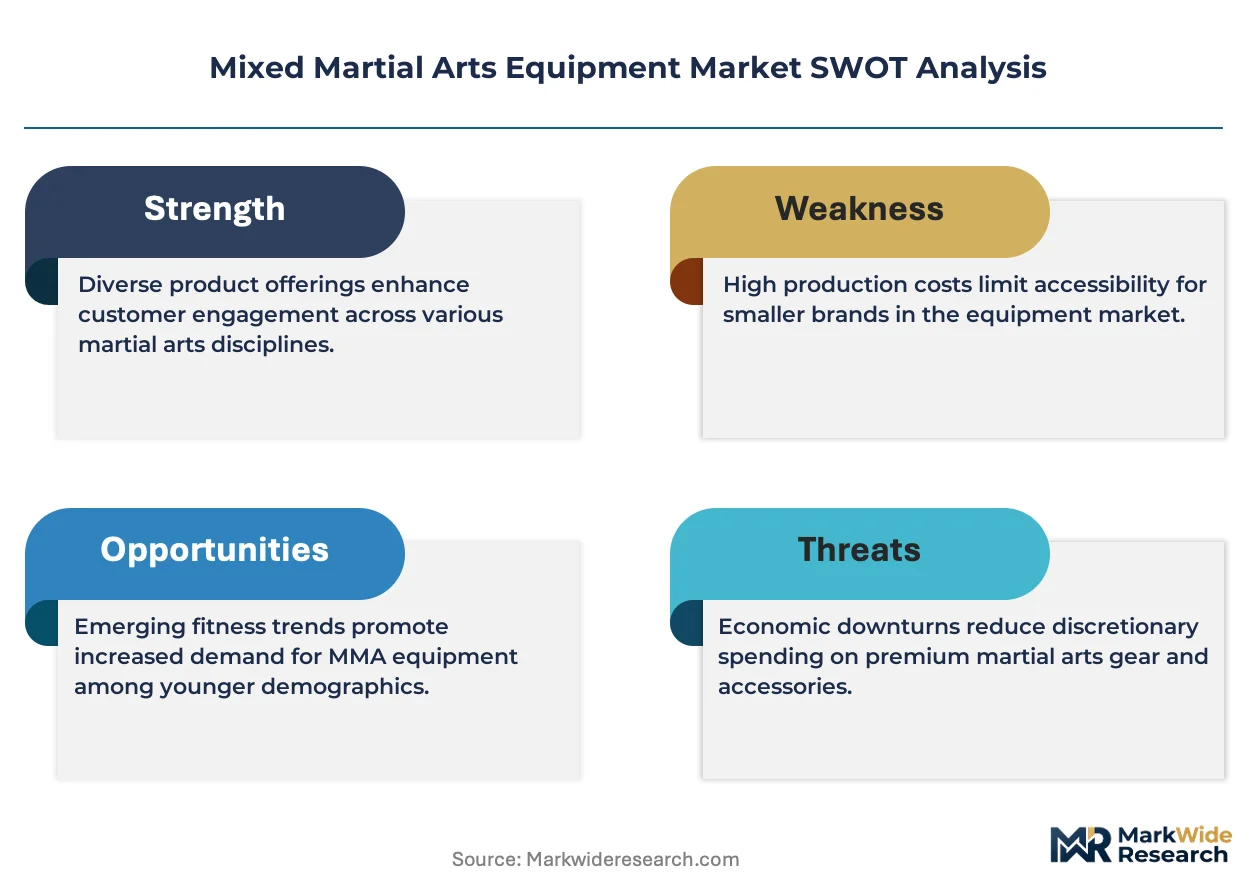
This market functions as a regulatory-entrenchment defensive moat. State athletic commission certification requirements and ISO 9001 alignment for Olympic committee access create structural switching costs that protect incumbent positioning.
For Market Incumbents: Build regulatory-entrenchment moats by deepening ISO certification coverage across European and Asian national Olympic committees ahead of potential Los Angeles inclusion. Secure exclusive supply agreements with Nevada and California state athletic commissions to lock in padding density specification influence. Vertical integration into Bangkok manufacturing partnerships reduces exposure to Thai logistics disruptions. Invest in biomechanical engineering talent retention as emerging DTC brands poach specialized glove designers. For New Entrants and Emerging Players: Establish a beachhead in India's nascent MMA training infrastructure through distribution partnerships with emerging metro gym chains in Mumbai and Delhi. Target subscription-based equipment replacement programs in California and Texas where high-frequency training consumers show enrollment density. White-space opportunity exists in REACH-compliant synthetic leather formulations for EU institutional contracts. Go-to-market angle should emphasize direct-to-consumer platforms with athlete content integration rather than brick-and-mortar retail markup. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment subscription programs and institutional gym bulk contracts. Long-term viability across the analysis window favors brands with Olympic committee certification pathways and multi-jurisdiction regulatory compliance capabilities. Acquisition target archetype: mid-tier synthetic fabric specialists with ISO 9001 alignment and DTC platform infrastructure. Signal to watch: state athletic commission rule harmonization on glove padding density that would strand non-compliant legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Acquisition | Opens institutional procurement pathways across European and Asian national Olympic committees. |
| Direct-to-Consumer Platform Launch | Bypasses traditional retail markup while enabling athlete content integration for brand building. |
| REACH-Compliant Material Reformulation | Maintains EU market access as substance restrictions tighten on synthetic leather coatings. |
| Subscription-Based Replacement Program | Captures high-frequency California and Texas training consumers with predictable recurring revenue. |
| Biomechanical Engineering Talent Acquisition | Addresses scarcity of specialized glove designers combining combat sport knowledge with orthopedic science. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fight academy owners, state athletic commission officials, equipment procurement managers at gym chains, and regulatory affairs specialists at mouthguard manufacturers. Secondary validation drew from FDA 510(k) filings for dental protection devices, ASTM standards documentation, ISO certification registries, and customs trade data on leather and synthetic textile imports. Bottom-up equipment shipment data from Bangkok industrial zones was triangulated against top-down gym membership expansion rates across target metro markets.
Calibration against historical certification timeline data and fight academy equipment refresh cycles anchored the analytical framework. Segmentation dimensions modeled include product type, material grade tier, use case intensity, and end-user procurement authority across the projection horizon. CAGRs were derived from equipment replacement frequency patterns and institutional bulk contract expansion trajectories. Industry-specific forecast inputs incorporated state athletic commission rule evolution scenarios and Olympic recognition pathway probabilities.
Stress conditions across leather price volatility, Thai logistics disruption severity, and regulatory harmonization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding gym infrastructure buildout rates and amateur participation growth. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Wetsuits Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Sandbells Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Crampon Market