
 Europe Running Gear Market | 2026-2036
Europe Running Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Running Gear Market Intelligence
The gap between premium carbon-plated racing shoes and basic entry-level trainers is recalibrating how brands allocate R&D budgets across Europe. Nike, Inc. leverages its proprietary foam formulations and athlete co-development programs to dominate the performance tier. ASICS Corporation anchors its position through biomechanical research partnerships with European sports institutes. Adidas AG competes by integrating recycled ocean plastics into mid-range lines, blurring the sustainability-price boundary.
Running gear encompasses footwear, apparel, accessories, and wearable electronics engineered for repetitive impact absorption, moisture management, and kinematic tracking during locomotion at speeds exceeding eight kilometers per hour. Shoes incorporate ethylene-vinyl acetate midsoles with energy-return coefficients between fifty and seventy percent, while wearables integrate photoplethysmography sensors for real-time cadence and heart-rate variability feedback. The shoes segment leads absolute revenue but wearables generates the highest margin pools as Garmin Ltd. and others command premium pricing for GPS-enabled pacing analytics. Accessories targeting trail runners shows the fastest volume trajectory, driven by hydration vest and headlamp demand from outdoor adventurers. The apparel segment remains mature, with cotton-polyester blends giving way to merino wool and regenerated nylon across mid-range and premium tiers.
REACH restricts per- and polyfluoroalkyl substances in water-repellent textiles, forcing reformulation of jacket membranes sold across Germany, France, and Italy. The EU Green Deal's textile strategy mandates extended producer responsibility schemes that raise compliance costs for budget-tier imports. ECHA substance evaluations now cover antimicrobials used in sock liners, creating certification bottlenecks for non-EU suppliers. Stakeholders must monitor how the EU AI Act classifies algorithmic coaching features embedded in connected footwear and wearables.
Market Dynamics
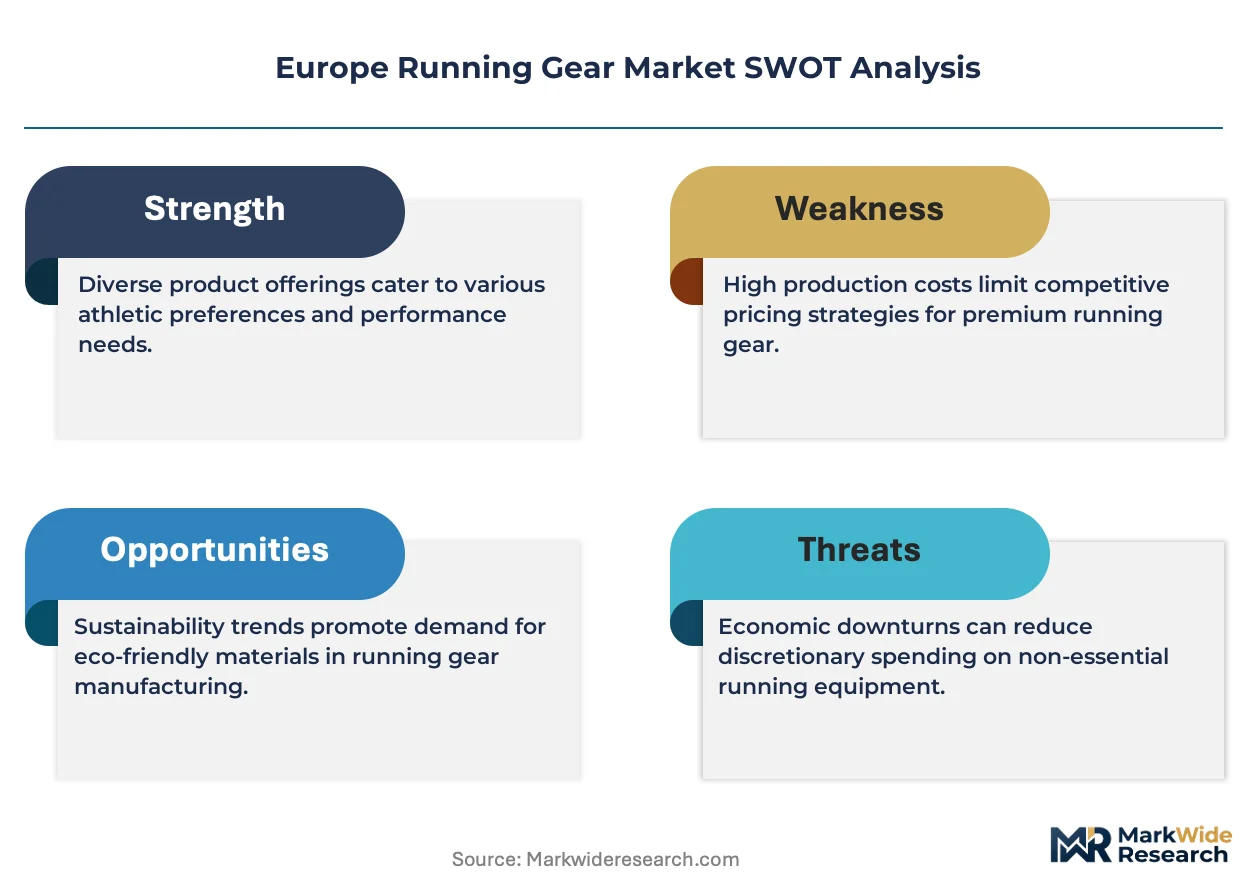
REACH chemical restrictions and the EU Green Deal's circular economy mandates are forcing material reformulation across the entire European running gear supply chain, compressing margins for budget-tier imports while rewarding compliant domestic producers.
Growth Catalysts
- Trail Running Surge:Casual runners across Germany and France are migrating from road to trail surfaces, expanding demand for specialized traction outsoles and hydration systems.
- Wearable Integration:Photoplethysmography sensors embedded in GPS-enabled pacing devices now command premium positioning among fitness enthusiasts seeking real-time cadence feedback.
- EU Green Deal Textile Strategy:Extended producer responsibility schemes accelerate investment in recycled ocean plastic midsoles and regenerated nylon uppers.
Market Restraints
- Ethylene-Vinyl Acetate Cost Volatility:Petrochemical feedstock fluctuations destabilize midsole production economics for energy-return formulations.
- Antimicrobial Certification Bottlenecks:ECHA substance evaluations on sock liner treatments create month-long delays for non-EU suppliers seeking market entry.
- Per- and Polyfluoroalkyl Substance Bans:REACH restrictions on water-repellent textile membranes force jacket manufacturers into expensive reformulation cycles.
Strategic Opportunities
- Algorithmic Coaching Features:The EU AI Act's classification framework for connected footwear creates first-mover advantage for brands embedding kinematic tracking.
- Merino Wool Substitution:Cotton-polyester blend displacement in mid-range apparel opens procurement contracts with Australian and New Zealand fiber cooperatives.
- Specialty Store Channel Expansion:Urban centers in Italy and Spain show underpenetrated distribution for biomechanical fitting services.
Industry Challenges
- Biomechanical Research Talent Scarcity:European sports institutes face capacity constraints in athlete co-development programs.
- CSRD Reporting Integration:Dual compliance with circular economy mandates and corporate sustainability disclosure requirements strains mid-tier finance functions.
- Legacy Inventory Disposal:Pre-REACH water-repellent stock requires specialized waste handling under extended producer responsibility schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Running Gear Market |
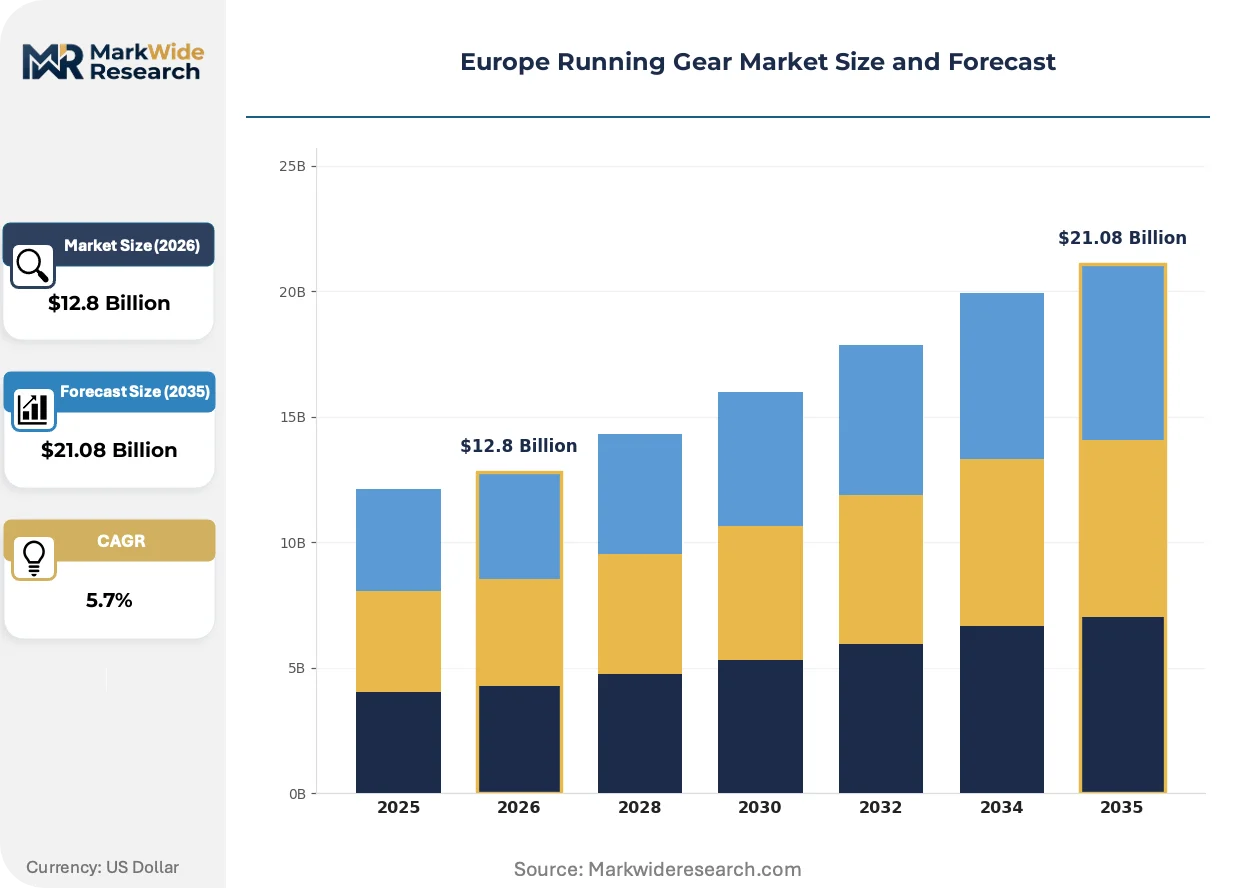
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Apparel, Accessories, Wearables End User: Athletes, Casual Runners, Fitness Enthusiasts, Outdoor Adventurers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | ASICS Corporation, Under Armour, Inc., Nike, Inc., Brooks Sports, Inc., New Balance Athletics, Inc., Adidas AG, Skechers USA, Inc., Garmin Ltd., Puma SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Running Gear Market Strategic Shifts & Innovations
Carbon-plate foam sandwich constructions are compressing performance differentiation timelines across European racing categories. Material science convergence with digital coaching interfaces now determines competitive positioning.
Supercritical nitrogen-infused PEBA foam is electrifying energy-return coefficients in marathon racing flats. Elite amateur runners in the UK and Netherlands are adopting these platforms at twice the rate of recreational segments. This technology is electrifying the gap between podium-capable and training-tier footwear, forcing brands to license formulations or exit the premium tier entirely.
REACH authorization requirements for textile finishing chemicals now cover antimicrobial silver nanoparticles used in odor-control sock liners. German and French authorities are accelerating enforcement timelines. Trail-running apparel with membrane technologies faces the steepest compliance cost escalation, pushing manufacturers toward fluorine-free alternatives.
Direct-to-consumer subscription models for wearable replacement cycles are displacing traditional retail stocking patterns. Specialty running stores in Berlin and Amsterdam are unbundling gait analysis from product sales, charging fees for biomechanical assessment. This channel restructuring is most visible in the Benelux region, where urban density supports rapid fulfillment of customized insole orders.
Europe Running Gear Market Segmentation
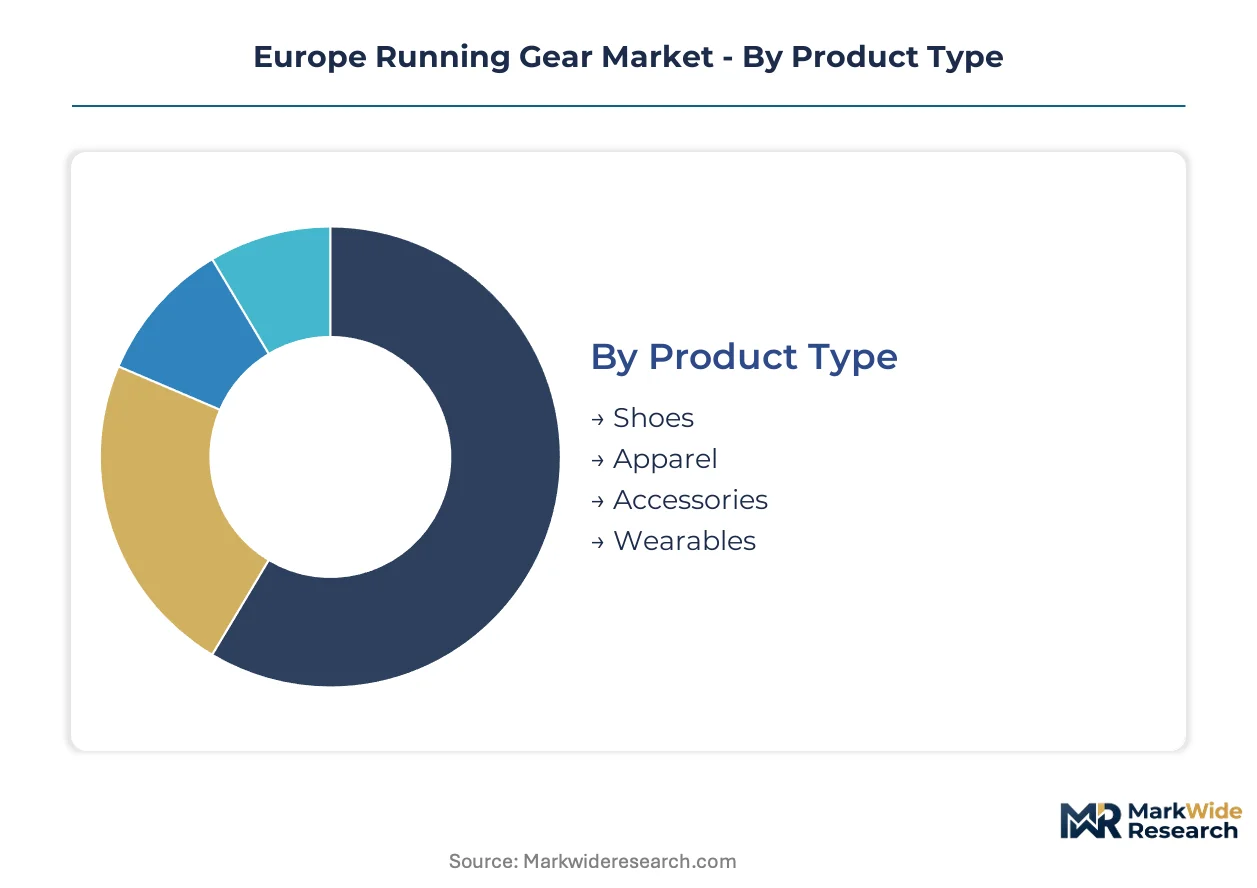
Segmentation in Europe's running gear market reveals how capital deployment, regulatory exposure, and channel economics fragment opportunity across distinct product and customer configurations. Understanding these boundaries allows manufacturers to match R&D intensity with margin recovery potential.
Product Type:
Capital intensity peaks in segments requiring specialized tooling, biomaterial synthesis, or sensor integration.
- Shoes:Ethylene-vinyl acetate midsoles with energy-return coefficients between fifty and seventy percent dominate manufacturing investment. German and French trail running participation is driving specialized traction outsole development, though petrochemical feedstock volatility destabilizes production economics.
- Wearables:Photoplethysmography sensors embedded in GPS-enabled devices command the highest margin pools. Garmin Ltd. and competitors extract premium pricing for real-time cadence and heart-rate variability feedback from fitness enthusiasts in Western European urban centers.
- Apparel:Cotton-polyester blends are yielding to merino wool and regenerated nylon across mid-range and premium tiers, with REACH compliance costs compressing budget-tier imports.
- Accessories:Hydration vests and headlamps for trail runners show accelerating volume trajectory from outdoor adventurers migrating from road to off-road surfaces.
Shoes absorb the bulk of installed capacity; wearables is expanding most quickly.
End User:
Application intensity varies by training volume, technical sophistication, and willingness to pay for biomechanical optimization.
- Casual Runners:The fastest-expanding cohort across Germany and France, migrating from road to trail surfaces and demanding entry-level traction systems alongside hydration accessories.
- Fitness Enthusiasts:Concentrated in Western European urban centers, this segment drives demand for wearable integration and real-time kinematic tracking through specialty retail channels.
- Athletes:Elite amateur runners in the UK and Netherlands adopt supercritical nitrogen-infused PEBA foam platforms at twice the rate of recreational segments, forcing brands into licensing arrangements or premium tier exit.
- Outdoor Adventurers:Trail-running specialists requiring membrane technologies and fluorine-free alternatives as REACH restrictions on per- and polyfluoroalkyl substances escalate compliance costs.
Casual runners command the largest addressable base; outdoor adventurers post the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect fulfillment speed, service bundling capability, and urban density requirements.
- Specialty Stores:Biomechanical fitting services and gait analysis unbundling are restructuring retail economics in Berlin and Amsterdam, with urban density supporting rapid customized insole fulfillment.
- Online Retail:Direct-to-consumer subscription models for wearable replacement cycles are displacing traditional stocking patterns across the Benelux region.
- Supermarkets:Budget-tier footwear and basic cotton-polyester apparel serve price-sensitive casual runners with limited technical requirements.
- Department Stores:Mid-range positioning dominates, though extended producer responsibility schemes under the EU Green Deal raise compliance costs for imported inventory.
Online retail captures the fastest volume migration; specialty stores retain the highest service-margin extraction.
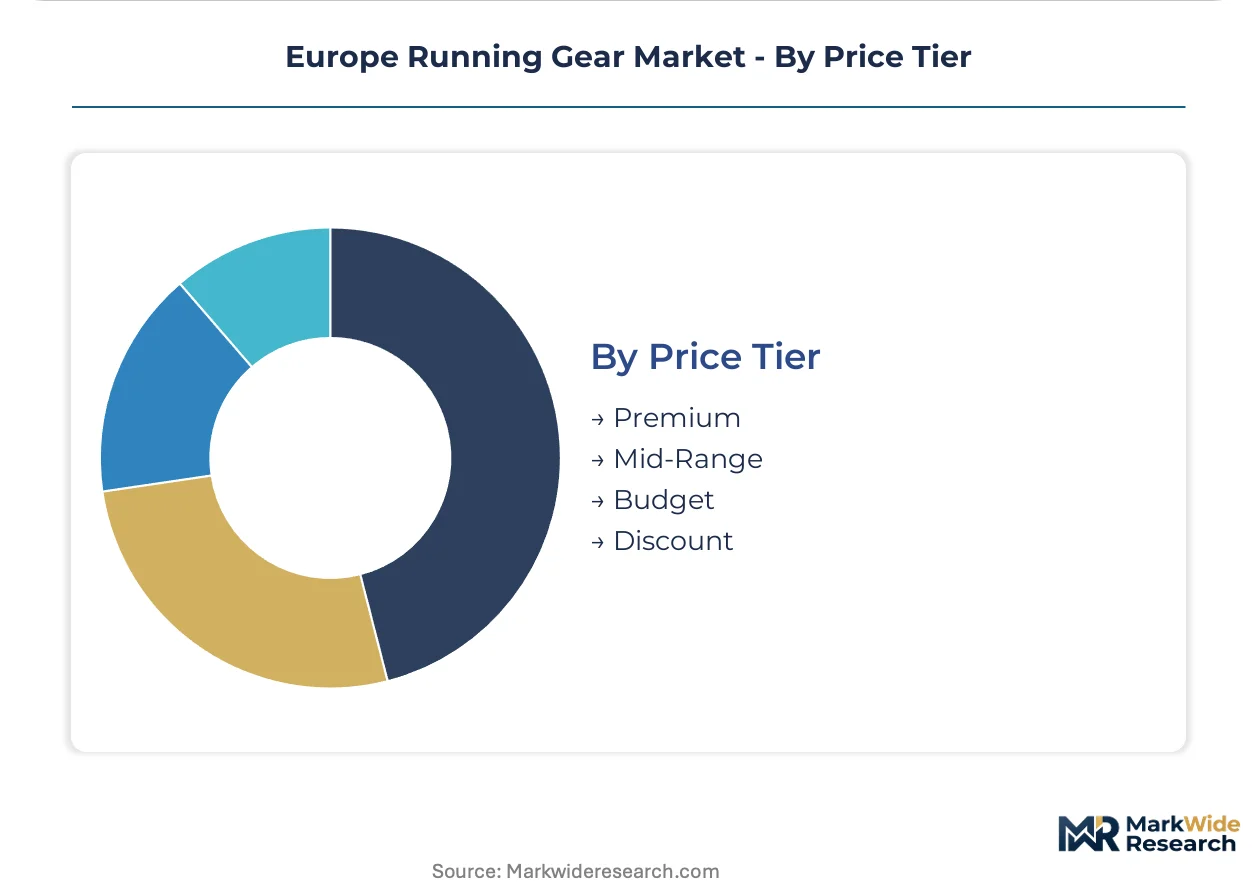
Price Tier:
Margin architecture stratifies by material certification grade, performance tier, and sustainability credential intensity.
- Premium:Carbon-plated racing platforms and GPS-enabled wearables with algorithmic coaching features target elite amateurs and fitness enthusiasts seeking kinematic tracking advantages ahead of EU AI Act classification frameworks.
- Mid-Range:Recycled ocean plastic midsoles and regenerated nylon uppers blur the sustainability-price boundary, appealing to environmentally conscious casual runners in Italy and Spain.
- Budget:Basic ethylene-vinyl acetate formulations face margin compression from REACH chemical restrictions and circular economy mandates, concentrating procurement among compliant domestic producers.
- Discount:Pre-REACH water-repellent inventory and non-certified antimicrobial treatments require specialized waste handling under extended producer responsibility schemes, shrinking viable supply sources.
Premium tier captures the highest margin concentration; mid-range is gaining share fastest as sustainability credentials displace pure performance positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors specialty retail innovation across the continent, with Amsterdam and London forming secondary clusters for wearable distribution and biomechanical service unbundling.
Germany
Trail running participation among casual runners is accelerating demand for specialized traction outsoles and hydration systems in Bavarian and Black Forest regions. ECHA substance evaluations on antimicrobial silver nanoparticles create certification bottlenecks for sock liner imports. The Rhine-Ruhr corridor concentrates manufacturing compliance expertise as domestic producers absorb market share from REACH-noncompliant budget imports.
France
Outdoor adventurers migrating from road to trail surfaces are expanding volume for headlamp and hydration vest categories in the Alpine foothills. ANSM and CNIL oversight intersects with EU AI Act classification frameworks for algorithmic coaching features in connected footwear. Lyon and Grenoble host emerging clusters for fluorine-free membrane technology development as authorities accelerate PFAS enforcement timelines.
United Kingdom
Elite amateur runners in London and the Southeast adopt supercritical nitrogen-infused PEBA foam platforms at twice recreational segment rates. Post-Brexit regulatory divergence from REACH creates dual compliance burdens for importers serving both UK and EU markets. Manchester and Birmingham specialty stores are unbundling gait analysis from product sales, charging standalone fees for biomechanical assessment.
Netherlands
Benelux urban density supports rapid fulfillment of customized insole orders through direct-to-consumer subscription models displacing traditional retail stocking. The Dutch Authority for Consumers and Markets enforces extended producer responsibility schemes under EU Green Deal textile strategy alignment. Amsterdam anchors wearable replacement cycle logistics while Eindhoven region develops sensor integration capabilities for photoplethysmography-enabled devices.
Italy
Mid-range sustainability positioning with recycled ocean plastic midsoles is gaining fastest share among environmentally conscious casual runners in Milan and Turin. REACH restrictions on water-repellent textile membranes force expensive reformulation cycles for jacket manufacturers in Lombardy and Piedmont. The country's national textile regulator coordinates with ECHA on pre-REACH inventory disposal requirements under circular economy mandates.
Europe Running Gear Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the European running gear supply chain. The market structure concentrates around three tiers: multinational sportswear conglomerates with integrated R&D pipelines, specialized biomechanical research partners, and digital-native wearable platforms. Strategic archetypes include foam formulation licensors, circular material integrators, and algorithmic coaching feature developers. Competitive moves center on athlete co-development program expansion and recycled feedstock procurement contracting.
Among Japanese-origin sportswear specialists, ASICS Corporation exemplifies the biomechanical research partnership archetype through European sports institute collaboration. Nike, Inc. and Adidas AG occupy contrasting positions on the sustainability-performance boundary, with the former emphasizing proprietary foam development and the latter integrating circular material credentials into mid-range positioning. Garmin Ltd. anchors the wearable tier through GPS-enabled pacing analytics commanding premium pricing from fitness enthusiasts.
| Leading Market Players |
|---|
| ASICS Corporation |
| Under Armour, Inc. |
| Nike, Inc. |
| Brooks Sports, Inc. |
| New Balance Athletics, Inc. |
| Adidas AG |
| Skechers USA, Inc. |
| Garmin Ltd. |
| Puma SE |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts concentrated in Western European urban centers anchor value-based pricing for GPS-enabled wearables and biomechanical fitting services, with subscription models for wearable replacement cycles displacing traditional per-unit transactions across the Benelux region.
Pricing Analysis
Energy-return coefficients in ethylene-vinyl acetate midsoles anchor value-based pricing for performance footwear, with carbon-plated racing platforms commanding premiums tied to measurable speed outcomes. Price differentiation rests on REACH certification grade and recycled content percentage, as EU Green Deal extended producer responsibility schemes add compliance cost layers. Cost compression in budget-tier ethylene-vinyl acetate formulations is intensifying because petrochemical feedstock volatility destabilizes production economics. Casual runners migrating from road to trail surfaces show highest price sensitivity, while elite amateurs in the UK and Netherlands demonstrate lowest sensitivity for supercritical nitrogen-infused PEBA foam platforms.
Supply Chain Analysis
Reverse-logistics flows for pre-REACH water-repellent textile inventory require specialized waste handling under extended producer responsibility schemes, with German and French authorities accelerating enforcement timelines. Manufacturing concentration spans Vietnam, China, and Bangladesh for apparel assembly, while sensor integration for photoplethysmography-enabled devices centers on the Netherlands and Taiwan. Raw material dependencies include petrochemical derivatives for midsole formulations, Australian merino wool fiber, and regenerated nylon from ocean plastic recovery. Single-source vulnerability in antimicrobial silver nanoparticle supply creates month-long certification bottlenecks for non-EU suppliers. Distribution runs through specialty stores unbundling gait analysis services and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into recycled feedstock procurement and captive biomaterial synthesis capabilities is reshaping competitive positioning, as brands race to secure compliant supply ahead of REACH authorization expansions.
For Market Incumbents: To counter margin compression from ECHA substance evaluations on sock liner treatments, incumbents should deepen in-house production of fluorine-free membrane technologies and secure long-term procurement contracts with Australian and New Zealand fiber cooperatives for merino wool substitution.
For New Entrants and Emerging Players: Capture underpenetrated specialty store distribution in Italian and Spanish urban centers for biomechanical fitting services, with algorithmic coaching feature development as the go-to-market angle ahead of EU AI Act classification finalization.
For Investors and Strategic Acquirers: The window for entry favors circular material integrators with REACH-compliant certification infrastructure and established European sports institute partnerships. Long-term viability hinges on defensible feedstock procurement positions. Practitioners should monitor ECHA authorization timelines for antimicrobial additives and EU AI Act implementation guidance as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Procurement | Secures compliant supply chains ahead of REACH authorization expansions for textile finishing chemicals. |
| Biomechanical Fitting Service Expansion | Captures margin extraction opportunities in underpenetrated Italian and Spanish urban retail clusters. |
| Fluorine-Free Membrane Development | Addresses PFAS enforcement acceleration in Germany and France with compliant trail-running apparel. |
| Algorithmic Coaching Integration | Positions ahead of EU AI Act classification frameworks for connected footwear kinematic tracking. |
| Direct-to-Consumer Subscription Launch | Displaces traditional retail stocking patterns through wearable replacement cycle models in Benelux. |
Research Approach
Multi-period observation of trail running participation rates, REACH compliance cost trajectories, and wearable adoption patterns anchored the trend analysis, supplemented by interviews with footwear brand R&D directors, specialty retail buyers in Berlin and Amsterdam, ECHA regulatory affairs consultants, and biomaterial procurement managers. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal textile strategy documentation, customs records for ethylene-vinyl acetate imports, and SEC filings of listed sportswear conglomerates. Bottom-up segment sizing triangulated with top-down macroeconomic indicators across the European running gear supply chain.
An input-output matrix structured the analytical framework, modeling volume and value across product type, end user archetype, distribution channel, and price tier dimensions over the projection horizon. CAGRs were derived from segment-level growth rate synthesis. Industry-specific forecast inputs included petrochemical feedstock price indices and ECHA authorization timeline probabilities for antimicrobial treatments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH regulatory expansion scope and EU AI Act enforcement intensity. Forecasts reflect documented assumptions on compliance cost pass-through rates and casual runner segment retention. Practitioners should monitor ECHA substance evaluation acceleration signals and carbon-plate foam technology licensing announcements for early indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Riding Gear Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Cycling Helmet Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Tetherball Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Shuttlecock Market