
 North America Sporting Goods Market | 2026-2036
North America Sporting Goods Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sporting Goods Market Analytics
Asset-light leasing models for high-end fitness equipment is tilting competitive dynamics toward brands that minimize capital deployment. Nike, Inc. leverages its direct-to-consumer platform to control pricing and capture margin pools traditionally ceded to wholesale partners. New Balance Athletics, Inc. anchors its manufacturing presence in domestic facilities, sustaining regional supply chain resilience against trans-Pacific disruption. Wilson Sporting Goods Co. specializes in institutional procurement channels, occupying a defensible position in school and league sponsorship ecosystems.
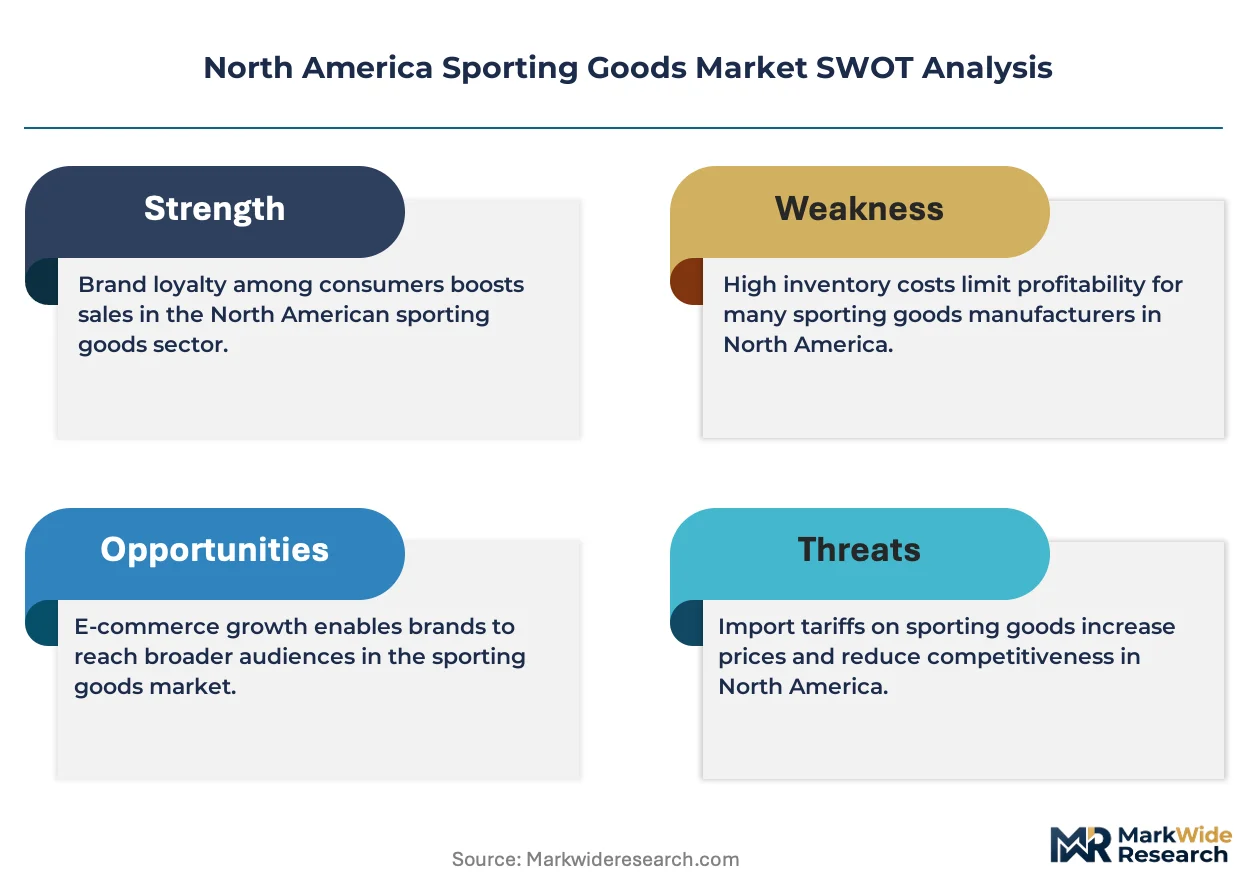
North America sporting goods encompass equipment, apparel, and footwear engineered for athletic performance, recreation, and physical conditioning, typically constructed from advanced polymers, composite fibers, or moisture-wicking textiles designed to withstand repetitive biomechanical stress. These products serve commercial purposes spanning competitive sports, fitness training, outdoor recreation, and casual leisure activity across consumer and institutional buyer segments. Fitness equipment commands expanding shelf space as recreational players and fitness enthusiasts shift spending toward home-based strength and cardio systems. Premium price tiers capture disproportionate margin contribution as lululemon athletica Inc. and comparable brands condition consumers to associate technical fabric innovation with elevated price positioning.
The U.S. Consumer Product Safety Commission and Health Canada enforce divergent testing protocols for protective gear, compelling manufacturers to maintain dual certification pathways or standardize to the stricter jurisdiction. California's Proposition 65 chemical disclosure requirements add compliance layers for apparel and equipment containing regulated substances, shaping material selection across supplier networks. Stakeholders must monitor how state-level environmental regulations propagate beyond California, determining whether to front-run compliance nationally or maintain fragmented product specifications by destination market.
Market Dynamics
The U.S. Consumer Product Safety Commission's updated equipment safety protocols are compelling manufacturers to redesign protective gear and elevate testing standards, creating a structural compliance burden that favors scaled producers with dedicated certification infrastructure.
Growth Catalysts
- Home-based workout culture:Fitness enthusiasts represent a rapidly expanding buyer segment as post-pandemic exercise habits solidify around residential strength and cardio systems.
- California Proposition 65:Chemical disclosure requirements for regulated substances are shaping material selection across supplier networks and elevating transparency standards.
- Boutique fitness studio density:Metropolitan corridors in California concentrate demand intensity through elevated outdoor recreation participation and premium studio penetration.
Market Restraints
- Dual certification pathways:The U.S. Consumer Product Safety Commission and Health Canada enforce divergent testing protocols for protective gear, forcing manufacturers to maintain parallel compliance tracks or standardize to stricter jurisdiction.
- Trans-Pacific supply disruption:Concentrated sourcing from Asian manufacturing clusters exposes inventory cycles to port congestion and tariff volatility.
- Advanced polymer input costs:Specialized composite fibers and moisture-wicking textiles face price pressure from petrochemical feedstock fluctuations.
Strategic Opportunities
- Asset-light leasing models:High-end fitness equipment rental platforms minimize capital deployment for consumers while generating recurring revenue streams for operators.
- Direct-to-consumer platform expansion:Brands capturing margin pools traditionally ceded to wholesale partners through owned digital channels.
- Institutional procurement channels:School and league sponsorship ecosystems offer defensible positions with multi-year contract visibility and volume predictability.
Industry Challenges
- Biomechanical testing expertise:Equipment engineers with specialized knowledge of repetitive stress analysis and injury prevention protocols remain scarce relative to product development timelines.
- State-level regulatory fragmentation:Environmental regulations propagating beyond California force decisions on whether to front-run compliance nationally or maintain fragmented product specifications by destination market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sporting Goods Market |
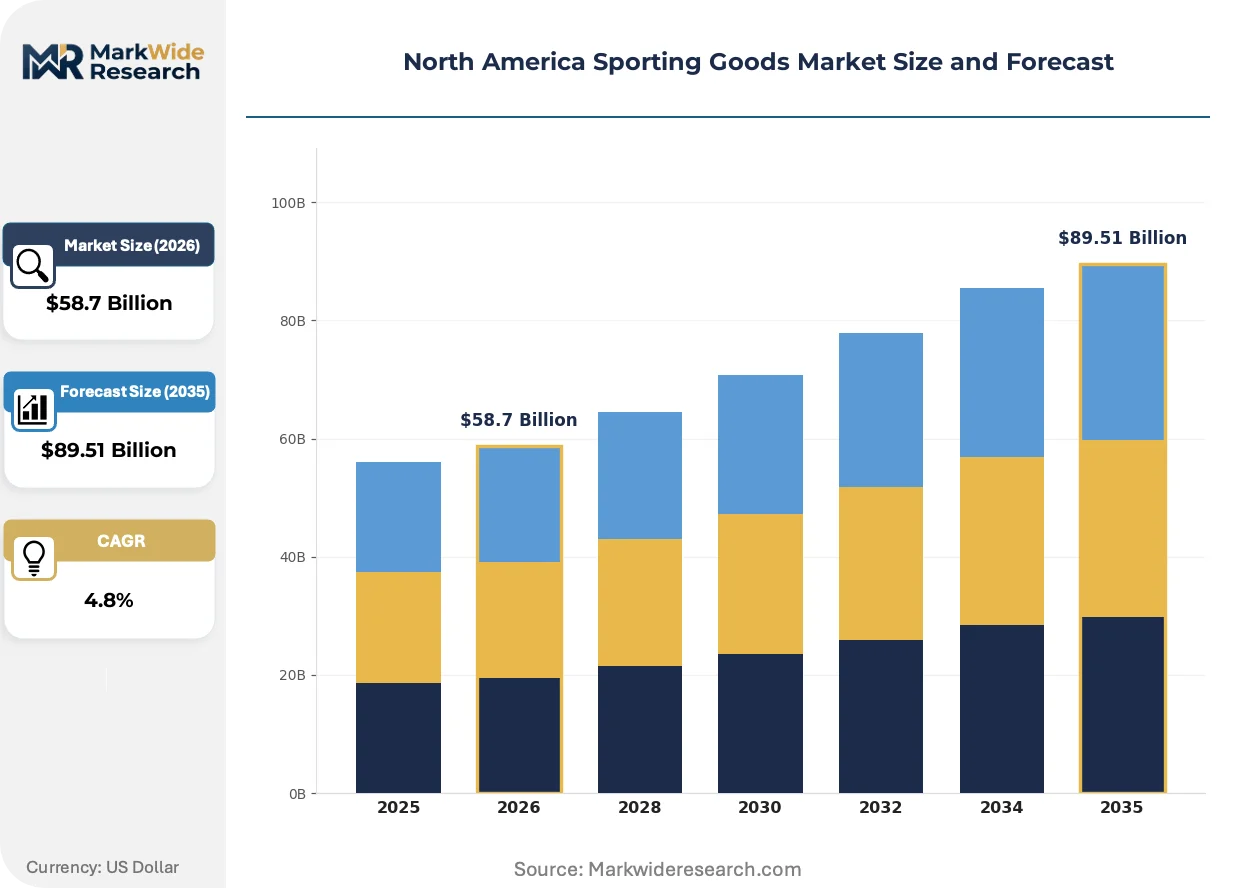
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balls, Bats, Climbing Gear, Fitness Equipment End User: Professional Athletes, Recreational Players, Schools, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Nike, Inc., Adidas AG, Under Armour, Inc., PUMA SE, Columbia Sportswear Company, lululemon athletica Inc., New Balance Athletics, Inc., Callaway Golf Company, Wilson Sporting Goods Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sporting Goods Market Evolving Landscape
Material science breakthroughs and channel restructuring are compressing traditional value chain positions while elevating technical performance expectations across price tiers.
Smart sensor integration is hybridizing conventional fitness equipment with real-time biomechanical feedback systems. Boutique studios and home gym operators are adopting these connected platforms at accelerating replacement cycles. The technology is hybridizing hardware margins with subscription revenue pools, compressing standalone equipment valuations.
The U.S. Consumer Product Safety Commission's updated equipment safety protocols mandate elevated impact testing for protective headgear and padding. Manufacturers must redesign product architectures and expand laboratory certification capacity. Youth and amateur league segments face the steepest compliance timelines and sourcing disruptions.
Subscription-based equipment access is displacing outright ownership among urban fitness consumers. Traditional sporting goods retailers are losing traffic to direct-to-consumer platforms and specialty leasing services. California's metropolitan corridors exhibit the fastest behavioral transition, with boutique studio members leading adoption curves.
North America Sporting Goods Market Segmentation
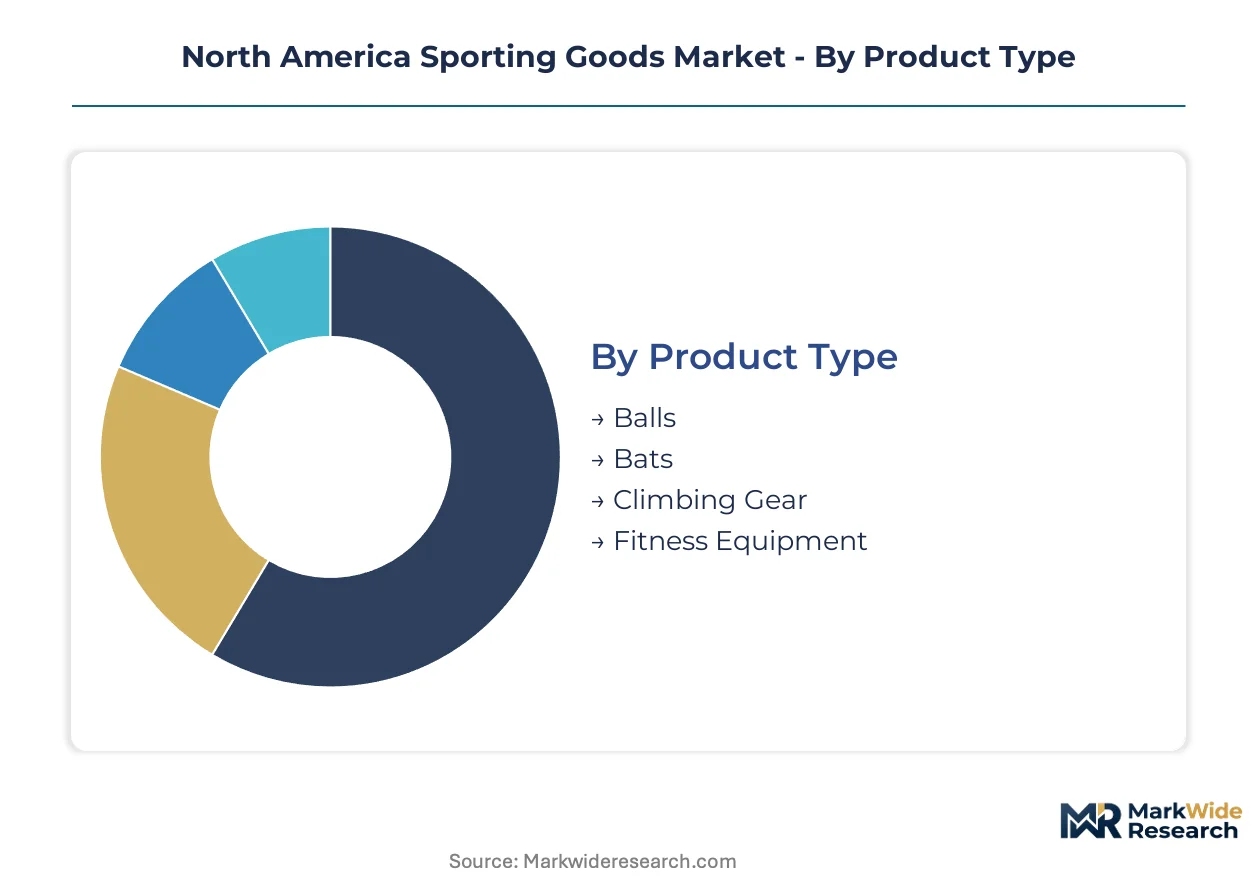
Segmentation in North American sporting goods reveals divergent margin structures across equipment categories and buyer sophistication levels. Manufacturers calibrate material specifications and channel strategies differently for institutional procurement versus individual consumers.
Product Type:
Mature equipment categories coexist with emerging technical gear as participation patterns shift toward specialized outdoor and home-based activities.
- Fitness Equipment:Residential strength and cardio systems incorporate carbon steel frames, polymer pulley housings, and Bluetooth-enabled performance tracking. California's metropolitan corridors concentrate demand intensity as boutique studio members extend professional-grade equipment into home environments, though polymer input cost volatility compresses margin stability.
- Climbing Gear:Dynamic ropes utilize kernmantle construction with polyamide sheaths and ultrahigh-molecular-weight polyethylene cores; harnesses integrate load-distribution padding and aluminum alloy buckles. Colorado and Pacific Northwest climbing communities drive technical innovation requirements, with the U.S. Consumer Product Safety Commission's updated fall-arrest testing protocols elevating certification burdens for entry-level suppliers.
- Balls:Composite leather or synthetic rubber constructions with internal bladder systems for pressure retention. School and league procurement channels sustain volume predictability through multi-year sponsorship contracts.
- Bats:Aluminum alloy or composite fiber barrels with tapered handles engineered for swing-weight optimization. Youth league participation rates in Texas and Florida metropolitan areas anchor replacement cycle timing.
Fitness Equipment retains volume leadership; Climbing Gear holds the steepest expansion curve.
End User:
Buyer sophistication stratifies sharply between performance-optimized professional requirements and durability-focused institutional procurement.
- Fitness Enthusiasts:Technical fabric knowledge and biomechanical performance expectations condition purchasing decisions toward premium price tiers. Home-based workout culture solidification post-pandemic sustains above-average replacement frequency for connected strength and cardio systems.
- Schools:Procurement committees prioritize equipment durability, multi-sport versatility, and compliance with the U.S. Consumer Product Safety Commission's youth protective gear mandates. Budget approval cycles and bond financing schedules create lumpy demand patterns.
- Professional Athletes:Custom-fitted equipment with batch-of-one manufacturing tolerances and sponsor-mandated visibility requirements. Equipment engineers with specialized repetitive stress analysis expertise remain scarce relative to product development timelines.
- Recreational Players:Price-sensitive segment with quality thresholds set by occasional-use durability expectations rather than performance optimization. Supermarket and mass-market channels capture disproportionate transaction volume.
Schools dominate institutional procurement volume; Fitness Enthusiasts command the sharpest margin expansion.
Distribution Channel:
Channel economics favor asset-light operators minimizing inventory carrying costs while maximizing customer data capture.
- Online Retail:Direct-to-consumer platforms capture margin pools traditionally ceded to wholesale partners through owned digital infrastructure. Real-time inventory visibility and subscription-based equipment access models accelerate behavioral transition among urban fitness consumers.
- Specialty Stores:Staff technical expertise and fitting services justify premium positioning for climbing gear and protective equipment. California's boutique fitness studio density concentrates foot traffic in Los Angeles and San Francisco metropolitan corridors.
- Supermarkets:High-velocity ball and bat categories with impulse-purchase placement strategies. Seasonal promotional calendars align with youth league registration periods.
- Wholesale:Institutional procurement aggregation for school district and municipal park system buyers. Multi-year contract visibility supports manufacturing capacity planning.
Online Retail gains share fastest; Wholesale maintains contract-backed stability.
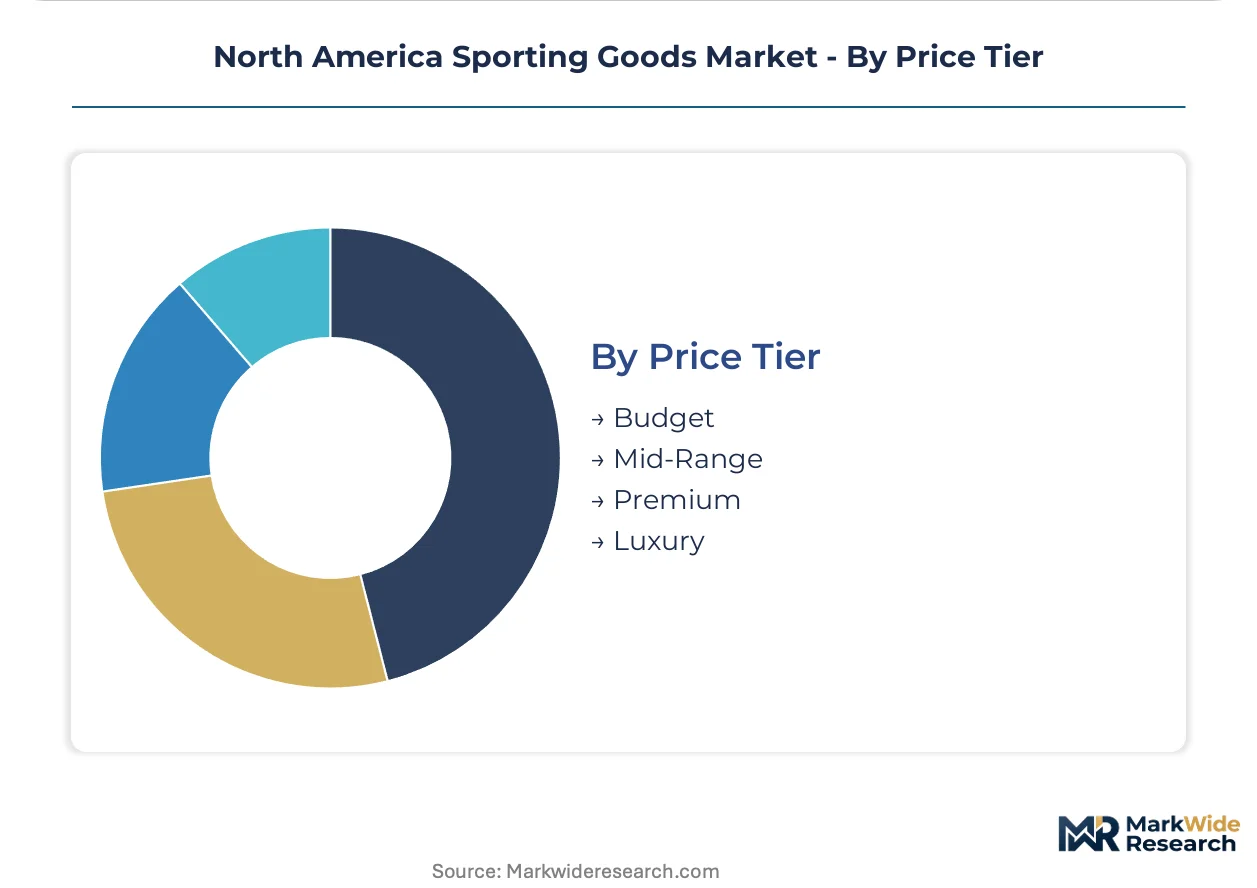
Price Tier:
Three-tier pricing structure separates technical innovation premiums from specification-standardized volume segments.
- Premium:Technical fabric innovation and biomechanical engineering justify elevated positioning through measurable performance differentiation. Lululemon athletica Inc. and comparable brands condition consumer willingness-to-pay associations.
- Mid-Range:Specification convergence across competitors compresses differentiation to brand equity and channel availability. California Proposition 65 compliance costs propagate uniformly across this tier.
- Budget:Polymer and composite fiber cost engineering prioritizes functional adequacy over durability optimization. Trans-Pacific supply disruption exposure concentrates inventory risk.
- Luxury:Limited-edition collaborations and heritage craftsmanship narratives support scarcity-based pricing. Direct-to-consumer platform exclusivity reinforces positioning.
Premium captures disproportionate margin contribution; Budget absorbs tariff volatility exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Consumer Product Safety Commission's updated equipment safety protocols and Health Canada's parallel certification requirements are reshaping manufacturing footprints across the continent. Federal and state-level incentives for domestic production are accelerating facility investments in key corridors.
United States
California's metropolitan corridors concentrate boutique fitness studio density and outdoor recreation participation that outpaces national averages. The U.S. Consumer Product Safety Commission enforces divergent testing protocols from Health Canada, compelling manufacturers to maintain dual certification pathways. Los Angeles and San Francisco anchor demand intensity for premium technical apparel and connected home fitness systems.
Canada
Health Canada mandates protective gear testing standards that frequently exceed U.S. requirements, elevating compliance burdens for cross-border suppliers. Provincial procurement programs for school athletic equipment sustain institutional volume in Ontario and Quebec. Toronto and Vancouver metropolitan areas exhibit accelerating adoption of subscription-based fitness equipment access models.
Mexico
Nearshoring incentives under the USMCA framework are attracting assembly operations for ball and bat categories serving North American distribution. Mexico's federal consumer protection agency enforces labeling standards that align with U.S. requirements, simplifying export compliance. Monterrey and Guadalajara industrial corridors concentrate manufacturing investments targeting Texas and California retail channels.
Texas
Youth league participation rates in Houston and Dallas metropolitan areas anchor replacement cycle timing for aluminum alloy bats and composite balls. State-level physical education mandates sustain institutional procurement volume across independent school districts. Austin's boutique fitness studio proliferation is driving demand for residential strength equipment with professional-grade specifications.
Colorado
Rocky Mountain climbing communities in Boulder and Denver drive technical innovation requirements for dynamic ropes and harness systems. The state's outdoor recreation economy generates above-average per-capita spending on specialized gear relative to national benchmarks. Colorado's concentration of biomechanical testing laboratories supports regional product development for fall-arrest equipment.
North America Sporting Goods Market Competitive Landscape
On the supply side, the industry is consolidating around scaled producers with dedicated certification infrastructure and fragmented among specialized regional fabricators. Tiered competitive dynamics separate premium technical innovators from specification-standardized volume players. Three strategic archetypes dominate: direct-to-consumer platform operators, institutional procurement specialists, and domestic manufacturing reshoring advocates. M&A activity targets connected fitness technology capabilities, while strategic partnerships secure alternative material sourcing for polymer-dependent categories.
Within the premium technical apparel tier, lululemon athletica Inc. and Nike, Inc. occupy positions that exemplify brand-conditioned willingness-to-pay for fabric innovation. Among domestic manufacturing advocates, New Balance Athletics, Inc. anchors supply chain resilience strategies. Wilson Sporting Goods Co. represents the institutional procurement specialist archetype, sitting within school and league sponsorship ecosystems that offer multi-year contract visibility.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Under Armour, Inc. |
| PUMA SE |
| Columbia Sportswear Company |
| lululemon athletica Inc. |
| New Balance Athletics, Inc. |
| Callaway Golf Company |
| Wilson Sporting Goods Co. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific tariff exposure determines both pricing tier spreads and supply chain shape across North American sporting goods. Manufacturers absorbing polymer feedstock volatility and dual certification costs for the U.S. Consumer Product Safety Commission and Health Canada must calibrate tier positioning against inventory risk concentration in Asian manufacturing clusters.
Pricing Analysis
Certification level creates the primary spread between premium protective gear and budget alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects divergent compliance burdens, with U.S. Consumer Product Safety Commission-grade equipment commanding sustained premiums. Cost compression in the budget tier is intensifying because petrochemical feedstock fluctuations transmit directly to polymer-dependent categories. Recreational players exhibit highest price sensitivity, while institutional procurement committees prioritize durability and compliance over unit cost.
Supply Chain Analysis
Petrochemical derivatives and advanced polymer feedstocks anchor cost structures for composite fibers and moisture-wicking textiles. Manufacturing concentrates in China, Vietnam, and Taiwan for apparel and equipment assembly, with Mexico emerging under USMCA nearshoring incentives for ball and bat categories. Single-source vulnerability concentrates in specialized polymer suppliers serving carbon steel frame and polymer pulley housing production. Distribution runs through direct-to-consumer platforms, specialty retail, and institutional wholesale channels with divergent margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated institutional procurement committees and direct-to-consumer platforms that disintermediate traditional wholesale relationships. Fragmentation among specialty retailers accelerates this consolidation.
For Market Incumbents: Pre-empt channel displacement by deepening direct-to-consumer platform infrastructure and securing multi-year institutional contracts before procurement committees consolidate vendor lists. Asset-light leasing models represent an emerging entrant archetype threatening equipment ownership economics. Certification investment in U.S. Consumer Product Safety Commission and Health Canada dual pathways preserves access to cross-border institutional volume. For New Entrants and Emerging Players: Build out subscription-based equipment access platforms targeting California metropolitan fitness enthusiasts, the most penetrable segment given boutique studio density and behavioral transition momentum. Institutional procurement channels offer white-space opportunity in school district aggregation platforms underserved by legacy vendors. Direct-to-consumer launch with real-time inventory visibility and subscription bundling captures margin pools ceded to wholesale partners. For Investors and Strategic Acquirers: Health Canada's protective gear mandate reshapes the acquisition landscape toward scaled producers with dedicated laboratory certification infrastructure. Long-term viability centers on manufacturers with backward integration into polymer compounding or captive domestic assembly capacity. The signal to monitor is state-level environmental regulation propagation beyond California, which would accelerate compliance cost divergence between national-standardized and regionally-fragmented product specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Reshoring | USMCA incentives and tariff exposure accelerate facility investments in Mexico and Texas corridors. |
| Direct-to-Consumer Platform Expansion | Nike's owned digital infrastructure captures margin pools traditionally ceded to wholesale partners. |
| Smart Sensor Integration | Biomechanical feedback systems hybridize hardware margins with recurring subscription revenue pools. |
| Dual Certification Infrastructure | U.S. Consumer Product Safety Commission and Health Canada compliance creates barrier to entry for scaled producers. |
| Asset-Light Leasing Models | Peloton and comparable platforms minimize consumer capital deployment while generating predictable recurring streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, U.S. Consumer Product Safety Commission enforcement databases, and Health Canada product safety filings. Primary interviews engaged brand managers at technical apparel manufacturers, category buyers at sporting goods retailers, supply planners at polymer compounders, and procurement directors at school district athletic departments. Secondary validation drew from Nielsen retail audit data, SEC 10-K filings of publicly traded competitors, and USMCA trade flow statistics. Bottom-up SKU-level demand modeling and top-down macroeconomic scaling were cross-referenced for triangulation.
Forecast inputs include fitness equipment replacement cycle timing, youth league participation rates, and boutique studio membership density across metropolitan corridors. Segmentation dimensions encompass product type, end user sophistication, distribution channel economics, and price tier positioning. CAGRs were derived from regression analysis against historical volume trajectories and projected participation pattern shifts. Polymer feedstock price indices and trans-Pacific shipping rate volatility were incorporated as sensitivity variables.
Stress conditions across tariff rate escalation, dual certification timeline compression, and petrochemical price spikes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding post-pandemic home-based workout culture persistence and state regulatory propagation patterns. Cross-checking against IHS Markit consumer expenditure benchmarks and U.S. Census Bureau retail trade data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Boxing Gear Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Golf Bags Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Fishing Rods Market