
 Global Pharmacokinetics Services Market | 2026-2036
Global Pharmacokinetics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacokinetics Services Market Foresight
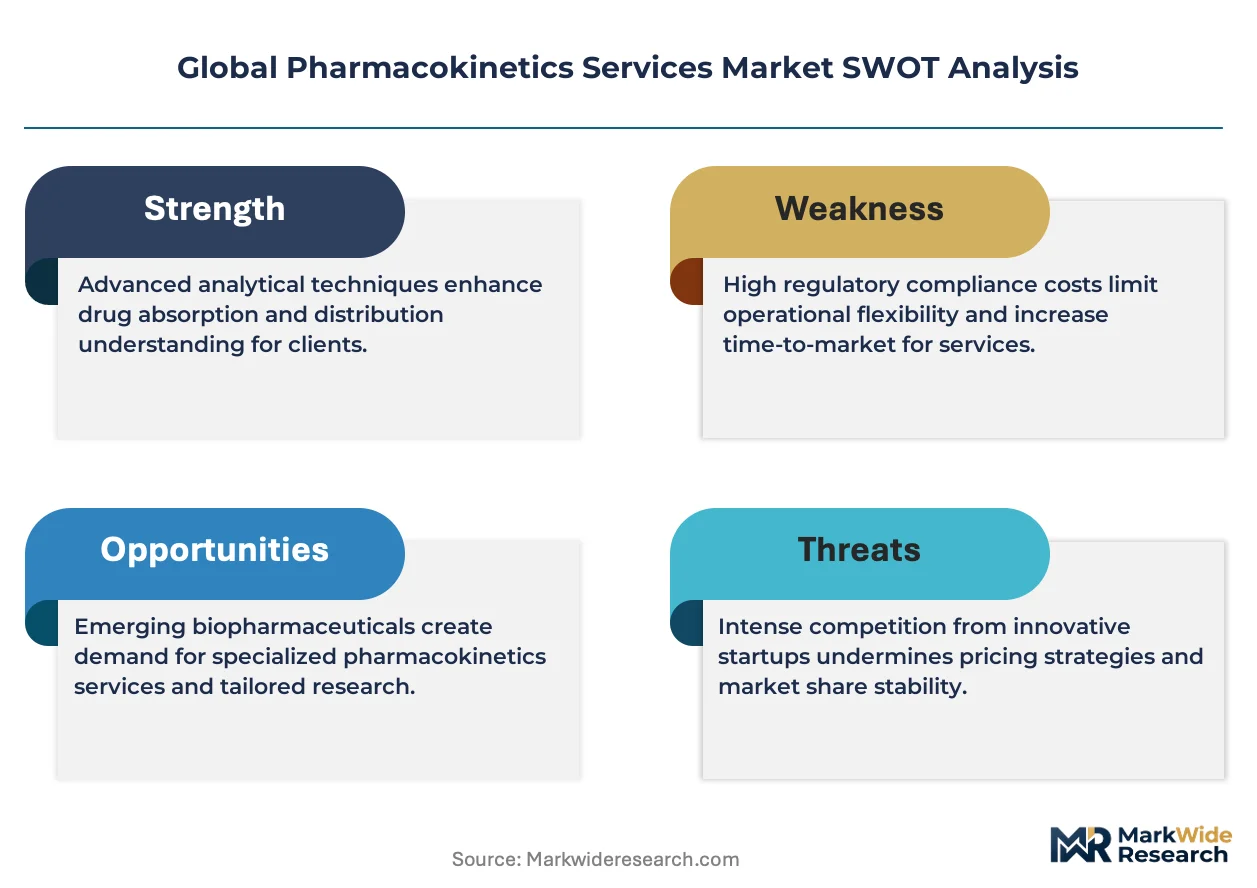
The FDA's enhanced bioequivalence guidelines for complex generics is realigning the cost-of-entry calculus for pharmacokinetics service providers, forcing investments in higher-resolution mass spectrometry and validated bioanalytical methods. Charles River Laboratories International, Inc. leverages its integrated discovery-to-safety platform to anchor large-molecule PK programs across North America and Europe. Eurofins Scientific SE sustains competitive density through a decentralized laboratory network that controls regional turnaround times for bioavailability studies. WuXi AppTec dominates Asia-Pacific PK outsourcing by operating GLP-certified facilities in China that specialize in NCE toxicokinetics.
Pharmacokinetics services encompass the quantitative analysis of drug absorption, distribution, metabolism, and excretion (ADME) in biological systems, typically requiring liquid chromatography-tandem mass spectrometry (LC-MS/MS) detection limits below 1 ng/mL to characterize parent compounds and metabolites in plasma matrices. These services enable dose optimization, bioequivalence demonstration, and regulatory safety margins for new molecular entities across the pharmaceutical development pipeline. ADME studies command the largest revenue share within service type segmentation due to their mandatory placement in IND-enabling packages, while toxicokinetics generates the fastest growth as oncology biologics demand expanded safety pharmacology support. Contract research organizations capture the dominant end-user channel position because mid-cap biotech firms lack in-house bioanalytical infrastructure and prefer variable cost structures for Phase I trial support.
The FDA's Bioanalytical Method Validation guidance and EMA's ICH M3(R2) nonclinical safety standards collectively shape study design parameters, sample throughput requirements, and documentation rigor that PK vendors must satisfy for regulatory submission acceptance. China's NMPA implementation of ICH-aligned pharmacokinetic study guidelines is accelerating local laboratory certification upgrades and cross-border data acceptance protocols. Japan's PMDA maintains distinct bridging study expectations for ethnic pharmacokinetic comparisons that sustain specialized regional service demand. Stakeholders must monitor evolving biosimilar interchangeability standards in major jurisdictions, as these determinations will restructure the volume and complexity of comparative pharmacokinetics engagements required for abbreviated approval pathways.
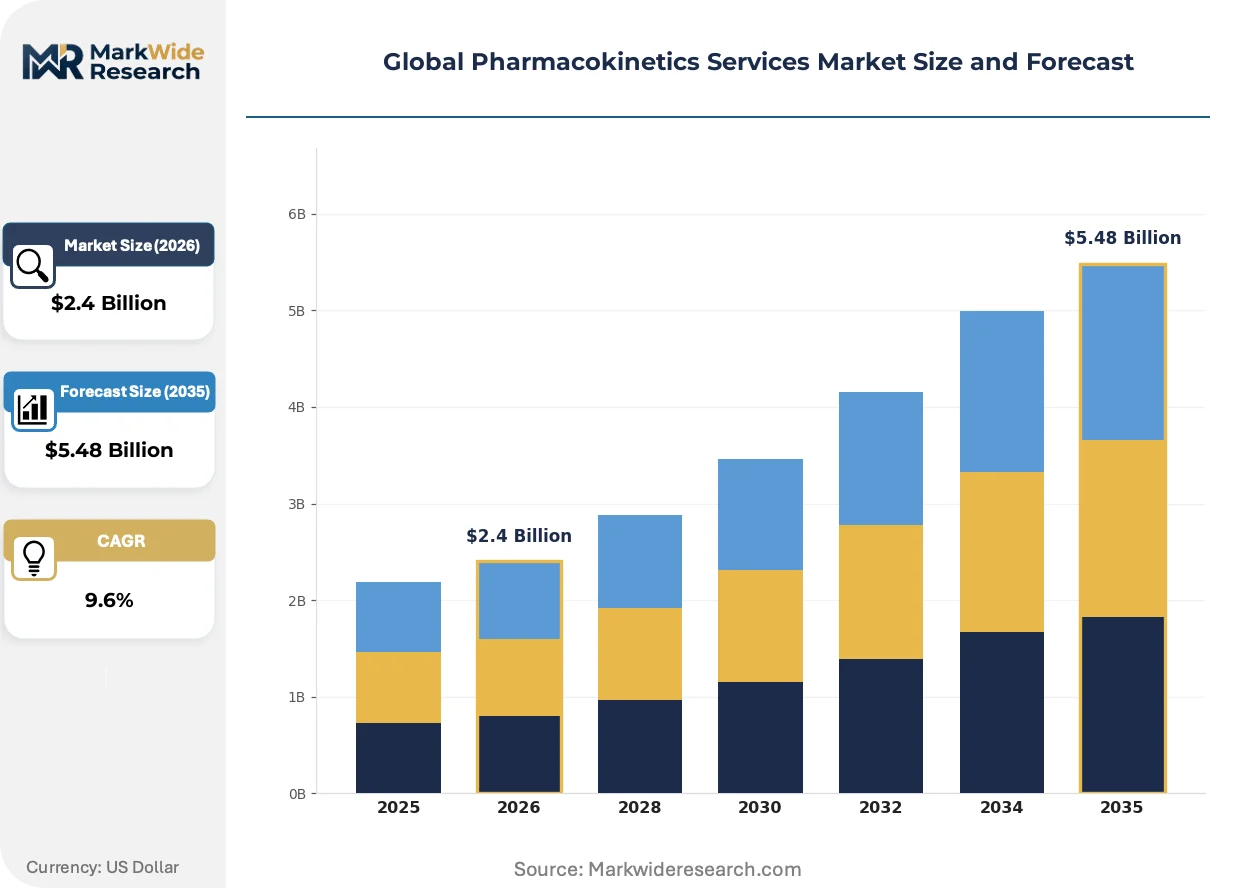
Market Dynamics
Contract research organizations face intensifying pressure from the FDA's enhanced bioequivalence guidelines for complex generics, which mandate higher-resolution mass spectrometry and validated bioanalytical methods that reshape capital allocation across the service tier.
Growth Catalysts
- FDA Bioanalytical Method Validation guidance:The FDA's stringent sample throughput requirements and documentation rigor compel pharmacokinetics vendors to upgrade LC-MS/MS infrastructure, expanding addressable service revenue from biopharmaceutical sponsors.
- Oncology biologics pipeline expansion:Toxicokinetics demand accelerates as large-molecule development programs require expanded safety pharmacology support, particularly for antibody-drug conjugates and cell therapies entering IND-enabling phases.
- Mid-cap biotech outsourcing preference:Variable cost structures for Phase I trial support displace fixed bioanalytical infrastructure investments, channeling demand toward specialized contract research organizations with GLP-certified capacity.
Market Restraints
- High-resolution mass spectrometer capital intensity:Orbitrap and Q-TOF platforms require $800,000-$1.2 million per unit, compressing margins for regional laboratories without sufficient sample volume to amortize equipment costs.
- Specialized analytical chemist scarcity:The shallow talent pool for LC-MS/MS method development and GLP-compliant validation constrains laboratory expansion velocity in secondary markets.
- Japan PMDA bridging study requirements:Ethnic pharmacokinetic comparison mandates sustain fragmented regional service demand, preventing scale economies for pan-Asian study execution.
Strategic Opportunities
- China NMPA ICH alignment:The NMPA's adoption of ICH M3(R2) nonclinical safety standards accelerates local laboratory certification upgrades and cross-border data acceptance, opening captive domestic biopharma demand to international vendors.
- Biosimilar interchangeability determinations:Evolving standards in the United States and European Union restructure comparative pharmacokinetics engagement volume, creating specialized analytical service niches for abbreviated approval pathways.
- Microsampling and dried blood spot convergence:Integration of volumetric absorptive microsampling with automated sample processing reduces clinical site burden and expands pediatric and geriatric trial accessibility.
Industry Challenges
- GLP certification timeline compression:Regulatory audit preparation and facility qualification for OECD-compliant toxicokinetics studies demand 18-24 month lead times, misaligning with sponsor accelerated development schedules.
- Legacy bioanalytical method transfer complexity:Migrating validated assays between sponsor laboratories and contract research organizations generates protocol deviation risks and sample reanalysis costs.
- Biologics immunogenicity assay integration:Anti-drug antibody testing alongside pharmacokinetic analysis requires specialized ligand-binding capacity that few integrated platforms have scaled efficiently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacokinetics Services Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: ADME Studies, Bioavailability Studies, Drug Metabolism, Toxicokinetics, Pharmacodynamics, Others Therapy Area: Oncology, Neurology, Immunology, Endocrinology, Infectious Diseases, Cardiovascular Application: Drug Discovery, Clinical Trials, Preclinical Studies, Regulatory Submissions, Personalized Medication, Safety Assessment End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions, Government Agencies, Research Centers |
| Companies Covered | Charles River Laboratories International, Inc., IQVIA Holdings, Inc., Eurofins Scientific SE, Certara, L.P., Evotec AG, WuXi AppTec, Parexel International Corporation, Shanghai Medicilon Inc., GVK Biosciences Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacokinetics Services Market Shifts & Advancements
High-resolution mass spectrometry platforms and automated sample handling systems are compressing analytical turnaround timelines while elevating detection sensitivity thresholds. These capabilities reshape competitive differentiation across the pharmacokinetics service tier.
High-resolution mass spectrometry is electrifying method development workflows for complex biologics. Biopharmaceutical sponsors with large-molecule pipelines adopt Orbitrap and Q-TOF platforms at accelerating velocity to characterize post-translational modifications and metabolite identification. This capability compression enables contract research organizations to displace sponsor in-house bioanalytical groups for NCE toxicokinetics programs.
EMA ICH M3(R2) nonclinical safety standards tighten study design parameters and documentation rigor for regulatory submission acceptance across European development programs. The industrial consequence elevates sample throughput requirements and forces harmonization of data management systems with OECD GLP principles. Oncology biologics developers targeting EMA centralized procedures invest most heavily in compliant bioanalytical infrastructure.
Mid-cap biotech procurement teams consolidate vendor relationships around integrated discovery-to-safety platforms rather than fragmented specialty shops. This concentration displaces single-service regional laboratories and rewards contract research organizations with captive toxicology and bioanalytical capacity. The United States exhibits this pattern most visibly, where Boston and San Francisco corridor sponsors prioritize vendor risk reduction over unit cost minimization.
Global Pharmacokinetics Services Market Segmentation
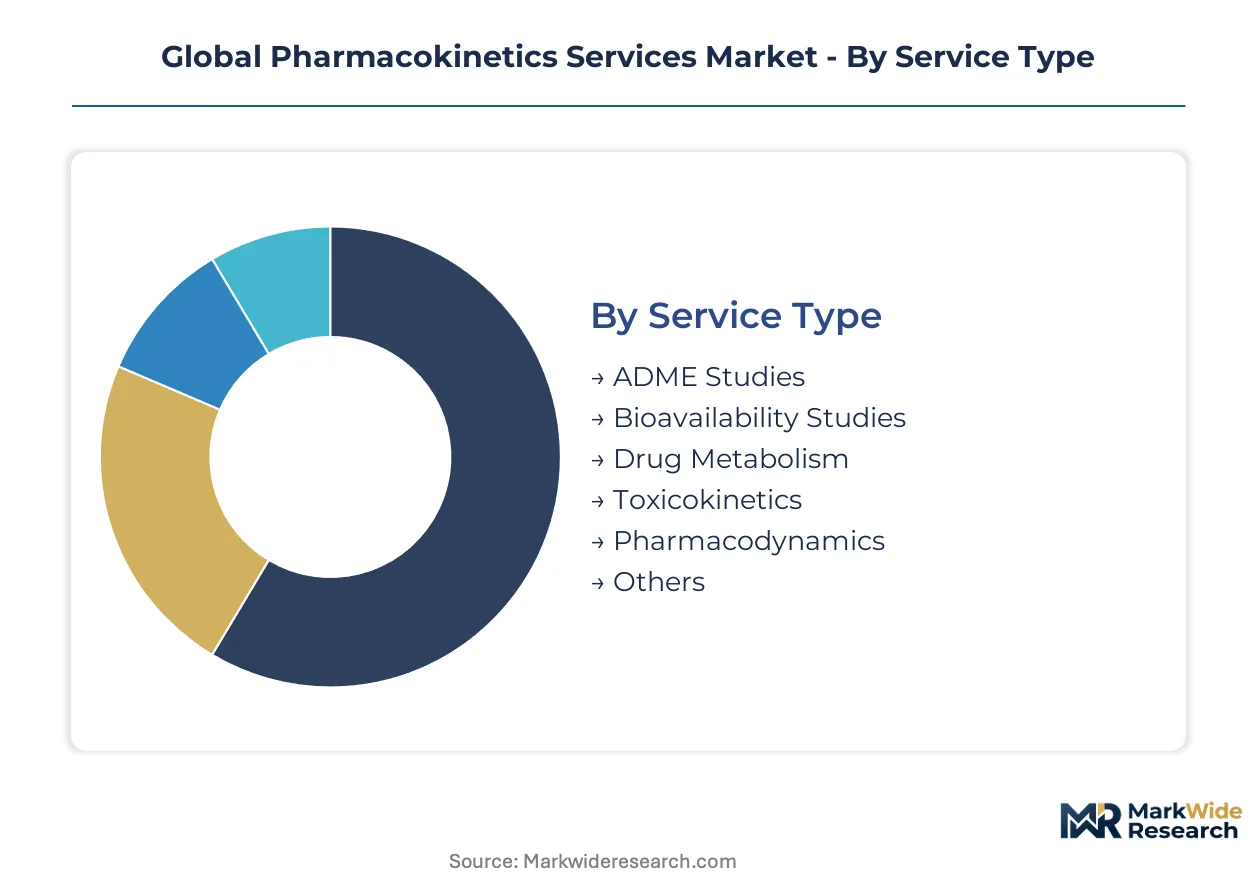
Segmentation in pharmacokinetics services reveals how capital allocation, regulatory exposure, and therapeutic complexity concentrate value capture across distinct service tiers. Understanding these divisions illuminates where specialized capabilities command premium positioning.
Service Type:
Capital intensity varies sharply across service types, with mass spectrometry infrastructure requirements and GLP certification timelines determining barrier heights.
- ADME Studies:These investigations quantify absorption, distribution, metabolism, and excretion profiles using LC-MS/MS platforms with sub-nanogram detection thresholds. Pharmaceutical sponsors in the United States concentrate demand here for IND-enabling packages. ADME studies absorb the bulk of installed capacity; toxicokinetics is expanding most quickly.
- Toxicokinetics:Safety pharmacology support for oncology biologics requires expanded exposure assessments and specialized bioanalytical validation. Boston corridor sponsors drive volume for antibody-drug conjugate programs.
- Bioavailability Studies:Comparative pharmacokinetic analysis for generic drug approvals demands validated methods under FDA bioequivalence guidelines.
- Drug Metabolism:Metabolite identification and reaction phenotyping services support dose optimization and drug-drug interaction predictions.
- Pharmacodynamics:Biomarker integration with PK measurements enables mechanistic understanding of drug action.
- Others:Specialized services including PBPK modeling and special population studies.
Service type selection correlates directly with development phase risk tolerance and regulatory submission complexity.
Therapy Area:
Oncology commands the steepest analytical requirements, with large-molecule complexity and immunogenicity concerns reshaping capability investments.
- Oncology:Antibody-drug conjugates and cell therapies demand expanded safety pharmacology support with specialized ligand-binding assays. United States biotech clusters generate the densest sponsor demand.
- Neurology:Blood-brain barrier penetration studies and cerebrospinal fluid sampling protocols require specialized method development expertise.
- Immunology:Biologics development programs concentrate demand for immunogenicity assessment alongside pharmacokinetic characterization.
- Endocrinology:Hormone therapeutic equivalents require sensitive bioanalytical methods for bioequivalence demonstrations.
- Infectious Diseases:Antiviral and antimicrobial PK studies support dose optimization for narrow therapeutic indices.
- Cardiovascular:Established small-molecule programs sustain steady demand for validated bioanalytical methods.
Oncology and immunology together concentrate the fastest capability expansion; cardiovascular maintains the most mature service infrastructure.
Application:
Development phase positioning determines sample throughput requirements and documentation rigor expectations.
- Drug Discovery:High-throughput screening support and early ADME characterization enable lead optimization decisions. San Francisco corridor sponsors prioritize speed over GLP compliance.
- Clinical Trials:Phase I bioanalytical support demands rapid turnaround and validated methods for dose escalation decisions.
- Preclinical Studies:GLP-compliant toxicokinetics for IND-enabling safety packages requires OECD-aligned facility certification.
- Regulatory Submissions:Method validation documentation and bioequivalence study reports satisfy FDA and EMA review standards.
- Personalized Medication:Therapeutic drug monitoring and pharmacogenomic integration support precision dosing protocols.
- Safety Assessment:Integrated toxicokinetics and safety pharmacology evaluations for biologics development programs.
Clinical trials and preclinical studies together anchor the revenue base; personalized medication shows the steepest expansion trajectory.
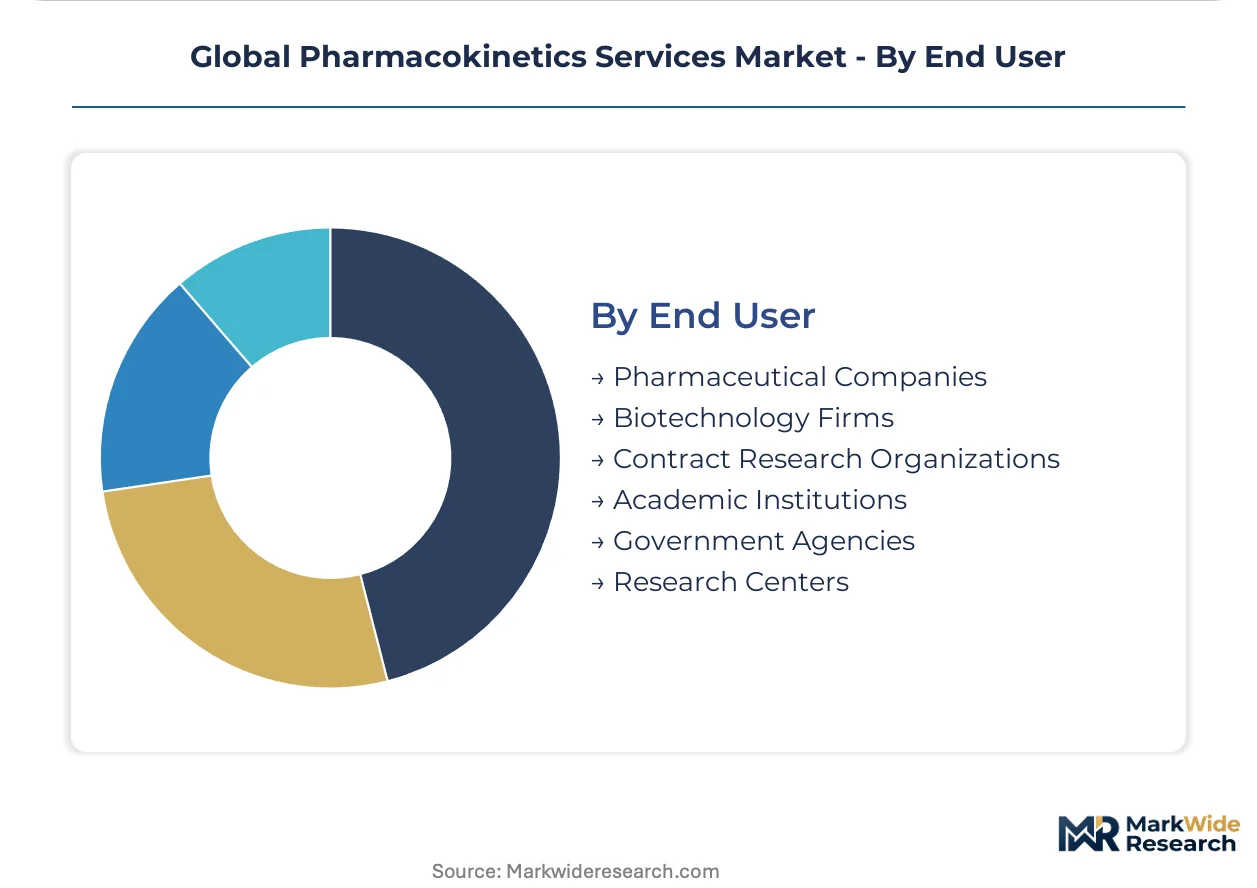
End User:
Organizational scale and in-house capability determine outsourcing depth and vendor relationship structures.
- Pharmaceutical Companies:Large sponsors maintain selective outsourcing for specialized bioanalytical capabilities while retaining strategic functions in-house. Pfizer and Merck operations in the United States exemplify hybrid models.
- Biotechnology Firms:Mid-cap developers lack fixed infrastructure and prefer variable cost structures for Phase I support.
- Contract Research Organizations:Tier-one CROs subcontract specialized PK services to niche laboratories with platform-specific expertise.
- Academic Institutions:Research programs generate method development collaborations and training pipeline contributions.
- Government Agencies:Regulatory science initiatives and reference standard development sustain specialized service demand.
- Research Centers:Non-profit institutes require bioanalytical support for investigator-initiated trials.
Pharmaceutical companies and biotechnology firms together dominate procurement volume; contract research organizations represent the fastest-growing customer channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacokinetics services concentrate where Phase I clinical trial infrastructure and specialized CRO capacity overlap. The United States absorbs the largest absolute demand due to its concentration of biotech clusters and FDA-regulated development programs.
United States
Boston and San Francisco corridor sponsors drive dense demand for antibody-drug conjugate PK programs. FDA bioanalytical method validation guidance shapes laboratory infrastructure investments across Massachusetts and California. Charles River Laboratories anchors integrated discovery-to-safety platforms serving large-molecule developers in these clusters.
China
Domestic biopharma expansion and NCE toxicokinetics outsourcing sustain facility utilization in Shanghai and Suzhou. NMPA implementation of ICH-aligned pharmacokinetic study guidelines accelerates GLP certification upgrades. WuXi AppTec operates certified capacity that captures cross-border data acceptance protocols for international sponsors.
Germany
EMA centralized procedure submissions from European oncology developers concentrate bioanalytical demand in Baden-Württemberg and Bavaria. ICH M3(R2) nonclinical safety standards enforce OECD GLP harmonization requirements. Eurofins Scientific SE maintains decentralized laboratory networks controlling regional turnaround times for bioavailability studies.
Japan
PMDA bridging study expectations for ethnic pharmacokinetic comparisons sustain specialized regional service demand. Tokyo and Osaka clusters require distinct analytical capacity for comparative pharmacokinetics engagements. Local laboratories capture mandatory domestic trial execution that prevents full pan-Asian study consolidation.
India
Cost-sensitive bioanalytical method development and generic drug bioequivalence studies concentrate in Hyderabad and Bangalore. CDSCO alignment with ICH guidelines expands export-oriented laboratory certification. GVK Biosciences and regional CROs serve international sponsors seeking variable cost structures for Phase I support.
Global Pharmacokinetics Services Market Competitive Landscape
United States producers anchor the premium-tier integrated platform segment; European specialists hold method validation and regulatory submission capabilities. The vendor structure stratifies across three tiers: global full-service CROs with captive toxicology capacity, regional laboratories with platform-specific expertise, and niche method development shops serving discovery-phase sponsors. Consolidation pressure intensifies as mid-cap biotech procurement teams consolidate vendor relationships around risk reduction rather than unit cost minimization.
Within the integrated platform tier, Charles River Laboratories International, Inc., IQVIA Holdings, Inc., and Eurofins Scientific SE exemplify archetypes that span discovery through regulatory submission. These entities occupy positions where GLP-certified toxicokinetics and bioanalytical capacity converge, representing the structural direction of sponsor procurement consolidation. Regional specialists in China and India sit within cost-optimized tiers serving generic bioequivalence and early-phase method development demand.
| Leading Market Players |
|---|
| Charles River Laboratories International, Inc. |
| IQVIA Holdings, Inc. |
| Eurofins Scientific SE |
| Certara, L.P. |
| Evotec AG |
| WuXi AppTec |
| Parexel International Corporation |
| Shanghai Medicilon Inc. |
| GVK Biosciences Private Limited |
| Others |
Supply & Pricing Matrix
High-resolution mass spectrometry platform adoption simultaneously compresses per-sample analytical costs and concentrates supply capability among laboratories with Orbitrap and Q-TOF infrastructure investments. This dual effect reshapes pricing power toward GLP-certified facilities in the United States, Germany, and China while marginalizing regional players lacking sufficient sample volume to amortize equipment costs.
Pricing Analysis
Volume concentration against margin compression defines the pricing structure, with large-molecule toxicokinetics commanding premium rates while generic bioequivalence studies face downward pressure from Indian and Chinese laboratory competition. Price differentiation hinges on GLP certification tier and therapeutic complexity, with oncology biologics developers showing lowest price sensitivity due to regulatory risk aversion. Mid-cap biotech firms exhibit highest price sensitivity, prioritizing variable cost structures over analytical sophistication. Cost compression in standard bioanalytical services is intensifying because automated sample handling systems reduce labor intensity and enable throughput scaling.
Supply Chain Analysis
GLP certification and OECD facility qualification function as supply chain gating mechanisms that restrict viable vendor pools and extend procurement timelines. Equipment manufacturing concentrates in the United States, Germany, and Japan, with Thermo Fisher Scientific and SCIEX anchoring mass spectrometer production. Reagent supply draws from specialized chemical producers in Switzerland and the United States, with isotopically labeled internal standards representing critical dependencies. Single-source vulnerability persists for high-resolution detector components sourced from precision electronics manufacturers in Japan. Distribution runs through direct manufacturer relationships for major platforms and regional distributors for consumables and reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmacokinetics services market is becoming a vertical-integration race as sponsors consolidate vendor relationships around integrated discovery-to-safety platforms rather than fragmented specialty shops. Captive toxicology capacity and GLP-certified bioanalytical infrastructure represent the decisive upstream levers that determine competitive positioning.
For Market Incumbents: Deepen integration between toxicokinetics and safety pharmacology capabilities to anchor large-molecule oncology programs against emerging platform competitors. Expand GLP-certified capacity in the Boston and San Francisco corridors where sponsor concentration sustains premium pricing. Charles River Laboratories and IQVIA exemplify the integrated model that procurement teams increasingly favor for vendor risk reduction. For New Entrants and Emerging Players: Capture white-space opportunity in microsampling and dried blood spot automation, where pediatric and geriatric trial accessibility creates underserved demand. The Asia-Pacific region outside China offers the most penetrable geography given NMPA certification barriers that protect domestic incumbents. A go-to-market angle emphasizing rapid turnaround for Phase I dose-escalation decisions can displace slower established laboratories. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap CROs possessing GLP certification gaps but strong method development talent pools, given FDA bioequivalence guideline enforcement as catalyst for mandatory infrastructure investment. Long-term viability favors platforms with captive toxicology capacity spanning IND-enabling through regulatory submission phases. The signal to watch is biosimilar interchangeability determinations in the United States and European Union, which would restructure comparative pharmacokinetics engagement volume and favor scaled analytical providers.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Certification Expansion | OECD-compliant facility qualification opens IND-enabling toxicokinetics revenue from FDA-regulated sponsors. |
| High-Resolution Mass Spectrometry Deployment | Orbitrap and Q-TOF platforms enable complex biologics method development that displaces sponsor in-house capacity. |
| Microsampling Technology Integration | Volumetric absorptive microsampling reduces clinical site burden and expands pediatric trial accessibility for CROs. |
| Cross-Border Data Acceptance Protocols | NMPA ICH alignment enables international sponsors to leverage China-based GLP-certified capacity. |
| Integrated Discovery-to-Safety Platform Buildout | Captive toxicology and bioanalytical convergence anchors consolidated vendor relationships from mid-cap biotech procurement teams. |
Research Methodology
FDA guidance documents, EMA regulatory submissions, and ClinicalTrials.gov registration data formed the secondary backbone for service demand quantification and regulatory requirement mapping. Primary interviews with drug development executives, regulatory affairs leads at sponsor organizations, CRO procurement managers, and bioanalytical laboratory directors validated secondary findings and informed capability investment patterns. Bottom-up triangulation across service type, therapy area, and end-user segmentation combined with top-down cross-checks against industry revenue estimates.
Historical trendline analysis of ADME study volume, toxicokinetics outsourcing rates, and CRO market penetration established baseline growth parameters across the projection horizon. The analytical framework modeled segmentation dimensions including service type, therapeutic complexity, development phase positioning, and regional regulatory cluster. CAGRs were derived from regression analysis of sponsor pipeline expansion, regulatory submission volume, and laboratory capacity addition patterns. Forecast inputs incorporated oncology biologics pipeline density, FDA bioequivalence guideline implementation timelines, and NMPA ICH alignment progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosimilar interchangeability standard evolution and mass spectrometer technology substitution cycles. Forecasts reflect documented assumptions regarding sponsor outsourcing preference stability and regulatory harmonization trajectories. A model refresh is warranted upon material change in FDA bioanalytical method validation guidance or NMPA cross-border data acceptance protocol implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aspirin API Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Cough Remedies Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Apixaban Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Ibuprofen API Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
UK Pharmacovigilance Market