
 Corn Oil Market | 2026-2036
Corn Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Oil Market Intelligence
EPA Renewable Fuel Standard obligations is repositioning corn oil economics for fuel producers. Cargill, Incorporated leverages its integrated ethanol-to-oil infrastructure across the US corn belt. Archer Daniels Midland Company sustains one of the largest merchant corn oil positions through wet milling dominance. Bunge Limited anchors South American supply chains with crushing assets in Argentina and Brazil.
Corn oil is a refined triglyceride oil extracted from corn germ, typically containing 13% saturated fatty acids and a smoke point near 450°F for refined grades, serving as a cooking medium, biodiesel feedstock, and industrial lubricant base. Refined corn oil occupies the largest volume share due to its neutral flavor profile and extended fry-life in foodservice operations. Organic corn oil commands premium positioning as clean-label formulations displace conventional alternatives in North American and European retail channels.
FDA food-contact substance notifications govern corn oil purity thresholds for packaged food applications, while EPA renewable fuel regulations determine biodiesel eligibility and credit generation. USDA biofuel program guidelines and ISO 22000 food safety management standards further shape processor compliance burdens and customer qualification requirements. Stakeholders must monitor RFS mandate litigation and state-level low-carbon fuel standards as these will determine whether fuel-grade offtake premiums persist or revert toward food-service parity.
Market Dynamics
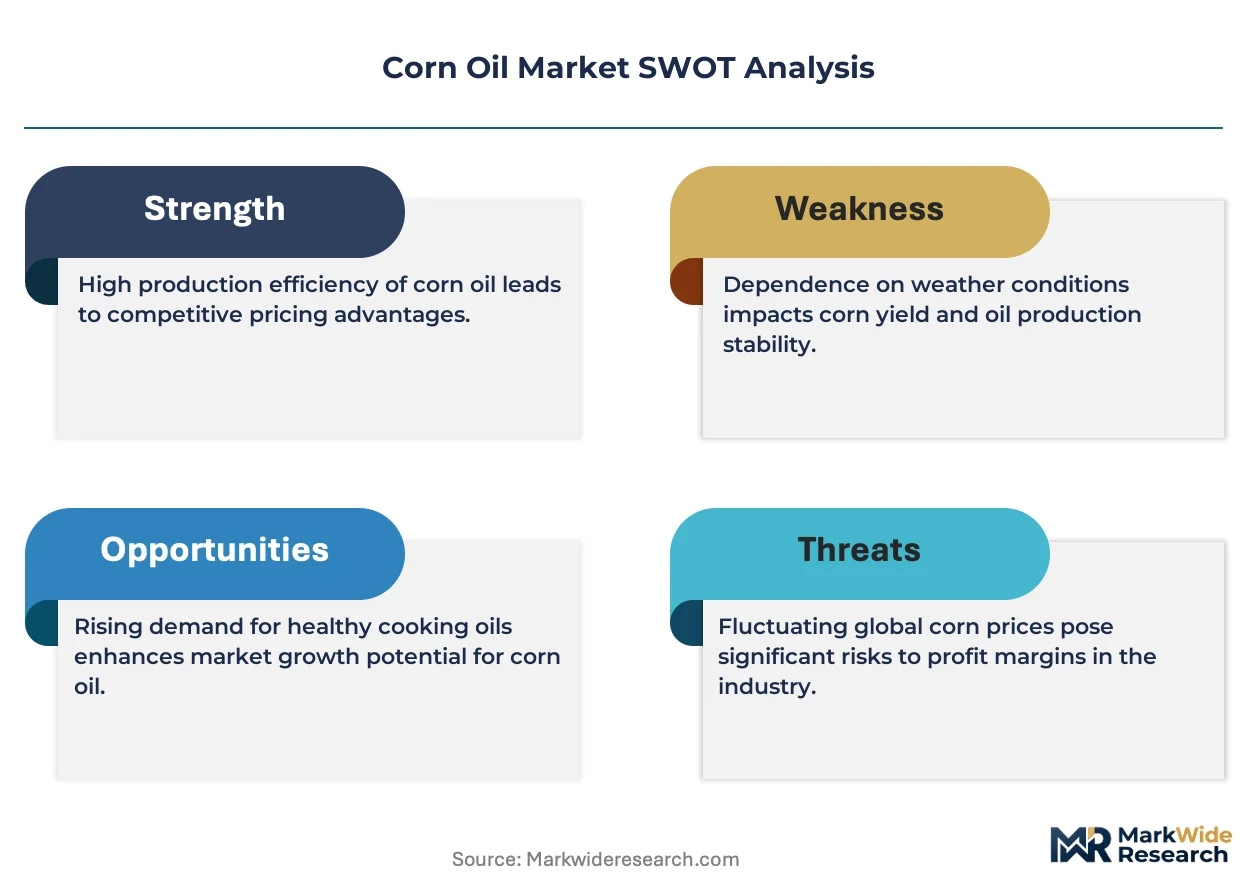
EPA Renewable Fuel Standard obligations are restructuring corn oil economics by diverting co-product streams from foodservice channels toward biodiesel refiners competing for limited supply.
Growth Catalysts
- Renewable Fuel Standard mandates:EPA compliance obligations force fuel producers to secure qualified feedstocks, creating guaranteed offtake for distillers corn oil.
- Cold-press extraction advancement:Mechanical pressing technologies reduce hexane residues below FDA food-contact thresholds, opening premium food-grade applications.
- Ethanol plant clustering:Iowa and Illinois concentrate 60% of US ethanol capacity, anchoring corn oil supply within 200-mile crush-to-refinery corridors.
Market Restraints
- Crude oil price volatility:Biodiesel economics depend on petroleum diesel spreads; sustained crude weakness collapses fuel-grade premiums toward food-service parity.
- Single-crop dependency:Corn germ supply ties exclusively to ethanol and wet-milling runs, creating volume ceilings unrelated to oil demand.
- Soybean oil substitution:Soy oil's larger global surplus and established biodiesel qualification under RFS rules constrain corn oil pricing power.
Strategic Opportunities
- Clean-label retail expansion:Organic corn oil commands shelf-space premiums in North American natural-product channels as conventional oils face ingredient-list scrutiny.
- Low-carbon fuel standards:California LCFS and Oregon CFP credit corn oil with lower carbon intensity scores than soy, attracting West Coast biodiesel investment.
- Industrial lubricant formulations:Biobased hydraulic fluids and metalworking coolants represent unpenetrated demand outside food and fuel verticals.
Industry Challenges
- Fractionation expertise scarcity:Wet-milling operators with germ-separation proficiency face recruitment competition from pharmaceutical and biotechnology sectors.
- RFS litigation uncertainty:Pending court challenges to EPA mandate volumes create investment paralysis in dedicated fuel-grade refining capacity.
- ISO 22000 certification timelines:Food safety management audits require 12-18 month implementation cycles, delaying new processor market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Oil Market |
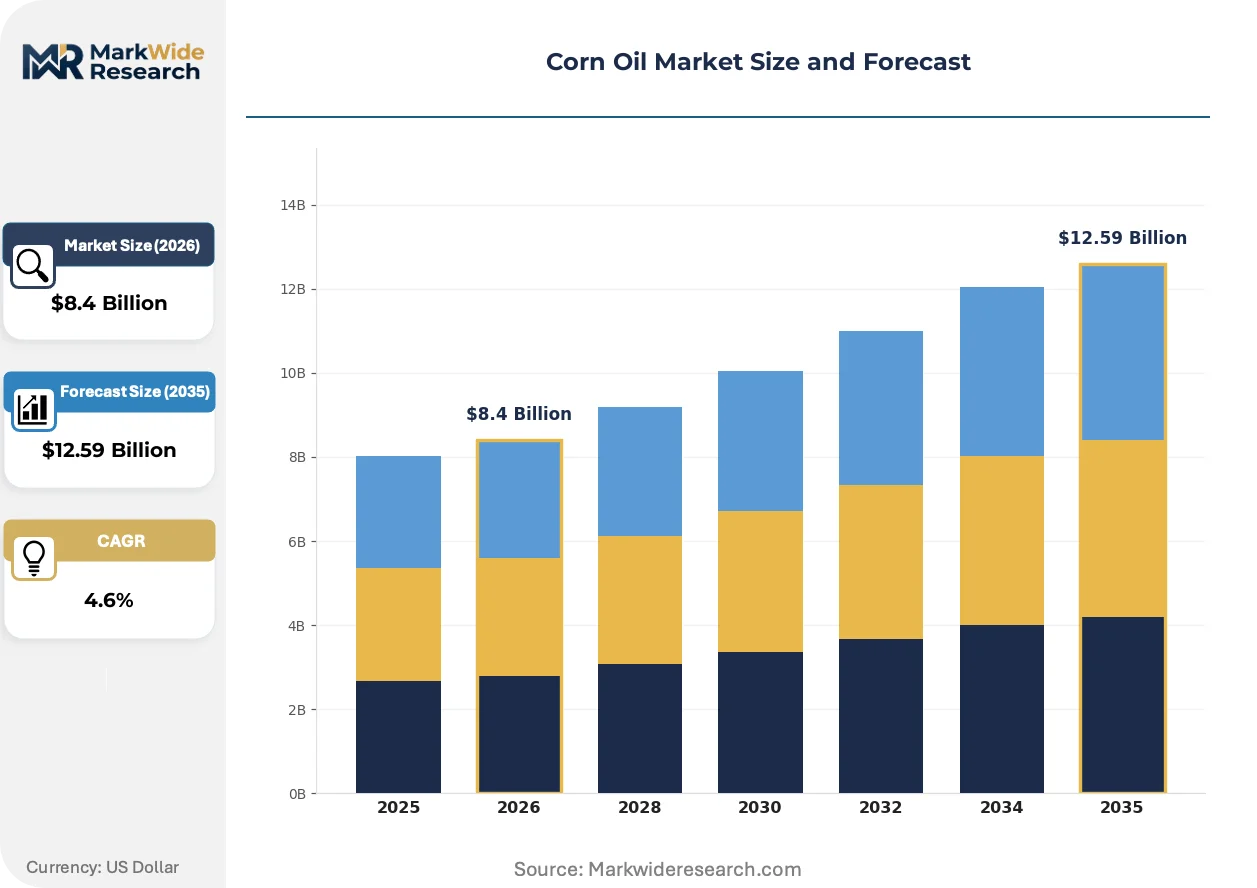
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Corn Oil, Crude Corn Oil, Pomace Oil, Organic Corn Oil Industry Vertical: Food & Beverage, Cosmetics, Pharmaceuticals, Biofuel Application: Cooking, Baking, Frying, Emulsifying Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Wilmar International Limited, Ingredion Incorporated, Cargill, Incorporated, Abu Dhabi Vegetable Oil Company LLC, Savola Group, Archer Daniels Midland Company, Conagra Brands, Inc., Associated British Foods plc, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Oil Market Strategic Shifts & Innovations
Corn oil processing is experiencing simultaneous pressure from fuel-policy restructuring and food-industry clean-label demands, forcing technology choices that bifurcate supply chains.
Expeller-pressed extraction is rewriting grade specifications across the industry. Mechanical pressing eliminates hexane solvent residues entirely, satisfying FDA food-contact substance notifications for infant formula and pharmaceutical applications. Premium food manufacturers in the Northeast and Pacific Northwest specify expeller-pressed certificates of analysis, compressing margins for conventional solvent-extracted grades.
California's Low Carbon Fuel Standard and Oregon's Clean Fuels Program are tightening carbon intensity benchmarks for biodiesel feedstocks. These state-level frameworks award higher credit values to corn oil relative to soy oil based on lifecycle emissions modeling. Fuel producers are responding by redirecting procurement teams toward Midwest ethanol plants with verified carbon accounting.
Direct-procurement contracts between biodiesel refiners and ethanol plant operators are displacing merchant spot markets. Large renewable diesel facilities in Louisiana and Texas now negotiate multi-year offtake agreements with Iowa and Illinois ethanol producers, locking in volume before germ extraction. This channel consolidation concentrates pricing power among integrated processors with crush-to-refinery logistics networks.
Corn Oil Market Segmentation
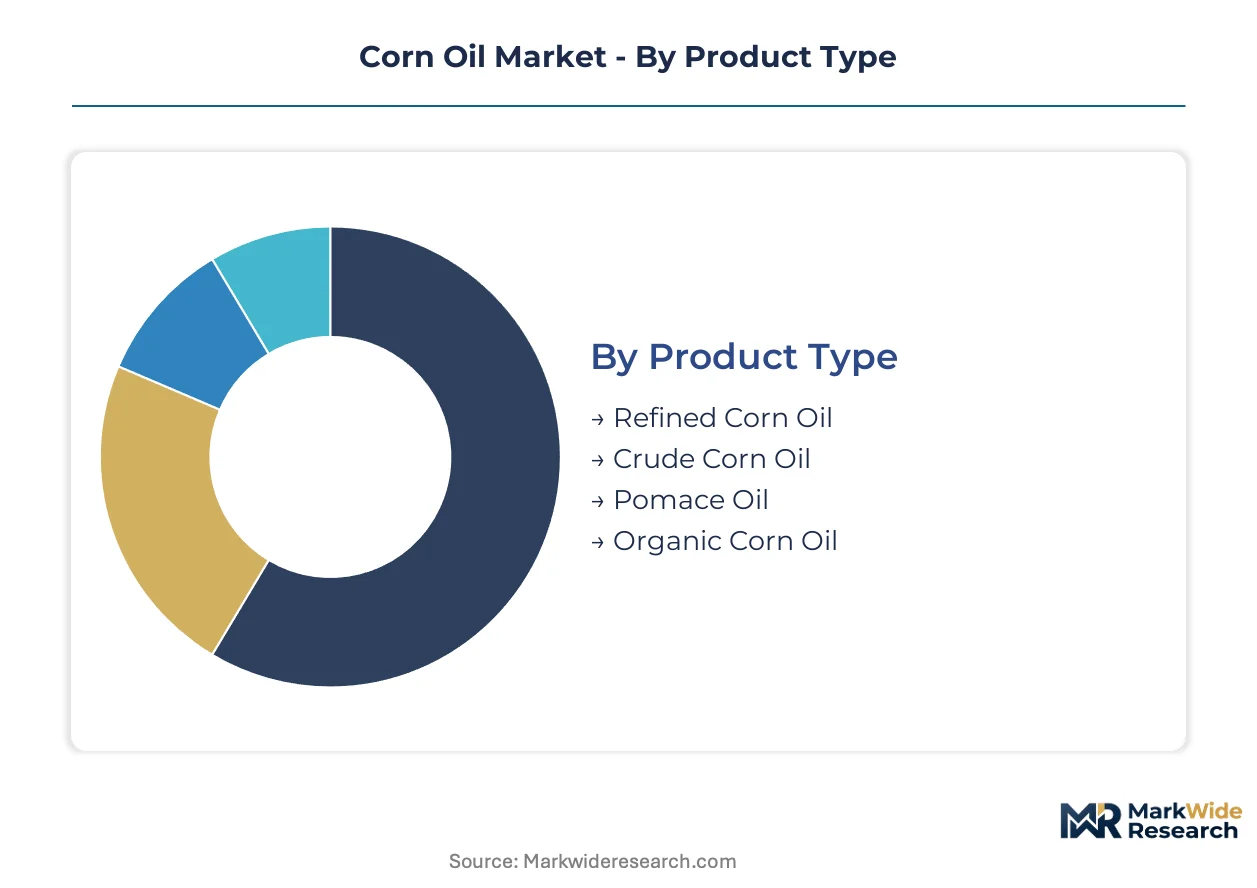
Corn oil segmentation reflects bifurcated supply chains serving food-grade purity requirements and fuel-grade volume commitments. Specification tiers determine extraction technology, carbon intensity scoring, and end-use qualification under divergent regulatory frameworks.
Product Type:
Cold-press and expeller technologies differentiate grade hierarchies, with solvent residue thresholds separating food-contact eligibility from fuel-only designation.
- Refined Corn Oil:Degummed, neutralized, and bleached to achieve smoke points near 450°F with hexane residues below FDA food-contact substance notification limits. Foodservice operators in Iowa and Illinois specify refined grades for extended fry-life in high-volume quick-service restaurants, though biodiesel offtake agreements now divert increasing volumes from food channels toward renewable diesel refineries in Louisiana and Texas.
- Organic Corn Oil:Expeller-pressed from non-GMO corn germ under USDA National Organic Program certification, commanding shelf-space premiums in Northeast and Pacific Northwest natural-product retail channels. Clean-label formulations displace conventional alternatives as ingredient-list scrutiny intensifies among North American and European consumers, though limited germ supply constrains volume scaling.
- Crude Corn Oil:Unrefined extract containing phospholipids and free fatty acids requiring downstream processing for food applications; serves as primary feedstock for biodiesel refiners with in-house pretreatment capacity.
- Pomace Oil:Secondary extraction from germ residues after primary pressing, yielding higher acidity and darker coloration suitable for industrial lubricant formulations and non-food oleochemical applications.
Mature deployment sits with refined corn oil. Newer deployment is concentrated in organic corn oil.
Industry Vertical:
End-use concentration patterns reveal regulatory arbitrage between food safety mandates and renewable fuel credit generation.
- Biofuel:EPA Renewable Fuel Standard obligations and California LCFS carbon intensity scoring redirect distillers corn oil from merchant markets toward long-term offtake contracts with Midwest ethanol plant operators. Fuel producers compete for limited germ-derived supply as soybean oil substitution faces lifecycle emissions penalties under state-level low-carbon frameworks.
- Food & Beverage:Neutral flavor profiles and extended oxidative stability position refined corn oil as standard frying medium across institutional foodservice and packaged snack manufacturing. FDA food-contact substance notifications govern purity thresholds for infant formula and pharmaceutical excipient applications.
- Cosmetics:Emollient properties and comedogenic ratings drive demand in personal care formulations, particularly for expeller-pressed grades marketed as natural alternatives to mineral oil bases.
- Pharmaceuticals:USP-grade refined corn oil serves as excipient carrier for lipid-soluble active ingredients, with ISO 22000 certification and solvent residue documentation required for drug master file submissions.
Established volume concentration rests with food and beverage applications. Steepest expansion trajectory belongs to biofuel verticals.
Application:
Functional performance requirements dictate smoke point thresholds and oxidative stability specifications across thermal processing applications.
- Frying:High-temperature stability demands refined grades with polar compound limits enforced by foodservice quality audits; Iowa and Illinois quick-service chains specify corn oil for cost-competitive fry-life against palm and soy alternatives.
- Cooking:Sauté and shallow-frying applications tolerate lower refinement levels, though consumer preference for neutral flavor profiles sustains refined grade dominance in retail bottle markets.
- Baking:Creaming properties and moisture retention characteristics position corn oil in commercial bakery formulations, particularly for extended shelf-life packaged goods.
- Emulsifying:Lecithin-rich crude fractions and modified phospholipid derivatives serve food processing and cosmetic formulation applications requiring surfactant functionality.
Volume leadership sits with frying applications. Emerging specification intensity concentrates in emulsifying segments.
Distribution Channel:
Channel economics reflect procurement scale divergences between institutional volume buyers and fragmented retail consumption.
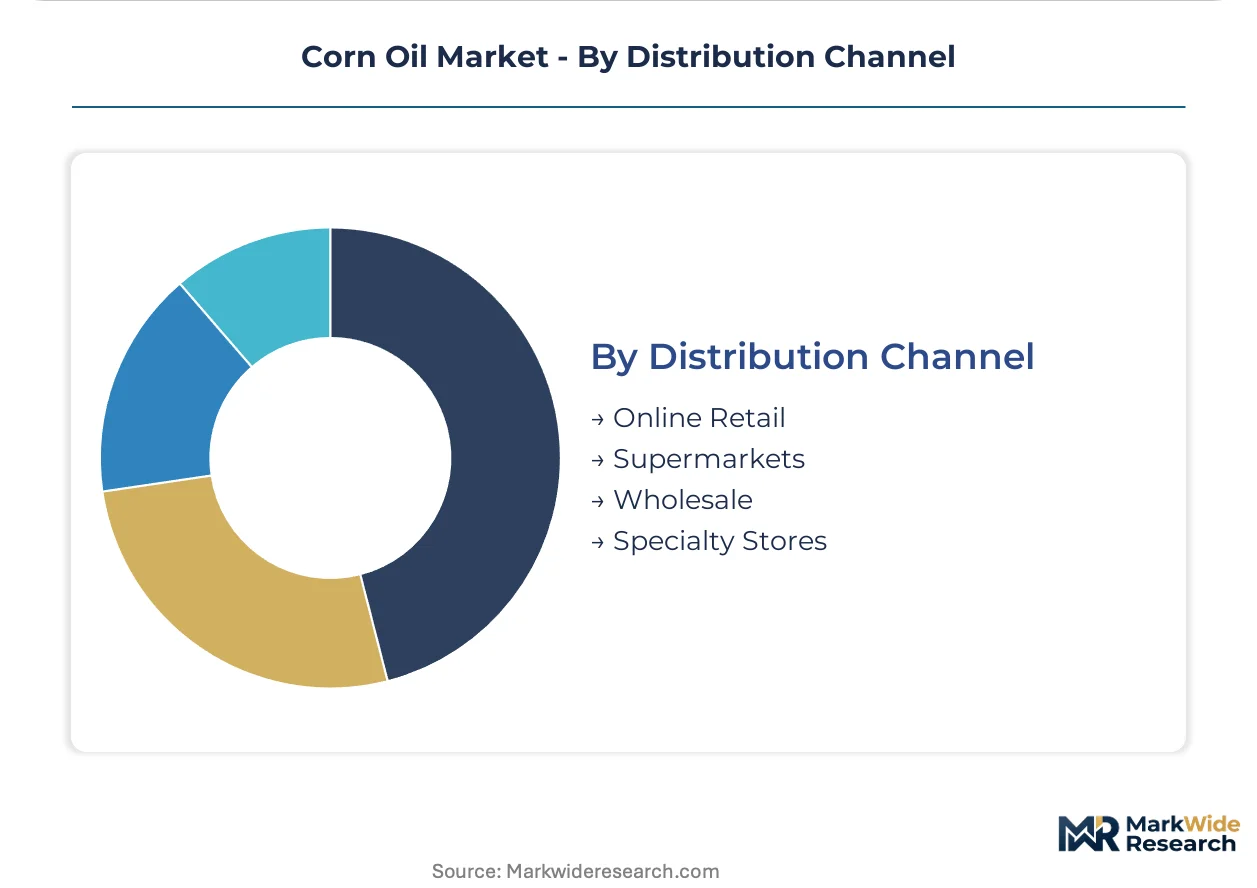
- Wholesale:Direct-procurement contracts between biodiesel refiners and ethanol plant operators displace spot markets, locking in multi-year volume commitments before germ extraction. Integrated crush-to-refinery logistics networks concentrate pricing power among processors with captive supply chains.
- Supermarkets:Retail shelf placement for refined and organic grades competes on price-per-unit against soy, canola, and private-label alternatives, with clean-label positioning commanding premium positioning in natural-product aisles.
- Online Retail:Specialty and organic grades reach direct-to-consumer channels with certificate-of-analysis documentation for expeller-pressed and non-GMO verification, bypassing conventional retail margin structures.
- Specialty Stores:Gourmet and ethnic food retailers stock imported and artisanal corn oil variants for niche culinary applications with limited volume but elevated margin capture.
Contractual volume concentration rests with wholesale channels. Fastest share gains are occurring in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Midwest ethanol plant operators concentrate corn oil supply within 200-mile crush-to-refinery corridors, while Brazilian processors leverage integrated crushing assets to serve South American biodiesel demand.
United States
EPA Renewable Fuel Standard obligations redirect distillers corn oil toward biodiesel refiners competing for limited germ-derived supply. Iowa and Illinois ethanol plant clusters anchor 60% of domestic capacity, with cold-press extraction technologies expanding across wet-milling facilities in Cedar Rapids and Decatur to meet premium food-grade specifications.
Brazil
Biodiesel blend mandates under the RenovaBio program stimulate corn oil offtake from integrated ethanol-to-oil processors. Bunge Limited and domestic crushing groups concentrate operations in Mato Grosso and Goiás, where corn-soy rotation expands germ availability beyond traditional soybean oil dominance.
Argentina
Biofuels law requirements sustain fuel-grade demand for crude corn oil fractions with in-house pretreatment capacity. Rosario and Buenos Aires provinces host wet-milling complexes that fractionate germ streams for export to European renewable diesel facilities seeking lower carbon intensity feedstocks.
China
GB standards for edible oils and expanding biofuel pilot programs create dual-channel demand for refined and crude grades. Shandong and Hebei provinces concentrate corn processing capacity, with state-owned ethanol groups negotiating direct-procurement contracts with regional oil refiners.
India
FSSAI food safety regulations govern refined corn oil purity for packaged food applications, while BIS standards shape industrial grade specifications. Maharashtra and Gujarat host the largest oilseed processing clusters, with domestic ethanol expansion in Punjab and Haryana creating new germ supply sources.
Corn Oil Market Key Industry Players
US-based agribusiness conglomerates anchor the integrated processing tier; European and Middle Eastern traders hold merchant positioning. Market structure bifurcates between crush-to-refinery operators with captive ethanol plant networks and independent refiners dependent on spot procurement. Strategic archetypes include wet-milling specialists with germ-separation proficiency, renewable fuel offtake aggregators, and clean-label organic certifiers. Dominant competitive moves center on multi-year supply contracts locking in volume before extraction and backward integration into ethanol plant ownership.
Within the integrated processing tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify Midwest-based operators with crush-to-refinery logistics networks spanning Iowa and Illinois ethanol corridors. Bunge Limited occupies a merchant positioning archetype, anchoring South American supply chains through Argentine and Brazilian crushing assets.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Abu Dhabi Vegetable Oil Company LLC |
| Savola Group |
| Archer Daniels Midland Company |
| Conagra Brands, Inc. |
| Associated British Foods plc |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Refined-expeller-crude grade divergence separates food-contact premiums from fuel-grade spot volatility, with extraction technology choice locking processors into divergent buyer relationships and margin profiles. Cold-press certification commands shelf-space premiums in Northeast retail channels while unrefined crude flows through long-term offtake contracts toward Louisiana renewable diesel facilities.
Pricing Analysis
Volume-vs-margin split separates merchant biodiesel refiners chasing spot supply from integrated processors capturing food-grade premiums. Three-tier pricing structure across organic, refined, and crude levels reflects extraction technology investment and certification burden. Pricing pressure stems from soybean oil substitution under EPA Renewable Fuel Standard rules, compressing fuel-grade spreads toward food-service parity. Merchant biodiesel operators exhibit highest price sensitivity due to petroleum diesel spread dependency, while organic certifiers maintain pricing power through clean-label scarcity.
Supply Chain Analysis
Germ supply rests on Iowa and Illinois ethanol plant clustering, with wet-milling capacity in Cedar Rapids and Decatur anchoring 60% of domestic volume. Corn kernel availability and hexane solvent logistics constitute critical input dependencies alongside mechanical pressing equipment for premium grades. Single-crop dependency creates structural risk as germ volume ceilings tie exclusively to ethanol production runs regardless of oil demand. Distribution runs through direct-procurement contracts displacing spot markets, with crush-to-refinery corridors consolidating pricing power among integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn oil economics have become a vertical-integration race as fuel-policy restructuring forces processors to secure captive germ supply before extraction. Players are pursuing backward integration into ethanol plant ownership to lock in volume ahead of renewable diesel offtake competition.
For Market Incumbents: Lock in multi-year germ supply agreements with Iowa and Illinois ethanol operators before renewable diesel facility commissioning accelerates. Defend food-grade margin position by accelerating cold-press capacity expansion to meet FDA infant formula notification thresholds. Soybean oil substitution under RFS rules threatens fuel-grade pricing power, requiring integrated processors to deepen upstream control over wet-milling assets. For New Entrants and Emerging Players: California LCFS carbon intensity scoring opens a window for Midwest ethanol plant operators with verified lifecycle accounting to capture West Coast biodiesel premiums. Target organic certification gaps in Pacific Northwest natural-product retail channels where clean-label displacement of conventional oils remains underpenetrated. Pursue direct-to-online retail positioning with certificate-of-analysis documentation bypassing conventional retail margin structures. For Investors and Strategic Acquirers: Re-rating potential sits with wet-milling specialists with germ-separation proficiency given fractionation expertise scarcity and recruitment competition from pharmaceutical sectors. Long-term viability favors processors with captive ethanol plant networks and crush-to-refinery logistics spanning 200-mile corridors. Watch RFS mandate litigation outcomes as inflection indicator for dedicated fuel-grade refining investment paralysis.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Plant Ownership | Captive germ supply secures volume ahead of renewable diesel offtake competition in Iowa and Illinois corridors. |
| Cold-Press Capacity Expansion | Mechanical pressing eliminates hexane residues, qualifying processors for FDA infant formula and pharmaceutical applications. |
| California LCFS Carbon Accounting Verification | Lifecycle emissions documentation unlocks premium credit values for corn oil relative to soy under state-level frameworks. |
| Organic Certification Investment | USDA National Organic Program qualification commands shelf-space premiums in Northeast and Pacific Northwest retail channels. |
| Direct-Procurement Contract Structuring | Multi-year offtake agreements with biodiesel refiners displace merchant spot markets and concentrate pricing power. |
Research Approach
USDA biofuel program guidelines, EPA Renewable Fuel Standard filings, and Iowa State University extension data formed the secondary backbone for supply-side modeling. Primary interviews with ethanol plant operations managers, biodiesel refinery procurement leads, wet-milling technical directors, and FDA regulatory affairs specialists validated extraction technology trends and grade specification evolution. Bottom-up germ volume estimates from ethanol plant capacity data triangulated against top-down biodiesel feedstock demand projections.
Bottom-up segmentation across product type, industry vertical, and distribution channel anchored volume and value outputs over the projection horizon. Grade tier differentiation by extraction technology, end-use qualification under EPA and FDA frameworks, and regional crush-to-refinery corridor density shaped the analytical lens. CAGRs were derived from ethanol plant expansion schedules and renewable diesel facility commissioning timelines, with carbon intensity scoring under California LCFS and Oregon CFP informing premium capture assumptions.
The model assumes a particular technology adoption path; alternative pathways for expeller-pressed extraction scaling would alter the outlook for solvent-extracted grade margins. Forecasts reflect assumptions around RFS mandate stability, crude oil price bands, and organic certification penetration rates. A small set of triggers—RFS litigation outcomes, soybean oil carbon intensity recalibration, and fractionation labor market tightness—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dried Beet Pulp Market
Ingredients
North America Lipid Market
Ingredients
Modified Soya Flour Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Calendula Oil Market
Ingredients
High Oleic Oil Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Bran Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Edible Oils and Fats Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Amylase Market
Ingredients
Food Colors Market