
 United Arab Emirates Sunflower Oil Market | 2026-2036
United Arab Emirates Sunflower Oil Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Sunflower Oil Market Insights
Black Sea crushing capacity is expanding, and Ukrainian and Russian sunflower seed processors are redirecting export volumes toward Middle East buyers. Cargill Incorporated leverages its Black Sea origination network to secure cost-advantaged supply lines into Jebel Ali. IFFCO Group anchors its position through integrated refining and packaging assets in Sharjah. Abu Dhabi Vegetable Oil Co. competes on private-label contracts with major UAE retail chains.
Sunflower oil is a triglyceride vegetable oil extracted from Helianthus annuus seeds, typically refined to achieve smoke points above 230 degrees Celsius for high-heat cooking applications. Its primary commercial purpose centers on frying, baking, and as a salad oil base across food manufacturing and foodservice operations. Refined product dominates volume flows due to neutral flavor profiles and extended shelf stability demanded by institutional buyers. Bulk packaging leads margin capture in the food processing and catering segments, while bottle formats sustain household penetration through supermarket channels.
MOHAP enforces edible oil labeling and fortification standards that shape product formulation requirements for all UAE market entrants. ESMA conformity assessment procedures govern packaging integrity and nutritional declaration accuracy, creating compliance thresholds for imported and domestically refined oils. Stakeholders must monitor Black Sea supply volatility and local warehousing capacity as decisive variables for procurement timing and inventory positioning.
Market Dynamics
MOHAP's edible oil fortification mandates are restructuring procurement specifications across UAE food manufacturing, forcing importers and domestic refiners to reformulate product lines and upgrade testing infrastructure to maintain market access.
Growth Catalysts
- MOHAP Fortification Protocols:Mandatory vitamin A and D enrichment requirements for all edible oils sold in the UAE are creating premium product tiers and expanding addressable value per liter.
- Foodservice Corridor Expansion:Dubai's hotel and restaurant procurement clusters are scaling refined sunflower oil volumes as tourism capacity targets drive commercial kitchen buildouts.
- Black Sea Supply Diversification:Ukrainian and Russian crushing capacity additions are redirecting export flows toward Middle East buyers, improving UAE importer negotiating positions.
Market Restraints
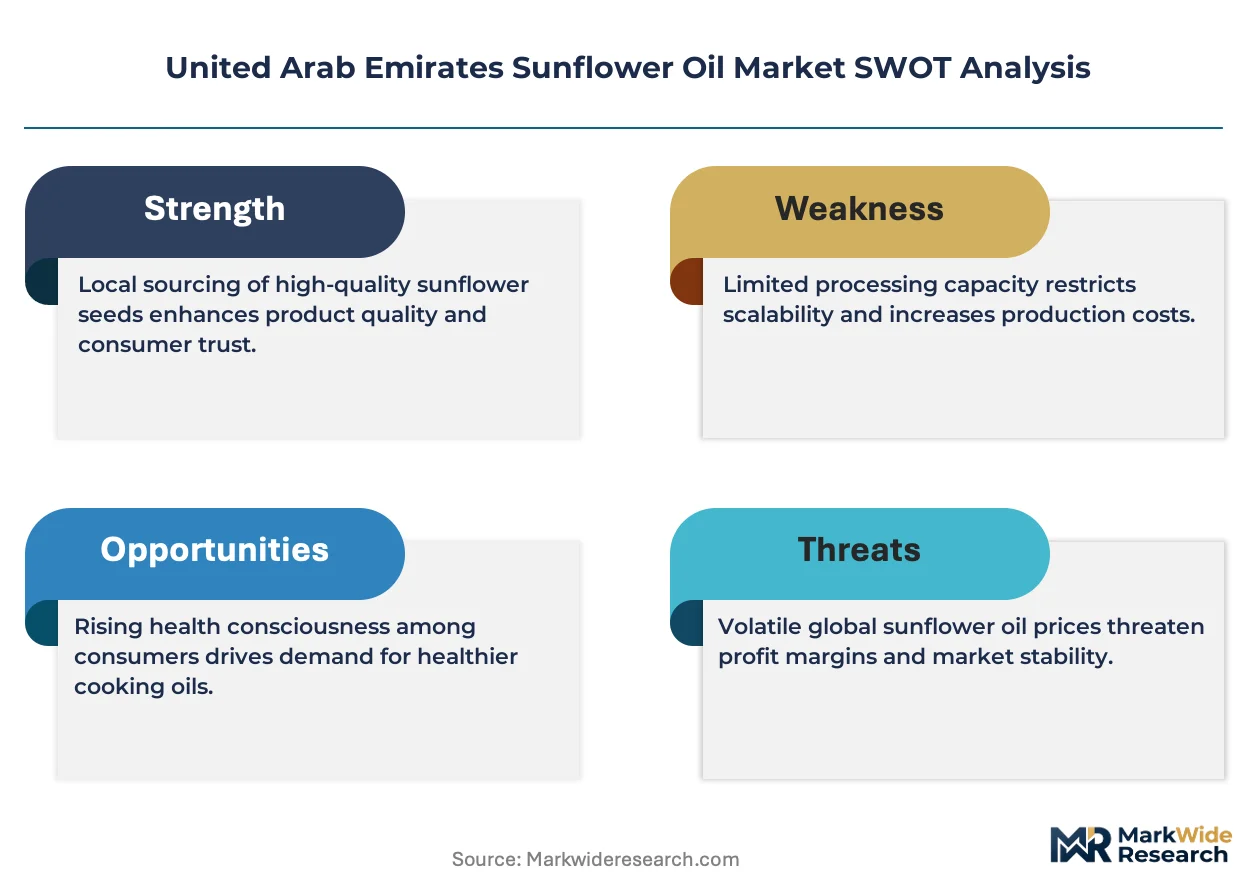
- Seed Price Volatility:Sunflower seed input costs fluctuate with Black Sea harvest conditions and export duty regimes, compressing refiner margins during supply shocks.
- Single-Region Supply Concentration:Overreliance on Black Sea origination creates vulnerability to port congestion, sanctions complexity, and weather-driven crop failures.
- Substitution Elasticity:Palm oil and canola oil price competitiveness in deep-frying applications limits sunflower oil pricing power in institutional segments.
Strategic Opportunities
- Sharjah Industrial Zone Expansion:Underutilized refining and packaging infrastructure in the emirate's food processing corridor offers capacity for private-label contract growth.
- ESMA Digital Labeling Pathway:The standards body's QR-code nutritional disclosure pilot creates first-mover positioning for brands investing in traceability infrastructure.
- E-commerce Bulk Channels:Direct-to-kitchen delivery platforms serving Dubai's cloud kitchen clusters are bypassing traditional distributor markups for high-volume buyers.
Industry Challenges
- Halal Certification Complexity:Multi-jurisdictional halal authority recognition requirements delay product launches and complicate cross-border shipments from non-OIC sources.
- Cold Chain Integration:Bulk oil storage and transport temperature control standards strain existing warehousing infrastructure during summer peak demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Sunflower Oil Market |
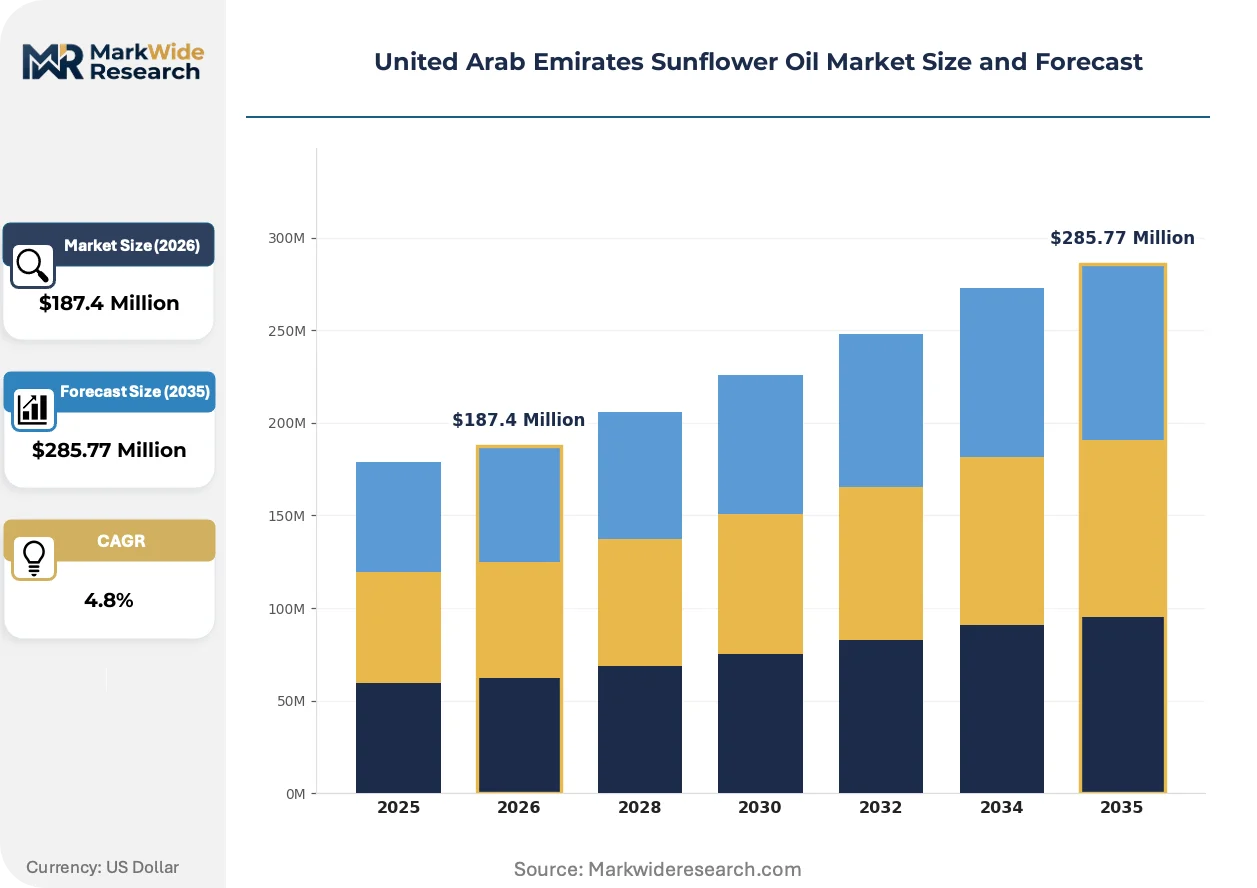
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Crude, Organic, Non-Organic End User: Households, Restaurants, Food Processing, Catering Services Packaging Type: Bottles, Bulk, Pouches, Cans Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores |
| Companies Covered | IFFCO Group, Cargill Incorporated, Abu Dhabi Vegetable Oil Co., Sime Darby Plantation Berhad, Archer Daniels Midland Company, Abu Dhabi Sunflower Oil Co., Savola Group, Rafael Salgado S.A., United Foods Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Sunflower Oil Market Trends and Innovations
Digital traceability infrastructure and processing automation are compressing quality assurance timelines while regulatory disclosure requirements reshape how sunflower oil moves from Black Sea crushers to UAE retail shelves.
Blockchain-enabled provenance tracking is modularizing supply chain verification for UAE importers. Large food manufacturers are deploying distributed ledger systems to document seed origin, crushing dates, and transit conditions. This technology is modularizing compliance documentation, allowing MOHAP auditors to verify chain-of-custody without physical warehouse inspections.
ESMA's updated nutritional labeling standards now require trans-fat disclosure thresholds and serving-size standardization across all edible oil packaging. Refiners must reformulate blends and redesign labels to avoid non-conformity penalties. Dubai-based retail chains are accelerating private-label launches to capture margin from compliant product lines before enforcement deadlines tighten.
Direct sourcing contracts between Sharjah refiners and Dubai foodservice operators are displacing traditional distributor intermediaries. Hotel procurement departments are negotiating annual volume agreements with fixed pricing clauses, transferring inventory risk upstream. This pattern concentrates most visibly in Dubai's hospitality corridor, where group purchasing organizations aggregate demand across property portfolios.
United Arab Emirates Sunflower Oil Market Segmentation
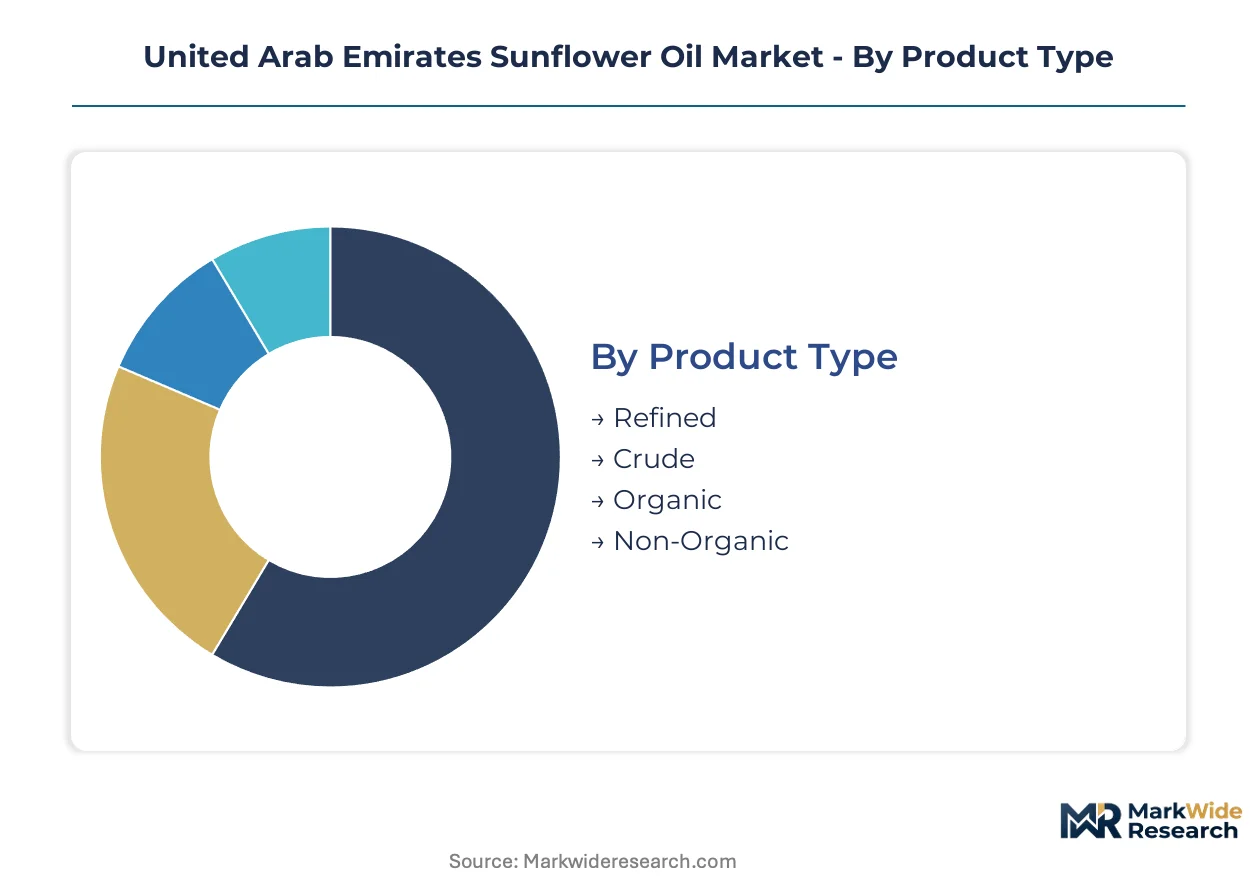
Sunflower oil flows through distinct commercial channels in the UAE, each with divergent margin profiles and regulatory exposure. Procurement specifications vary sharply between institutional buyers and household consumers, shaping how refiners configure their product portfolios.
Product Type:
Capital requirements peak with refining infrastructure, where deodorization and winterization equipment demands the heaviest upfront investment.
- Refined:Deodorized and bleached to achieve neutral flavor profiles and smoke points exceeding 230 degrees Celsius. Dubai's hotel procurement clusters specify refined grades exclusively for high-heat frying applications, with MOHAP fortification mandates adding vitamin A and D blending equipment costs.
- Crude:Unprocessed oil retaining phospholipids and free fatty acids, traded in tanker volumes for Sharjah-based refiners with captive processing capacity. Margins compress during Black Sea harvest volatility, but backward integration into crushing secures supply certainty.
- Organic:Certified seed origin and cold-press extraction command premium positioning in UAE supermarket channels. ESMA traceability requirements extend documentation burdens across the value chain.
- Non-Organic:Conventional cultivation and solvent extraction dominate volume flows into food manufacturing and foodservice operations.
Most installed capacity flows through Refined. Expansion is steepest in Organic.
End User:
Volume concentration tilts toward buyers with centralized procurement and annual contract structures.
- Restaurants:Dubai's hospitality corridor drives bulk refined oil consumption through group purchasing organizations aggregating demand across property portfolios. Direct sourcing contracts with Sharjah refiners are displacing traditional distributor markups.
- Food Processing:Manufacturers of packaged snacks and baked goods specify fortified refined grades with extended shelf stability. MOHAP compliance testing adds overhead that favors suppliers with in-house laboratory infrastructure.
- Households:Supermarket bottle purchases sustain brand recognition but generate lower per-liter margins than institutional segments.
- Catering Services:Event and corporate dining operators mix bulk procurement with flexible delivery scheduling to match seasonal demand spikes.
Restaurants absorb the largest volume share. Food Processing is gaining share fastest.
Packaging Type:
Margin capture diverges between asset-heavy bulk infrastructure and brand-intensive retail formats.
- Bulk:Tanker and intermediate bulk container shipments dominate food processing and catering procurement, minimizing per-unit packaging costs. Jebel Ali liquid bulk terminals enable direct vessel-to-truck transfers for major refiners.
- Bottles:PET and glass formats sustain household penetration through UAE supermarket private-label programs. Label redesign costs for ESMA nutritional disclosure compliance concentrate investment in this segment.
- Pouches:Flexible packaging gains traction in value-oriented retail channels with lower per-unit price points.
- Cans:Metal packaging serves niche applications requiring extended shelf life or specific export market requirements.
Bulk infrastructure handles the greatest throughput. Bottles command the steepest expansion trajectory.
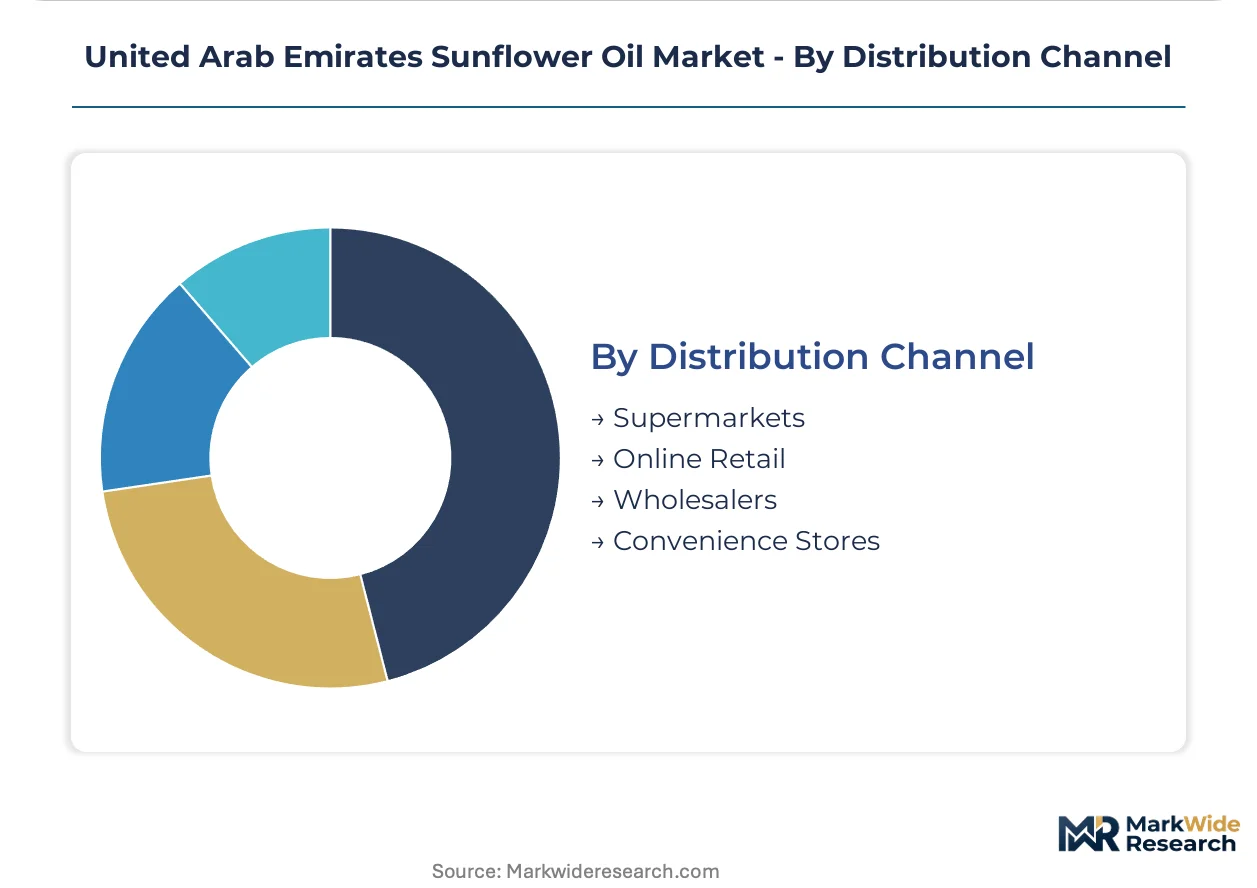
Distribution Channel:
Channel economics reflect divergent working capital intensity and customer acquisition costs.
- Wholesalers:Traditional distributors aggregate fragmented foodservice demand but face margin pressure from direct sourcing trends. Inventory financing requirements strain smaller operators during price volatility.
- Supermarkets:Carrefour, Lulu, and Union Coop chains drive private-label expansion with compliant fortification and ESMA-standardized labeling. Shelf placement fees concentrate power with retail buyers.
- Online Retail:E-commerce bulk channels serving Dubai's cloud kitchen clusters bypass distributor markups through direct-to-kitchen delivery platforms.
- Convenience Stores:Small-format retail captures impulse purchases with premium pricing on single-unit bottles.
Wholesalers retain the deepest installed relationships. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity gravitates toward emirates with lower utility tariffs and streamlined MOHAP licensing, creating compliance-cost arbitrage between Dubai's premium corridor and Sharjah's industrial zones. This geographic sorting concentrates high-volume processing in cost-optimized locations while brand headquarters cluster near buyer decision centers.
Dubai
Hotel procurement clusters along Sheikh Zayed Road and Dubai Marina drive bulk refined oil consumption through group purchasing organizations. ESMA's digital labeling pilot programs receive priority rollout in Dubai retail chains. Jebel Ali liquid bulk terminals enable direct vessel-to-truck transfers for Cargill Incorporated and other major importers serving the emirate's foodservice corridor.
Sharjah
IFFCO Group anchors integrated refining and packaging assets in the Hamriyah Free Zone, exploiting lower industrial electricity rates than Dubai. MOHAP's centralized laboratory testing facility in Sharjah reduces compliance transit times for local refiners. The emirate's underutilized warehousing infrastructure attracts private-label contract manufacturers serving supermarket chains.
Abu Dhabi
Abu Dhabi Vegetable Oil Co. competes on private-label contracts with Lulu and Union Coop retail networks across the capital. The emirate's national oil company downstream expertise occasionally cross-pollinates into edible oil storage terminal design. Khalifa Port expansion plans include dedicated liquid bulk berths for agricultural commodity imports.
Northern Emirates
Ras Al Khaimah and Fujairah host smaller trading houses that consolidate Black Sea shipments for redistribution to inland emirates. These operators exploit lower land costs for tank farm construction but face temperature control challenges during summer peak demand. Port infrastructure limitations constrain direct vessel calls, forcing reliance on Jebel Ali transhipment.
United Arab Emirates Sunflower Oil Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and direct-to-kitchen e-commerce channels. The vendor base clusters around three functional archetypes: integrated refiners with captive crushing relationships, trading houses with Black Sea origination networks, and private-label specialists serving retail chains. Consolidation pressure operates through direct sourcing contracts that displace traditional distributor intermediaries, while capacity expansion concentrates in Sharjah's industrial corridor.
Within the integrated refining tier, IFFCO Group and Cargill Incorporated exemplify divergent supply chain strategies—one anchored in domestic processing assets, the other in origination logistics. Abu Dhabi Vegetable Oil Co. occupies a position between these models, relying on toll refining arrangements rather than captive crushing. These three entities collectively represent the competitive spectrum from upstream control to downstream brand positioning.
| Leading Market Players |
|---|
| IFFCO Group |
| Cargill Incorporated |
| Abu Dhabi Vegetable Oil Co. |
| Sime Darby Plantation Berhad |
| Archer Daniels Midland Company |
| Abu Dhabi Sunflower Oil Co. |
| Savola Group |
| Rafael Salgado S.A. |
| United Foods Company |
| Others |
Pricing and Supply Chain Analysis
Captive refining capacity in Sharjah anchors both supply security and margin capture for integrated operators serving Dubai's foodservice corridor. This backward integration into deodorization and winterization equipment insulates processors from Black Sea seed price spikes while enabling fixed-price annual contracts with hotel procurement clusters.
Pricing Analysis
Distributor margin compression is accelerating as direct sourcing contracts between Sharjah refiners and Dubai hospitality operators displace traditional wholesale intermediaries. Three-tier pricing structure across premium fortified, standard refined, and economy crude grades reflects MOHAP compliance costs and volume scale. Pricing pressure stems from palm oil substitution elasticity in deep-frying applications. Food processing manufacturers exhibit highest price sensitivity due to commodity input exposure, while hotel group purchasing organizations accept premium positioning for supply certainty.
Supply Chain Analysis
Regional distribution centers in Jebel Ali liquid bulk terminals enable hub-and-spoke patterns radiating to Sharjah refiners and Abu Dhabi packaging facilities. Supply concentrates in Ukraine, Russia, and Argentina as dominant seed origins. Raw material dependencies center on sunflower seed availability, crushing capacity utilization, and ocean freight container allocation. Single-region supply concentration creates vulnerability to Black Sea port congestion and sanctions complexity. Distribution runs through integrated refiner-direct contracts and supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE sunflower oil market functions as a stable compounder underpinned by MOHAP fortification mandates that create irreversible premium product tiers and expand per-liter value capture.
For Market Incumbents: Lock in direct sourcing contracts with Dubai's group purchasing organizations before distributor displacement accelerates. Expand captive laboratory testing infrastructure to absorb MOHAP compliance overhead that strains smaller competitors. Defend against palm oil substitution by emphasizing smoke point performance in high-heat frying applications. For New Entrants and Emerging Players: Cloud kitchen direct-to-kitchen delivery platforms represent the most penetrable channel bypassing entrenched wholesale relationships. Target organic certification white space in supermarket private-label programs where ESMA traceability requirements deter incumbent reformulation. Pursue toll refining arrangements with underutilized Sharjah capacity rather than greenfield infrastructure investment. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance testing infrastructure and MOHAP licensing concentration create scale advantages for integrated operators. The market supports long-term viability through recurring foodservice demand and regulatory-mandated product upgrading. Acquisition target archetype: Sharjah-based refiners with private-label contracts and excess packaging capacity. Watch Black Sea export duty volatility as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing | Captive Ukrainian seed supply secures cost advantage during Black Sea volatility. |
| MOHAP Fortification Compliance Investment | In-house vitamin blending equipment creates barrier against non-compliant imports. |
| Direct-to-Kitchen E-Commerce Launch | Bypassing distributor markups captures margin from Dubai cloud kitchen expansion. |
| ESMA Digital Labeling Pilot Participation | QR-code traceability infrastructure positions for first-mover retail shelf advantage. |
| Private-Label Contract Manufacturing Expansion | Sharjah underutilized capacity serves Lulu and Union Coop margin compression strategies. |
Research Methodology
Multiple input streams — procurement manager interviews, refiner operational data, and customs trade records — were reconciled to construct volume and value estimates across the UAE sunflower oil market. Primary discussions with food manufacturing procurement leads, hotel group purchasing officers, Sharjah refinery operations directors, and MOHAP compliance specialists informed demand segmentation and regulatory impact assessment. Secondary validation drew from UAE Federal Customs Authority import statistics, ESMA standards documentation, MOHAP fortification circulars, and Black Sea agricultural commodity export data. Bottom-up channel volume builds were triangulated against top-down edible oil consumption benchmarks.
Data-stream reconciliation across product type, end user, packaging format, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation adjusted for MOHAP regulatory phase-in schedules and foodservice corridor capacity buildouts. Modeled inputs included Black Sea crushing capacity expansion timelines, Dubai tourism infrastructure commissioning, and Sharjah industrial zone utility cost differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Black Sea geopolitical stability and seed harvest variability. Outputs reflect documented assumptions around regulatory enforcement consistency and tourism demand recovery patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hibiscus Extract Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Europe Gelatin Market
Ingredients
Valerian Root Oil Market
Ingredients
Wheat Starch Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Ice Cream Bases Market
Ingredients
Casein Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Camelina Oil Market
Ingredients
Germany Gelatin Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Barley Malt Extract Market
Ingredients
Global Amaranth Oil Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Pet Food Ingredients Market