
 Palmitoyl Chloride Market | 2026-2036
Palmitoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Palmitoyl Chloride Market Outlook
Pharmaceutical companies are unwinding historical reliance on industrial-grade palmitoyl chloride, redirecting procurement toward pharmaceutical-grade and cosmetic-grade specifications. Lanxess anchors European supply through backward integration into palm oil derivatives and captive chlorination capacity. Jiangxi Yuanxing Chemical Co. Ltd dominates bulk industrial-grade production from Jiangxi Province, while Sigma-Aldrich specializes in high-purity laboratory and pharma-grade distribution channels.
Palmitoyl chloride is a C16 saturated fatty acid chloride synthesized via thionyl chloride or phosphorus trichloride reaction with palmitic acid, typically yielding a colorless to pale yellow liquid with a pungent odor and reactivity toward nucleophiles that makes it essential for amidation and esterification in organic synthesis. Cosmetic-grade material commands premium positioning amid tightening dermatological safety standards, while pharmaceutical-grade volumes are accelerating fastest as lipid nanoparticle formulations expand in mRNA therapeutics and oncology drug delivery. Industrial-grade supply remains mature and price-competitive, serving surfactant and agrochemical intermediate markets where margin pools are thinner.
REACH registration requirements in Europe, FDA Good Manufacturing Practice standards for pharmaceutical excipients, and China's GB chemical safety codes collectively determine which suppliers gain market access and which product grades qualify for regulated end uses. The EU Green Deal's chemical sustainability criteria are beginning to constrain palm-oil-derived feedstock acceptance, pushing producers to document chain-of-custody certification. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to pursue multi-grade certification or concentrate capacity in the specification tier with the most durable compliance pathway.
Market Dynamics
Pharmaceutical-grade specification requirements are compressing industrial-grade margins while concentrating supply among chlorination specialists with documented chain-of-custody certification. This structural force is redirecting capital toward purity-upgrade infrastructure and regulatory compliance documentation systems.
Growth Catalysts
- Lipid nanoparticle formulations:mRNA therapeutics and oncology drug delivery systems are pulling pharmaceutical-grade volumes upward. FDA Good Manufacturing Practice standards for excipients are accelerating qualification timelines for compliant suppliers.
- REACH registration:European chemical sustainability criteria under the EU Green Deal are constraining palm-oil-derived feedstock acceptance. Producers with documented certification are gaining preferential market access.
- China and India:Asian chemical manufacturers are expanding fatty acid chloride output capacity. Regional production clusters are reducing import dependency for surfactant and agrochemical intermediate markets.
Market Restraints
- Feedstock volatility:Palm oil derivative prices fluctuate with Malaysian and Indonesian export policy shifts. Chlorination input costs track sulfur and phosphorus trichloride spot markets.
- Supply concentration:Bulk industrial-grade production clusters in Jiangxi Province create geographic single-point vulnerability. Logistics disruptions ripple through surfactant downstream channels.
- Substitution pressure:Stearoyl chloride competes in amidation applications where carbon chain length flexibility exists. Formulators blend C16-C18 chlorides to optimize cost-performance ratios.
Strategic Opportunities
- Underpenetrated geographies:Brazil's agrochemical sector imports palmitoyl chloride for surfactant intermediates. ANVISA pharmaceutical excipient registration opens pathway for grade-upgrade capture.
- Emerging applications:Cosmetic-grade material commands premium positioning amid dermatological safety standard tightening. K-beauty and J-beauty formulators specify documented impurity profiles.
- Technology convergence:Continuous flow chlorination reactors integrate with real-time analytical release testing. Automated quality systems reduce batch-to-batch variation for pharmaceutical customers.
Industry Challenges
- Skill scarcity:Experienced chlorination chemists with thionyl chloride handling expertise are retiring. Training programs for phosphorus trichloride reactor operation lag replacement demand.
- Certification timelines:FDA Type II Drug Master File preparation extends 18-24 months. Pharmaceutical-grade qualification delays revenue recognition for capital-intensive purity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palmitoyl Chloride Market |
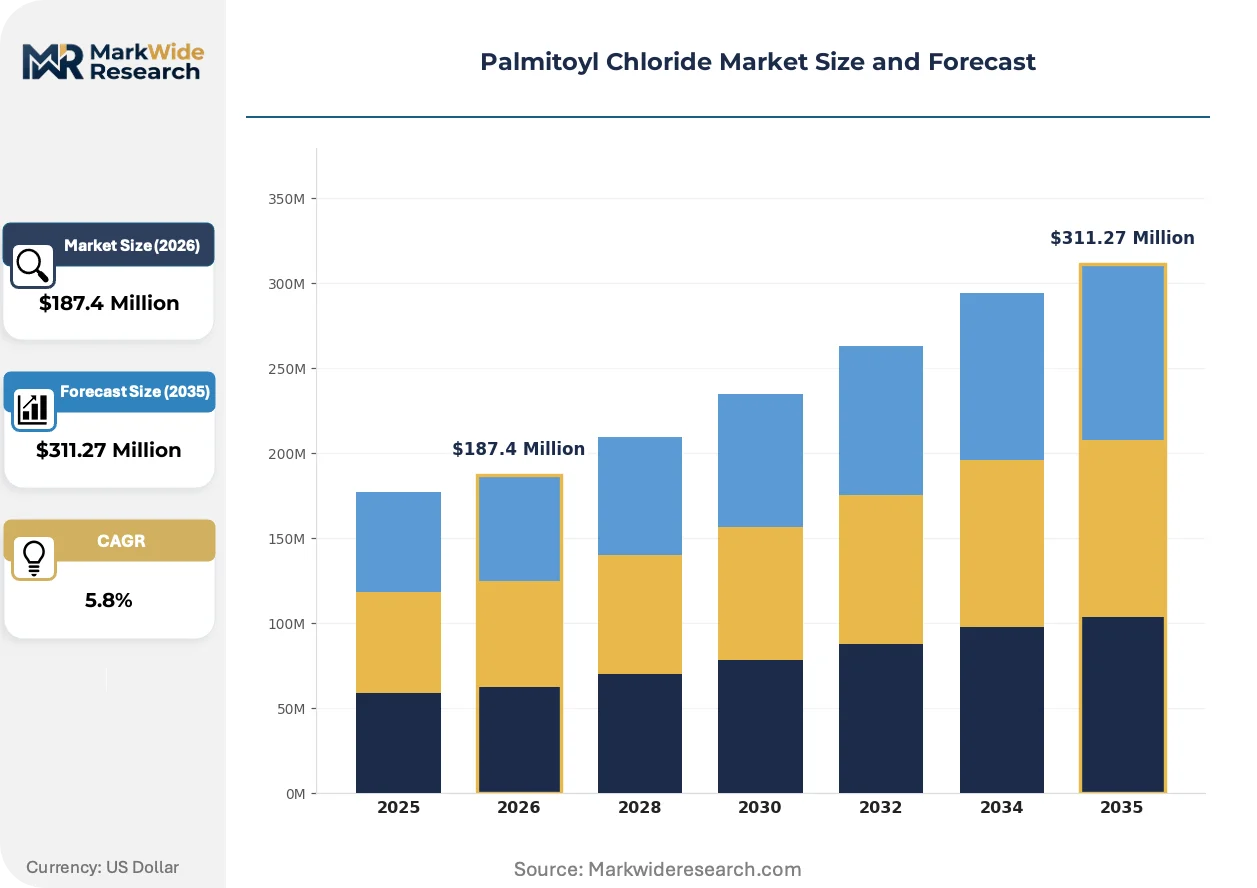
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Personal Care, Pharmaceuticals, Food Additives, Surfactants End User: Cosmetic Manufacturers, Pharmaceutical Companies, Food Processors, Chemical Industries Form: Liquid, Powder, Granules, Emulsion |
| Companies Covered | Lanxess, Shiva Pharmachem Ltd., Jiangxi Yuanxing Chemical Co. Ltd, ERCO Worldwide, Westlake Corporation, Chongqing Changfeng Chemical Industrial Co. Ltd., Hebei Guochen Chemical Co. Ltd., Sigma-Aldrich, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palmitoyl Chloride Market Strategic Shifts
Process intensification and regulatory digitization are restructuring how palmitoyl chloride is manufactured, qualified, and procured. These shifts favor suppliers with integrated analytical capabilities and documented sustainability credentials.
Continuous flow chlorination technology is bifurcating the reactor landscape between batch-operated industrial-grade plants and pharmaceutical-grade facilities with real-time process analytical technology. Lipid nanoparticle formulators specify sub-ppm impurity thresholds that batch systems struggle to guarantee. This technology divide is compressing margins for non-upgraded assets while enabling premium capture for compliant producers.
EU Green Deal chemical sustainability criteria are tightening palm-oil-derived feedstock documentation requirements. ECHA is expanding substance evaluation scope for fatty acid chlorides under REACH Article 54. Cosmetic and pharmaceutical end-users are demanding mass-balance certification that traces feedstock to plantation level, with suppliers in Malaysia and Indonesia investing in segregated supply chains.
Specification-driven purchasing is displacing spot-market procurement for pharmaceutical-grade material. Large molecule drug developers are locking multi-year supply agreements with audited chlorination specialists. This behavioral shift is most visible in mRNA vaccine manufacturing clusters where excipient security-of-supply clauses override price competition in contract negotiations.
Palmitoyl Chloride Market Segmentation
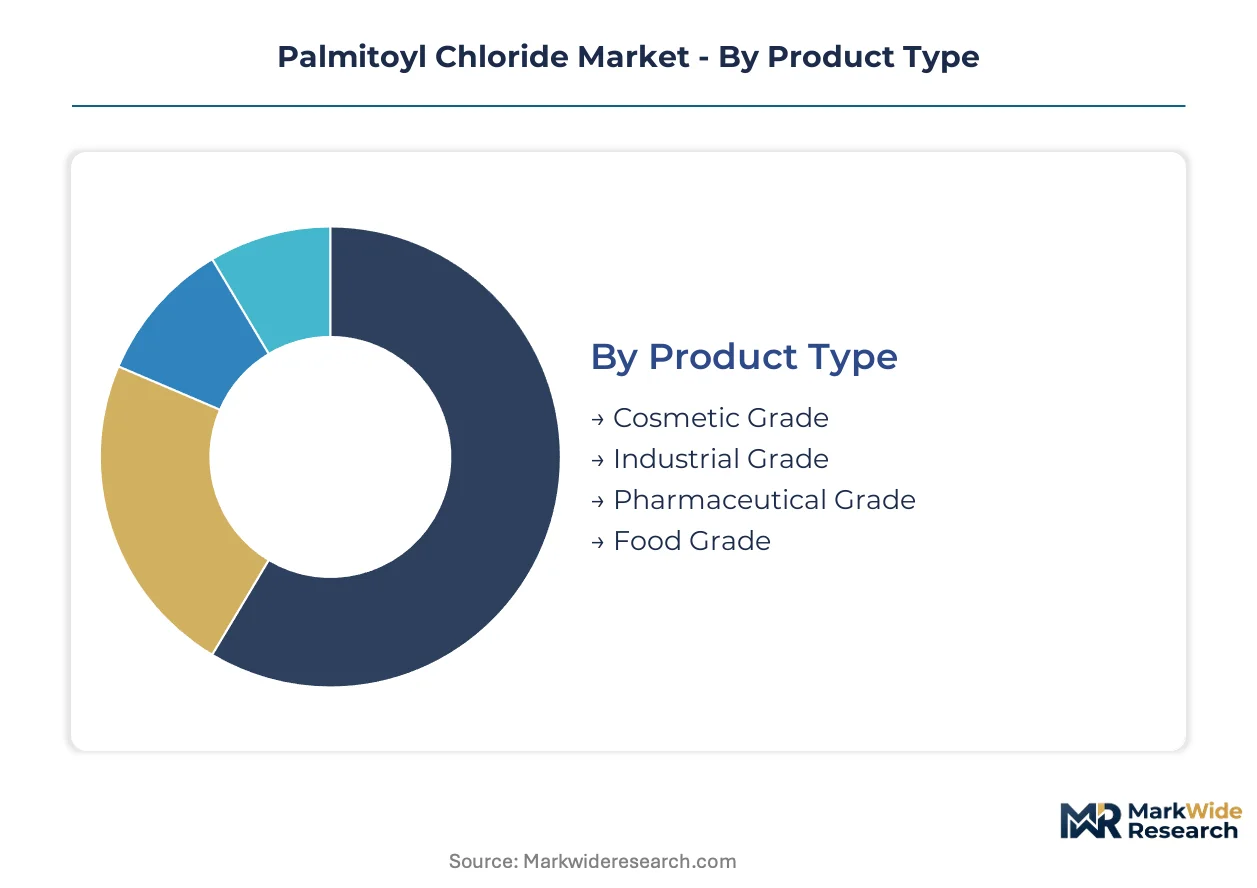
Grade purity thresholds and regulatory qualification requirements fragment procurement behavior across end-use verticals. Formulators specify divergent impurity profiles that reshape supplier capability investments and margin structures.
Product Type:
Substitution pressure from stearoyl chloride and C14-C18 chloride blends intensifies most acutely in industrial-grade applications where chain-length flexibility reduces specification rigidity.
- Pharmaceutical Grade:Sub-ppm impurity thresholds and documented chain-of-custody certification qualify material for lipid nanoparticle formulations. FDA Drug Master File requirements compress supplier pools to chlorination specialists with validated continuous flow reactors.
- Cosmetic Grade:Dermatological safety standards and mass-balance feedstock documentation command premium positioning. K-beauty and J-beauty formulators in Seoul and Osaka specify detailed impurity profiles that batch-operated plants cannot guarantee.
- Industrial Grade:Surfactant and agrochemical intermediate applications dominate procurement volumes from Jiangxi Province clusters.
- Food Grade:Limited application scope constrains dedicated production capacity investments.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates qualification-intensive pharmaceutical applications from price-sensitive surfactant markets.
- Pharmaceuticals:mRNA therapeutics and oncology drug delivery systems pull volumes upward. Lipid nanoparticle formulations specify excipient-grade material that triggers FDA Good Manufacturing Practice audits.
- Personal Care:Cosmetic-grade material integrates into emulsifier and conditioning agent formulations. EU Green Deal sustainability criteria constrain palm-oil-derived feedstock acceptance for mass-market products.
- Surfactants:Industrial-grade supply serves agrochemical and cleaning product intermediates where margin pools are thinner.
- Food Additives:Niche application scope limits dedicated supply chain development.
Surfactants retain volume leadership; Pharmaceuticals holds the steepest expansion curve.
End User:
Customer type determines procurement modality — specification-driven long-term agreements versus spot-market purchasing.
- Pharmaceutical Companies:Large molecule drug developers lock multi-year supply agreements with audited chlorination specialists. Security-of-supply clauses override price competition in contract negotiations.
- Cosmetic Manufacturers:K-beauty and J-beauty formulators demand documented impurity profiles and mass-balance certification. Premium positioning reflects dermatological safety standard tightening.
- Chemical Industries:Surfactant and agrochemical intermediate producers source industrial-grade material on price-competitive terms.
- Food Processors:Limited penetration constrains segment-specific supplier development.
Chemical Industries retain volume leadership; Pharmaceutical Companies holds the steepest expansion curve.
Form:
Supply concentration in liquid production reflects reactor economics and downstream handling infrastructure.
- Liquid:Colorless to pale yellow liquid with pungent odor represents standard commercial form. Thionyl chloride and phosphorus trichloride reaction outputs ship in bulk tank containers or drums.
- Powder:Solid-phase handling advantages attract specific formulation applications. Drying and milling investments concentrate among specialty chemical distributors.
- Granules:Limited commercial availability reflects narrow application demand.
- Emulsion:Aqueous dispersion form serves niche cosmetic formulation requirements.
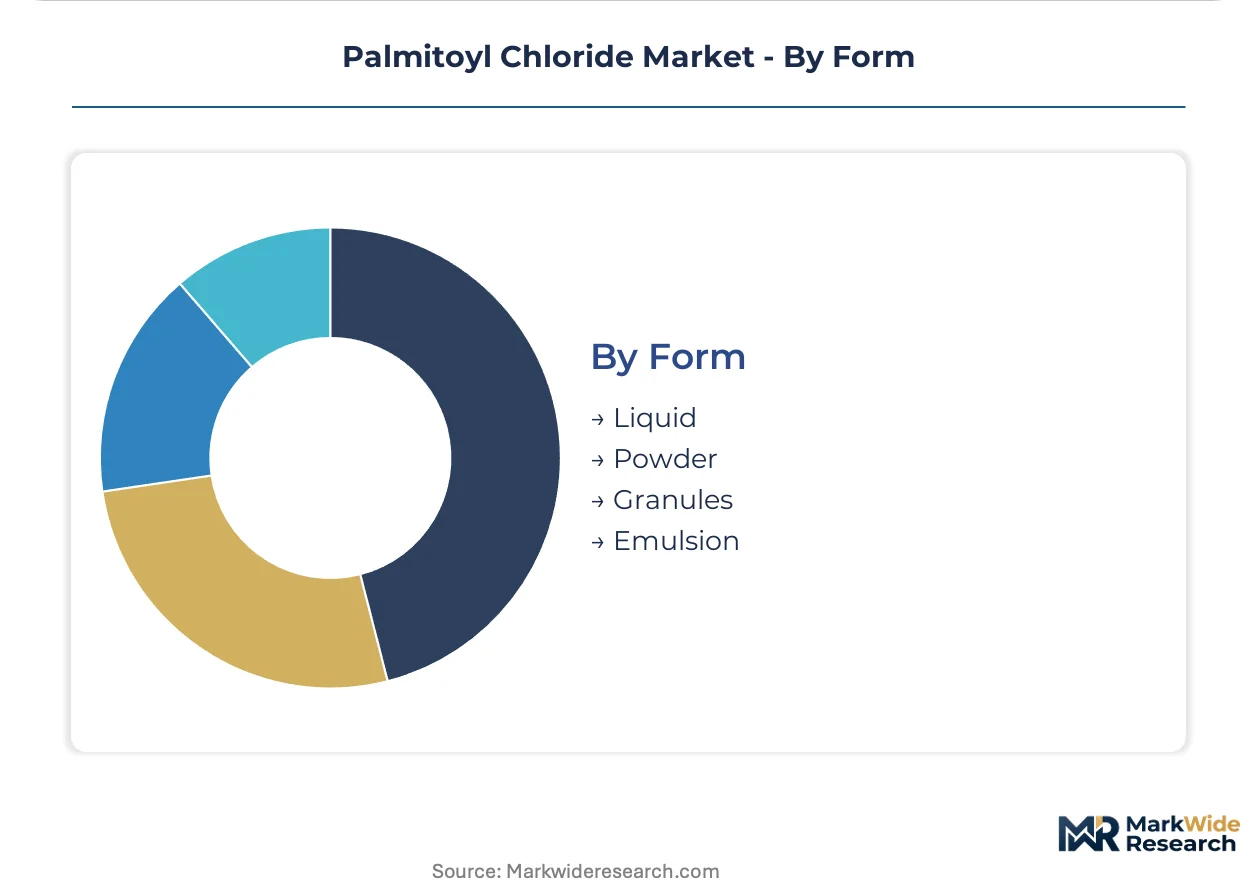
Liquid retains volume leadership; Powder holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker infrastructure anchors European palmitoyl chloride distribution, while Shanghai's Yangshan deep-water port facilities handle the bulk of Asian fatty acid chloride transshipment. These maritime assets determine regional supply security and grade availability.
United States
FDA Type II Drug Master File requirements drive pharmaceutical-grade qualification investments among chlorination specialists. EPA oversight of thionyl chloride emissions shapes reactor permitting in Texas and Louisiana chemical corridors. Houston's petrochemical cluster hosts backward-integrated producers with captive palm oil derivative supply.
Germany
REACH registration obligations and ECHA substance evaluation protocols constrain supplier pools to certified chlorination operators. EU Green Deal sustainability criteria pressure feedstock documentation standards. Leverkusen and Ludwigshafen chemical parks concentrate pharmaceutical-grade capacity with integrated analytical release systems.
China
GB chemical safety codes and NMPA pharmaceutical excipient standards govern multi-grade production licensing. Dual carbon goals accelerate chlorination process efficiency mandates. Jiangxi Province industrial clusters dominate bulk industrial-grade output, while Shanghai and Jiangsu facilities upgrade for pharmaceutical qualification.
India
CDSCO pharmaceutical excipient registration and BIS quality standards create compliance barriers for imported material. PLI scheme incentives support specialty chemical manufacturing scale-up. Gujarat chemical corridors expand fatty acid chloride capacity to serve domestic surfactant and agrochemical intermediate demand.
Brazil
ANVISA pharmaceutical excipient registration opens pathways for grade-upgrade capture in Latin America's largest pharma market. Agrochemical surfactant demand pulls industrial-grade imports through Santos port facilities. São Paulo state chemical distributors consolidate procurement for regional formulators.
Palmitoyl Chloride Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and grade purity specifications. The vendor base stratifies between multinational chemical conglomerates with backward-integrated feedstock control and regional chlorination operators serving price-sensitive industrial segments. Three archetypes dominate: integrated palm oil derivative processors, standalone chlorination specialists, and laboratory-grade distributors. Capacity expansion in pharmaceutical-grade continuous flow reactors and strategic partnerships for chain-of-custody certification represent the dominant competitive moves.
Within the integrated processor tier, Lanxess anchors European supply security through captive chlorination assets. Jiangxi Yuanxing Chemical Co. Ltd exemplifies the scale-driven industrial-grade archetype from its Jiangxi Province manufacturing base. Sigma-Aldrich occupies the high-purity distribution position, serving pharmaceutical and laboratory customers with documented impurity profile specifications.
| Leading Market Players |
|---|
| Lanxess |
| Shiva Pharmachem Ltd. |
| Jiangxi Yuanxing Chemical Co. Ltd |
| ERCO Worldwide |
| Westlake Corporation |
| Chongqing Changfeng Chemical Industrial Co. Ltd. |
| Hebei Guochen Chemical Co. Ltd. |
| Sigma-Aldrich |
| BASF |
| Others |
Value Chain & Pricing Dynamics
FDA Good Manufacturing Practice standards for pharmaceutical excipients gate both supply qualification and price differentiation simultaneously, compressing supplier pools while enabling premium capture for compliant chlorination specialists. REACH registration in Europe and NMPA standards in China extend this dual-gating effect across major demand centers, creating tiered margin structures that reward documented purity and sustainability credentials.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade contracts from spot-market industrial-grade procurement, with large molecule drug developers locking multi-year supply agreements that override price competition. Price differentiation hinges on certification grade and chain-of-custody documentation, with cosmetic-grade material commanding premiums amid dermatological safety tightening. Pricing pressure stems from feedstock volatility in palm oil derivatives and sulfur trichloride inputs, with agrochemical surfactant producers exhibiting highest price sensitivity while mRNA vaccine manufacturers prioritize security-of-supply over cost.
Supply Chain Analysis
China and India anchor bulk industrial-grade production, with Jiangxi Province clusters and Gujarat chemical corridors feeding surfactant and agrochemical intermediate demand. Raw material dependencies center on Malaysian and Indonesian palm oil derivatives, sulfur trichloride, and phosphorus trichloride. Single-source vulnerability concentrates in Jiangxi Province's geographic clustering, where logistics disruptions ripple through downstream channels. Distribution runs through Rotterdam's chemical tanker infrastructure for European pharmaceutical-grade material and Shanghai's Yangshan port for Asian transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment, where FDA Drug Master File preparation timelines and REACH registration obligations create switching costs that protect qualified incumbents from price-only competition.
For Market Incumbents: Fortify position by deepening backward integration into palm oil derivative supply and accelerating continuous flow reactor upgrades for pharmaceutical-grade purity. Stearoyl chloride substitution pressure in amidation applications demands proactive customer lock-in through multi-year excipient supply agreements. Certification investment in EU Green Deal mass-balance documentation preserves premium positioning against emerging Asian competitors. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade qualification with automated quality systems and real-time analytical release testing that batch-operated incumbents cannot match. Brazil's ANVISA registration pathway offers the most penetrable geography, with São Paulo state chemical distributors consolidating procurement for regional formulators. K-beauty and J-beauty cosmetic-grade specifications provide a go-to-market angle through documented impurity profiles that command dermatological safety premiums. For Investors and Strategic Acquirers: FDA Type II Drug Master File submission waves reshape the acquisition landscape, favoring targets with validated continuous flow assets over batch-operated legacy plants. Long-term viability centers on chlorination specialists with integrated analytical capabilities and documented sustainability credentials. Watch ECHA substance evaluation scope expansion under REACH Article 54 as the inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Derivatives | Captive feedstock supply insulates margin compression from Malaysian export policy volatility. |
| Continuous Flow Reactor Upgrade | Real-time process analytical technology guarantees sub-ppm impurity thresholds for lipid nanoparticle formulators. |
| EU Green Deal Mass-Balance Certification | Segregated supply chain documentation preserves pharmaceutical and cosmetic market access. |
| Long-term Supply Agreement with mRNA Developers | Security-of-supply clauses override price competition in excipient procurement negotiations. |
| Joint Venture for Asian Production Scale-Up | Shanghai and Jiangsu facilities leverage GB chemical safety codes for domestic pharmaceutical qualification. |
Study Parameters
Operator-level perspectives from chlorination plant managers, pharmaceutical procurement leads at lipid nanoparticle formulators, cosmetic R&D directors specifying dermatological safety standards, and distribution channel partners in Rotterdam and Shanghai anchored the qualitative base. Primary interviews combined with secondary validation from FDA Drug Master File databases, ECHA REACH registration records, customs and trade data for fatty acid chloride flows, and SEC filings from listed chemical conglomerates. Bottom-up grade-tier volume estimates and top-down end-use industry sizing were triangulated against production capacity disclosures from Jiangxi Province industrial clusters.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios, regulatory timeline acceleration assumptions, and substitution elasticity between palmitoyl and stearoyl chlorides. Segmentation dimensions modeled include grade purity tier, end-use application, regional production hub, and customer procurement modality. CAGRs were derived from regression analysis of historical volume trajectories and forward projection of lipid nanoparticle formulation expansion. Industry-specific inputs incorporated NMPA pharmaceutical excipient licensing pace and EU Green Deal chemical sustainability criteria implementation timelines.
Material uncertainties — palm oil derivative export policy shifts, chlorination input cost spikes, and REACH Article 54 substance evaluation scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance timeline stability and mRNA therapeutic manufacturing scale-up continuity. Recalibration cycles align with material shifts in ECHA evaluation protocols and FDA excipient audit priority changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Thiochemicals Market