
 United States Cellulose Acetate Market | 2026-2036
United States Cellulose Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cellulose Acetate Market Intelligence
Gulf Coast petrochemical capacity expansion is rebalancing domestic acetic acid feedstock availability for cellulose acetate producers. Eastman Chemical Company leverages its Kingsport, Tennessee integrated complex to sustain captive supply of raw materials. Celanese Corporation anchors its North American position through specialized acetyl chain operations. Daicel Corporation competes via technology leadership in high-purity filtration grades.
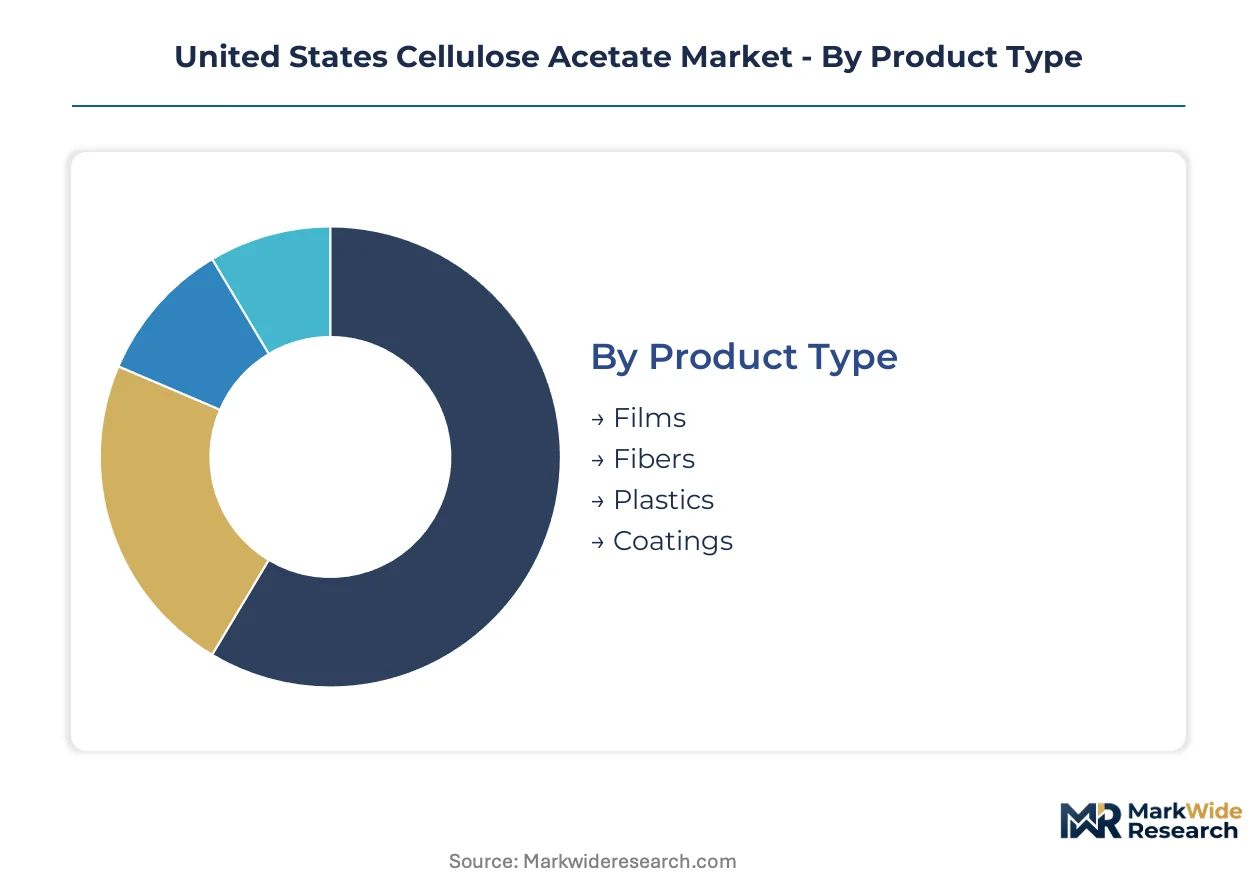
Cellulose acetate is a thermoplastic polymer derived from cellulose esterification with acetic anhydride, typically containing 39 to 44 percent acetyl content and exhibiting a glass transition temperature near 180 degrees Celsius. It serves primarily as a functional material in filtration media, textile fibers, and controlled-release coatings where biodegradability and optical clarity prove essential. Fibers command the largest volume share within product type segments, reflecting entrenched cigarette filter tow demand, while Films represents the fastest-expanding category driven by specialty packaging and LCD polarizer applications. Plastics occupies a mature niche in tool handles and eyeglass frames where aesthetic finish and machinability sustain margin pools despite slower volume growth.
EPA regulations under the Toxic Substances Control Act govern chemical manufacturing emissions, while FDA standards specify food-contact compliance thresholds for cellulose acetate films and coatings. OSHA workplace exposure limits further shape production facility design and operational costs across domestic manufacturing sites. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York that could reshape packaging material specifications and recycling infrastructure requirements.
Market Dynamics
EPA Toxic Substances Control Act enforcement is intensifying emissions scrutiny at acetylation facilities, forcing producers to retrofit Kingsport and Narrows plants with carbon capture adjacent to cigarette filter tow lines.
Growth Catalysts
- LCD polarizer film demand:Specialty packaging and display manufacturers in Tennessee and Virginia are expanding cellulose acetate film offtake for optical clarity applications.
- Biodegradable filtration mandates:Municipal water districts across the Southeast are specifying cellulose acetate over synthetic polymers for membrane applications.
- Acetic acid feedstock localization:Gulf Coast petrochemical expansion is shortening supply chains for domestic acetyl raw material inputs.
Market Restraints
- Acetic anhydride price volatility:Feedstock costs fluctuate with methanol-carbon monoxide synthesis economics and energy input swings.
- Single-source supply concentration:Domestic cigarette filter tow production clusters in three Tennessee-Virginia-North Carolina corridor facilities.
- Polypropylene substitution in filtration:Melt-blown synthetic media captures share in cost-sensitive industrial air filtration segments.
Strategic Opportunities
- California extended producer responsibility:State packaging mandates create certified biodegradable film demand that cellulose acetate satisfies.
- Controlled-release pharmaceutical coatings:FDA food-contact compliance positions the material for oral dosage form barrier applications.
- Digital printing substrate convergence:Specialty printers in North Carolina are trialing cellulose acetate for high-clarity graphic overlay production.
Industry Challenges
- Acetylation process engineering expertise:Skilled operators capable of managing sulfuric acid catalysis and degree-of-substitution control remain scarce in the domestic labor pool.
- OSHA workplace exposure compliance:Acetic acid vapor monitoring and ventilation retrofitting at aging production facilities demands sustained capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cellulose Acetate Market |
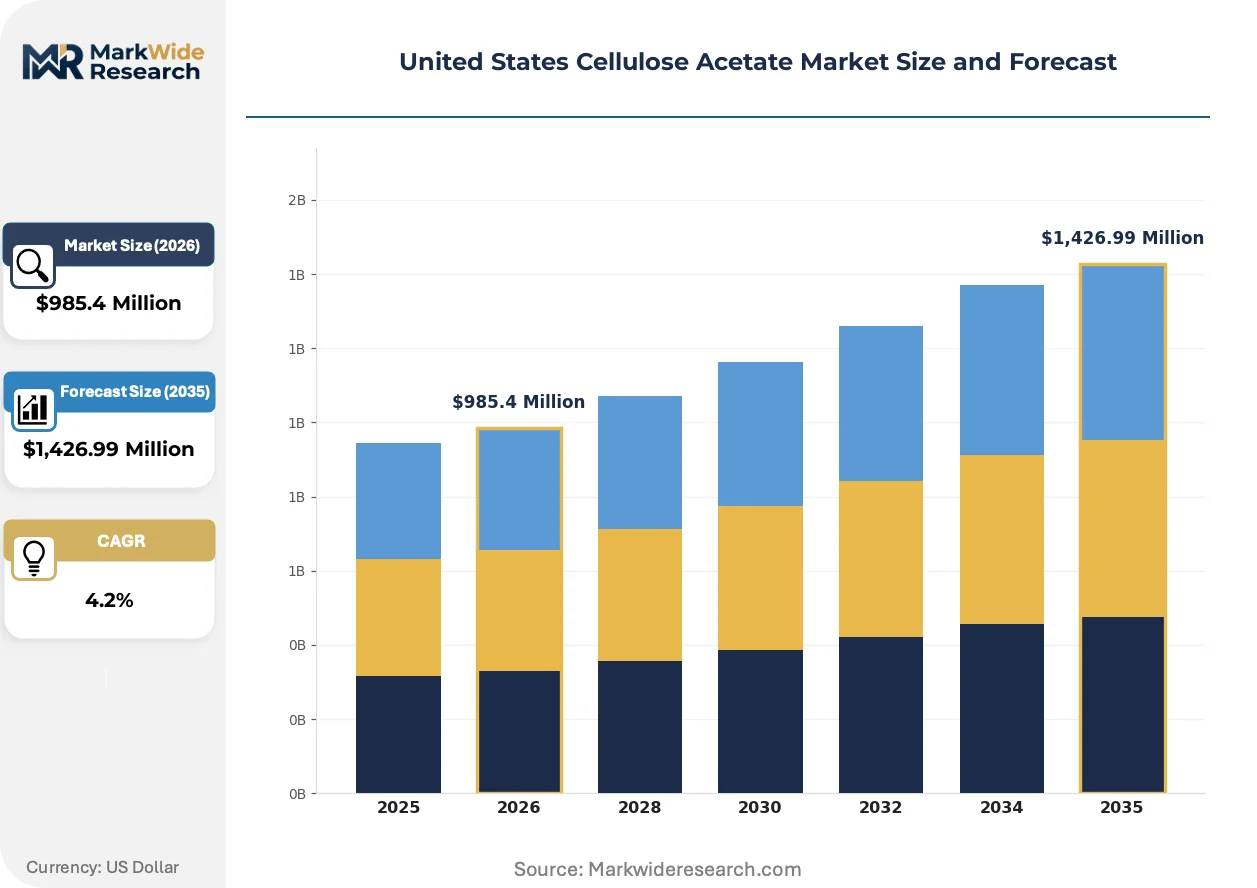
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,426.99 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Fibers, Plastics, Coatings End Use Industry: Textiles, Packaging, Healthcare, Automotive Form: Granules, Sheets, Solutions, Powders Application: Filtration, Adhesives, Inks, Lacquers |
| Companies Covered | Eastman Chemical Company, Celanese Corporation, Daicel Corporation, Rayonier Advanced Materials, Mitsubishi Chemical Holdings Corporation, Solvay, Sappi, Rotuba Extruders, Cerdia International GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cellulose Acetate Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on synthetic polymer persistence are redirecting R&D investment toward high-performance biodegradable alternatives across filtration, packaging, and optical applications.
Cellulose acetate butyrate modification is unifying the mechanical durability of engineering plastics with the optical transmission properties required for polarizer protection films. Display manufacturers in the Research Triangle corridor are qualifying these grades for foldable screen substrates. The convergence is compressing qualification timelines for conventional polyethylene terephthalate alternatives in premium electronics applications.
FDA food-contact notification pathways are tightening purity documentation requirements for cellulose acetate films used in direct-contact packaging. Manufacturers must now submit comprehensive extractables testing for acetic acid residual and plasticizer migration. Specialty film converters in Virginia are restructuring quality systems to accommodate the expanded compliance burden.
Specification-driven procurement is consolidating buyer power among Southeast tobacco filter manufacturers and specialty chemical distributors. Direct mill relationships are displacing multi-tier distribution for high-volume cigarette filter tow grades. The shift is most visible across the Tennessee-Virginia manufacturing corridor where captive acetyl complexes serve integrated filter rod production.
United States Cellulose Acetate Market Segmentation
Cellulose acetate producers configure product specifications around acetyl content, degree of substitution, and plasticizer loadings to match end-use performance requirements. Segmentation reflects the tension between high-volume cigarette filter tow grades and specialty optical or pharmaceutical applications demanding tighter purity tolerances.
Product Type:
Standardization dominates high-volume tow production while specialty grades require customized acetyl content and plasticizer packages for niche optical and pharmaceutical applications.
- Films:Cast or extruded sheets with 39-44 percent acetyl content deliver optical clarity for LCD polarizer protection and food-contact packaging. Tennessee and Virginia converters are expanding offtake for display manufacturing and biodegradable packaging mandates.
- Fibers:Continuous filament tow with controlled denier and crimp configuration serves cigarette filter applications. Kingsport and Narrows facilities anchor domestic production capacity for this specification-driven segment.
- Plastics:Injection-molding and extrusion grades with butyrate modification enhance weather resistance for tool handles and automotive trim.
- Coatings:Solution-grade resins dissolved in acetone or MEK provide controlled-release barriers for pharmaceutical tablets.
Most installed capacity flows through Fibers. Expansion is steepest in Films.
End Use Industry:
Volume concentration in tobacco filtration contrasts with value capture in healthcare and specialty packaging where regulatory compliance commands premium positioning.
- Textiles:Filament yarn and staple fiber for apparel linings and industrial sewing thread. North Carolina textile mills specify cellulose acetate for moisture management and dyeability in performance garments.
- Packaging:Thermoformed trays and transparent windows for premium food and cosmetic presentation. California extended producer responsibility legislation is accelerating certified biodegradable film procurement.
- Healthcare:Dialysis membrane substrates and pharmaceutical tablet coatings requiring USP Class VI biocompatibility validation.
- Automotive:Interior trim components and steering wheel covers leveraging leather-like aesthetic and UV stability.
Textiles commands the largest volume commitment. Healthcare climbs the fastest on regulatory tailwinds.
Form:
Processing method determines form selection, with melt-processing favoring granules and solvent-based applications requiring solutions or powders.
- Granules:Pelletized resin for injection molding and extrusion of eyeglass frames, tool handles, and automotive components. Southeast compounders favor this form for consistent feed and colorability.
- Sheets:Calendered or cast film stock for thermoforming and die-cutting into packaging inserts and graphic overlays.
- Solutions:Dissolved resin in acetone or proprietary solvent blends for coating and spinning operations. Pharmaceutical coaters specify low-viscosity grades for spray application uniformity.
- Powders:Fine particle size for solvent slurry preparation and compression molding of precision optical components.
Granules absorb the majority of production throughput. Solutions gain share fastest in pharmaceutical outsourcing.
Application:
Functional performance requirements separate commodity filtration from specialty adhesive and coating applications where purity and consistency drive supplier selection.
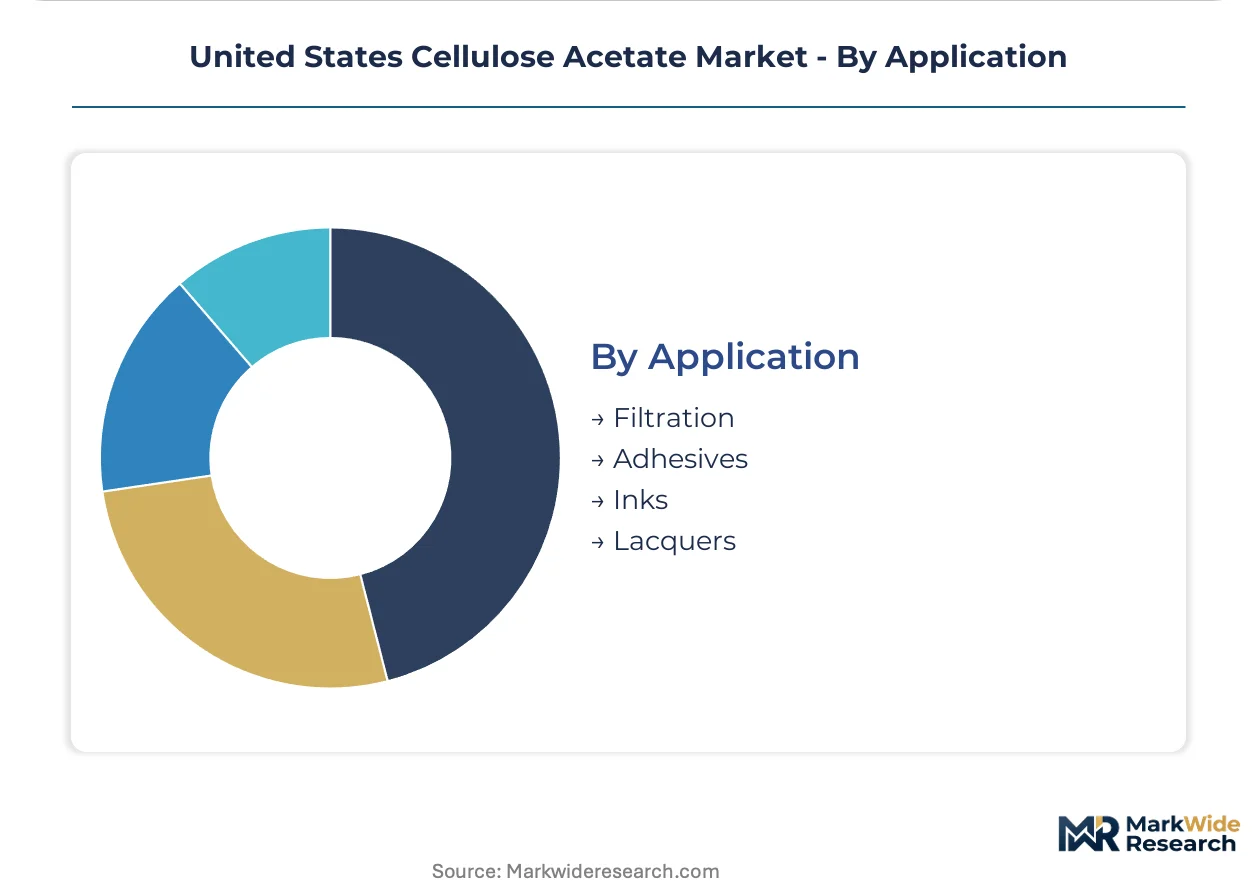
- Filtration:Cigarette filter tow and water purification membranes. EPA emissions standards at acetylation facilities directly impact cost structure for this dominant application.
- Adhesives:Solvent-borne systems for laminating and bonding where cellulose acetate provides tack and open time control.
- Inks:Flexographic and gravure vehicles for high-clarity printing on flexible packaging substrates.
- Lacquers:Protective and decorative coatings for eyeglass frames, automotive trim, and wood finishing where hardness and gloss retention matter.
Filtration anchors manufacturing scale. Inks expand most quickly on digital printing substrate convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic cellulose acetate production concentrates where acetylation facilities face lower retrofit costs under EPA emissions standards. Tennessee, Virginia, and North Carolina anchor capacity because existing infrastructure avoids the capital intensity of greenfield compliance in stricter jurisdictions.
Southeast Manufacturing Corridor
Cigarette filter tow demand from tobacco processors drives volume commitments across Tennessee and Virginia. EPA Toxic Substances Control Act enforcement targets acetylation emissions at Kingsport and Narrows facilities. Kingsport hosts integrated acetyl chain operations that supply captive raw materials to adjacent filter rod production.
Mid-Atlantic Chemical Belt
Specialty film converters in Virginia expand capacity for LCD polarizer protection and food-contact packaging applications. FDA food-contact notification pathways require comprehensive extractables testing that reshapes quality system investments. Research Triangle display manufacturers qualify cellulose acetate butyrate grades for foldable screen substrates.
Gulf Coast Feedstock Hub
Petrochemical capacity expansion near Houston shortens acetic acid supply chains for domestic acetyl inputs. OSHA workplace exposure limits for acetic acid vapor shape ventilation retrofitting decisions at aging production facilities. Corpus Christi methanol-carbon monoxide synthesis operations influence feedstock pricing dynamics for upstream cellulose acetate producers.
California Packaging Market
Extended producer responsibility legislation accelerates certified biodegradable film procurement from out-of-state suppliers. State mandates specify material specifications that cellulose acetate satisfies through inherent biodegradability. Los Angeles and San Francisco specialty converters trial the material for premium cosmetic and food presentation windows.
Midwest Industrial Corridor
Automotive interior trim specifications in Michigan and Ohio sustain demand for weather-resistant cellulose acetate butyrate grades. NHTSA material safety standards intersect with aesthetic requirements for steering wheel covers and dashboard components. Detroit-area compounders favor granule form for consistent feed and colorability in injection-molding operations.
United States Cellulose Acetate Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty optical and pharmaceutical grades where purity premiums offset smaller scale. The domestic market structures around three Tennessee-Virginia-North Carolina corridor facilities that anchor cigarette filter tow supply. Strategic archetypes include integrated petrochemical operators with captive acetyl chains, specialty film converters with FDA compliance capabilities, and regional compounders serving automotive and tool handle niches. Capacity expansion and regulatory compliance retrofitting dominate competitive moves as EPA emissions scrutiny intensifies.
Among integrated chemical producers, Eastman Chemical Company and Celanese Corporation exemplify the acetyl chain control archetype, while Daicel Corporation represents technology leadership in high-purity filtration grades. Eastman anchors its position through the Kingsport complex. Celanese maintains North American specialization in acetyl derivatives. Daicel competes via Japanese process expertise adapted to domestic pharmaceutical and optical specifications.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Celanese Corporation |
| Daicel Corporation |
| Rayonier Advanced Materials |
| Mitsubishi Chemical Holdings Corporation |
| Solvay |
| Sappi |
| Rotuba Extruders |
| Cerdia International GmbH |
| Others |
Cost & Logistics Intelligence
Captive acetyl chain integration at Kingsport and Narrows facilities anchors both supply security and pricing power for domestic cellulose acetate producers. Eastman Chemical Company's backward integration into acetic acid feedstock insulates margin pools from Gulf Coast petrochemical volatility while concentrating bargaining leverage against specialty film converters.
Pricing Analysis
Direct-to-OEM mill relationships displace distributor margins for high-volume cigarette filter tow grades. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial standard levels reflects FDA notification burden and acetyl content precision. Cost compression in industrial filtration tiers intensifies because polypropylene substitution erodes volume commitments. Tobacco filter manufacturers exhibit lowest price sensitivity; specialty pharmaceutical coaters face highest cost pressure from extractables testing requirements.
Supply Chain Analysis
Regional distribution centers in Memphis and Richmond serve hub-and-spoke patterns radiating toward Research Triangle display manufacturers and North Carolina textile mills. Domestic production draws from Tennessee, Virginia, and North Carolina acetylation facilities; acetic anhydride feedstock sources from Gulf Coast methanol-carbon monoxide synthesis operations. Single-source vulnerability concentrates at Kingsport for captive cellulose acetate supply to integrated filter rod production. Distribution runs through specialty chemical distributors for low-volume pharmaceutical and optical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose acetate functions as a late-cycle quality story where specification-driven procurement favors producers with FDA food-contact certification and EPA emissions compliance infrastructure. The demand-shift toward pharmaceutical-grade purity standards rewards quality system investments over commodity scale.
For Market Incumbents: Anchor Kingsport acetyl chain dominance through carbon capture retrofit completion ahead of EPA Toxic Substances Control Act enforcement deadlines. Consolidate specification control by acquiring Virginia specialty film converters with validated extractables testing capabilities. Polypropylene substitution in industrial air filtration threatens volume erosion; defend position through cellulose acetate butyrate modification for foldable display substrates.
For New Entrants and Emerging Players: Launch via pharmaceutical coating outsourcing partnerships with North Carolina dosage form manufacturers seeking USP Class VI validated suppliers. White-space targets include California extended producer responsibility compliance for biodegradable packaging films and Research Triangle foldable screen substrate qualification. The most penetrable segment is specialty ink vehicles for digital printing substrate convergence.
For Investors and Strategic Acquirers: Roll-up economics work for FDA-compliant specialty film converters because regulatory compliance creates customer switching costs that sustain margin premiums. Long-term viability centers on pharmaceutical and optical grade positioning rather than tobacco filtration commodity exposure. Watch California packaging mandate enforcement velocity as inflection indicator for certified biodegradable film demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid Feedstock | Gulf Coast petrochemical expansion shortens supply chains for domestic acetyl raw material inputs. |
| Carbon Capture Retrofit at Acetylation Facilities | EPA Toxic Substances Control Act enforcement forces emissions compliance investment at Kingsport and Narrows plants. |
| FDA Food-Contact Notification Pathway Investment | Extractables testing requirements reshape quality systems for Virginia specialty film converters. |
| Cellulose Acetate Butyrate Modification Development | Research Triangle display manufacturers qualify grades for foldable screen substrate applications. |
| Direct Mill Relationship Consolidation | Tobacco filter manufacturers displace multi-tier distribution for high-volume cigarette filter tow procurement. |
Research Approach
Coverage spans the Southeast manufacturing corridor, Mid-Atlantic chemical belt, and California packaging market, with primary inputs from each. The study combines interviews with plant managers at acetylation facilities, procurement leads at tobacco filter manufacturers, pharmaceutical coating specialists, and specialty film converters with secondary validation. Sources include EPA emissions filings, FDA food-contact notifications, SEC 10-K disclosures from integrated chemical producers, and American Chemistry Council sector reports. Bottom-up volume modeling triangulates against top-down acetyl chain capacity assessments.
Rate-of-change decomposition separates volume drivers by product type, end-use industry, and form specifications across the projection horizon. Segmentation dimensions modeled include acetyl content grade, plasticizer loading, FDA compliance tier, and regional production hub. CAGRs derive from installed capacity utilization trends and substitution elasticity estimates. Forecast inputs incorporate EPA regulatory timeline assumptions and California extended producer responsibility implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated polypropylene substitution or delayed carbon capture retrofit completion. Forecasts reflect assumptions about acetic anhydride feedstock pricing stability and tobacco consumption trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Potassium Benzoate Market