
 Fungal Staining Reagent Market | 2026-2036
Fungal Staining Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Staining Reagent Market Foresight
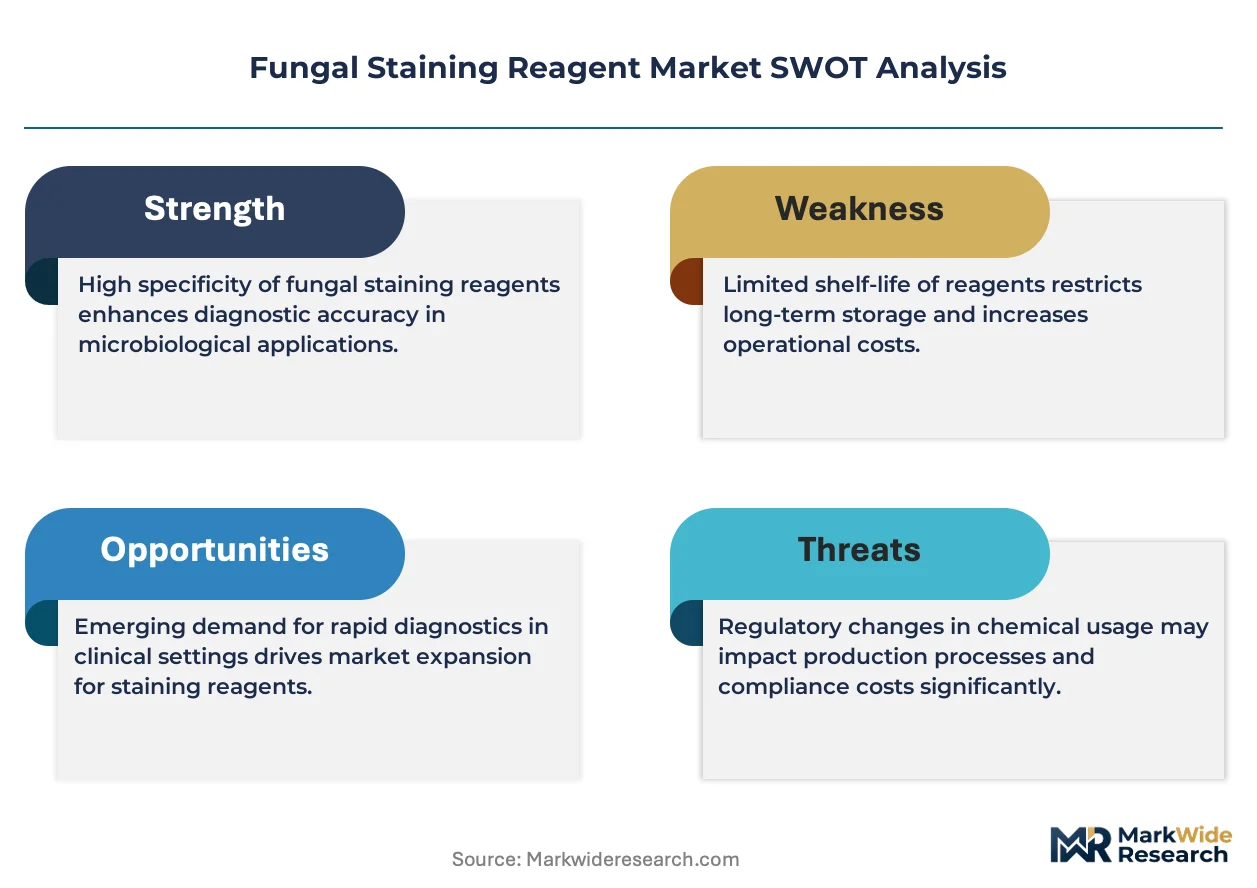
EU MDR is restructuring the cost-of-entry calculus for fungal staining reagent manufacturers seeking CE-marked distribution across European diagnostic laboratories. Thermo Fisher Scientific leverages its broad life sciences distribution network to sustain shelf presence in regulated markets. HiMedia Laboratories anchors its position through specialized microbial media and stain formulations tailored to emerging market price points. Abcam plc differentiates via antibody-centric reagent portfolios that extend into immunohistochemistry-adjacent workflows.
Fungal staining reagents comprise dye-based chemical formulations designed to bind chitin-rich cell walls or specific polysaccharide structures, enabling microscopic visualization of fungal elements in tissue sections or culture specimens. Periodic acid-Schiff and methenamine silver formulations require precise oxidation-reduction chemistry to stain fungal carbohydrates with diagnostic clarity. Ready-to-use liquid kits command premium positioning in histopathology workflows where standardization reduces inter-laboratory variability. Powdered stains retain cost advantages in high-volume research settings where on-site reconstitution fits budget constraints. Diagnostic laboratories represent the dominant end-user channel, absorbing volume through centralized procurement contracts that favor suppliers with broad reagent menus.
FDA quality system regulations and EU MDR technical documentation requirements shape product development timelines and post-market surveillance obligations for reagent manufacturers. ISO 13485 certification serves as a baseline credential for suppliers targeting regulated clinical markets across both jurisdictions. Stakeholders must monitor evolving harmonization gaps between FDA in vitro diagnostic guidance and EU MDR performance evaluation standards as dual-market registration strategies face divergent evidentiary demands.
Market Dynamics
EU MDR technical documentation mandates are compressing product development timelines while simultaneously fragmenting supplier access across European diagnostic networks, forcing reagent manufacturers to rebuild quality management systems from substrate sourcing through post-market surveillance.
Growth Catalysts
- EU MDR Performance Evaluation Standards:Tightened CE-marking requirements for in vitro diagnostic reagents are consolidating procurement toward ISO 13485-certified suppliers with established notified body relationships, accelerating replacement of legacy stain formulations.
- Histopathology Workflow Automation:Integrated slide staining platforms in hospital-based laboratories are standardizing reagent consumption patterns and locking in volume commitments to kit-format suppliers.
- Chitin-Binding Fluorophore Advances:Novel synthetic dye chemistry targeting fungal cell wall polysaccharides is expanding diagnostic specificity beyond traditional Periodic acid-Schiff and methenamine silver methods.
Market Restraints
- Phenol and Chromium Salt Input Volatility:Bulk chemical precursors for oxidative staining reactions face price instability tied to industrial supply chain disruptions and environmental handling restrictions.
- Notified Body Capacity Bottleneck:EU MDR designation delays for conformity assessment organizations are extending time-to-market for reformulated reagents by 12-18 months.
- Molecular Diagnostic Substitution:PCR and MALDI-TOF-based fungal identification platforms are displacing morphology-dependent staining in tertiary care reference laboratories.
Strategic Opportunities
- India Central Drugs Standard Control Organization Streamlining:CDSCO's phased implementation of medical device rules creates first-mover positioning for reagent kit manufacturers establishing local technical file repositories.
- Point-of-Care Mycology Testing:Dermatology clinics and urgent care networks are adopting rapid staining protocols for on-site superficial fungal infection confirmation.
- Digital Pathology Integration:Whole-slide imaging platforms require standardized, batch-consistent reagent formulations to enable algorithmic fungal element detection.
Industry Challenges
- ISO 13485 Auditor Scarcity:Qualified quality management system assessors with specific in vitro diagnostic reagent experience command premium consulting rates, delaying certification readiness.
- Legacy Stain Inventory Amortization:High-volume hospital laboratories face capital efficiency pressure from partially depleted bulk powder stockpiles incompatible with automated platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Staining Reagent Market |
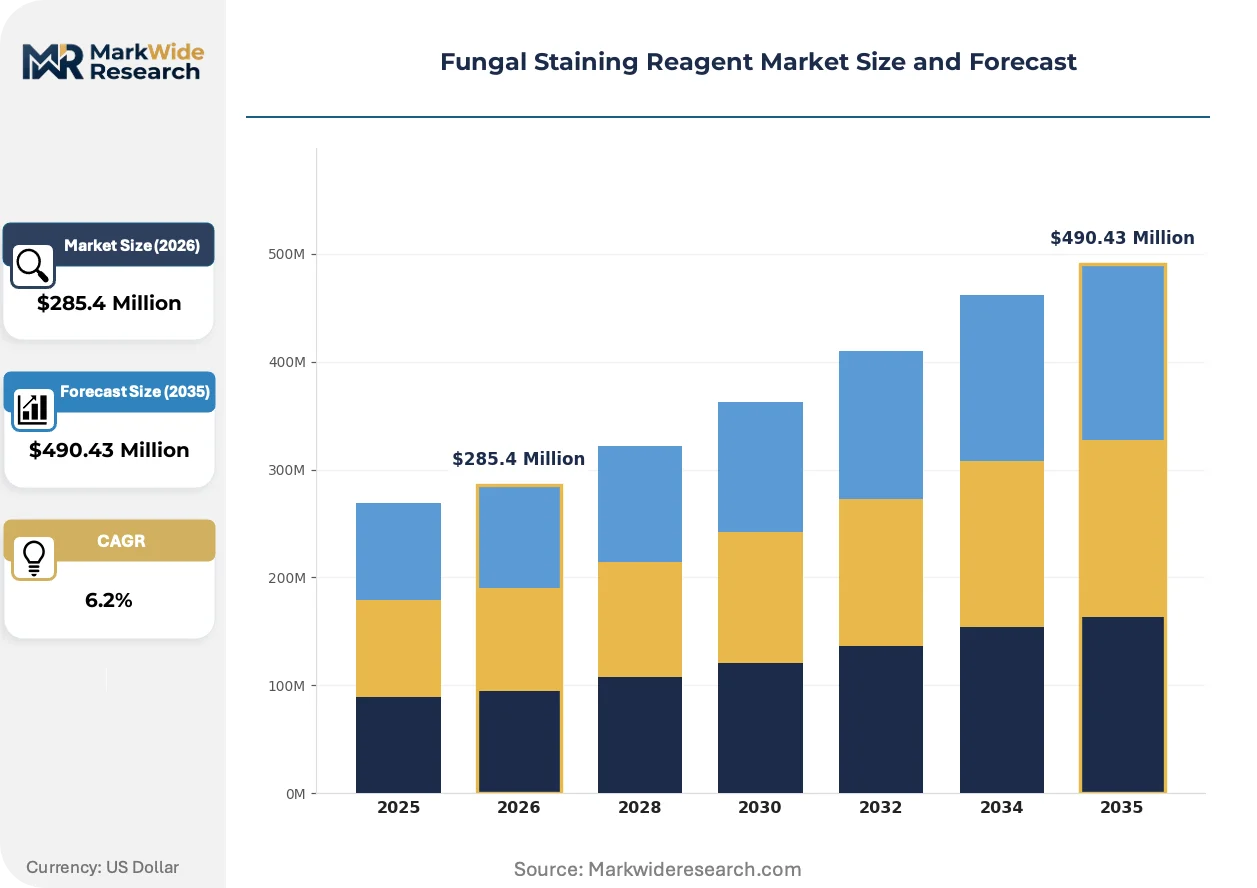
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactophenol Cotton Blue, Calcofluor White, Periodic Acid Schiff, Methenamine Silver, Toluidine Blue Application: Histopathology, Microbial Identification, Parasitology, Mycology Research, Clinical Diagnostics End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Academic Institutions, Biotechnology Firms Delivery Mode: Liquid Stains, Powdered Stains, Ready-to-Use Kits, Pre-mixed Solutions, Lyophilized Powders |
| Companies Covered | Becton, Dickinson and Company, HiMedia Laboratories, Thermo Fisher Scientific, Hardy Diagnostics, Agilent Technologies, Merck KGaA, Abcam plc, Biocare Medical, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Staining Reagent Market Shifts & Advancements
Reagent formulation science is converging with digital pathology infrastructure requirements, compressing the acceptable variability window for staining intensity and creating new specification tiers for instrument-compatible products.
Lyophilized reagent bead technology is modularizing quality control workflows by enabling single-test-unit packaging with embedded reference standards. Reference laboratories in Germany and the United States are piloting these formats for sporadic fungal isolate confirmation. The technology is modularizing supplier-customer relationships around just-in-time inventory rather than bulk procurement cycles.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence packages for even legacy stain formulations previously grandfathered under the Medical Devices Directive. Reagent manufacturers must now generate analytical and clinical validation data for products with decades of unchallenged use. Powdered stain categories face disproportionate documentation burden due to on-site reconstitution variability.
Centralized procurement consortia among North American hospital networks are consolidating vendor panels and unbundling reagent purchasing from instrument maintenance contracts. Group purchasing organizations now negotiate multi-year sole-source agreements for ready-to-use kit formats. This concentration is most visible in integrated delivery networks spanning multiple states with standardized laboratory information systems.
Fungal Staining Reagent Market Segmentation
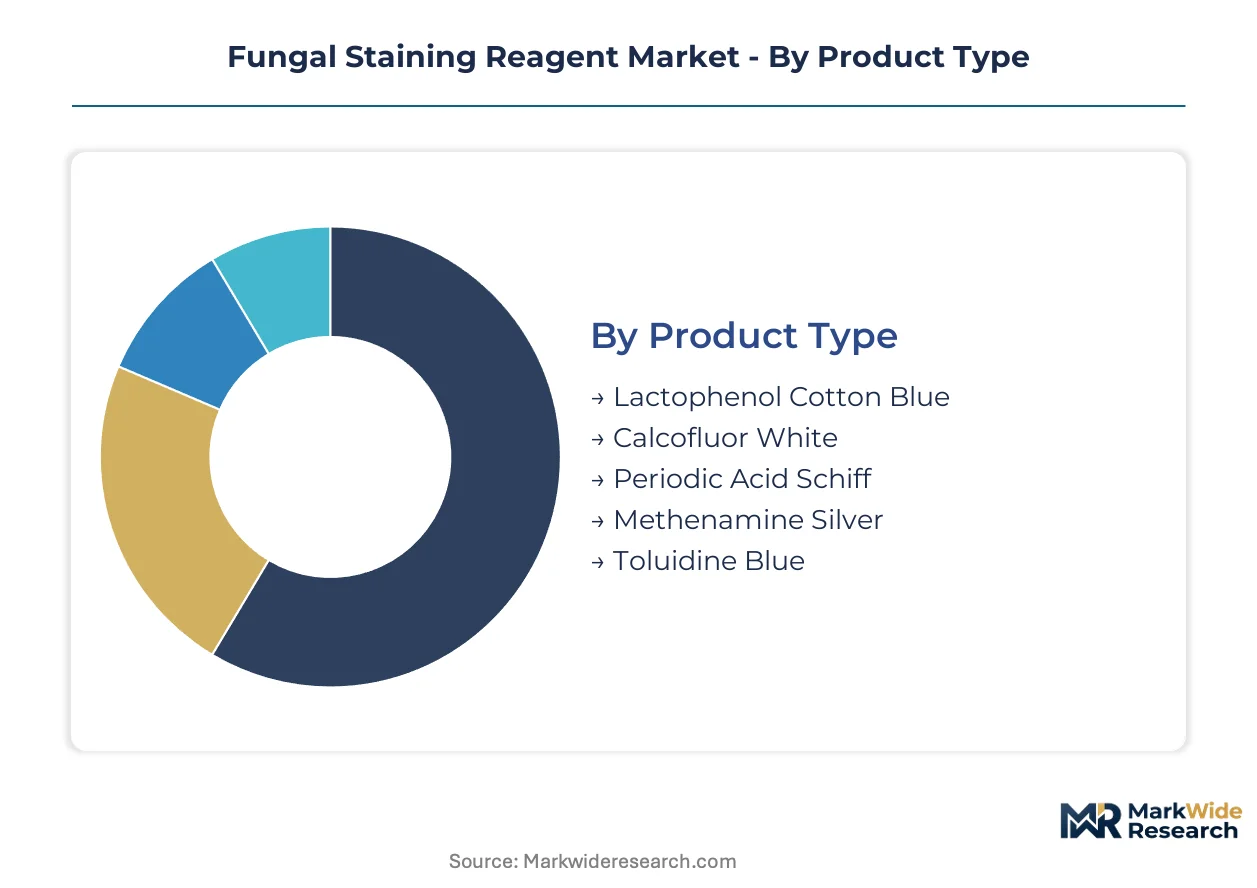
Product formulation chemistry and delivery format specifications dictate procurement patterns across diagnostic workflows. Staining reagent manufacturers align R&D investment with the technical requirements of automated platforms versus manual microscopy environments.
Product Type:
Carbohydrate-binding specificity and oxidation-reduction chemistry define performance hierarchies in fungal cell wall visualization.
- Periodic Acid Schiff:Oxidizes fungal glycoproteins to generate magenta aldehyde complexes with diagnostic clarity in tissue sections. Demand concentrates in US hospital pathology departments amid digital whole-slide imaging standardization requiring batch-consistent staining intensity.
- Methenamine Silver:Deposits black metallic silver onto fungal cell walls through chromic acid oxidation, offering superior contrast in necrotic tissue. German reference laboratories specify Grocott-modified formulations under tightened EU MDR analytical validation requirements for invasive fungal infection confirmation.
- Lactophenol Cotton Blue:Phenol-preserved lactose medium with aniline blue dye for rapid mountant preparation in culture-based identification.
- Calcofluor White:Fluorescent chitin-binding benzoxazole dye requiring UV microscopy infrastructure.
- Toluidine Blue:Thiazine dye for polychromatic fungal element visualization in semithin resin sections.
Periodic Acid Schiff leads on scale; Methenamine Silver leads on momentum.
Application:
Workflow automation intensity varies sharply across diagnostic disciplines, fragmenting reagent specification requirements.
- Histopathology:Tissue section staining for formalin-fixed paraffin-embedded specimens demands precisely controlled reagent pH and molarity. North American integrated delivery networks lock in multi-year kit-format contracts with vendors holding FDA 510(k) clearance for companion diagnostic workflows.
- Clinical Diagnostics:Direct specimen examination from sterile sites requires rapid turnaround staining protocols. India's CDSCO streamlined medical device registration is attracting kit manufacturers to establish technical file repositories for import substitution.
- Microbial Identification:Culture-based morphological confirmation in reference laboratories.
- Parasitology:Co-detection staining for ova and parasite screening in tropical medicine settings.
- Mycology Research:Experimental staining for novel antifungal compound screening in academic settings.
Histopathology commands volume concentration; Clinical Diagnostics shows the steepest expansion trajectory.
End User:
Capital deployment cycles and regulatory sophistication create distinct purchasing authority patterns across customer types.
- Diagnostic Laboratories:Centralized procurement contracts favor suppliers with broad reagent menus and ISO 13485 certification. Germany's expanding mycology testing panels under EU MDR quality mandates are consolidating vendor relationships toward notified body-audited manufacturers.
- Research Institutes:Grant-funded experimental workflows prioritize powdered stain flexibility over kit standardization. Budget constraints in emerging market facilities sustain demand for bulk phenol and chromium salt formulations despite handling complexity.
- Pharmaceutical Companies:GMP-compliant reagent qualification for antifungal drug development.
- Academic Institutions:Teaching laboratory consumption of entry-tier staining materials.
- Biotechnology Firms:Specialized staining for fungal expression system validation.
Diagnostic Laboratories anchor procurement volume; Research Institutes offer margin expansion through premium fluorophore adoption.
Delivery Mode:
Supply chain configuration and shelf-life stability determine geographic reach and customer access economics.
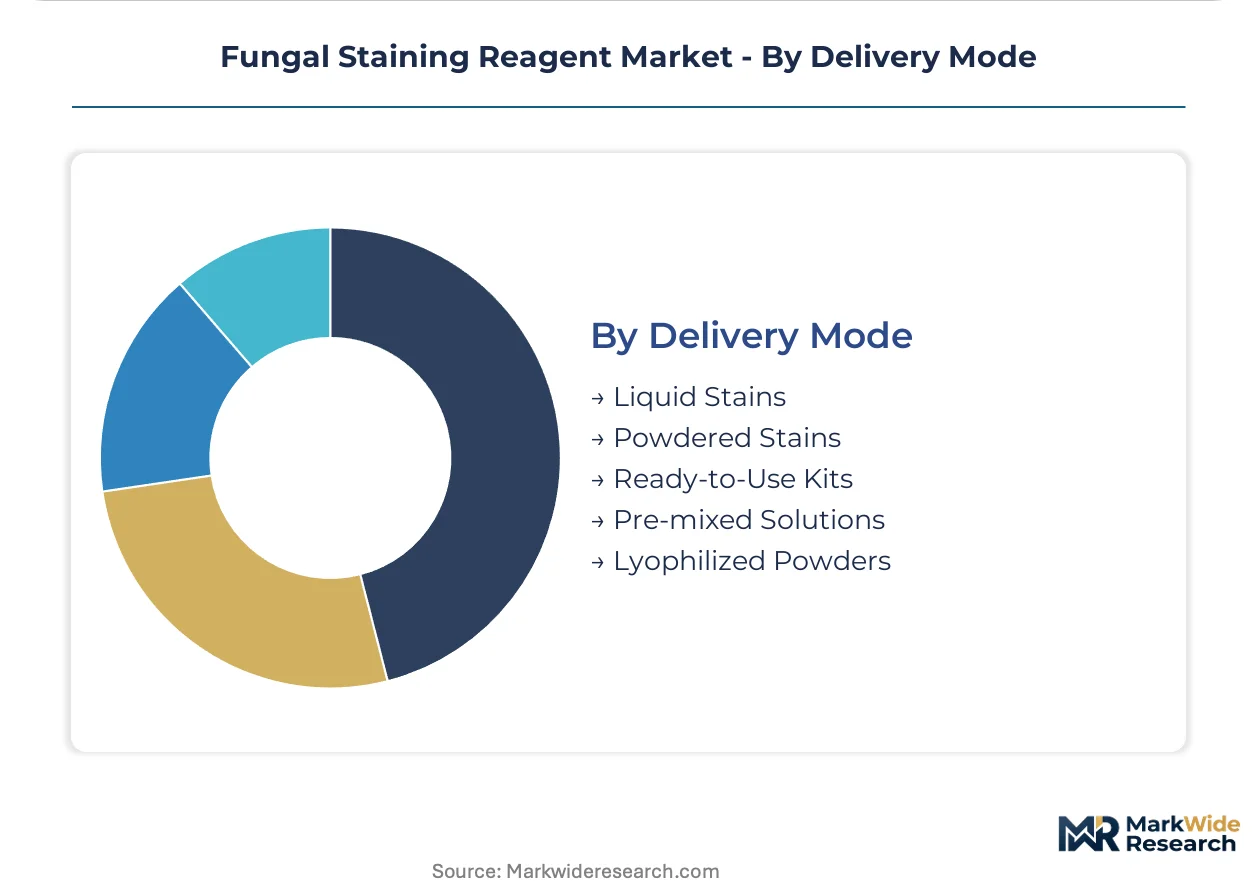
- Ready-to-Use Kits:Pre-formulated liquid reagents in instrument-compatible cartridges eliminate on-site reconstitution variability. US hospital networks standardizing on integrated slide staining platforms are locking in sole-source agreements with kit-format suppliers.
- Lyophilized Powders:Single-test-unit bead technology with embedded reference standards enables just-in-time inventory for sporadic testing. German and US reference laboratories pilot these formats for fungal isolate confirmation with reduced cold chain burden.
- Liquid Stains:Bulk container formats for high-throughput manual staining workflows.
- Powdered Stains:Cost-optimized formats for research settings with on-site reconstitution capability.
- Pre-mixed Solutions:Intermediate convenience tier for mid-volume laboratories.
Ready-to-Use Kits dominate revenue capture; Lyophilized Powders are gaining share fastest through digital pathology integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Histopathology specialists cluster in Germany's Ruhr industrial belt and the US Northeast corridor, anchoring demand for standardized staining protocols. These workforce concentrations shape procurement patterns across diagnostic networks.
United States
Integrated delivery networks spanning Massachusetts to Pennsylvania standardize on FDA-cleared kit formats for companion diagnostic workflows. The FDA's 510(k) pathway for in vitro diagnostic reagents compresses time-to-market for reformulated stains. Philadelphia's medical research corridor drives adoption of automated slide staining platforms requiring batch-consistent reagent specifications.
Germany
Reference laboratories in Munich and Heidelberg expand mycology testing panels under tightened EU MDR quality mandates. The EU MDR Annex I general safety requirements now demand clinical evidence packages for legacy stain formulations previously grandfathered under prior directives. Bavaria's diagnostic manufacturing cluster concentrates notified body-audited suppliers serving centralized hospital procurement consortia.
India
CDSCO's phased medical device rules implementation attracts kit manufacturers establishing local technical file repositories for import substitution. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune hosts emerging reagent formulators targeting price-sensitive diagnostic segments. The central drugs regulator streamlines registration pathways for pre-mixed staining solutions.
China
Domestic histopathology automation drives standardization of reagent consumption in Beijing and Shanghai hospital networks. NMPA's in vitro diagnostic reagent classification rules shape product development timelines for carbohydrate-binding formulations. The Yangtze River Delta manufacturing corridor concentrates suppliers of phenol and chromium salt precursors for oxidative staining chemistry.
Japan
PMDA's quality management system requirements for in vitro diagnostics sustain premium positioning for instrument-compatible reagent cartridges. Tokyo and Osaka metropolitan areas anchor demand from aging-population healthcare infrastructure requiring high-throughput fungal diagnostics. METI's industrial standards framework governs fluorophore purity specifications for research-grade applications.
Fungal Staining Reagent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across reagent formulation tiers, creating a bifurcated supply structure. The market consolidates around suppliers holding dual FDA and ISO 13485 credentials while fragmenting at the research-grade powder segment. Three archetypes dominate: life sciences conglomerates with distribution breadth, regional chemical specialists with cost-optimized formulations, and antibody-centric developers extending into immunohistochemistry-adjacent workflows. Competitive intensity centers on notified body relationship depth and automated platform compatibility certification.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven archetypes with broad reagent menus spanning regulated clinical markets. HiMedia Laboratories occupies a focused specialist position with microbial media and stain formulations tailored to emerging market price points. Abcam plc represents the antibody-centric developer archetype extending reagent portfolios into adjacent diagnostic workflows. These three company types illustrate how credential depth, geographic focus, and technology origin shape competitive positioning without requiring specific strategic action claims.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| HiMedia Laboratories |
| Thermo Fisher Scientific |
| Hardy Diagnostics |
| Agilent Technologies |
| Merck KGaA |
| Abcam plc |
| Biocare Medical |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
EU MDR Annex I clinical evidence requirements now gate qualified supply access for fungal staining reagent manufacturers while simultaneously compressing margin structures for legacy formulations lacking notified body certification. Environmental handling restrictions on phenol and chromium salt precursors further stratify supplier tiers, with ISO 13485-audited manufacturers commanding premium positioning against uncertified competitors frozen out of hospital procurement contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates instrument-compatible kit formats from standalone reagent procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and automation compatibility. Pricing pressure stems from centralized procurement consortia unbundling reagent purchasing from maintenance contracts. Research institutes exhibit highest price sensitivity due to grant-funded budget constraints, while integrated delivery networks prioritize standardization over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from North American hospital networks mandate multi-supplier qualification for phenol derivatives and chromic acid precursors. Manufacturing concentrates in Germany, China, and the United States for oxidative staining chemistry. Supply chain risk centers on single-source vulnerability for specialty fluorophore intermediates. Distribution runs through life sciences distributors holding cold chain capabilities for liquid kit formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fungal staining reagent market functions as a regulatory compounder where EU MDR implementation generates replacement demand for grandfathered stain formulations lacking clinical evidence packages.
For Market Incumbents: Lock in automated platform compatibility certifications with integrated slide staining manufacturers to defend against molecular diagnostic substitution threats. Deepen backward integration into phenol and chromium salt precursor supply to offset raw material volatility. Prioritize notified body relationship investment to compress CE-marking timelines for reformulated products. For New Entrants and Emerging Players: Enter via India's CDSCO streamlined registration pathway for pre-mixed staining solutions targeting price-sensitive diagnostic segments. Capture white-space in point-of-care mycology testing for dermatology clinics requiring rapid staining protocols. Pursue lyophilized bead technology partnerships with reference laboratories piloting just-in-time inventory models. For Investors and Strategic Acquirers: Roll-up economics work for regional chemical specialists with cost-optimized formulations because EU MDR compliance costs are consolidating procurement toward scaled manufacturers with quality management infrastructure. Target acquisition profiles emphasizing ISO 13485 certification depth and automated platform compatibility. Monitor notified body capacity expansion as the signal indicating inflection in time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Investment | EU MDR designation delays extend reformulation timelines by 12-18 months for manufacturers lacking established auditor access. |
| Automated Platform Compatibility Certification | Integrated slide staining manufacturers in the US Northeast lock in sole-source kit format agreements with certified suppliers. |
| Lyophilized Reagent Bead Development | Single-test-unit packaging with embedded reference standards enables digital pathology algorithmic detection standardization. |
| Backward Integration into Precursor Supply | Phenol and chromium salt input volatility compresses margins for manufacturers without captive chemical sourcing. |
| CDSCO Technical File Repository Establishment | India's phased medical device rules create first-mover positioning for import substitution in Maharashtra's diagnostic belt. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with histopathology laboratory directors, diagnostic procurement managers, reagent formulation scientists, and notified body auditors informed demand-side and supply-side dynamics. Secondary sources included FDA 510(k) filings, EU MDR technical documentation databases, CDSCO registration records, and customs trade data for phenol derivative imports. Bottom-up and top-down triangulation anchored volume and value estimates.
Granularity-level modeling addressed product type chemistry, application workflow intensity, end-user capital deployment cycles, and delivery mode supply chain configuration across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating regulatory milestone timing and automation adoption curves. Forecast inputs incorporated EU MDR implementation phasing, digital pathology platform deployment rates, and molecular diagnostic substitution velocity in tertiary care settings.
Inputs from regulatory filing databases and hospital procurement contract disclosures were available through the study window; gaps in real-time notified body audit queue data introduce uncertainty bands around time-to-market assumptions for reformulated reagents. Deviation in EU MDR designation timelines for conformity assessment organizations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Penicillin Intermediate Market