
 Global Textile Finishing Chemicals Market | 2026-2036
Global Textile Finishing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Finishing Chemicals Market Intelligence
The end-use mix for textile finishing chemicals is shifting as demand from technical textiles overtakes traditional apparel applications in value. This change favors suppliers with strong R&D in specialized formulations for automotive and protective clothing. BASF SE leverages its extensive chemical portfolio to serve these high-performance segments. Huntsman International LLC competes on the strength of its specialized dyes and finishing effects, while Archroma differentiates through its focus on sustainable and water-saving solutions.
Textile finishing chemicals are formulations applied to fabrics post-weaving or knitting to impart specific functional properties. These treatments, such as applying a cross-linking agent, enhance characteristics like wrinkle resistance, flame retardancy, or water repellency. Within chemical types, demand for anti-microbial agents and flame retardants is strong, driven by technical textile requirements. Softeners remain a high-volume, mature category primarily used for cotton and polyester fabrics in the apparel and home textiles industries.
Regulatory frameworks like Europe's REACH and the US EPA's chemical safety rules heavily influence formulation development, pushing for lower volatile organic compounds. In Asia, compliance with standards such as China's GB standards and OEKO-TEX certification is essential for market access. The critical decision for chemical manufacturers now involves balancing the cost of developing compliant, bio-based alternatives against the performance demands of industrial end-users.
Market Dynamics
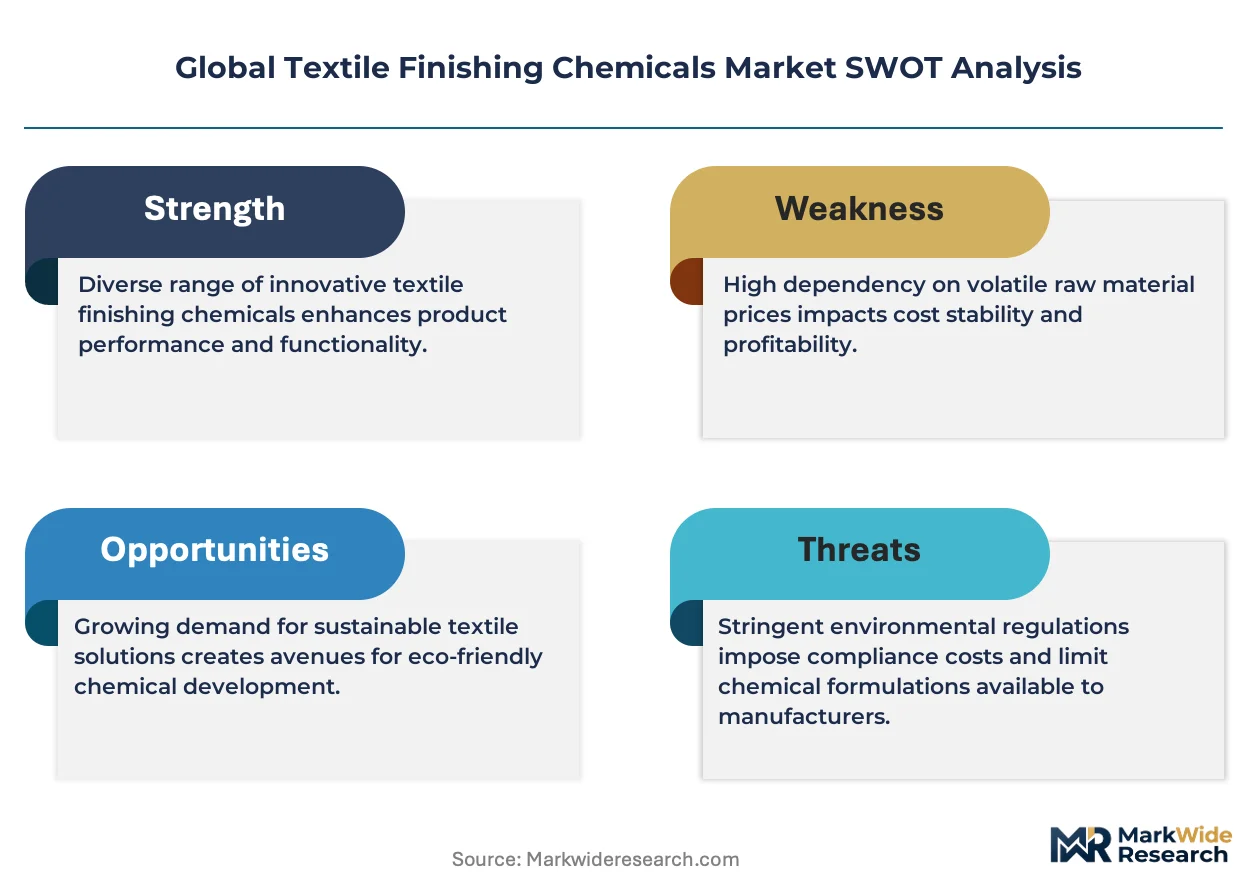
The market's central dynamic is the tension between performance requirements from technical textiles and the simultaneous push for sustainable, bio-based formulations mandated by regulations like REACH, forcing a trade-off between function, compliance, and cost.
Growth Catalysts
- Bio-based Chemistry:The development of finishing agents derived from renewable sources like plant oils and starches establishes new benchmarks for sustainability, attracting apparel brands.
- Technical Textile Growth:Rising consumption in automotive interiors and medical nonwovens creates specific demand for high-performance flame retardants and anti-microbial agents.
- Manufacturing Consolidation:Demand concentrates in textile production centers such as Vietnam and Bangladesh, streamlining supply chains for chemical formulators targeting high-volume factories.
Market Restraints
- Input Cost Volatility:Fluctuation in the price of petrochemical feedstocks, the primary inputs for many conventional finishes, creates margin pressure and pricing uncertainty for manufacturers.
- Regulatory Burden:The high cost and extended timelines for developing and registering new chemicals under frameworks like the EPA's TSCA create barriers to innovation.
- Substitution Risk:Non-chemical finishing technologies, such as plasma surface treatment and enzymatic processes, present a viable, water-saving alternative for certain functional effects.
Strategic Opportunities
- Smart Textiles:A niche exists for developing formulations that can encapsulate or bond with electronic components and conductive yarns for use in wearable technology.
- Multifunctional Formulations:Creating single-application treatments that combine properties like water repellency and UV protection offers efficiency gains for fabric mills producing performance apparel.
- Circular Economy Integration:Designing finishing chemicals that do not hinder the end-of-life recyclability of polyester or cotton fibers aligns with brand-level circularity goals.
Industry Challenges
- Cross-Border Compliance:Managing a portfolio of products to meet disparate chemical safety regulations, such as China's GB standards and Europe's REACH, is operationally complex.
- R&D Capital Intensity:Significant capital investment is required to equip laboratories for testing new bio-based alternatives against industry performance standards before commercialization.
- Formulation Expertise Scarcity:A talent gap exists for chemical engineers who possess dual expertise in both advanced polymer science and sustainable green chemistry principles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Finishing Chemicals Market |
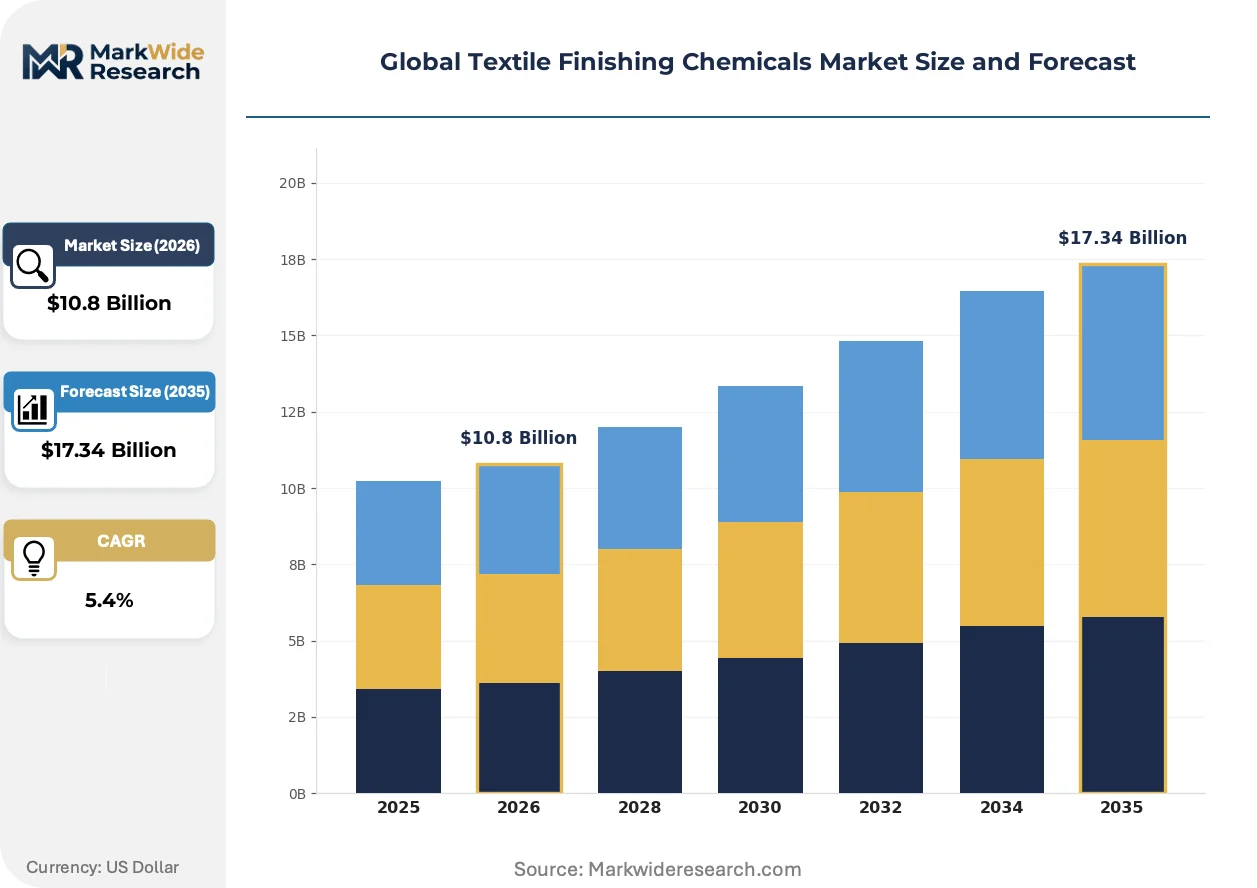
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chemical Type: Water Repellents, Softeners, Anti-Microbial Agents, Flame Retardants, Anti-Static Agents Finish Type: Mechanical, Chemical, Resin, Enzymatic, Bio-Based Fabric Type: Cotton, Polyester, Nylon, Wool, Silk End Use Industry: Apparel Manufacturers, Home Textiles, Technical Textiles, Automotive Upholstery, Sportswear |
| Companies Covered | BASF SE, Huntsman International LLC, Archroma, Dow Inc., DyStar Group, Evonik Industries AG, Wacker Chemie AG, Solvay S.A., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Finishing Chemicals Market Strategic Shifts & Innovations
Innovation in the textile finishing chemicals market is pivoting from volume-driven commodities to value-added specialties. This shift reflects a deeper industry re-evaluation of material performance, environmental impact, and manufacturing efficiency across the supply chain.
Digital finishing technology, using inkjet-style precision application, enables targeted chemical treatments on fabric surfaces. Technical textile producers and rapid-prototyping labs are adopting this method to reduce waste and accelerate development cycles. This digital process is absorbing the functions of separate, water-intensive padding baths, compressing overall production timelines and resource consumption.
Europe's REACH regulation is enforcing stricter controls on per- and polyfluoroalkyl substances (PFAS), which are foundational to many durable water repellent finishes. This directly impacts the performance outerwear and protective clothing sectors. Chemical suppliers must invest heavily in R&D for effective, commercially viable PFAS-free alternatives to maintain market access.
Brand-level procurement is moving away from specifying chemical recipes and toward demanding certified functional outcomes. Apparel and home goods companies now mandate proof of compliance with standards like OEKO-TEX or bluesign as a non-negotiable purchasing criterion. This change is most visible in textile exports from manufacturing hubs in Asia to Western consumer markets.
Global Textile Finishing Chemicals Market Segmentation
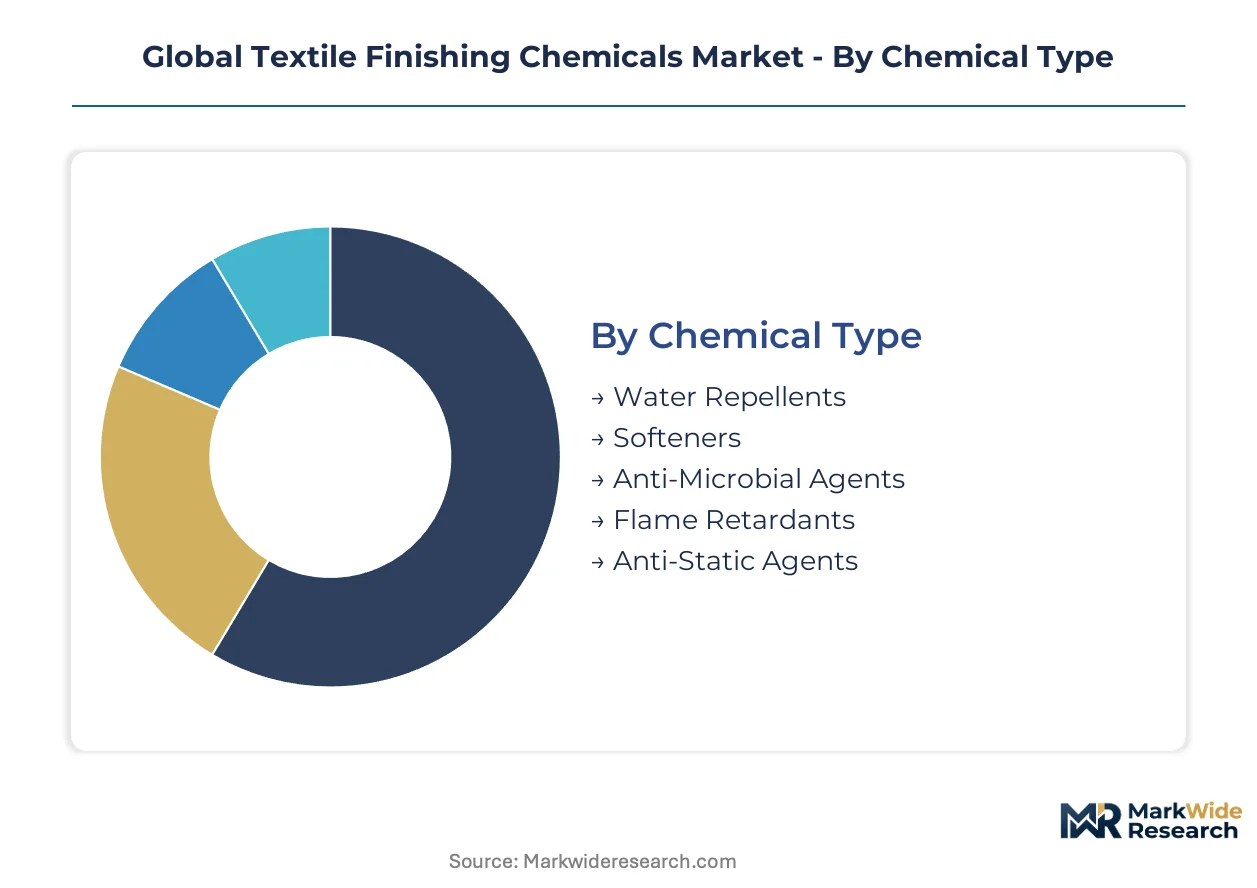
Market segmentation provides a granular view of the diverse requirements and opportunities within the textile finishing chemicals sector. Understanding these distinct segments enables manufacturers to tailor formulations, optimize production, and align with specific end-user demands across various applications and material types.
Chemical Type:
Supply concentration for textile finishing chemicals heavily influences the availability and pricing of specific chemical types, impacting formulation choices for fabric mills.
- Water Repellents:These chemicals create a hydrophobic surface on fabrics, preventing water penetration. Demand for durable water repellent (DWR) finishes is strong in performance outerwear and protective clothing, particularly with the shift towards PFAS-free alternatives in Europe.
- Softeners:Applied to fabrics to enhance hand feel, reduce friction, and improve drape. This high-volume, mature category remains essential for cotton and polyester blends across apparel and home textiles, improving comfort and processing efficiency.
- Anti-Microbial Agents:These treatments inhibit the growth of bacteria, fungi, and other microorganisms on textiles, crucial for hygiene and odor control. Technical textile requirements in medical nonwovens and sportswear drive significant demand for effective anti-microbial solutions.
- Flame Retardants:Formulations that impart fire resistance to textiles, slowing ignition and spread of flames. Automotive upholstery and protective clothing sectors require robust flame retardants to meet stringent safety standards.
- Anti-Static Agents:Chemicals that reduce static electricity build-up on synthetic fibers, improving comfort and preventing dust attraction.
Today's leader: Softeners. Tomorrow's challenger: Anti-Microbial Agents.
Finish Type:
Different finish types cater to distinct application needs, from aesthetic enhancements to critical performance attributes, influencing the choice of chemical and process.
- Mechanical:Physical processes like calendering or napping alter fabric surface properties, enhancing texture or luster without chemical application.
- Chemical:These finishes involve the application of chemical formulations to impart specific functional properties like wrinkle resistance or water repellency. The versatility of chemical finishes makes them a cornerstone of modern textile processing for diverse performance requirements.
- Resin:Often used for wrinkle resistance and dimensional stability, resin finishes involve cross-linking agents that bond with cellulose fibers. These treatments are common in cotton-based apparel, requiring careful formulation to balance performance and fabric integrity.
- Enzymatic:Bio-catalytic processes using enzymes to modify fabric surfaces, often for desizing, biopolishing, or denim washing. This eco-friendly approach reduces harsh chemical use and water consumption.
- Bio-Based:Finishes derived from renewable biological sources like plant oils, starches, or natural polymers. These innovative solutions establish new sustainability benchmarks, attracting apparel brands seeking reduced environmental impact and consumer appeal.
Demand for Chemical finishes drives current volume, while Bio-Based finishes are gaining share fastest.
Fabric Type:
Customer requirements often dictate the fabric type chosen for finishing, influencing chemical selection and treatment processes to achieve desired properties.
- Cotton:A natural cellulosic fiber widely used in apparel and home textiles, requiring finishes for wrinkle resistance, softening, and moisture management. Cotton fabrics absorb chemicals readily, influencing formulation and application methods.
- Polyester:A synthetic fiber known for durability and wrinkle resistance, often requiring finishes for anti-static properties, moisture wicking, and flame retardancy. Its hydrophobic nature demands specialized finishing chemistries for effective treatment.
- Nylon:A strong, synthetic polyamide fiber used in sportswear, hosiery, and industrial textiles, often treated for water repellency, UV protection, and anti-microbial effects.
- Wool:A natural protein fiber valued for warmth and resilience, requiring finishes for shrink resistance, mothproofing, and enhanced softness.
- Silk:A luxurious natural protein fiber, often finished to enhance drape, luster, and hand feel, while also requiring care in chemical selection due to its delicate nature.
The market prioritizes solutions for Cotton fabrics, with Polyester gaining traction for performance applications.
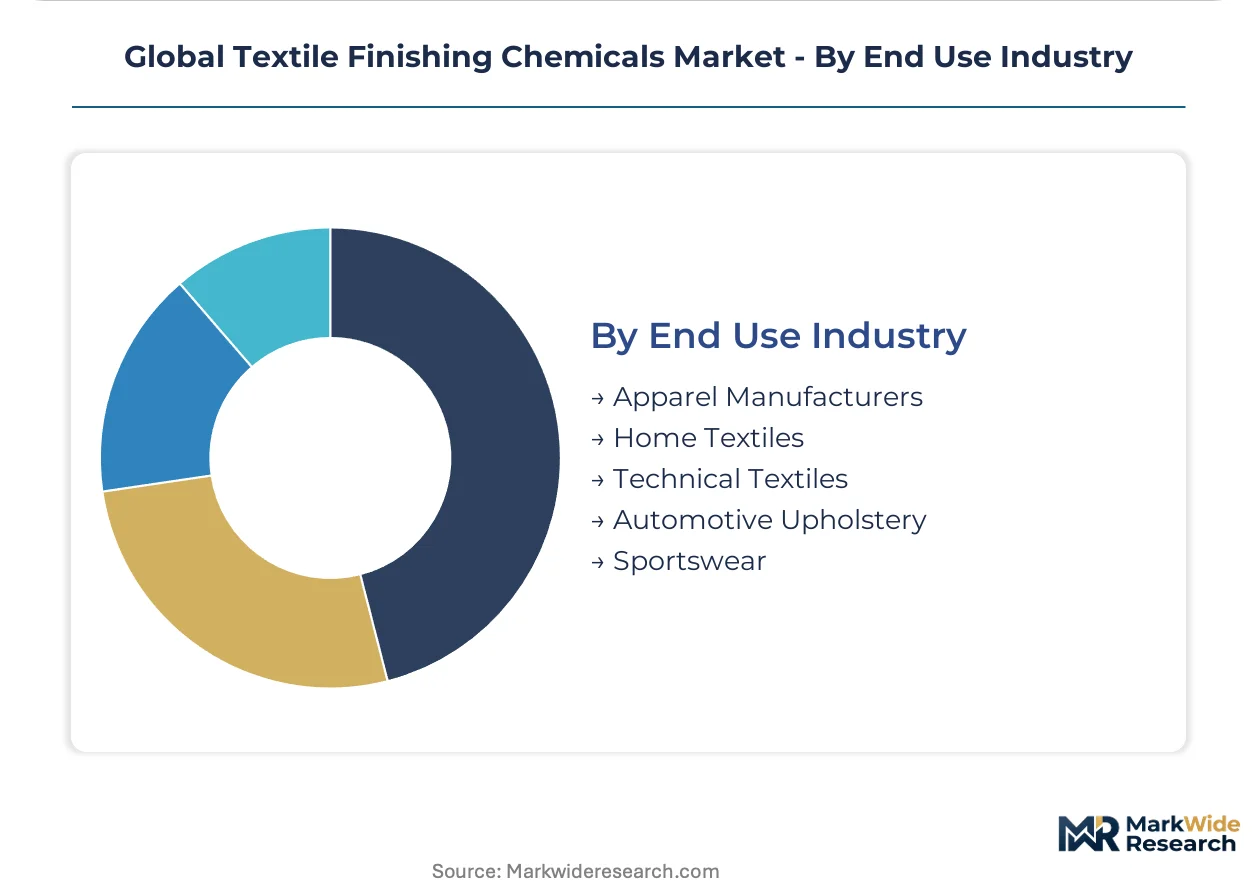
End Use Industry:
Margin potential varies significantly across end-use industries, driving chemical manufacturers to prioritize high-value segments with specialized functional needs.
- Apparel Manufacturers:This segment encompasses a broad range of clothing items, from everyday wear to fashion garments, requiring finishes for aesthetics, comfort, and basic performance. High-volume production in Vietnam and Bangladesh drives consistent demand for cost-effective solutions.
- Home Textiles:Products like bedding, towels, and upholstery fall into this category, demanding finishes for softness, durability, stain resistance, and fire safety. Consumer preferences for comfort and longevity influence finishing chemical selection.
- Technical Textiles:High-performance fabrics designed for specific functional purposes in non-traditional applications. This segment, including medical textiles and protective clothing, demands advanced flame retardants, anti-microbial agents, and durable water repellents.
- Automotive Upholstery:Textiles used in car interiors, requiring stringent finishes for flame retardancy, stain resistance, UV stability, and durability. Compliance with automotive industry standards is paramount, driving demand for specialized, high-performance formulations.
- Sportswear:Performance apparel for athletic activities, demanding finishes for moisture wicking, breathability, odor control, and UV protection.
High-volume needs define the Apparel Manufacturers sector, while Technical Textiles applications offer premium value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory disparities between regions drive the strategic location of textile finishing chemical production, seeking optimal balance between compliance costs and market access. This dynamic encourages manufacturing migration to regions with less stringent environmental frameworks or strong export-oriented textile industries. Companies evaluate various national standards when establishing or expanding operations.
Vietnam
Demand for performance finishes in sportswear and automotive textiles is rising within Vietnam's expanding manufacturing base. The Vietnamese government actively promotes foreign investment in high-tech textile manufacturing through various incentives. Ho Chi Minh City's industrial parks attract chemical suppliers supporting the apparel export sector with specialized formulations.
Bangladesh
Apparel manufacturers in Bangladesh demand cost-effective softeners and basic functional finishes for high-volume production. The Bangladesh textile industry must adhere to international compliance standards like OEKO-TEX for access to Western export markets. Dhaka's garment factories form a dense cluster for chemical distribution and technical support services.
China
The vast domestic market drives demand for a full spectrum of finishing chemicals, from apparel to technical textiles. China's GB standards increasingly influence formulation development, particularly for environmental compliance and product safety. The Yangtze River Delta region hosts major chemical producers and textile mills, fostering innovation in finishing technologies.
Germany
High-performance technical textiles for automotive and medical sectors create specific demand for specialized flame retardants and water repellents. Europe's REACH regulation mandates strict chemical safety and sustainability for all formulations sold within the bloc. The Rhine-Main area is a hub for chemical R&D and specialized textile finishing expertise.
Turkey
Strong domestic apparel and home textiles industries require diverse finishing agents for comfort, durability, and aesthetic appeal. Turkish textile producers increasingly adopt bluesign and OEKO-TEX standards to access European consumer markets. Bursa's textile cluster drives significant consumption of dyeing and finishing chemicals for regional production.
Global Textile Finishing Chemicals Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied customer needs and regulatory pressures. The market exhibits a tiered structure, with large, diversified chemical conglomerates competing against specialized formulators focused on niche applications. Strategic archetypes include global chemical giants, regional specialists, and sustainability-focused innovators. Geographic expansion and portfolio diversification are common competitive moves.
Within the global chemical conglomerate tier, BASF SE represents a diversified player with an extensive portfolio spanning various industries. Huntsman International LLC exemplifies a major player focused on specialized dyes and finishing effects, catering to performance textiles with specific functional demands. Archroma occupies a distinct position by emphasizing sustainable and water-saving solutions, appealing to brands with strong environmental commitments and circular economy goals. These companies continually adapt their offerings to meet evolving regulatory landscapes and technical demands across multiple geographies.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| Archroma |
| Dow Inc. |
| DyStar Group |
| Evonik Industries AG |
| Wacker Chemie AG |
| Solvay S.A. |
| The Lubrizol Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock prices for conventional finishes impact manufacturing costs for chemical formulators. These costs influence pricing tiers for fabric mills producing apparel and technical textiles.
Pricing Analysis
Distributor margins significantly influence the final cost of textile finishing chemicals for fabric mills. The market largely employs a contract-based long-term offtake model for high-volume orders, with transactional pricing for specialized batches. Pricing differentiates based on certification levels like OEKO-TEX or bluesign, and the customization required for performance formulations. Pricing pressure stems from input cost volatility for petrochemical feedstocks. Apparel manufacturers in Bangladesh exhibit high price sensitivity, contrasting with technical textile producers for automotive upholstery who prioritize performance over cost.
Supply Chain Analysis
Logistics costs represent a significant component of the delivered price for textile finishing chemicals, particularly for specialized formulations shipped globally. Geographic supply concentration centers on China, Germany, and the United States, drawing raw materials like petrochemical feedstocks and plant oils. Regulatory restrictions, such as Europe's REACH and China's GB standards, present a structural supply chain risk. Distribution runs through direct sales channels to large textile mills and specialized chemical distributors for smaller factories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global textile finishing chemicals market is transitioning to a late-cycle quality story. This shift is driven by a demand for certified functional outcomes in technical textiles.
For Market Incumbents: Lock in long-term supply agreements with key technical textile manufacturers to secure high-value demand. Incumbents must also invest significantly in bio-based R&D to counter the substitution risk from non-chemical finishing technologies. Prioritizing certification investment, such as for OEKO-TEX or bluesign, reinforces market leadership against evolving regulatory frameworks like Europe's REACH. This strategy defends market share from specialized entrants focusing on sustainable alternatives.
For New Entrants and Emerging Players: Digital finishing technology creates a technology-first wedge for new entrants by enabling precise, waste-reducing chemical application. White-space targets include developing formulations for smart textiles and multifunctional treatments that combine properties like water repellency and UV protection. Small-to-medium sized apparel manufacturers in Vietnam represent a penetrable segment, seeking compliant and efficient solutions. A compelling go-to-market angle involves offering integrated solutions that combine advanced chemistry with application support.
For Investors and Strategic Acquirers: Consolidation pressure builds where R&D capital intensity and cross-border compliance costs create significant barriers to entry. The long-term viability for specialized chemical formulators with strong intellectual property in sustainable solutions remains favorable over the next decade. Acquisition targets include niche players possessing proven PFAS-free alternatives or advanced bio-based platforms. The signal to watch is increased M&A activity focused on companies with certified sustainable chemistry portfolios, indicating a market valuation shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands production of bio-based finishes to meet rising apparel brand demand. |
| Green Manufacturing Transition | Reduces environmental footprint, aligning with Europe's REACH regulations and consumer preferences. |
| Long-term Supply Agreement | Secures raw material access and stable pricing for key technical textile applications. |
| Joint Venture | Combines R&D expertise to accelerate development of PFAS-free DWR finishes for performance outerwear. |
| Certification Investment | Achieves OEKO-TEX or bluesign compliance, unlocking market access to Western consumer markets. |
Research Approach
Bottom-up apparel manufacturer modeling reconciled against top-down chemical producer tracking forms the analytical core of this study. The approach combines in-depth primary interviews with R&D directors, procurement leads at fabric mills, sustainability managers, and distribution channel partners. Secondary validation draws from customs and trade data, ACC/Cefic reports, company 10-K filings, and OEKO-TEX certification databases. This comprehensive triangulation ensures robust data integrity and market sizing.
An input-output matrix quantifies market dynamics by mapping chemical types to fabric types and end-use industries across the analysis window. Segmentation dimensions include chemical type, finish type, fabric type, end-use industry, and regional production hub. Compound annual growth rates were derived from historical growth patterns and projected technological advancements in green chemistry. Key forecast inputs include technical textile adoption rates and bio-based chemical R&D investment.
The model holds under current regulatory stability and feedstock price trends; deviation in new chemical bans or sustained input cost spikes would shift projections. Forecasts reflect assumptions regarding technical textile growth and bio-based finish commercialization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market