
 Octenylsuccinate Market | 2026-2036
Octenylsuccinate Market Size, Share, and Industry Trends Forecast 2026-2036
Octenylsuccinate Market Analytics
ISO 22000 certification is rotating toward a baseline rather than a differentiator among octenylsuccinate suppliers seeking access to multinational food manufacturer approved-vendor lists. Cargill leverages its backward integration into corn wet milling to secure raw material cost stability across North American production. Ingredion anchors its position through deep formulation partnerships with beverage emulsion developers, while Roquette competes on pea-derived and potato-based alternative chemistries that bypass common allergen labeling triggers.
Octenylsuccinate denotes a family of starch derivatives produced through esterification of native starch with octenylsuccinic anhydride, yielding amphiphilic molecules with a degree of substitution typically below 0.02 that function as oil-in-water emulsifiers, encapsulation matrices, and viscosity modifiers across food and pharmaceutical systems. The octenylsuccinate starch category dominates current volume given its entrenched use in flavor encapsulation for spray-dried beverage preparations, whereas octenylsuccinate gums represent the fastest-expanding segment as plant-based stabilizer demand from dairy-alternative formulators intensifies. Application concentration within food and beverage reflects mature margin pools in convenience food emulsions, while pharmaceuticals applications are deepening as excipient-grade specifications tighten.
FDA food additive regulations under 21 CFR 172.892 govern permissible use levels and labeling for octenylsuccinate starch in US commerce, while EFSA's ongoing re-evaluations of modified starch additives within the EU are pressuring suppliers to generate expanded toxicological dossiers. REACH registration requirements for octenylsuccinic anhydride feedstock constrain European market entry for non-integrated importers. Stakeholders must monitor regulatory divergence between FDA's generally-recognized-as-safe pathway and EFSA's emerging demands for extended dietary exposure studies when allocating product development resources across Atlantic markets.
Market Dynamics
Clean-label formulation mandates from North American and European food manufacturers are compressing approval timelines for modified starch emulsifiers, forcing suppliers to front-load toxicological dossiers ahead of regulatory reclassifications.
Growth Catalysts
- Spray-dried beverage expansion:Flavor encapsulation demand from ready-to-drink coffee and tea formulators is pulling octenylsuccinate starch volumes into new product pipelines.
- EFSA re-evaluation protocols:Accelerated safety data requirements are filtering out marginal suppliers and consolidating procurement among certified manufacturers with existing dossiers.
- Pea-derived alternatives:Roquette's potato and pea-based chemistries are opening formulation pathways that bypass allergen labeling triggers in European dairy-alternative applications.
Market Restraints
- Corn wet milling concentration:Backward-integrated North American producers control raw material cost stability, squeezing margin flexibility for non-integrated importers facing REACH registration burdens.
- Octenylsuccinic anhydride feedstock volatility:Petrochemical-derived anhydride pricing fluctuates with propylene chain dynamics, compressing derivative margins unpredictably.
- Degree of substitution ceiling:FDA's 0.02 substitution limit under 21 CFR 172.892 caps performance differentiation and blocks premium positioning based on modified functionality.
Strategic Opportunities
- Pharmaceutical excipient grade migration:Tightening USP-NF and EP specifications for modified starches in oral solid dosage forms is opening higher-margin demand channels outside food saturation.
- Plant-based stabilizer convergence:Dairy-alternative formulators in Germany's food processing corridor are trialing octenylsuccinate gums alongside hydrocolloid blends for clean-label emulsion stability.
- ISO 22000 baseline arbitrage:Suppliers achieving FSSC 22000 or BRCGS certification ahead of multinational approved-vendor list rotations can capture displaced volume from recertifying laggards.
Industry Challenges
- Cross-Atlantic regulatory divergence:FDA's GRAS pathway permits faster market entry than EFSA's extended dietary exposure study requirements, forcing dual-track development spending.
- Encapsulation formulation expertise scarcity:Beverage emulsion developers with deep spray-drying partnerships command premium supply agreements, constraining new supplier access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octenylsuccinate Market |
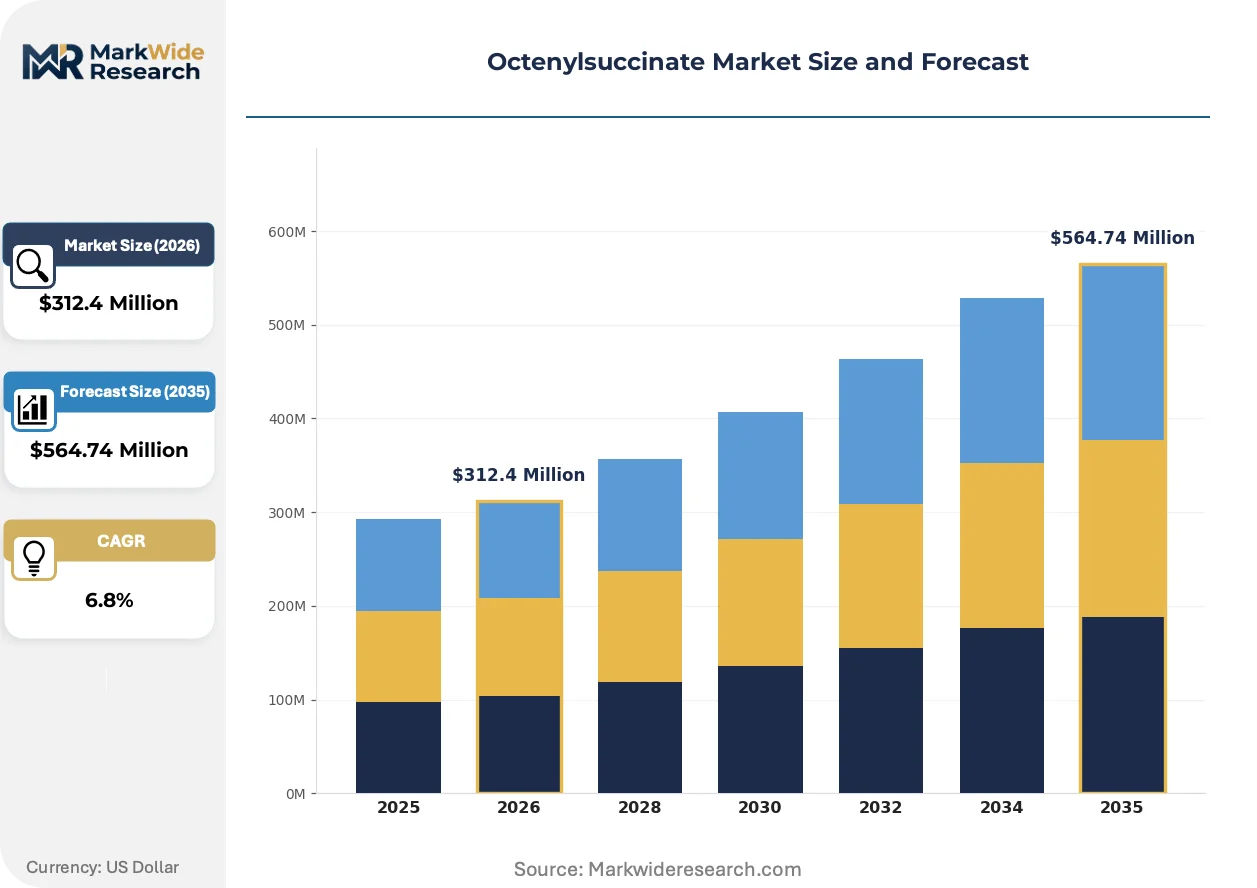
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Octenylsuccinate Starch, Octenylsuccinate Modified Starch, Octenylsuccinate Gums, Octenylsuccinate Polysaccharides Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Dietary Supplement Brands Formulation Type: Emulsions, Powders, Suspensions, Solutions |
| Companies Covered | Cargill, Tate & Lyle, Ingredion, Roquette, ADM, Südzucker, Emsland Group, Grain Processing Corporation, AGRANA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octenylsuccinate Market Evolving Landscape
Formulation science is pivoting toward molecular precision in starch modification, with degree-of-substitution control and alternative feedstock chemistry reshaping competitive capability requirements.
Enzymatic modification protocols are miniaturizing production footprints for specialty octenylsuccinate grades. Regional ingredient technology firms in the Netherlands and Denmark are piloting continuous-flow esterification systems that halve batch cycle times. The technology is miniaturizing capital barriers for mid-scale entrants, fragmenting supply concentration in European modified starch corridors.
REACH registration requirements for octenylsuccinic anhydride feedstock are tightening documentary burdens on non-integrated importers. ECHA's updated substance evaluation criteria now demand extended environmental fate studies for anhydride derivatives used in food-contact applications. German and French chemical distributors are consolidating import volumes through pre-registered toll manufacturers to share compliance costs.
Clean-label procurement criteria are compressing supplier qualification timelines. North American beverage manufacturers now require ISO 22000 certification as table stakes for approved-vendor list inclusion, displacing previous HACCP-only acceptance. Germany's contract manufacturing clusters are experiencing the tightest vendor consolidation as pan-European food brands centralize ingredient sourcing through fewer qualified gateways.
Octenylsuccinate Market Segmentation
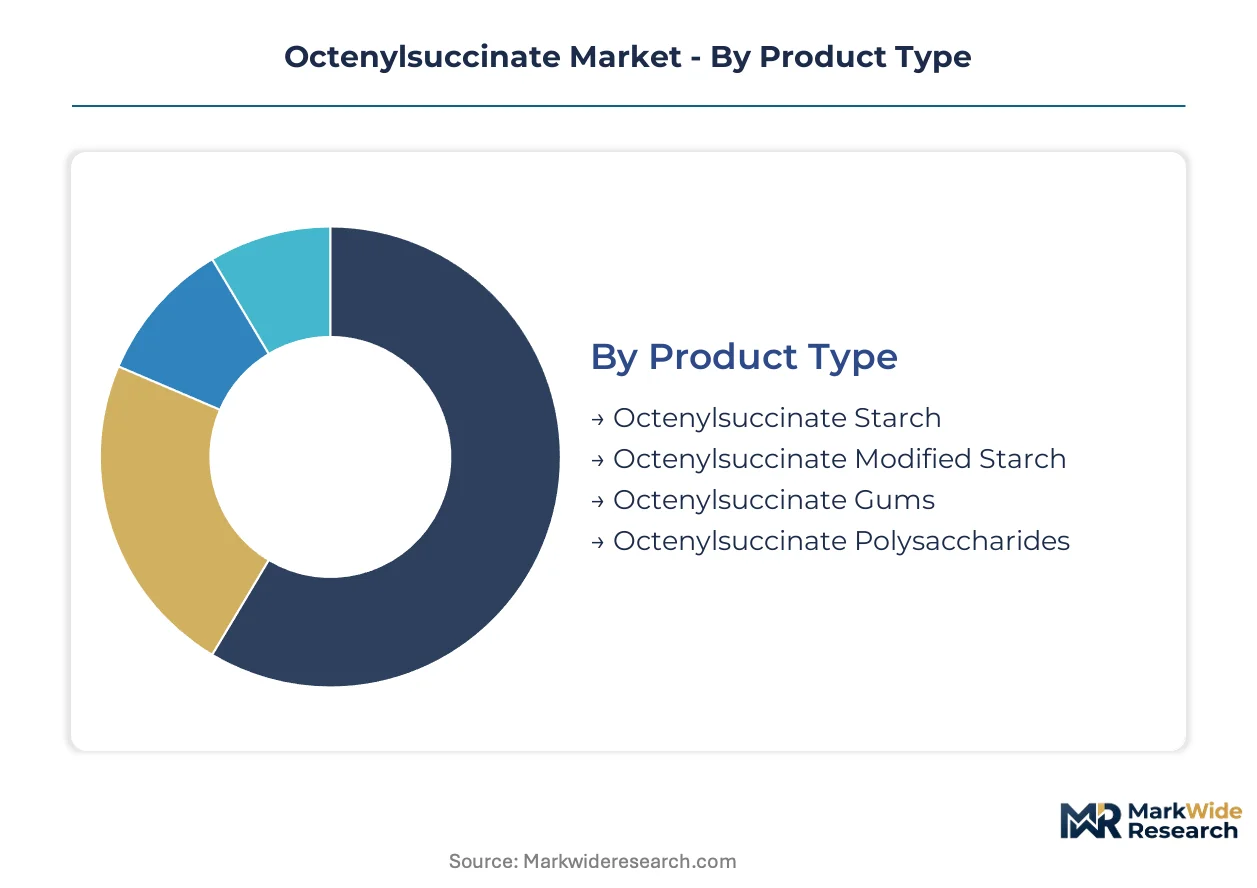
Octenylsuccinate derivatives serve divergent functional requirements across encapsulation, emulsification, and viscosity modification. Segmentation reveals where substitution pressure from hydrocolloid alternatives concentrates most intensely.
Product Type:
Octenylsuccinate gums face the sharpest substitution threat from locust bean and guar alternatives in dairy-alternative formulations.
- Octenylsuccinate Starch:Amphiphilic starch esters with degree of substitution below 0.02 function as oil-in-water emulsifiers and encapsulation matrices. Demand concentrates in spray-dried beverage flavor systems where FDA's 21 CFR 172.892 compliance is mandatory.
- Octenylsuccinate Gums:Plant-derived stabilizer chemistries from pea and potato feedstocks bypass common allergen labeling triggers. German dairy-alternative formulators are trialing these alongside hydrocolloid blends for clean-label emulsion stability.
- Octenylsuccinate Modified Starch:Secondary modification protocols enhance cold-water solubility for instant beverage applications.
- Octenylsuccinate Polysaccharides:Higher-molecular-weight variants serve pharmaceutical excipient specifications with tighter USP-NF tolerances.
Octenylsuccinate starch retains volume leadership; octenylsuccinate gums hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity food emulsifiers from premium pharmaceutical grades.
- Food & Beverage:Mature margin pools in convenience food emulsions dominate procurement volumes. North American ready-to-drink coffee and tea formulators are expanding flavor encapsulation contracts.
- Pharmaceuticals:Excipient-grade specifications for oral solid dosage forms command premium positioning. Tightening EP and USP-NF standards are filtering out uncertified suppliers.
- Cosmetics:Emulsion stabilizers for skincare formulations face competition from silicone alternatives.
- Nutraceuticals:Encapsulation matrices for omega-3 and probiotic delivery systems require modified starch compatibility with active ingredient stability profiles.
Food and beverage anchors procurement volume; pharmaceuticals delivers the widest margin spreads.
End User:
Customer type determines certification burden intensity and approved-vendor list access speed.
- Food Manufacturers:Multinational processors in Germany's food processing corridor centralize ingredient sourcing through ISO 22000-certified gateways. EFSA's re-evaluation protocols are compressing supplier qualification timelines.
- Dietary Supplement Brands:Clean-label positioning requirements are accelerating pea-derived and potato-based chemistry trials.
- Cosmetic Companies:Formulation partnerships with emulsion developers command premium supply agreements.
- Healthcare Providers:Hospital and clinical nutrition formulators prioritize excipient-grade documentation for enteral feeding applications.
Food manufacturers concentrate procurement scale; dietary supplement brands are expanding specification flexibility fastest.
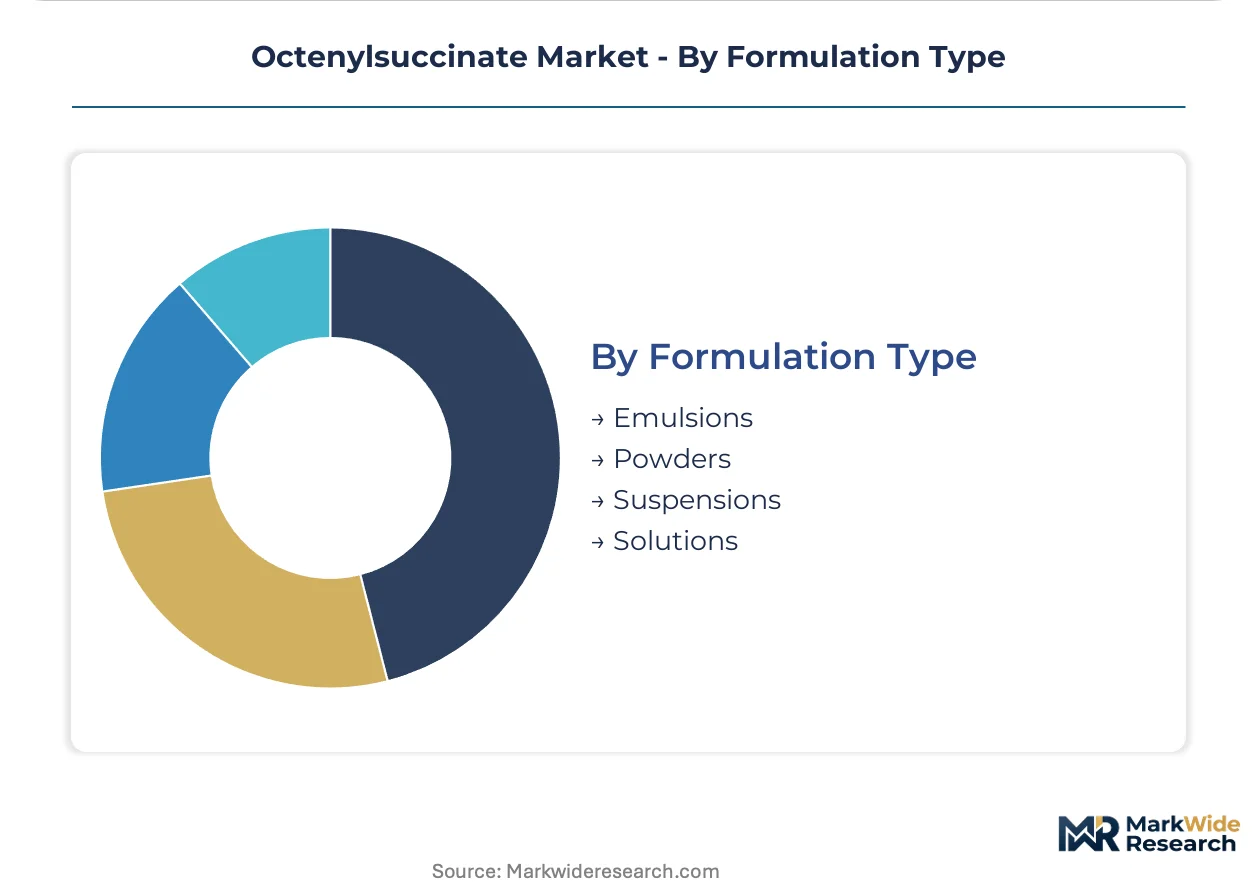
Formulation Type:
Supply concentration in spray-drying equipment shapes powder segment access barriers.
- Powders:Spray-dried flavor encapsulation dominates beverage preparation workflows. Continuous-flow esterification pilots in the Netherlands are halving batch cycle times for specialty grades.
- Emulsions:Oil-in-water systems for dairy alternatives require precise degree-of-substitution control for stability.
- Suspensions:Viscosity-modified delivery systems for nutraceutical actives demand particle size distribution uniformity.
- Solutions:Cold-water-soluble variants serve instant beverage and pharmaceutical liquid dosage applications.
Powders retain manufacturing volume dominance; emulsions are gaining share in plant-based formulation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 21 CFR 172.892 compliance mandates and EFSA's re-evaluation protocols are reshaping procurement geography, concentrating supplier qualification in jurisdictions with established regulatory dossiers and backward-integrated feedstock control.
United States
Spray-dried beverage formulators in the Midwest and Southeast are expanding flavor encapsulation contracts. FDA food additive regulations under 21 CFR 172.892 govern permissible use levels and labeling requirements. Corn wet milling clusters in Iowa and Illinois anchor North American production capacity for modified starch emulsifiers.
Germany
Specialty ingredient R&D clusters serve pan-European contract manufacturing from the food processing corridor. REACH registration requirements for octenylsuccinic anhydride feedstock constrain market entry for non-integrated importers. Continuous-flow esterification pilots in the Netherlands are fragmenting supply concentration across the Rhine-Ruhr and Bavarian chemical corridors.
China
SAMR's national food safety standards for modified starch additives are tightening documentary requirements for import clearance. GB standards compliance is becoming mandatory for domestic and imported octenylsuccinate derivatives. Yangtze River Delta chemical processors are expanding capacity for pharmaceutical-grade specifications.
India
FSSAI's food additive approval pathways are compressing timelines for modified starch emulsifiers in convenience food applications. The PLI scheme for food processing is incentivizing domestic encapsulation matrix production. Maharashtra and Gujarat ingredient technology corridors are attracting multinational formulation partnerships.
Netherlands
EFSA-driven reclassification of modified starches is pressuring suppliers to generate expanded toxicological dossiers. ECHA's updated substance evaluation criteria demand extended environmental fate studies for anhydride derivatives. Randstad region distributors are consolidating import volumes through pre-registered toll manufacturers to share compliance costs.
Octenylsuccinate Market Competitive Landscape
Player mix skews toward backward-integrated agribusiness conglomerates with captive corn wet milling capacity and regional specialists competing on alternative feedstock chemistries. Structure consolidates around North American giants controlling raw material cost stability, while European mid-scale entrants fragment through enzymatic modification miniaturization. Dominant archetypes include integrated starch processors, pea-derived alternative chemists, and pharmaceutical-grade specification specialists. Competitive moves center on formulation partnership deepening and ISO 22000 certification pre-positioning ahead of multinational vendor list rotations.
Among North American agribusiness anchors, Cargill and ADM exemplify the integrated processor archetype through upstream corn wet milling control. Ingredion occupies a position within the formulation partnership tier, anchoring supply relationships with beverage emulsion developers. Roquette represents the alternative feedstock specialist, competing on pea-derived and potato-based chemistries that bypass common allergen labeling triggers in European applications.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Ingredion |
| Roquette |
| ADM |
| Südzucker |
| Emsland Group |
| Grain Processing Corporation |
| AGRANA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between North American corn wet millers and multinational food manufacturers lock in both supply access and price visibility for octenylsuccinate starch volumes, insulating integrated producers from propylene-chain volatility while exposing non-integrated importers to margin compression.
Pricing Analysis
Certification level creates the primary spread across octenylsuccinate tiers, with ISO 22000 and FSSC 22000 commanding premiums over HACCP-only grades in approved-vendor negotiations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade specifications reflects degree-of-substitution precision and toxicological dossier depth. Cost compression in standard food-grade tiers is intensifying because REACH registration burdens squeeze non-integrated European importers. Dietary supplement brands exhibit highest price sensitivity due to clean-label positioning constraints, while pharmaceutical formulators accept premium positioning for USP-NF compliance.
Supply Chain Analysis
The United States and Germany anchor octenylsuccinate production through corn wet milling clusters in Iowa and Illinois and specialty ingredient R&D corridors in Bavaria and the Rhine-Ruhr. Manufacturing draws from corn starch, pea protein, and potato feedstock inputs, with petrochemical-derived octenylsuccinic anhydride feeding esterification reactions. Single-source vulnerability concentrates in propylene-chain anhydride suppliers, exposing derivative margins to upstream volatility. Distribution runs through pre-registered toll manufacturers in the Netherlands and Randstad region chemical distributors sharing REACH compliance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Germany's pan-European contract manufacturing clusters as multinational food brands centralize ingredient sourcing through fewer ISO 22000-certified gateways, compressing supplier qualification timelines and displacing marginal competitors.
For Market Incumbents: Compound formulation partnership depth with beverage emulsion developers to lock in spray-dried flavor encapsulation contracts before EFSA re-evaluation protocols filter uncertified suppliers. Prioritize backward integration into corn wet milling or captive octenylsuccinic anhydride supply to defend margin position against propylene-chain volatility. Accelerate FSSC 22000 certification pre-positioning ahead of multinational vendor list rotations displacing HACCP-only competitors. For New Entrants and Emerging Players: Differentiate on pea-derived and potato-based alternative chemistries that bypass allergen labeling triggers in European dairy-alternative applications. Target pharmaceutical excipient-grade specifications where USP-NF and EP compliance gaps exist among incumbent food-focused suppliers. Pursue continuous-flow esterification technology licensing from Netherlands-based pilot operators to halve batch cycle times and fragment supply concentration. For Investors and Strategic Acquirers: Regional enzymatic modification specialists with miniaturized production footprints and existing REACH registration dossiers present acquisition targets with defensible compliance moats. Long-term viability hinges on regulatory divergence arbitrage between FDA's GRAS pathway and EFSA's extended dietary exposure requirements. Watch ECHA substance evaluation criteria tightening for anhydride derivatives as the inflection signal for compliance-cost consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Cargill and ADM secure raw material cost stability across North American production corridors. |
| Continuous-Flow Esterification Technology | Netherlands and Denmark pilots fragment supply concentration by halving batch cycle times. |
| Pharmaceutical Excipient Grade Migration | USP-NF and EP specification tightening opens premium demand channels outside food saturation. |
| Pea-Derived Alternative Chemistry Development | Roquette bypasses common allergen labeling triggers in European dairy-alternative formulations. |
| FSSC 22000 Certification Pre-Positioning | Suppliers capture displaced volume from recertifying laggards in multinational vendor rotations. |
Research Methodology
Desk research of FDA 21 CFR filings, EFSA scientific opinions, REACH registration databases, and modified starch trade customs data preceded structured interviews with food manufacturer procurement directors, beverage emulsion formulators, pharmaceutical excipient quality managers, and chemical distributor compliance officers. Bottom-up volume modeling across product type, application, and formulation segments was cross-validated through top-down market sizing from corn wet milling capacity disclosures and octenylsuccinic anhydride derivative production estimates.
Variance decomposition across the projection horizon isolates drivers including EFSA re-evaluation timeline acceleration, spray-dried beverage pipeline expansion, and pharmaceutical-grade specification migration. Modeled segmentation spans starch versus gum chemistry, food versus pharmaceutical application, powder versus emulsion formulation, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections tied to convenience food emulsion growth and clean-label procurement intensity.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 21 CFR 172.892 stability and EFSA extended study requirement implementation; material deviation in propylene-chain pricing or REACH enforcement stringency would warrant model refresh. Recalibration cycles align with material shifts in regulatory divergence, feedstock volatility, and certification baseline migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Dimethyl Dicarbonate Market