
 Elemental Formula Market | 2026-2036
Elemental Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Elemental Formula Market Analysis
China is fragmenting its elemental formula production base as domestic dairy processors and specialty nutrition firms build dedicated hydrolysate and amino acid-based manufacturing lines to reduce import dependency. Mead Johnson & Company LLC leverages its pediatric metabolic disease portfolio to sustain premium positioning in hospital channels. Nestlé S.A. anchors its competitive stance through specialized R&D centers focused on protein hydrolysis technologies. Abbott Laboratories competes via extensive clinical validation programs that support insurance reimbursement claims.
Elemental formula consists of predigested nutrients—free amino acids, simple carbohydrates, and medium-chain triglycerides—formulated for individuals with impaired gastrointestinal absorption or severe food allergies, with protein content typically fully hydrolyzed to dipeptides or single amino acids to eliminate immunogenic epitopes. The powder segment dominates hospital procurement due to lower shipping costs and extended shelf stability, while liquid formats are gaining traction in home enteral nutrition programs where caregiver convenience determines compliance. Medical foods applications command the highest margin pools because regulatory classification as prescription products restricts price competition, whereas sports nutrition represents a faster-growing but lower-margin outlet driven by amateur endurance athletes seeking gut-friendly protein sources.
FDA oversight of infant formula quality and labeling, coupled with USDA reimbursement pathways for medical foods through WIC and Medicare, creates a dual-track compliance environment that favors established manufacturers with dedicated regulatory affairs teams. The EU's Novel Food Regulation and EFSA health claim requirements impose additional barriers for European market entry, particularly for amino acid-based products seeking pediatric indications. Stakeholders must monitor evolving reimbursement criteria for elemental formulas as public health agencies recalibrate medical food classifications and coverage thresholds.
Market Dynamics
Hospital procurement consolidation and evolving FDA enforcement discretion on hypoallergenic infant formula claims are compressing margin pools while simultaneously raising technical barriers to market entry for elemental formula manufacturers.
Growth Catalysts
- WIC and Medicare reimbursement pathways:USDA and CMS coverage expansion for medical foods in the United States reduces out-of-pocket burden for caregivers managing severe pediatric food allergies, accelerating prescription volume in tertiary pediatric gastroenterology departments.
- Protein hydrolysis technology maturation:Advances in enzymatic processing and amino acid fortification systems enable manufacturers to achieve complete immunogenic epitope elimination, satisfying the stringent tolerance thresholds required for FPIES and EoE patient populations.
- Home enteral nutrition program expansion:Post-acute care networks in Germany and Japan are integrating liquid elemental formats into reimbursement-covered home care protocols, shifting consumption from institutional to residential settings.
Market Restraints
- Amino acid raw material concentration:Fermentation-derived L-amino acid supply chains concentrate among specialty chemical producers in China and Switzerland, exposing formula manufacturers to input cost volatility and qualification timeline risk.
- Novel Food Regulation friction:EFSA's extended safety assessment timelines for amino acid-based pediatric products delay European market entry by 18-36 months relative to conventional hydrolysate formulations.
- Substitute threat from extensively hydrolyzed formulas:Partial hydrolysate products with documented tolerance in mild-to-moderate cow's milk protein allergy capture price-sensitive segments, constraining elemental formula addressable market expansion.
Strategic Opportunities
- Underpenetrated Brazilian pediatric allergy market:ANVISA's evolving medical food classification framework and expanding private insurance coverage for specialized nutrition create whitespace for amino acid-based entrants in South America's largest healthcare market.
- Sports nutrition gut-friendly positioning:Amateur endurance athletes seeking reduced gastrointestinal distress during training are adopting elemental protein formats, opening a consumer channel distinct from prescription medical foods.
- Dual carbon goals alignment in China:NMPA incentives for domestic biotechnology manufacturing and provincial carbon reduction mandates favor localized fermentation and processing capacity for amino acid ingredients.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating simultaneous FDA infant formula enforcement discretion, USDA WIC eligibility, and state-level medical food classification requirements command premium compensation and extend hiring timelines.
- Clinical validation capex intensity:Prospective randomized trials demonstrating tolerance and growth equivalence in FPIES populations require multi-site pediatric recruitment and 12-24 month follow-up periods, consuming substantial R&D budgets.
- Legacy ERP integration with track-and-trace mandates:FDA's enhanced infant formula recordkeeping requirements force manufacturers to reconfigure batch-level serialization systems without disrupting just-in-time hospital distribution workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elemental Formula Market |
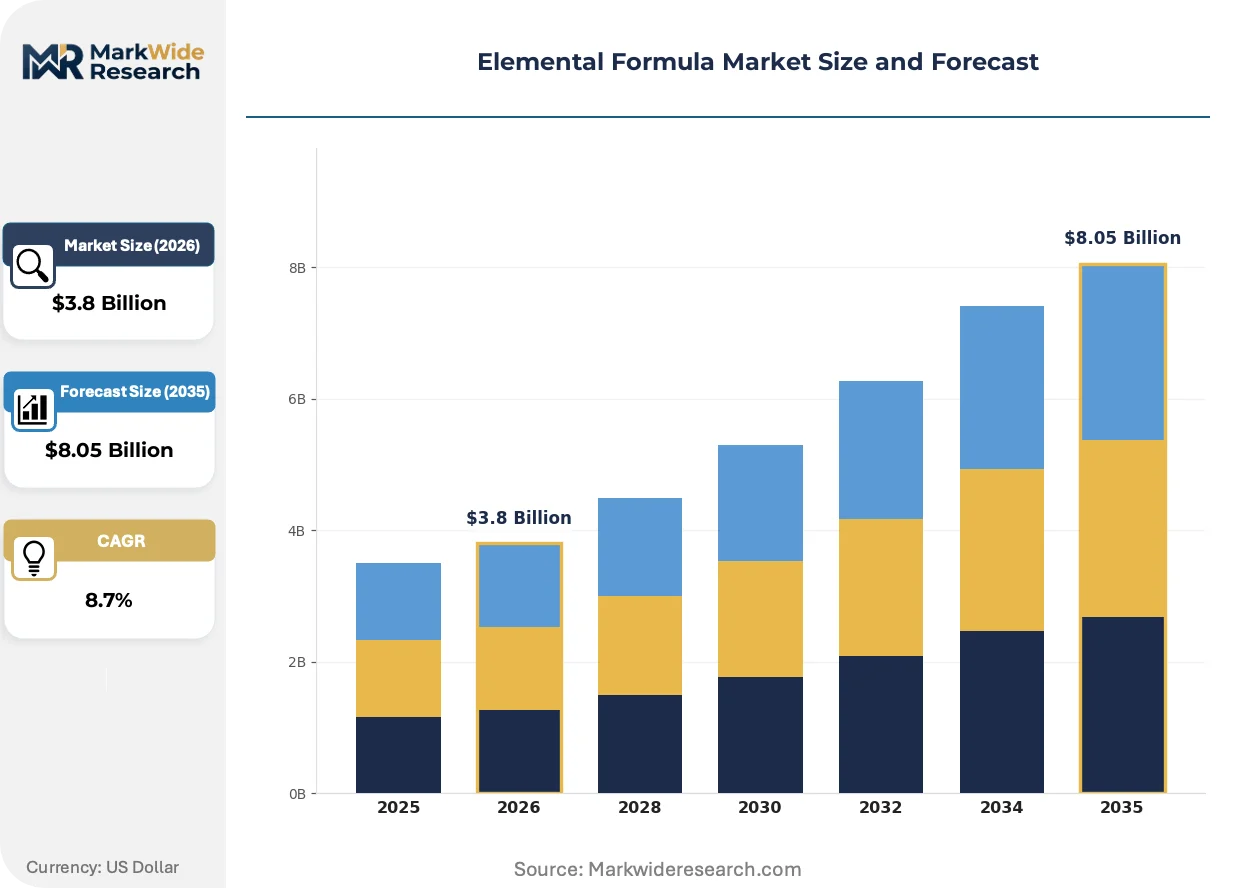
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Sachet Target Demographic: Infants, Adults, Elderly, Pregnant Women Distribution Channel: Retail Stores, Online, Pharmacies, Hospitals End Use: Clinical Nutrition, Sports Nutrition, Dietary Supplements, Medical Foods |
| Companies Covered | Mead Johnson & Company LLC, Yili Group, Nestlé S.A., Fonterra, Biostime, Abbott Laboratories, Fresenius Kabi AG, Royal FrieslandCampina, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elemental Formula Market Emerging Trajectories
Enzymatic processing advances and regulatory data harmonization initiatives are compressing development timelines while simultaneously fragmenting competitive positioning between hospital-channel specialists and consumer-facing nutrition platforms.
Continuous enzymatic hydrolysis systems with real-time molecular weight monitoring are replacing batch-wise protein processing in manufacturing facilities serving tertiary hospital networks. Pediatric metabolic disease centers in the United States and specialized allergy clinics in France are adopting these outputs for severe enteropathy cases. The technology is rendering obsolete conventional acid-precipitation methods that produced inconsistent peptide profiles and elevated rejection rates during incoming quality testing.
EFSA's updated guidance on health claims for protein hydrolysates in infant and follow-on formula creates a bifurcated compliance pathway between amino acid-based and peptide-containing products. Manufacturers must now maintain parallel substantiation dossiers or commit to single-technology positioning, raising fixed compliance costs. The amino acid segment is responding by accelerating clinical publication strategies targeting pediatric gastroenterology societies rather than general nutrition journals.
Caregiver purchasing patterns in home enteral nutrition are gravitating toward subscription-based replenishment models with integrated insurance pre-authorization support. Durable medical equipment suppliers and specialty pharmacies are displacing traditional wholesale distribution for liquid elemental formats in post-acute settings. This channel migration is most visible in California, Texas, and Florida, where Medicaid managed care expansion has concentrated eligible patient populations under single-source specialty pharmacy contracts.
Elemental Formula Market Segmentation
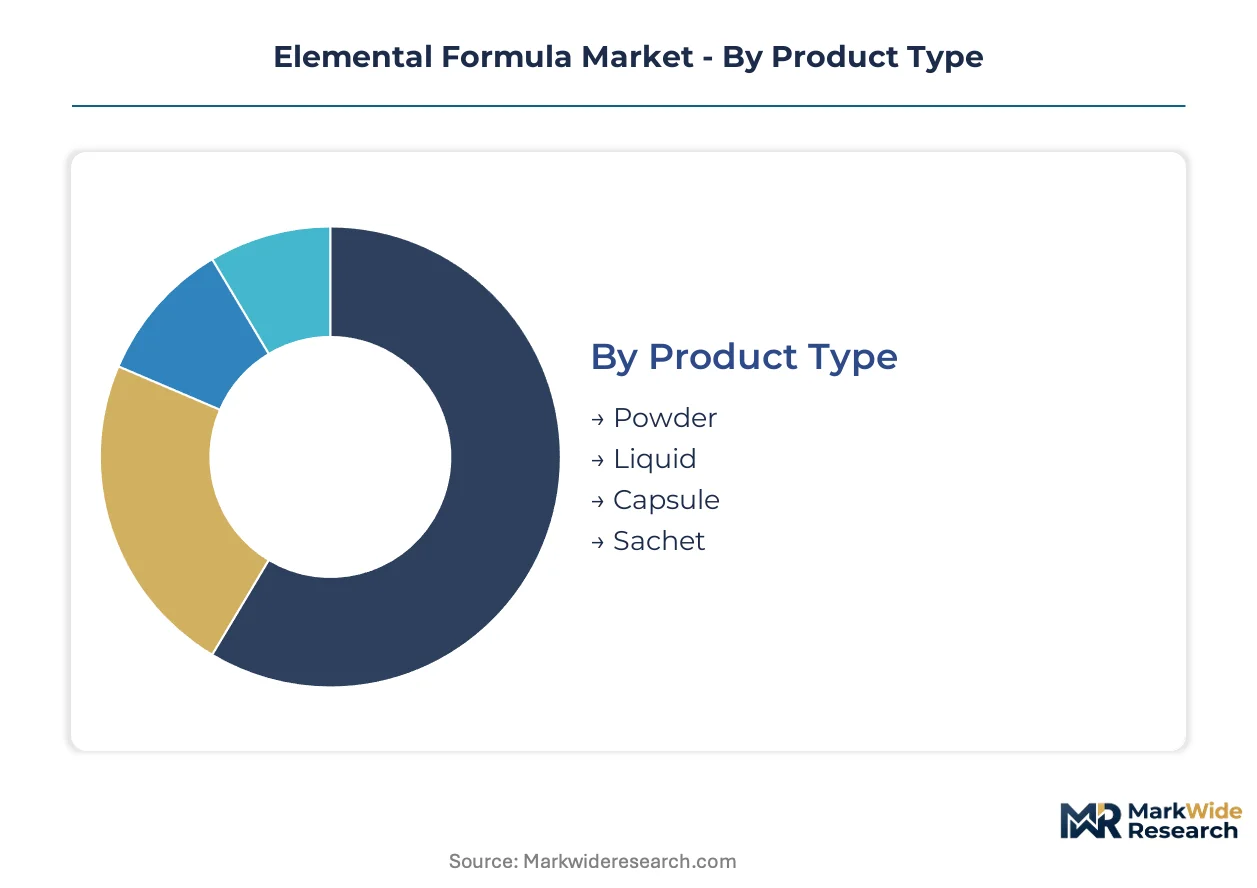
Elemental formula manufacturers configure production lines around distinct technical specifications and channel requirements. Segmentation choices directly determine regulatory pathways, reimbursement eligibility, and margin structure across hospital, retail, and direct-to-consumer channels.
Product Type:
Mature formats dominate institutional procurement while emerging delivery systems target convenience-driven home care segments.
- Powder:Dehydrated formulations requiring reconstitution with water provide extended shelf stability and reduced shipping costs. Hospital procurement departments in the United States and Germany favor powder for enteral nutrition programs where volume throughput and inventory turnover determine supplier selection.
- Liquid:Ready-to-feed formulations eliminate preparation error and reduce caregiver burden in residential settings. Post-acute care networks in Japan and California Medicaid managed care plans are expanding liquid format coverage for pediatric FPIES patients discharged to home care.
- Capsule:Encapsulated amino acid blends serve adult populations requiring precise dosing flexibility. Sports nutrition retailers stock capsule formats for endurance athletes seeking portable gut-friendly protein supplementation.
- Sachet:Single-serve powder packets address travel and workplace consumption scenarios. Brazilian and Mexican distributors are introducing sachet lines for private insurance-covered medical food programs.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Target Demographic:
Application intensity varies sharply across life stages, with pediatric and geriatric populations driving prescription volume through distinct clinical pathways.
- Infants:Amino acid-based formulations for severe food protein-induced enterocolitis require FDA infant formula compliance and documented growth equivalence. Tertiary pediatric gastroenterology departments in Boston and Paris prescribe these for failure-to-thrive cases unresponsive to extensively hydrolyzed alternatives.
- Adults:Enteral and parenteral nutrition candidates with short bowel syndrome or active Crohn's disease represent stable hospital demand. German and Japanese home care reimbursement frameworks cover adult elemental formula for post-surgical intestinal rehabilitation.
- Elderly:Dysphagia and malabsorption in aged populations create institutional demand for liquid and pudding-thick preparations. US skilled nursing facilities incorporate elemental supplements into pressure ulcer prevention protocols.
- Pregnant Women:Hyperemesis gravidarum and gestational food protein intolerance generate niche prescription demand. French and UK maternal-fetal medicine specialists prescribe elemental formulas when conventional antiemetics fail.
Infants command premium pricing through medical food classification; adults represent the steepest expansion trajectory as home enteral nutrition programs mature.
Distribution Channel:
Channel selection determines reimbursement capture rate and regulatory compliance burden for manufacturers.
- Retail Stores:Mass-market outlets stock limited SKUs for sports nutrition and general wellness positioning. Shelf placement depends on consumer pull-through rather than clinical validation.
- Online:Direct-to-consumer platforms enable subscription replenishment with insurance pre-authorization integration. California and Texas specialty pharmacies are displacing wholesale distribution for Medicaid-covered liquid formats.
- Pharmacies:Hospital outpatient and community pharmacies handle prescription medical foods with prior authorization requirements. French and German pharmacy networks maintain tighter formulary control than US retail chains.
- Hospitals:Inpatient and discharge planning procurement consolidates around GPO contracts and clinical nutrition committee approvals. Tertiary pediatric centers in the United States require documented FPIES tolerance data for formulary inclusion.
Hospitals anchor volume commitment; online is gaining share fastest as home care protocols expand.
End Use:
Regulatory classification separates medical food applications from consumer wellness positioning with substantial margin implications.
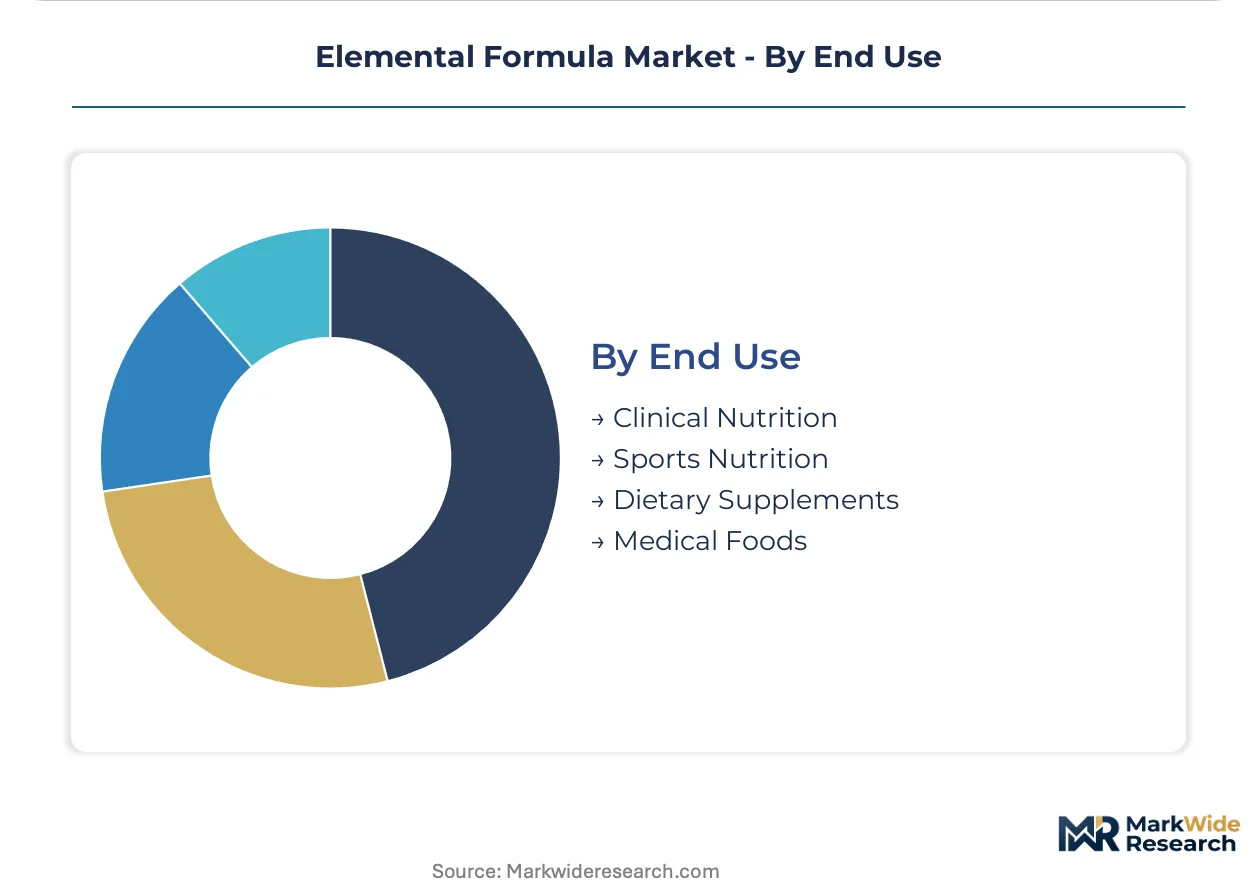
- Clinical Nutrition:Hospital and home care enteral feeding for malabsorption, short bowel syndrome, and post-surgical recovery. US Medicare Part B and German statutory health insurance cover these under medical device or pharmaceutical benefit categories.
- Sports Nutrition:Amateur endurance athletes seeking reduced gastrointestinal distress during training and competition. This consumer channel operates outside medical food reimbursement but carries lower compliance costs.
- Dietary Supplements:General wellness positioning for digestive health and protein supplementation. FDA DSHEA framework applies rather than infant formula or medical food regulations.
- Medical Foods:Prescription products for inborn errors of metabolism and severe food allergies. Mead Johnson and Abbott Laboratories compete through specialized metabolic disease portfolios and insurance reimbursement support.
Medical Foods captures the highest margin pool; Sports Nutrition shows the fastest volume climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States driving prescription volume through medical food reimbursement while China and Brazil expand domestic manufacturing to reduce import dependency.
United States
Medicaid managed care expansion in California, Texas, and Florida concentrates eligible pediatric FPIES patients under specialty pharmacy contracts. FDA infant formula enforcement discretion and USDA WIC pathways create dual-track compliance that favors established manufacturers with dedicated regulatory teams. Tertiary pediatric centers in Boston and Philadelphia require documented tolerance data for formulary inclusion.
Germany
Statutory health insurance covers adult elemental formula for post-surgical intestinal rehabilitation and home enteral nutrition programs. EFSA's extended safety assessment timelines for amino acid-based pediatric products delay market entry relative to conventional hydrolysates. Manufacturing clusters in North Rhine-Westphalia and Bavaria supply hospital procurement networks across the EU.
China
NMPA incentives for domestic biotechnology manufacturing and provincial carbon reduction mandates favor localized fermentation capacity for amino acid ingredients. Domestic dairy processors and specialty nutrition firms in the Yangtze River Delta and Shandong Peninsula are building dedicated hydrolysate manufacturing lines. Import dependency for elemental formulas is declining as local production scales.
Brazil
ANVISA's evolving medical food classification framework and expanding private insurance coverage create whitespace for amino acid-based entrants. São Paulo and Rio de Janeiro pediatric allergy clinics drive prescription demand for severe food protein intolerance cases. Distributors are introducing sachet formats for private insurance-covered medical food programs.
Japan
Post-acute care networks integrate liquid elemental formats into reimbursement-covered home care protocols, shifting consumption from institutional to residential settings. METI oversight of functional food claims intersects with MHLW medical device reimbursement pathways for enteral nutrition. Manufacturing concentration in the Kansai region serves aging population demand for dysphagia and malabsorption applications.
Elemental Formula Market Vendor Landscape
Capability concentration sits with specialized pediatric nutrition houses; scale advantage sits with diversified dairy and pharmaceutical conglomerates. The market structure tiers between hospital-channel specialists with metabolic disease portfolios and consumer-facing platforms seeking gut-friendly positioning. Three archetypes dominate: legacy infant formula manufacturers extending into hypoallergenic lines, clinical nutrition specialists with enteral feeding expertise, and dairy processors building amino acid capacity through backward integration. Competitive moves center on clinical validation capex for insurance reimbursement and enzymatic processing technology licensing.
Within the hospital-channel specialist tier, Mead Johnson & Company LLC and Abbott Laboratories occupy positions anchored by pediatric metabolic disease portfolios and extensive clinical validation programs. Nestlé S.A. represents the diversified nutrition conglomerate archetype, with specialized R&D centers focused on protein hydrolysis technologies. Among dairy-origin players, Yili Group and Fonterra exemplify the backward integration strategy, building domestic amino acid manufacturing capacity to reduce dependency on fermentation-derived inputs from specialty chemical suppliers.
| Leading Market Players |
|---|
| Mead Johnson & Company LLC |
| Yili Group |
| Nestlé S.A. |
| Fonterra |
| Biostime |
| Abbott Laboratories |
| Fresenius Kabi AG |
| Royal FrieslandCampina |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
Fermentation-derived L-amino acid supply chains concentrate among specialty chemical producers in China and Switzerland, anchoring margin capture downstream with medical food manufacturers who command prescription-tier pricing through FDA infant formula compliance and USDA WIC reimbursement pathways.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with GPO contracts securing volume commitments from tertiary pediatric centers and post-acute care networks. Three-tier pricing structure across premium amino acid-based, standard extensively hydrolyzed, and economy peptide-modified formulations reflects immunogenic epitope elimination thresholds and clinical validation depth. Cost compression in standard hydrolysate tiers is intensifying because extensively hydrolyzed alternatives capture price-sensitive mild allergy segments. Home enteral nutrition programs show lowest price sensitivity due to insurance pre-authorization integration, while sports nutrition retail channels exhibit highest sensitivity to per-gram protein cost.
Supply Chain Analysis
Upstream feedstock dependence centers on fermentation-derived amino acid precursors sourced from manufacturing clusters in China, Switzerland, and select North American biotechnology hubs. Critical inputs include L-glutamine, L-arginine, and enzymatic processing catalysts, alongside medium-chain triglyceride lipid fractions. Single-source vulnerability concentrates in specialty amino acid fermentation capacity, where qualification timelines extend procurement risk. Distribution runs through hospital GPO contracts, specialty pharmacy networks, and durable medical equipment suppliers serving post-acute care protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elemental formula markets are recovering from regulatory backlog compression, with EFSA safety assessment timelines and FDA enforcement discretion cycles creating predictable cadences of supply constraint and release.
For Market Incumbents: Entrench hospital formulary positions through accelerated FPIES tolerance publication strategies targeting pediatric gastroenterology societies rather than general nutrition journals. Deepen backward integration into amino acid fermentation capacity to reduce exposure to Chinese and Swiss specialty chemical supplier concentration. Secure Medicaid managed care specialty pharmacy contracts in California, Texas, and Florida before channel migration completes.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian pediatric allergy markets where ANVISA medical food classification remains fluid and private insurance coverage expansion creates whitespace. Target sports nutrition gut-friendly positioning among amateur endurance athletes, a consumer channel with lower compliance barriers and faster product launch timelines than prescription medical foods. Deploy subscription-based replenishment models with integrated insurance pre-authorization support to displace wholesale distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical nutrition specialists with enteral feeding expertise and established pediatric metabolic disease portfolios, rather than diversified dairy conglomerates seeking backward integration. Long-term viability hinges on sustained R&D intensity for enzymatic processing advances and regulatory affairs capabilities spanning simultaneous FDA, USDA, and state-level compliance. Monitor EFSA guidance harmonization initiatives and NMPA domestic biotechnology incentives as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Program Expansion | Multi-site pediatric FPIES trials satisfy Boston and Philadelphia tertiary center formulary requirements for amino acid-based entrants. |
| Enzymatic Processing Technology Licensing | Continuous hydrolysis systems with real-time molecular weight monitoring displace acid-precipitation methods in hospital-serving facilities. |
| Backward Integration into Amino Acid Fermentation | Captive L-glutamine and L-arginine production reduces qualification timeline risk from Chinese and Swiss specialty chemical suppliers. |
| Specialty Pharmacy Network Partnership | California and Texas Medicaid managed care contracts concentrate eligible pediatric patients under single-source distribution arrangements. |
| Sports Nutrition Channel Development | Amateur endurance athlete positioning opens gut-friendly protein consumption outside medical food reimbursement restrictions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric gastroenterologists, hospital procurement managers, regulatory affairs specialists at infant formula manufacturers, and specialty pharmacy formulary directors. Secondary validation drew from FDA infant formula enforcement discretion filings, EFSA health claim substantiation dossiers, CMS Medicare Part B medical food reimbursement data, and USDA WIC eligibility records. Bottom-up prescription volume modeling triangulated against top-down medical food market sizing across the analysis window.
Calibration approaches anchored volume projections to documented WIC and Medicare pathway expansions, with segmentation dimensions spanning product format (powder, liquid, capsule, sachet), target demographic (infant, adult, elderly, pregnant), distribution channel (hospital, pharmacy, online, retail), and end-use classification (medical food, clinical nutrition, sports nutrition, dietary supplement). CAGRs were derived from elasticity-adjusted prescription growth curves and home enteral nutrition program penetration rates, incorporating NMPA domestic manufacturing incentives and ANVISA regulatory evolution as scenario variables.
Sensitivities concentrate around EFSA safety assessment timeline compression, FDA enforcement discretion policy shifts, and amino acid raw material qualification disruptions. Forecasts reflect assumptions regarding sustained Medicaid managed care expansion and stable WIC medical food classification. Quarterly review of pediatric gastroenterology society publication patterns, specialty pharmacy contract awards, and NMPA biotechnology manufacturing incentive disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Palmitoyl Chloride Market