
 Metal Alkyls Market | 2026-2036
Metal Alkyls Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Alkyls Market Outlook
Single-site metallocene catalyst architectures is rewriting polyolefin production economics, forcing alkyl activator suppliers to recalibrate purity grades and batch consistency. Albemarle Corporation leverages its bromine-alkyl integration to sustain captive precursor supply for Ziegler-Natta systems. BASF SE anchors European catalyst demand through its polymerization agent portfolio. Nouryon competes on specialized aluminum alkyl formulations for high-melt-strength polypropylene.
Metal alkyls are organometallic compounds featuring a direct carbon-metal sigma bond, typically synthesized via Grignard-type reactions or transmetalation processes, and function primarily as co-catalysts, alkylating agents, and polymerization initiators requiring strict air- and moisture-free handling. Aluminum alkyls dominate volume due to their entrenched role in Ziegler-Natta polymerization, while lithium alkyls command premium positioning in pharmaceutical fine chemical synthesis where regioselectivity determines yield. Titanium alkyls occupy a narrower but high-growth niche in stereospecific polymerization systems where catalyst efficiency directly translates to plant throughput economics.
EPA oversight in the United States governs toxic release inventory reporting for pyrophoric metal alkyls, while REACH in Europe mandates full substance dossiers for aluminum and zinc alkyl registrations, elevating compliance costs for non-integrated suppliers. China's MEE enforces increasingly stringent emissions controls on organometallic production facilities, reshaping locational decisions for new alkyl capacity. Stakeholders must monitor regulatory divergence between jurisdictions as classification thresholds for self-reactive substances tighten, since misalignment in hazard communication standards threatens cross-border formulation trade.
Market Dynamics
Single-site metallocene catalyst architectures are forcing alkyl activator suppliers to recalibrate purity grades and batch consistency, compressing margins for non-specialized producers while rewarding integrated chemical conglomerates with captive precursor supply.
Growth Catalysts
- REACH substance dossier mandates:Full registration requirements for aluminum and zinc alkyls in Europe elevate compliance costs for non-integrated suppliers, advantaging established players with regulatory infrastructure.
- China olefin capacity expansion:Domestic polypropylene and polyethylene plant construction concentrates catalyst demand in East China chemical clusters, pulling metal alkyl volumes toward Ningbo and Shanghai port zones.
- Grignard-type synthesis refinements:Continuous-flow reactor technologies for organolithium production improve yield consistency and reduce solvent waste, lowering unit economics for pharmaceutical-grade lithium alkyls.
Market Restraints
- Magnesium price volatility:Primary magnesium supply concentration in Shaanxi province creates input cost instability for Grignard reagent manufacturers dependent on Chinese feedstock.
- Pyrophoric handling infrastructure:Specialized tankage, inert atmosphere warehousing, and fire suppression systems impose capital barriers that exclude regional distributors from direct alkyl handling.
- Aqueous quench substitution:Sodium hydride and potassium tert-butoxide displace lithium alkyls in selected deprotonation routes where regioselectivity requirements moderate.
Strategic Opportunities
- India pharmaceutical API surge:Contract manufacturing expansion under PLI scheme incentives creates incremental demand for organolithium reagents in asymmetric synthesis steps.
- Dual carbon policy alignment:China's MEE emissions controls on solvent-intensive alkyl production favor suppliers with carbon capture integration or bio-based feedstock pathways.
- Direct-to-plant catalyst delivery:Integrated logistics models bypassing regional warehouse networks reduce contamination risk and working capital burdens for polyolefin producers.
Industry Challenges
- Organometallic chemist scarcity:Specialized synthesis expertise for air-sensitive compounds concentrates at legacy chemical engineering programs in Germany, Japan, and select US research universities.
- REACH dossier compilation timelines:Extended substance evaluation periods for novel aluminum alkyl formulations delay market entry and freeze development capital for 18-36 month cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Alkyls Market |
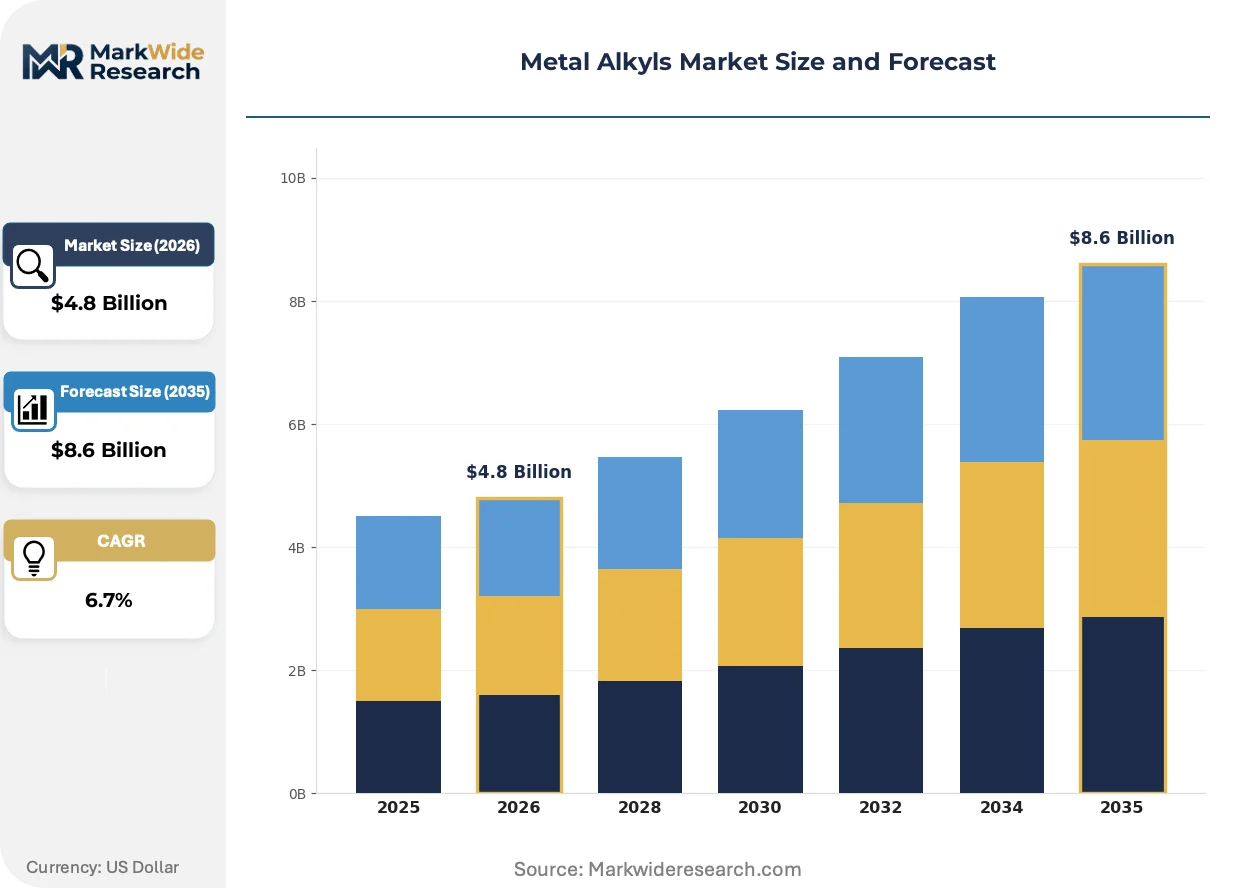
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alkyls, Zinc Alkyls, Lithium Alkyls, Titanium Alkyls Application: Catalysts, Additives, Antifoams, Polymerization Agents End User: Pharmaceuticals, Plastics, Agriculture, Coatings Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Strem Chemicals, BASF SE, Albemarle Corporation, TCI Chemicals, Akzo Nobel N.V., Nouryon, Gulbrandsen, FM Plastics, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Alkyls Market Strategic Shifts
Process intensification and regulatory precision are converging to reshape how metal alkyls are manufactured, qualified, and delivered to end-use customers across polymerization and pharmaceutical synthesis.
Continuous-flow Grignard synthesis platforms are replacing batch kettle operations for pharmaceutical-grade organolithium production. Contract API manufacturers in Hyderabad and Ahmedabad are adopting these systems to meet FDA and EMA contamination control standards. This shift is rendering obsolete traditional batch quench-and-filter workflows that generated inconsistent particle size distributions.
REACH Annex XVII restrictions on self-reactive substances are tightening classification thresholds for pyrophoric metal alkyls across EU member states. ECHA substance evaluation protocols now demand extended thermal stability data for transport classification, forcing reformulation of standard aluminum alkyl packages. Catalyst suppliers serving Rotterdam and Antwerp polymerization hubs are responding by consolidating formulation activities at integrated sites with on-site hazard testing capabilities.
Polyolefin producers are compressing catalyst qualification cycles from multi-year validation to 12-18 month windows. Procurement teams at integrated petrochemical complexes in Texas and Louisiana now demand real-time batch analytics and certificate-of-analysis digitization before contract award. This behavioral shift is most pronounced among metallocene system adopters where alkyl activator consistency directly correlates with plant throughput variance.
Metal Alkyls Market Segmentation
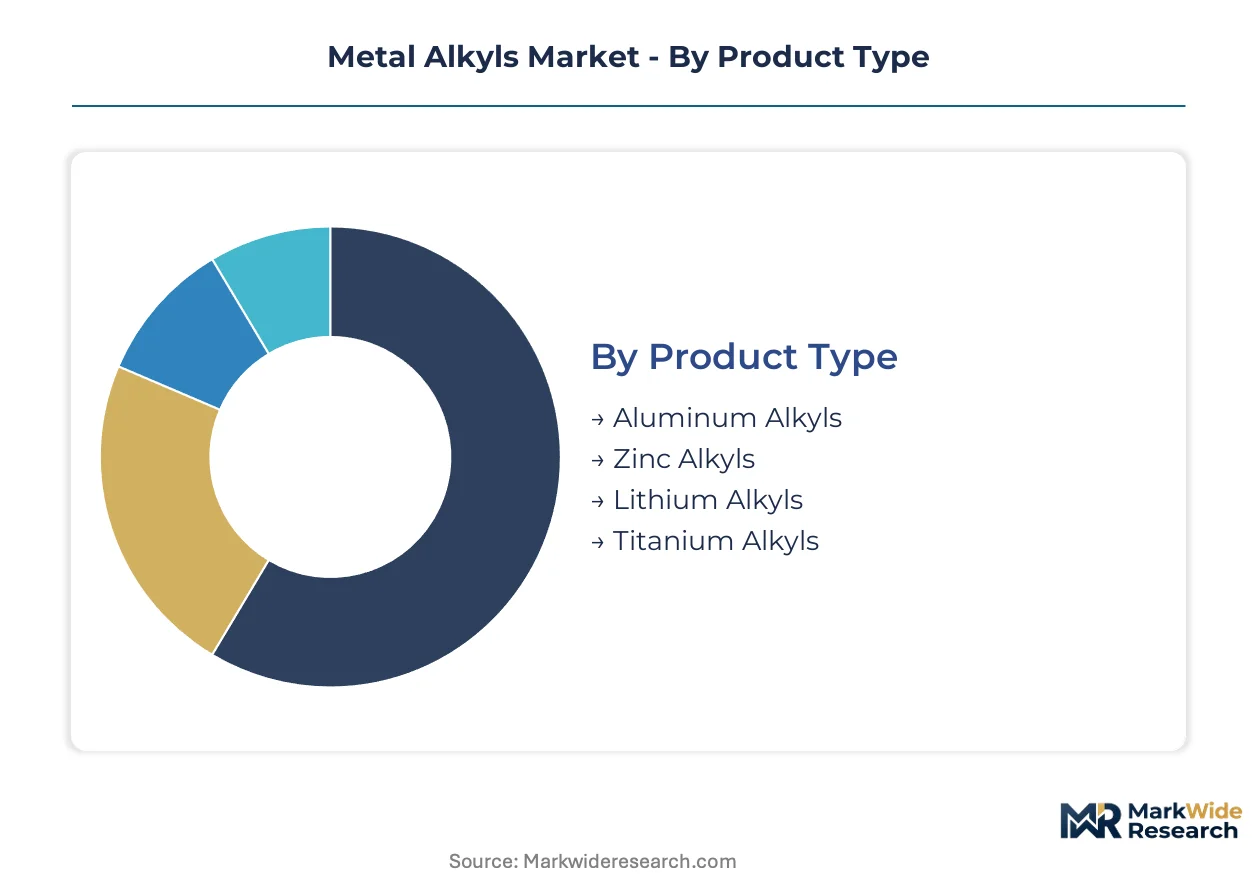
Metal alkyls segmentation reveals divergent velocity profiles across product chemistries and customer touchpoints. Polymerization catalyst buyers rotate inventory monthly while pharmaceutical API manufacturers lock in twelve-month supply contracts. Understanding these cycle-time differentials shapes working capital and pricing architecture for suppliers.
Product Type:
Aluminum alkyls turn inventory fastest through Ziegler-Natta catalyst channels, whereas lithium alkyls sit longest in pharmaceutical cold-chain warehouses awaiting batch release.
- Aluminum Alkyls:Triethylaluminum and triisobutylaluminum formulations dominate tonnage through their role as co-catalysts in polyethylene and polypropylene production. Demand concentrates in East China chemical clusters where Ningbo and Shanghai port zones host expanding olefin capacity. REACH substance dossier requirements advantage established European producers with regulatory infrastructure already deployed.
- Lithium Alkyls:Organolithium reagents including n-butyllithium and sec-butyllithium command premium positioning in asymmetric pharmaceutical synthesis where regioselectivity determines yield. Hyderabad and Ahmedabad contract API manufacturers under India's PLI scheme incentives are expanding offtake for Grignard-type reagents in continuous-flow reactor configurations.
- Zinc Alkyls:Diethylzinc serves niche applications in vapor deposition and specialized polymerization initiator systems.
- Titanium Alkyls:Stereospecific polymerization systems employ these compounds where catalyst efficiency directly translates to plant throughput economics.
Aluminum alkyls anchor the volume base while lithium alkyls gain share at the steepest rate.
Application:
Cost tier stratification separates commodity catalyst applications from precision pharmaceutical synthesis where specification tolerance tightens tenfold.
- Catalysts:Ziegler-Natta and metallocene polymerization systems consume the majority of aluminum alkyl volume. Polyolefin producers in Texas and Louisiana now compress qualification cycles to twelve-to-eighteen-month windows, demanding real-time batch analytics before contract award.
- Polymerization Agents:Single-site metallocene architectures force alkyl activator suppliers to recalibrate purity grades and batch consistency. Albemarle Corporation leverages bromine-alkyl integration to sustain captive precursor supply for integrated catalyst production.
- Additives:Flame retardant and stabilizer applications utilize metal alkyls in plastics compounding operations.
- Antifoams:Silicone-modified alkyl formulations serve process control in chemical manufacturing.
Catalyst applications concentrate procurement spend while polymerization agent specifications are tightening fastest.
End User:
Customer type determines hazard handling infrastructure requirements and contract structure complexity across the value chain.
- Plastics:Integrated petrochemical complexes drive bulk aluminum alkyl consumption through direct-to-plant delivery models that bypass regional warehouse networks and reduce contamination risk.
- Pharmaceuticals:FDA and EMA contamination control standards govern organolithium procurement for API synthesis. Continuous-flow reactor adoption in Indian contract manufacturing is displacing traditional batch quench-and-filter workflows.
- Agriculture:Agrochemical synthesis employs metal alkyls in specialized intermediate production.
- Coatings:Surface treatment and polymer modification applications utilize zinc and aluminum alkyl derivatives.
Plastics end users anchor volume throughput while pharmaceutical qualification requirements are expanding most quickly.
Distribution Channel:
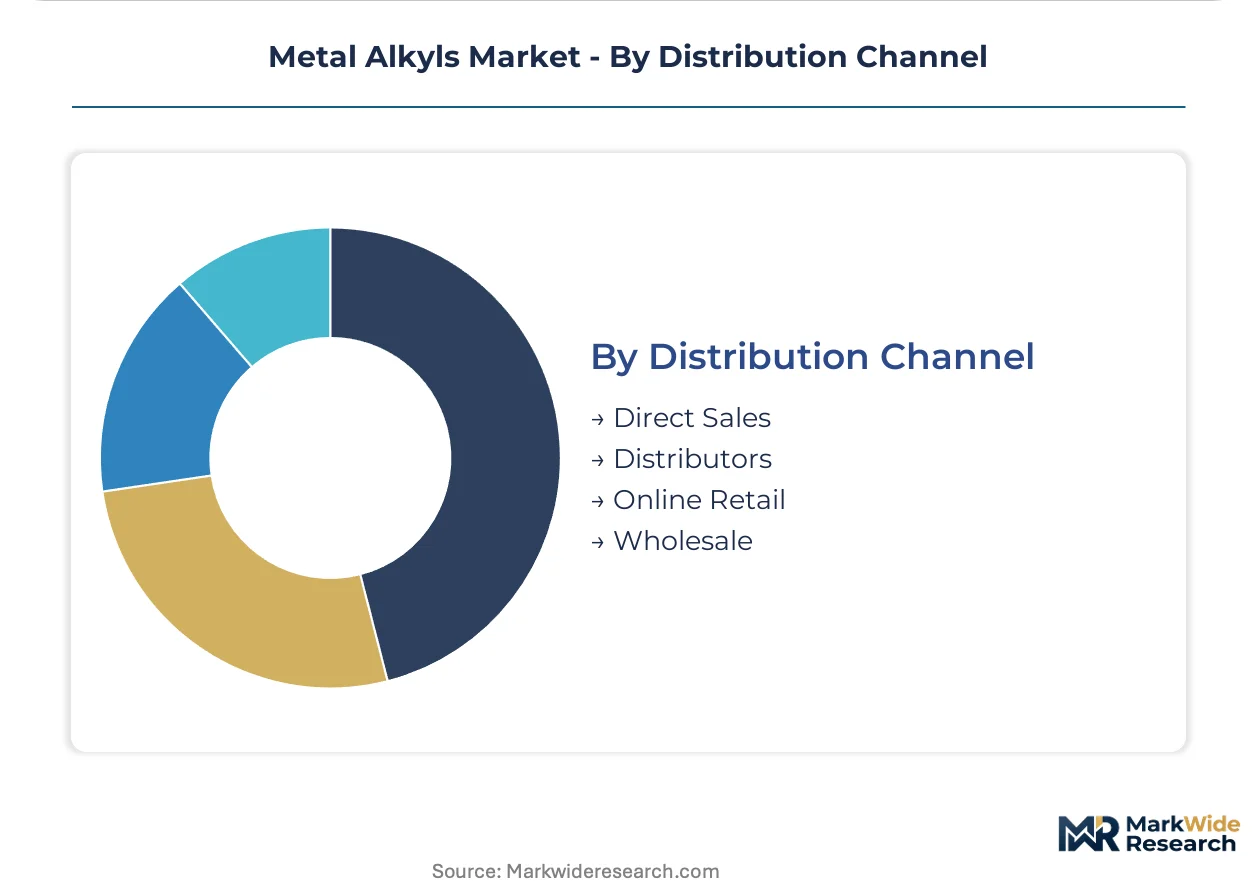
Supply concentration favors direct relationships with integrated producers, while distributor networks struggle to justify pyrophoric handling infrastructure capital.
- Direct Sales:Albemarle, BASF SE, and Nouryon maintain dedicated logistics for tanker delivery to polyolefin plants. Inert atmosphere warehousing and specialized fire suppression systems exclude regional distributors from direct alkyl handling.
- Distributors:Chemical distribution networks concentrate on formulated catalyst packages rather than neat alkyls due to capital barriers.
- Wholesale:Bulk material aggregation serves smaller polymerization operations with standardized specifications.
- Online Retail:Limited to analytical-grade quantities and research-scale packaging for academic and pilot-scale customers.
Direct sales channels dominate tonnage movement while distributor participation is compressing to formulated products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese metal alkyl production flows predominantly into domestic olefin polymerization plants, with residual volumes reaching Indian pharmaceutical manufacturers and European catalyst formulators through Rotterdam and Antwerp port zones.
China
Domestic polypropylene and polyethylene capacity expansion in Ningbo and Shanghai chemical clusters concentrates aluminum alkyl demand along the East China coast. MEE emissions controls on solvent-intensive production favor suppliers with carbon capture integration or bio-based feedstock pathways. Shaanxi province magnesium supply volatility creates input cost instability for Grignard reagent manufacturers serving pharmaceutical customers.
United States
Integrated petrochemical complexes in Texas and Louisiana compress catalyst qualification cycles to twelve-to-eighteen-month windows, demanding real-time batch analytics before contract award. EPA toxic release inventory reporting governs pyrophoric metal alkyl handling requirements. Gulf Coast polymerization hubs anchor direct-to-plant delivery models that bypass regional warehouse networks and reduce contamination risk.
Germany
REACH substance dossier mandates for aluminum and zinc alkyls elevate compliance costs for non-integrated suppliers, advantaging established players with regulatory infrastructure already deployed. ECHA substance evaluation protocols demand extended thermal stability data for transport classification. Ludwigshafen and Leverkusen chemical clusters host formulation activities at integrated sites with on-site hazard testing capabilities.
India
Contract manufacturing expansion under the PLI scheme incentives creates incremental demand for organolithium reagents in asymmetric synthesis steps. CDSCO and FDA contamination control standards govern API synthesis procurement. Hyderabad and Ahmedabad manufacturers adopt continuous-flow reactor technologies to displace traditional batch quench-and-filter workflows.
Japan
Stereoselective polymerization system adoption concentrates titanium alkyl demand where catalyst efficiency directly translates to plant throughput economics. METI industrial standards govern organometallic compound handling protocols. Chubu and Kansai chemical corridors maintain specialized synthesis expertise for air-sensitive compounds at legacy chemical engineering programs.
Metal Alkyls Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated chemical conglomerates with captive precursor supply dominate bulk aluminum alkyl volumes through direct tanker relationships with polyolefin plants. Mid-scale formulators concentrate on specialized lithium alkyl grades for pharmaceutical synthesis where regioselectivity determines yield. Competitive moves center on backward integration into magnesium and bromine feedstocks, plus capacity co-location with expanding Chinese olefin complexes.
Among diversified chemical conglomerates, Albemarle Corporation and BASF SE exemplify integrated archetypes with regulatory infrastructure spanning REACH dossier compilation and EPA reporting protocols. Nouryon occupies a position within the specialized formulation tier, competing on aluminum alkyl packages for high-melt-strength polypropylene applications. These three anchors represent distinct strategic postures: feedstock-integrated volume leadership, regulatory-scale compliance systems, and application-specific technical service.
| Leading Market Players |
|---|
| Strem Chemicals |
| BASF SE |
| Albemarle Corporation |
| TCI Chemicals |
| Akzo Nobel N.V. |
| Nouryon |
| Gulbrandsen |
| FM Plastics |
| LANXESS |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European aluminum alkyl production following REACH compliance exits tightens supplier pricing power while East China olefin expansion pulls volume toward Ningbo-Shanghai port zones. This utilization asymmetry rewards integrated producers with captive bromine-magnesium feedstock and compresses margins for non-specialized distributors.
Pricing Analysis
Metallocene-generation alkyl activators command substantial premiums over legacy Ziegler-Natta grades, while next-generation continuous-flow lithium alkyls price at pharmaceutical-tier levels. Three-tier pricing structure across pharmaceutical-grade, polymerization-grade, and technical-grade specifications separates procurement tiers. Cost compression in standard aluminum alkyls intensifies because Chinese domestic capacity expansion outpaces regional demand growth. Polyolefin producers exhibit highest price sensitivity due to compressed catalyst qualification cycles, while API manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms from integrated petrochemical buyers now stretch sixty-to-ninety days, forcing working capital intensity onto non-integrated suppliers. Supply concentrates in China, Germany, and the United States, with magnesium feedstock dependency anchoring production in Shaanxi province and bromine supply tethered to Albemarle's Arkansas operations. Single-source vulnerability around pharmaceutical-grade organolithium production in Hyderabad-Ahmedabad clusters threatens API supply continuity. Distribution runs through direct tanker relationships with polyolefin plants, bypassing regional warehouse networks due to pyrophoric handling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as polyolefin capacity expansion in China and India restarts catalyst procurement cycles. Olefin plant construction timelines provide the cyclical driver justifying inventory positioning ahead of demand inflection.
For Market Incumbents: Harden regulatory infrastructure around REACH dossier compilation and EPA toxic release reporting to exclude non-compliant challengers. Deepen backward integration into magnesium and bromine precursors to insulate margin structure from Shaanxi supply volatility. Prioritize capacity co-location with expanding Ningbo-Shanghai chemical clusters to capture logistics efficiency. For New Entrants and Emerging Players: India's PLI-scheme pharmaceutical contract manufacturing represents the most penetrable entry point for organolithium specialization. High-melt-strength polypropylene catalyst formulation for European automotive tiers offers secondary white-space opportunity. Lead with continuous-flow reactor technology as technical differentiation against legacy batch producers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-plant catalyst delivery operators with integrated logistics infrastructure. Five-to-ten year viability favors formulators with REACH registration assets and Chinese joint venture access. Monitor ECHA substance evaluation protocol delays as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine and Magnesium Feedstocks | Captive precursor supply insulates Albemarle from Shaanxi price volatility. |
| Continuous-Flow Reactor Technology Deployment | Indian API manufacturers adopt Grignard-type systems to meet FDA contamination standards. |
| REACH Substance Dossier Registration | Full aluminum and zinc alkyl registration advantages established European producers. |
| Direct-to-Plant Catalyst Delivery Model | Tanker relationships with Texas-Louisiana polyolefin hubs bypass contamination-risk warehouse networks. |
| Carbon Capture Integration at Production Facilities | China MEE emissions controls favor suppliers with dual carbon policy alignment. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings, and ECHA substance registration records preceded structured interviews with polymerization plant managers, pharmaceutical procurement leads, and organometallic R&D directors. Primary fieldwork with catalyst formulators and Grignard reagent manufacturers combined with secondary validation against ACC and Cefic industry reports. Bottom-up segment sizing triangulated against top-down capacity assessments across the analysis window.
Assumptions held fixed include REACH regulatory trajectory and Chinese dual carbon policy enforcement intensity, while olefin capacity expansion timing and magnesium price volatility were modeled as scenario variables. Segmentation dimensions spanned product chemistry tier, end-use industry, and regional production hub cluster. CAGRs derived from production capacity buildout schedules and catalyst consumption intensity ratios per ton of polyethylene and polypropylene output.
Practitioners should monitor ECHA evaluation protocol delays and Shaanxi magnesium supply disruptions for early signals of forecast revision. Macroeconomic deviation in polyolefin demand, regulatory reclassification of pyrophoric substances, or breakthrough aqueous quench technologies would prompt forecast adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Sequencing Reagents Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Ph Controlling Agents Market